
 Aeration System Market | 2026-2036
Aeration System Market Size, Share, and Industry Trends Forecast 2026-2036
Aeration System Market Outlook
Modular skid-mounted aeration packages are repositioning buyer choice away from site-built installations toward pre-engineered configurations. Xylem Inc. leverages its integrated digital platform to bundle blowers, diffusers, and control systems into single-source contracts. Aqua-Aerobic Systems, Inc. sustains differentiation through membrane aerated biofilm reactor specialization. Sulzer Ltd. anchors European demand with high-efficiency turbo compressor technology.
An aeration system introduces air or oxygen into water or wastewater to support aerobic biological degradation of organic pollutants, typically operating at dissolved oxygen setpoints between 1.5 and 2.5 mg per liter in activated sludge basins. Diffused aeration dominates municipal expenditure due to superior oxygen transfer efficiency at depth, while mechanical aeration retains share in lagoon applications where capital constraints limit infrastructure investment. Surface aeration occupies a narrowing niche in aquaculture and industrial equalization ponds where mixing intensity outweighs oxygen precision. Static mixers represent the smallest technology segment but attract interest in chemical process industries for combined aeration and blending.
EPA effluent limitation guidelines under the Clean Water Act mandate biological nutrient removal upgrades that expand fine-bubble diffuser replacement cycles. EU Urban Waste Water Treatment Directive revisions tighten total nitrogen discharge thresholds, redirecting capital toward energy-optimized aeration controls. ISO 15489 and ASME pressure vessel codes govern blower and diffuser manufacturing standards that shape supplier certification requirements. Stakeholders must monitor how electricity pricing volatility and carbon accounting frameworks alter the total-cost-of-ownership calculus between high-efficiency diffusers and legacy mechanical alternatives.
Market Dynamics
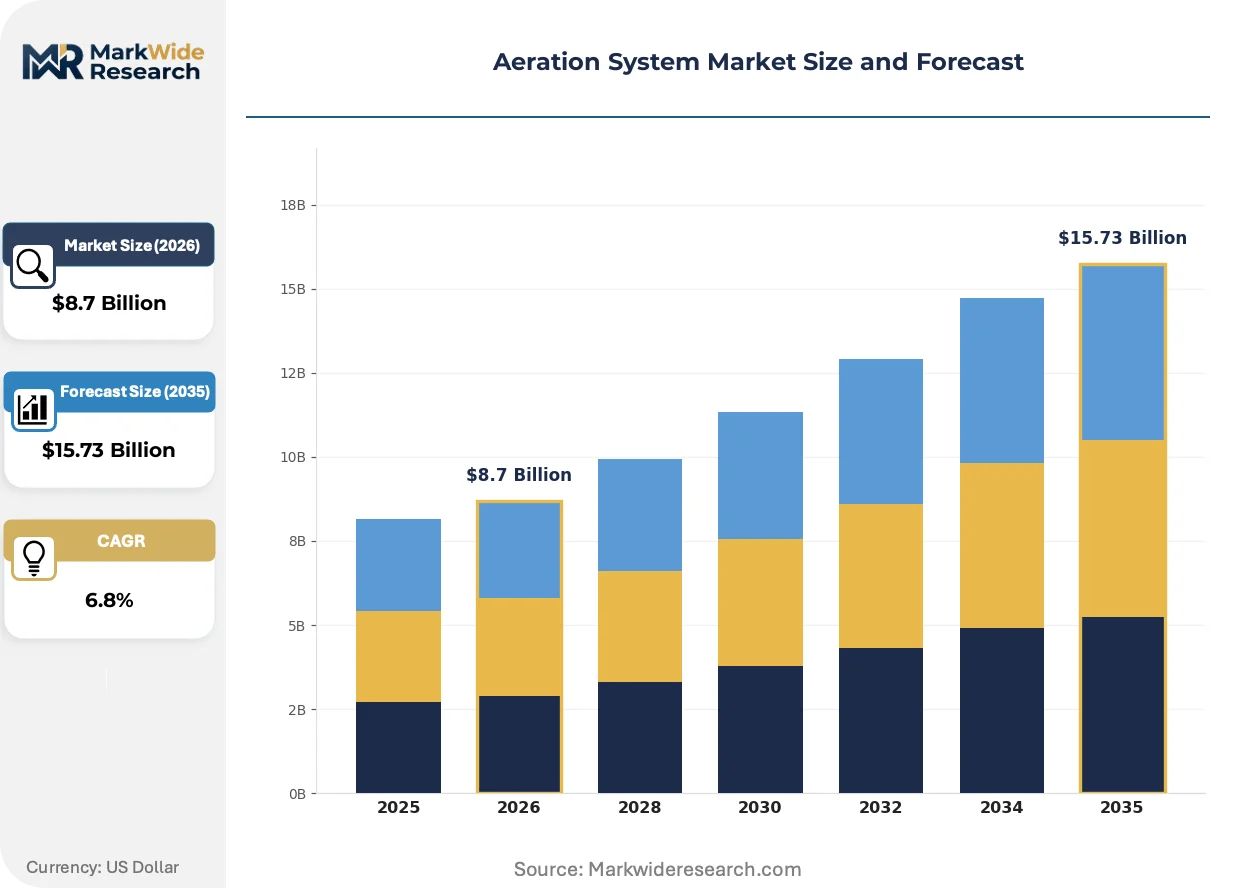
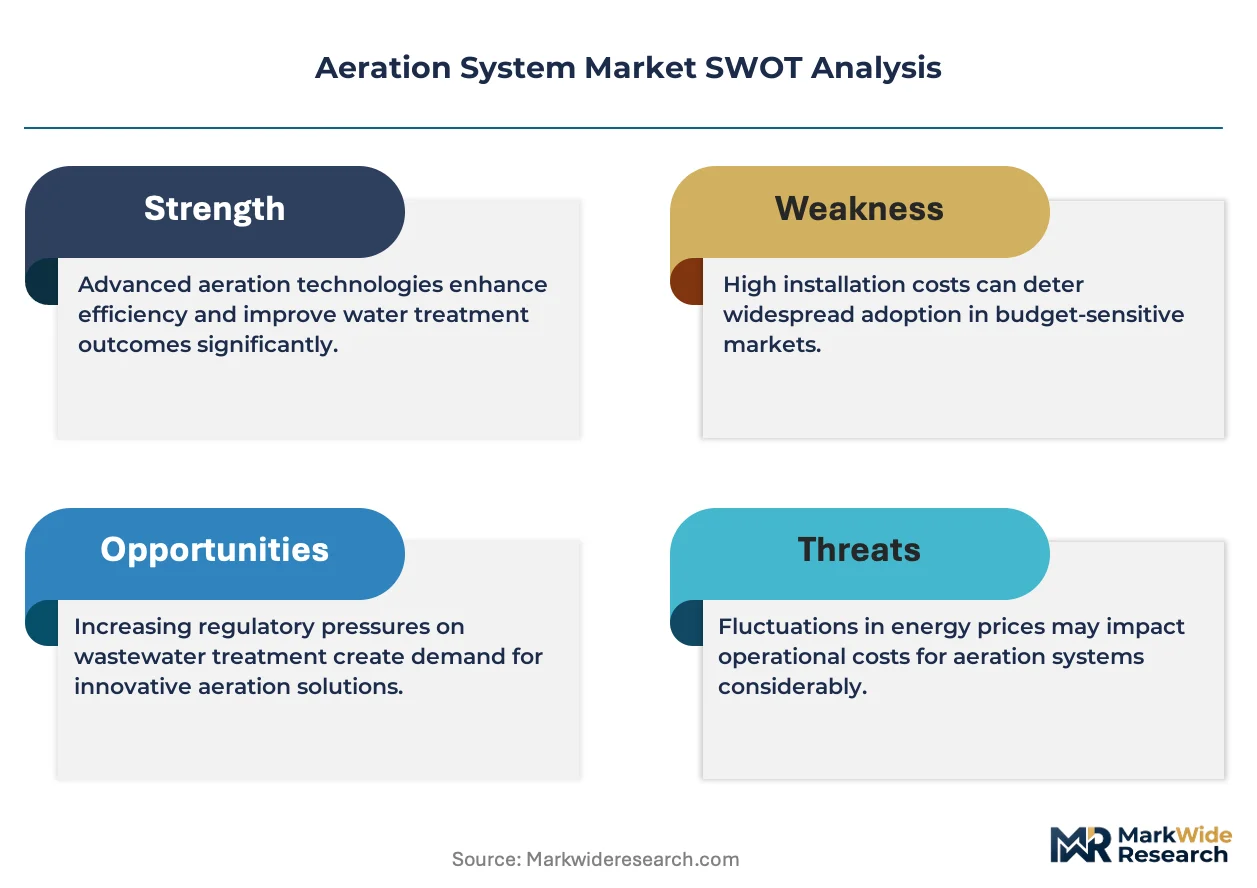
Energy cost volatility and carbon accounting frameworks are compressing the payback period for high-efficiency diffuser upgrades, redirecting capital from mechanical aeration toward fine-bubble systems in municipal wastewater plants.
Growth Catalysts
- EPA Clean Water Act discharge permits:Municipal utilities across the United States are expanding biological treatment capacity to comply with nutrient removal mandates, accelerating fine-bubble diffuser procurement cycles.
- EU Urban Waste Water Treatment Directive revisions:Tightened total nitrogen discharge thresholds in Germany and neighboring states are redirecting capital toward energy-optimized aeration controls and automated dissolved oxygen management.
- Modular skid-mounted configurations:Pre-engineered aeration packages are displacing site-built installations, reducing commissioning timelines and enabling faster biological capacity expansion in constrained urban footprints.
Market Restraints
- Electricity price volatility:Aeration systems consume 50-60% of total energy in activated sludge plants, making operating cost projections unreliable for municipal budget cycles and delaying replacement decisions.
- Specialized diffuser membrane supply:EPDM and silicone membrane production concentrates among a limited supplier base, creating vulnerability to raw material price swings and extended lead times.
- Lagoon capital constraints:Mechanical surface aeration retains share in rural and small-community applications where infrastructure investment limits preclude diffused system installation despite inferior oxygen transfer efficiency.
Strategic Opportunities
- India municipal wastewater infrastructure:Central government Swachh Bharat Mission allocations and AMRUT 2.0 funding are unlocking biological treatment plant construction in tier-2 and tier-3 cities lacking aeration infrastructure.
- Membrane aerated biofilm reactor convergence:Integration of gas-permeable membranes with biofilm processes enables higher biomass concentrations and reduced energy intensity for nutrient removal applications.
- Digital twin and predictive control platforms:Real-time dissolved oxygen optimization using machine learning algorithms is creating new service revenue streams and locking in long-term aftermarket relationships.
Industry Challenges
- Process control engineering talent scarcity:Municipal utilities struggle to recruit and retain instrumentation specialists capable of maintaining automated aeration control systems, limiting technology adoption.
- Legacy mechanical aeration retrofit complexity:Converting existing oxidation ditches and lagoons to diffused aeration requires basin draining, structural modification, and extended service interruptions that risk permit compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeration System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Diffused Aeration, Mechanical Aeration, Surface Aeration, Static Mixers Application: Aquaculture, Wastewater Treatment, Industrial Processes, Water Treatment End User: Agriculture, Municipalities, Manufacturing, Fisheries Capacity: Small Scale, Medium Scale, Large Scale, Others |
| Companies Covered | Aqua-Aerobic Systems, Inc., Aeration Industries International, LLC, Xylem Inc., Veolia Water Technologies & Solutions, SSI Aeration, Inc., Pentair plc, Fluence Corporation, SUEZ Water Technologies & Solutions, Sulzer Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeration System Market Strategic Shifts
Digital integration and materials science advances are compressing the traditional separation between blower hardware, diffuser media, and control software, creating unified system architectures that redefine supplier value capture.
Advanced polyurethane and modified silicone diffuser membranes are unifying mechanical durability with micro-bubble generation efficiency. German and Chinese municipal utilities are deploying these materials in high-solids industrial pretreatment applications where fouling resistance determines replacement cycles. This unification is collapsing the historical trade-off between capital cost and oxygen transfer rate, enabling single-source suppliers to capture margins previously fragmented across component vendors.
The EU F-Gas Regulation is accelerating the transition from oil-injected to oil-free turbo compressor technology in aeration blower applications. Equipment suppliers must now certify refrigerant containment and energy performance under standardized test protocols. European municipal procurement frameworks are responding by embedding F-Gas compliance into tender specifications, disadvantaging legacy blower architectures regardless of upfront capital cost.
Performance-based service contracts are displacing equipment-only sales in large municipal accounts. French and Dutch water utilities now contract for guaranteed dissolved oxygen delivery per kilowatt-hour consumed, transferring operational risk to equipment suppliers. This shift is most visible in Germany's Ruhr region, where multi-utility operators bundle aeration system availability into comprehensive wastewater treatment service agreements spanning 10-15 year horizons.
Aeration System Market Segmentation
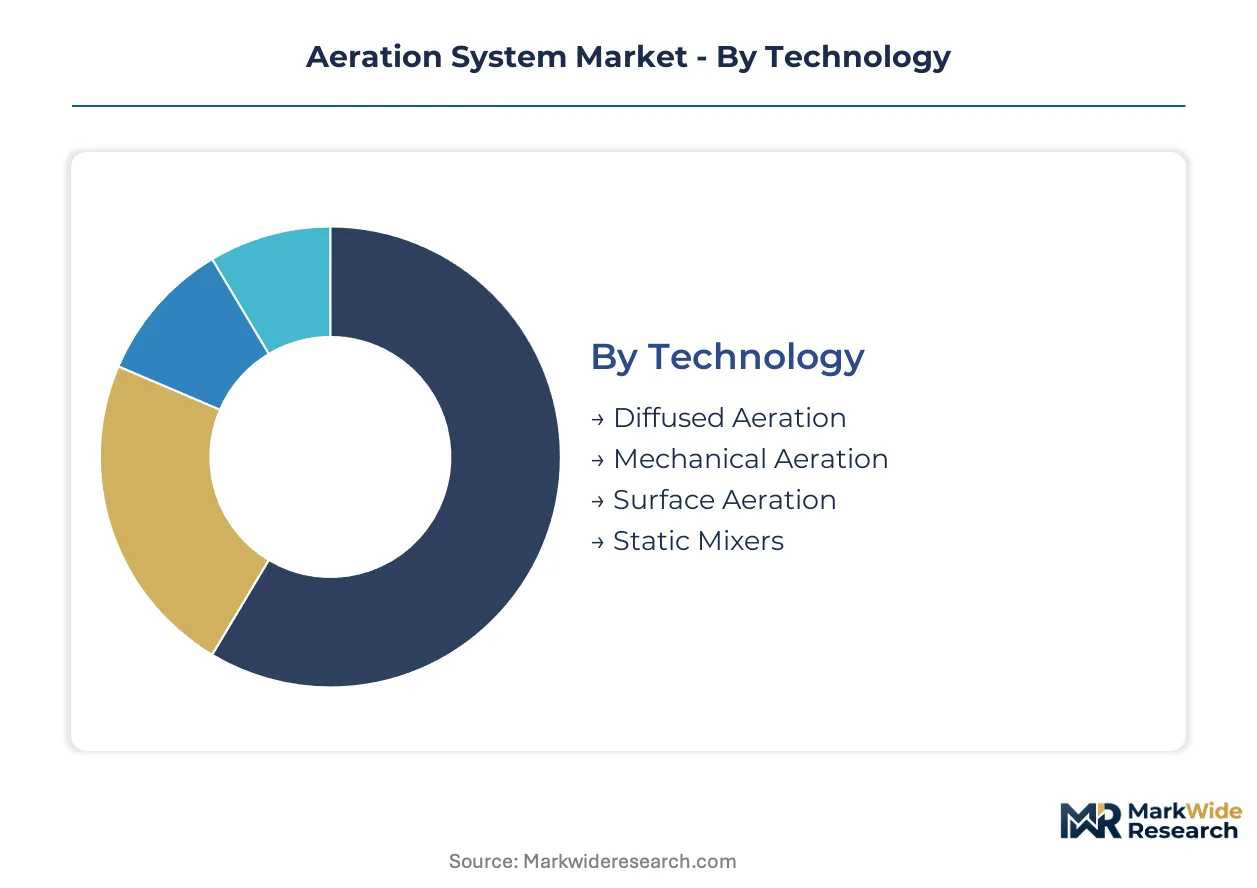
Segmentation in the aeration system market reveals how capital deployment priorities diverge across technology generations and facility scales. Upgrade cycles and replacement timelines vary dramatically by segment, shaping supplier contract structures and aftermarket revenue potential.
Technology:
Fine-bubble diffuser replacement cycles and mechanical aeration retrofit economics are compressing payback thresholds for municipal procurement teams.
- Diffused Aeration:Ceramic or membrane diffusers generate micro-bubbles at depths exceeding 4 meters, achieving standard oxygen transfer efficiencies above 2.0 kg O2 per kWh. Municipal wastewater plants in Germany and the United States are prioritizing these systems for activated sludge basin upgrades driven by EPA and EU Urban Waste Water Treatment Directive compliance deadlines.
- Mechanical Aeration:Surface-mounted impellers or brush rotors aerate through atmospheric oxygen entrainment, operating without submerged distribution networks. Rural municipalities in India and small-community lagoons across the United States retain this technology where capital constraints preclude basin reconstruction for diffused system installation.
- Surface Aeration:Floating aerators deliver high mixing intensity with lower oxygen precision, dominating aquaculture ponds and industrial equalization basins where uniform circulation outweighs dissolved oxygen setpoint control.
- Static Mixers:Fixed-blade elements combine aeration with inline blending for chemical process industries, occupying the smallest technology segment but attracting interest in petrochemical and pharmaceutical wastewater pretreatment.
Diffused aeration sits at the top of the volume ranking, with static mixers climbing the fastest in specialized industrial applications.
Application:
Regulatory discharge thresholds and production intensity determine oxygen demand specifications across end-use environments.
- Wastewater Treatment:Biological nutrient removal mandates in the United States, Germany, and China are accelerating fine-bubble diffuser procurement for nitrogen and phosphorus reduction. Activated sludge plants consume 50-60% of facility energy through aeration, making efficiency upgrades the primary lever for operating cost reduction.
- Industrial Processes:Chemical, food and beverage, and pulp and paper facilities require aeration for high-strength organic loading and pretreatment compliance. Membrane aerated biofilm reactor technology is gaining traction in these applications for reduced energy intensity.
- Water Treatment:Pre-ozonation and taste-and-odor control applications utilize diffused aeration for iron and manganese oxidation in potable water facilities.
- Aquaculture:Intensive fish farming operations in Norway and Vietnam deploy surface aerators and pure oxygen injection systems to maintain stocking densities that exceed natural dissolved oxygen replenishment rates.
Wastewater treatment commands the largest installed base, with industrial processes expanding most quickly as manufacturing effluent standards tighten.
End User:
Budget cycles and technical staffing depth create distinct purchasing patterns across buyer categories.
- Municipalities:City and regional wastewater utilities operate under political budget constraints and EPA discharge permit enforcement, favoring performance-based service contracts and energy-guaranteed procurement structures.
- Manufacturing:Industrial facilities prioritize uptime reliability and rapid biological response to production variability, accepting higher capital costs for automated dissolved oxygen control and redundant blower configurations.
- Agriculture:Livestock operations and dairy processing plants utilize lagoon-based aeration for manure management, constrained by seasonal cash flows and limited technical maintenance capacity.
- Fisheries:Commercial aquaculture enterprises in coastal China and Southeast Asia invest in aeration as production-limiting infrastructure, with equipment selection directly tied to harvest volume targets.
Municipalities represent the dominant revenue concentration, with manufacturing gaining share fastest through corporate sustainability commitments.
Capacity:
Scale determines equipment configuration complexity and supplier engagement model.
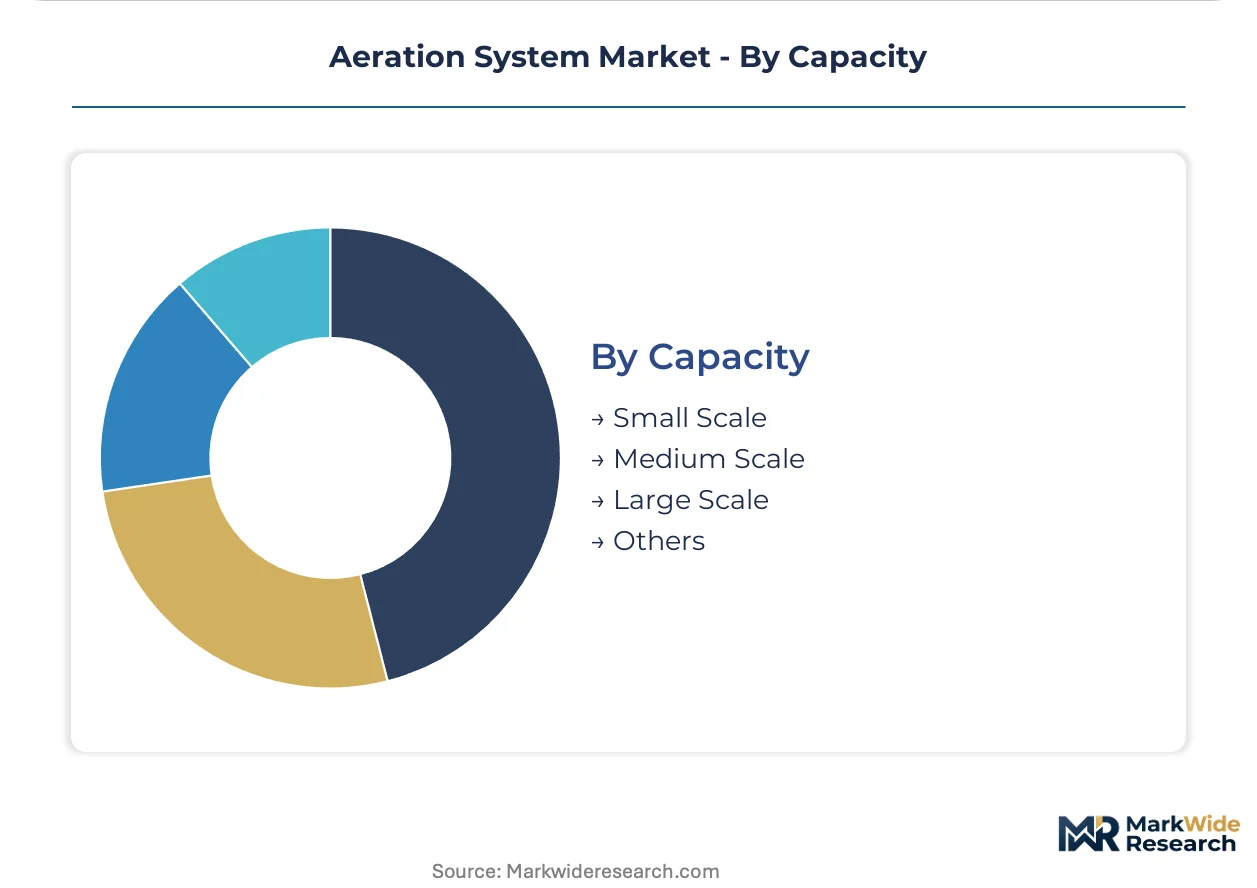
- Large Scale:Facilities exceeding 100,000 population equivalent demand multi-blower arrays, automated dissolved oxygen control loops, and predictive maintenance platforms. German Ruhr region utilities and metropolitan US plants exemplify this segment.
- Medium Scale:Tier-2 cities in India and regional treatment plants in France balance capital efficiency with biological capacity expansion, favoring modular skid-mounted packages over site-built installations.
- Small Scale:Package plants and decentralized systems serve rural communities and industrial satellite facilities, where simplified mechanical aeration dominates due to operator skill limitations.
- Others:Mobile and temporary aeration solutions support construction dewatering, emergency response, and pilot-scale testing applications with rental-based commercial models.
Large scale facilities anchor supplier profitability, with medium scale installations showing the steepest expansion trajectory in emerging municipal infrastructure markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diffused aeration technology originated in German municipal engineering during the 1970s energy crisis, establishing design standards that still govern oxygen transfer efficiency benchmarks. The industry's geographic footprint now spans three continents where wastewater infrastructure investment cycles diverge sharply.
United States
EPA Clean Water Act enforcement drives municipal utility capital planning across the Great Lakes and Chesapeake Bay watersheds. Nutrient removal mandates in Maryland and Virginia accelerate fine-bubble diffuser procurement for phosphorus compliance. Metropolitan Chicago and Atlanta anchor the largest activated sludge retrofit programs, with Cook County facilities replacing mechanical aeration ahead of 2027 permit deadlines.
Germany
The Ruhr region's multi-utility operators bundle aeration performance into 15-year service agreements spanning wastewater and energy distribution. EU F-Gas Regulation compliance redirects blower procurement toward oil-free turbo compressors certified under standardized test protocols. Bavarian industrial clusters around Munich and Nuremberg deploy membrane aerated biofilm reactors for high-strength pharmaceutical effluent pretreatment.
China
MEE discharge standard tightening in the Yangtze River Delta triggers biological treatment capacity expansion in tier-2 cities lacking aeration infrastructure. Central government dual carbon goals compress payback thresholds for energy-efficient diffuser upgrades in Jiangsu and Zhejiang provinces. Shanghai's municipal engineering institutes partner with European suppliers on smart aeration control system localization.
India
Swachh Bharat Mission allocations unlock biological treatment construction in Maharashtra and Gujarat municipalities previously served by oxidation ponds. AMRUT 2.0 funding channels toward tier-3 cities in Karnataka and Tamil Nadu where aeration infrastructure remains underdeveloped. Hyderabad and Pune treatment plants pilot modular skid-mounted configurations to accelerate commissioning in constrained urban footprints.
Japan
METI energy efficiency standards for municipal utilities drive dissolved oxygen automation adoption in Kansai region treatment facilities. Aging infrastructure in Osaka Prefecture requires simultaneous aeration and secondary clarifier upgrades to maintain NPDES-equivalent discharge permits. Tokyo's Bureau of Sewerage tests machine learning-based aeration optimization as part of its 2050 carbon neutral roadmap.
Aeration System Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth, with single-source system suppliers commanding pricing power over component vendors. The vendor base clusters around three strategic archetypes: integrated platform providers bundling blowers, diffusers, and controls; membrane technology specialists extracting value from materials science differentiation; and regional fabrication houses competing on delivery speed and customization flexibility. Competitive moves concentrate on digital twin service contracts and predictive maintenance platform deployment.
Within the integrated platform tier, Xylem Inc. and Sulzer Ltd. exemplify the convergence of blower hardware with automated control software. Aqua-Aerobic Systems, Inc. occupies a specialization position anchored in membrane aerated biofilm reactor technology. These three companies represent distinct competitive vectors—scale-driven system integration, European turbo compressor engineering heritage, and advanced biological process specialization—without implying specific market share positions or strategic priorities.
| Leading Market Players |
|---|
| Aqua-Aerobic Systems, Inc. |
| Aeration Industries International, LLC |
| Xylem Inc. |
| Veolia Water Technologies & Solutions |
| SSI Aeration, Inc. |
| Pentair plc |
| Fluence Corporation |
| SUEZ Water Technologies & Solutions |
| Sulzer Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates qualified supply for oil-free turbo compressors and anchors premium-tier pricing access for certified European suppliers, while municipal procurement teams in India and China face cost compression from electricity pricing volatility and carbon accounting frameworks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated digital platform providers from membrane specialists and regional fabrication houses. Price differentiation rests on ISO 15489 certification status and after-sales service bundling. Cost compression in the economy tier is intensifying because municipal utilities in India prioritize capital efficiency over energy performance. Small-community lagoon operators exhibit highest price sensitivity; German Ruhr region multi-utility operators show least.
Supply Chain Analysis
Single-source vulnerability sits with EPDM and silicone membrane production concentrated in Germany, China, and the United States. Raw material dependencies draw from specialized polymer feedstocks, high-grade ceramics for diffusers, and precision-machined compressor components. Tariff exposure on European blower exports to Asian markets creates procurement uncertainty for tier-2 city utilities. Distribution runs through direct municipal contracting in developed markets and EPC-led project bundling in emerging infrastructure markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where energy cost differentials between European carbon-priced electricity markets and subsidized industrial power in India compress payback periods for high-efficiency upgrades in the former while delaying them in the latter.
For Market Incumbents: Extend digital twin service contracts into 10-15 year performance-based agreements to lock out emerging platform competitors. Backward integration into membrane manufacturing reduces exposure to EPDM supply concentration. Invest in AMRUT 2.0 and Swachh Bharat Mission tender participation to anchor early-mover position in Indian tier-3 city expansion.
For New Entrants and Emerging Players: Enter via membrane aerated biofilm reactor specialization for pharmaceutical and food-and-beverage industrial pretreatment, where biomass concentration advantages command premium pricing. Target Maharashtra and Gujarat municipalities transitioning from oxidation ponds to biological treatment. Lead with modular skid-mounted configurations to accelerate commissioning timelines against site-built incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication houses with customization flexibility because municipal procurement fragmentation across 4,000+ US wastewater utilities prevents national-scale concentration. Monitor EPA effluent limitation guideline revision timing as inflection indicator for replacement cycle acceleration. Favor targets with certified oil-free turbo compressor portfolios over legacy oil-injected architectures facing F-Gas obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Machine learning-based dissolved oxygen optimization creates recurring service revenue at German Ruhr utilities. |
| Backward Integration into Membrane Manufacturing | In-house EPDM production reduces lead time vulnerability and captures margins from specialized suppliers. |
| Modular Skid-Mounted Configuration Expansion | Pre-engineered packages accelerate commissioning in constrained urban footprints across Indian tier-2 cities. |
| Oil-Free Turbo Compressor Certification | F-Gas compliance enables tender participation in EU municipal procurement frameworks. |
| Performance-Based Service Contract Conversion | Guaranteed dissolved oxygen delivery per kilowatt-hour transfers operational risk from municipalities to suppliers. |
Study Parameters
Bottom-up municipal utility modeling reconciled against top-down blower and diffuser manufacturer tracking forms the analytical core. Primary interviews with wastewater treatment plant engineers, municipal procurement officers, EPC contractors, and aftermarket service heads combined with secondary validation from EPA discharge permit databases, EU Urban Waste Water Treatment Directive compliance filings, SEC 10-K equipment supplier disclosures, and Indian AMRUT 2.0 project registries.
Input-output matrices map oxygen demand specifications across technology generations, facility capacity tiers, and geographic regulatory clusters. Segmentation dimensions include aeration technology type, application environment, end-user budget cycle archetype, and plant scale category. CAGRs derive from replacement timeline compression analysis and infrastructure investment pipeline tracking. Forecast inputs incorporate electricity pricing volatility scenarios and carbon accounting framework adoption curves.
Inputs from municipal procurement databases and equipment supplier order backlogs were available through the study window; gaps in real-time dissolved oxygen automation adoption rates introduce uncertainty bands around digital service revenue projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
HVAC Insulation Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Corrugated Air Duct Market