
 ASEAN Heat Exchanger Market | 2026-2036
ASEAN Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Heat Exchanger Market Outlook
ASME Section VIII certification is rotating as the primary gate for suppliers bidding on ASEAN power and petrochemical projects. Alfa Laval AB leverages its brazed plate expertise to anchor premium positions in food and beverage applications across Thailand and Malaysia. Kelvion Holding GmbH sustains manufacturing scale through its regional assembly footprint, while Hisaka Works Ltd specializes in corrosion-resistant designs for chemical processing clusters in Indonesia and Vietnam.
A heat exchanger is a thermal transfer device constructed from metallic alloys or composite materials, engineered to move thermal energy between two or more process fluids without mixing, with design pressures and temperatures specified per TEMA standards and client process datasheets. Plate configurations capture margin pools in HVAC and food processing installations where compact footprint and cleanability command pricing premiums. Shell and tube architectures dominate oil and gas and chemical processing contracts where high-pressure tolerance and fouling resistance prove decisive. Microchannel technology leads growth in automotive and precision manufacturing cooling loops across ASEAN assembly plants.
Indonesia's Ministry of Industry enforces local content rules that reshape procurement patterns for state-linked energy projects. Thailand's Department of Industrial Works imposes emissions monitoring standards that accelerate replacement of inefficient shell and tube bundles in refinery service. Singapore's Building and Construction Authority mandates energy efficiency benchmarks for commercial HVAC retrofits, expanding specification opportunities for advanced plate heat exchangers. Stakeholders must monitor evolving national content requirements and efficiency codes to align product portfolios with shifting compliance thresholds.
Market Dynamics
ASEAN energy infrastructure procurement is bifurcating between state-mandated local content compliance and the technical requirements of multinational EPC contractors, forcing fabricators to maintain dual certification and sourcing footprints.
Growth Catalysts
- Local Content Mandates:Indonesia's Ministry of Industry enforces domestic procurement thresholds for state-linked LNG-to-power projects, redirecting fabrication contracts toward certified domestic suppliers.
- Refinery Emissions Standards:Thailand's Department of Industrial Works imposes continuous emissions monitoring on petrochemical complexes, accelerating replacement cycles for inefficient shell and tube bundles.
- Microchannel Cooling Adoption:Precision manufacturing clusters in Vietnam's southern industrial provinces are specifying compact microchannel heat exchangers for automotive and electronics assembly lines.
Market Restraints
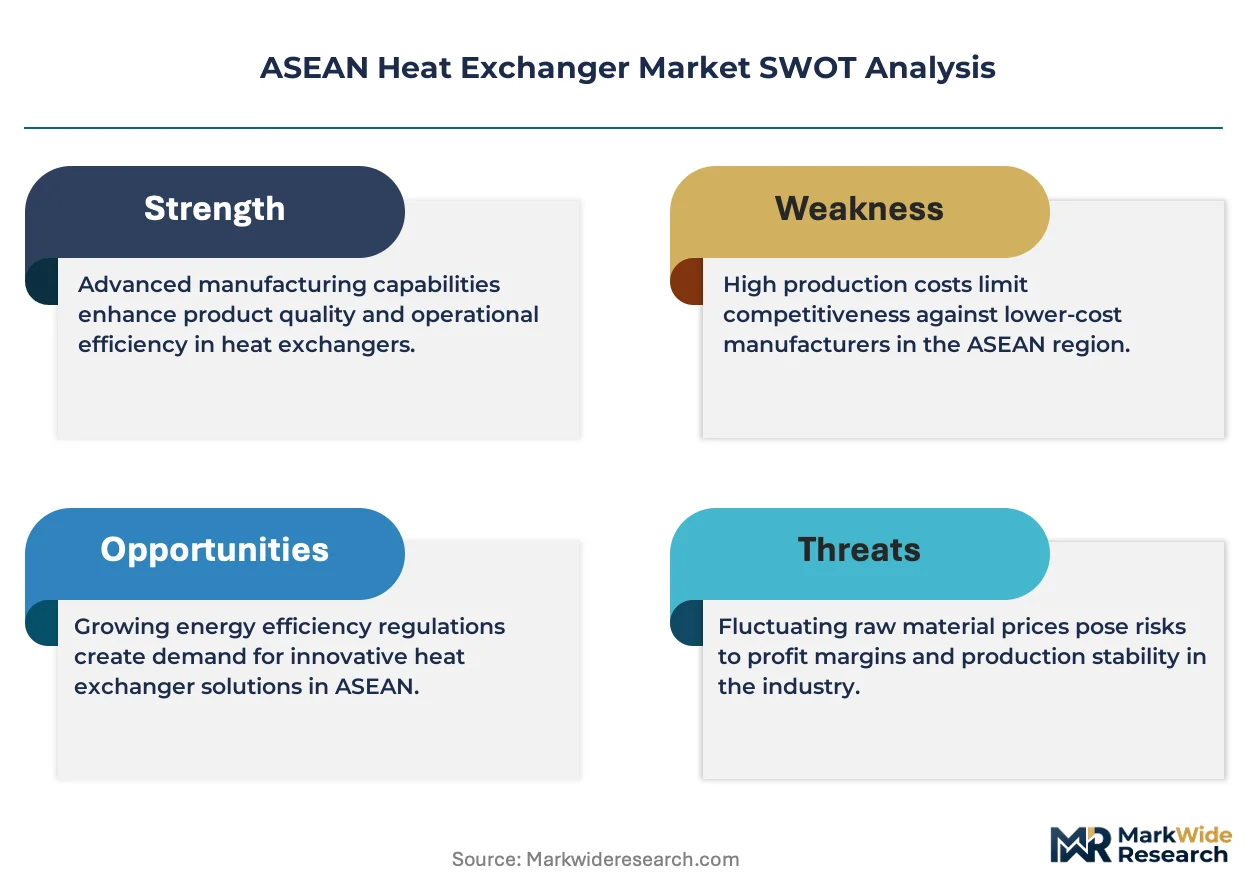
- Specialized Alloy Supply Concentration:High-grade titanium and superalloy plate for corrosion-resistant chemical service concentrates among Japanese and European specialty mills, exposing ASEAN fabricators to input cost volatility and extended lead times.
- ASME Section VIII Certification Bottleneck:The limited pool of third-party inspectors authorized for pressure vessel certification in Southeast Asia extends project qualification timelines for new market entrants.
- Competing Thermal Management Technologies:Direct-contact cooling and phase-change materials are displacing conventional heat exchangers in select semiconductor fabrication processes.
Strategic Opportunities
- LNG Cold Energy Recovery:Vietnam's southern provinces host expanding regasification terminals where cryogenic heat exchangers for cold chain and industrial cooling applications remain undersupplied.
- HVAC Retrofit Mandates:Singapore's Building and Construction Authority energy efficiency benchmarks for commercial buildings create specification pull for advanced plate heat exchangers in chiller replacement cycles.
- Digital Twin Integration:Convergence of IoT sensors and predictive maintenance software enables outcome-based service contracts for heat exchanger fleet management in refinery and chemical processing installations.
Industry Challenges
- Welding Certification Shortage:Qualified ASME Section IX welders for high-pressure alloy construction remain scarce across ASEAN fabricators, constraining capacity expansion.
- Legacy System Integration:Petrochemical operators in Thailand and Indonesia face complex retrofit requirements when installing compact plate designs to replace existing shell and tube footprints without process shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Heat Exchanger Market |
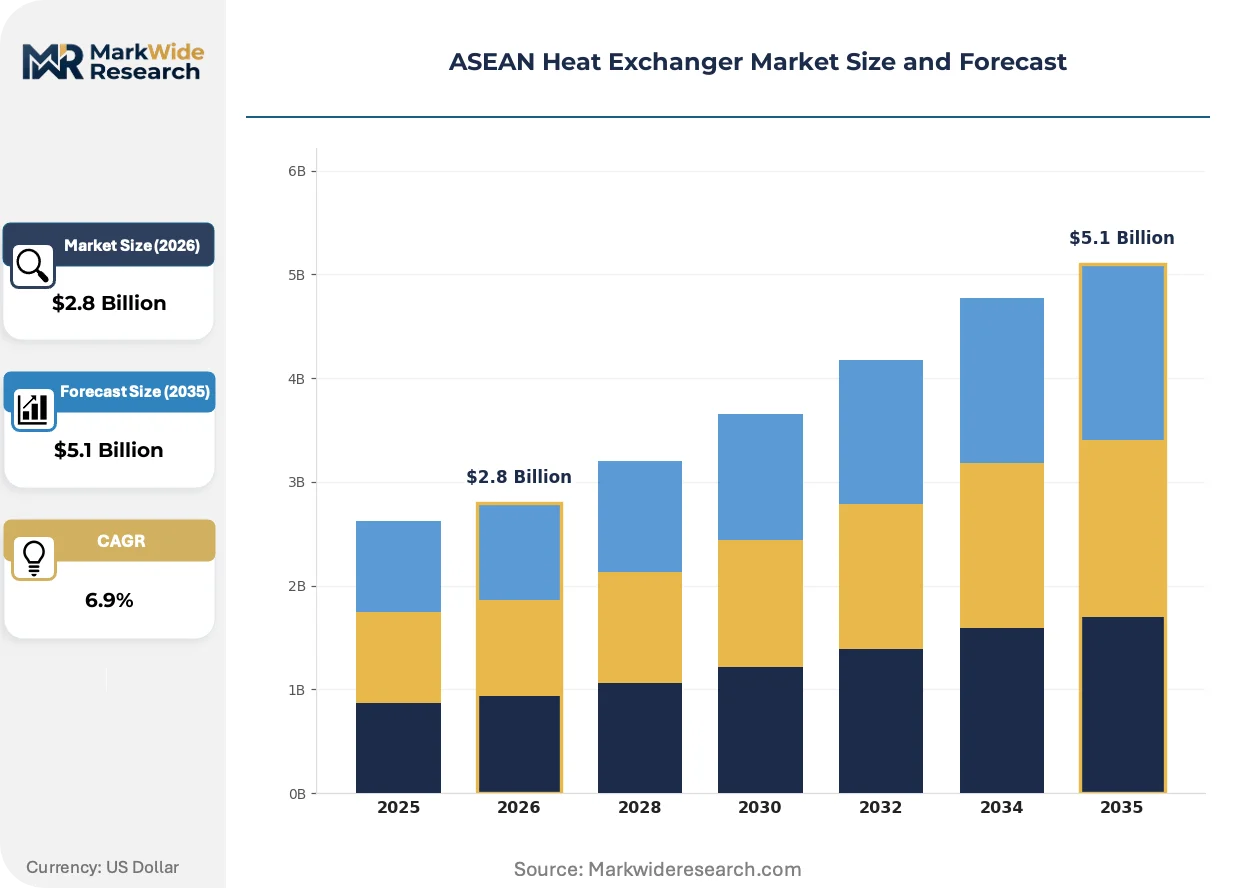
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.1 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubular, Plate, Air-Cooled, Shell and Tube Application: HVAC, Power Generation, Chemical Processing, Oil and Gas End User: Manufacturing, Healthcare, Automotive, Food and Beverage Technology: Double Pipe, Brazed Plate, Spiral, Microchannel |
| Companies Covered | Alfa Laval AB, General Electric Company, Danfoss AB, Xylem Inc., Kelvion Holding GmbH, Hisaka Works Ltd, SPX FLOW Inc, Thermax Limited, Chart Industries Inc, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Heat Exchanger Market Strategic Shifts
Heat exchanger technology trajectories in ASEAN are diverging between premium efficiency specifications for new-build energy infrastructure and cost-optimized designs for replacement cycles in mature industrial assets.
Additive manufacturing of heat transfer surfaces is fragmenting traditional fabrication economics. Selective laser melting enables complex channel geometries that improve thermal performance in compact footprints. Chemical processors in Singapore and Malaysia are piloting additively produced tube inserts for fouling-prone refinery service. This capability is fragmenting procurement patterns between early adopters seeking performance premiums and conventional buyers awaiting qualification data.
Singapore's Building and Construction Authority mandates granular energy efficiency disclosure for commercial building retrofits. This policy compresses payback thresholds for advanced plate heat exchanger upgrades in district cooling networks. Facility managers in Singapore's central business district are accelerating chiller replacement schedules to preempt compliance penalties.
After-sales service unbundling is reshaping buyer-supplier relationships in ASEAN process industries. End-users in Vietnam's petrochemical corridor are separating spare parts procurement from OEM maintenance contracts, favoring third-party service providers with localized inventory. This pattern is most pronounced in refinery and chemical processing clusters where operational cost pressures override brand loyalty in replacement bundle sourcing.
ASEAN Heat Exchanger Market Segmentation
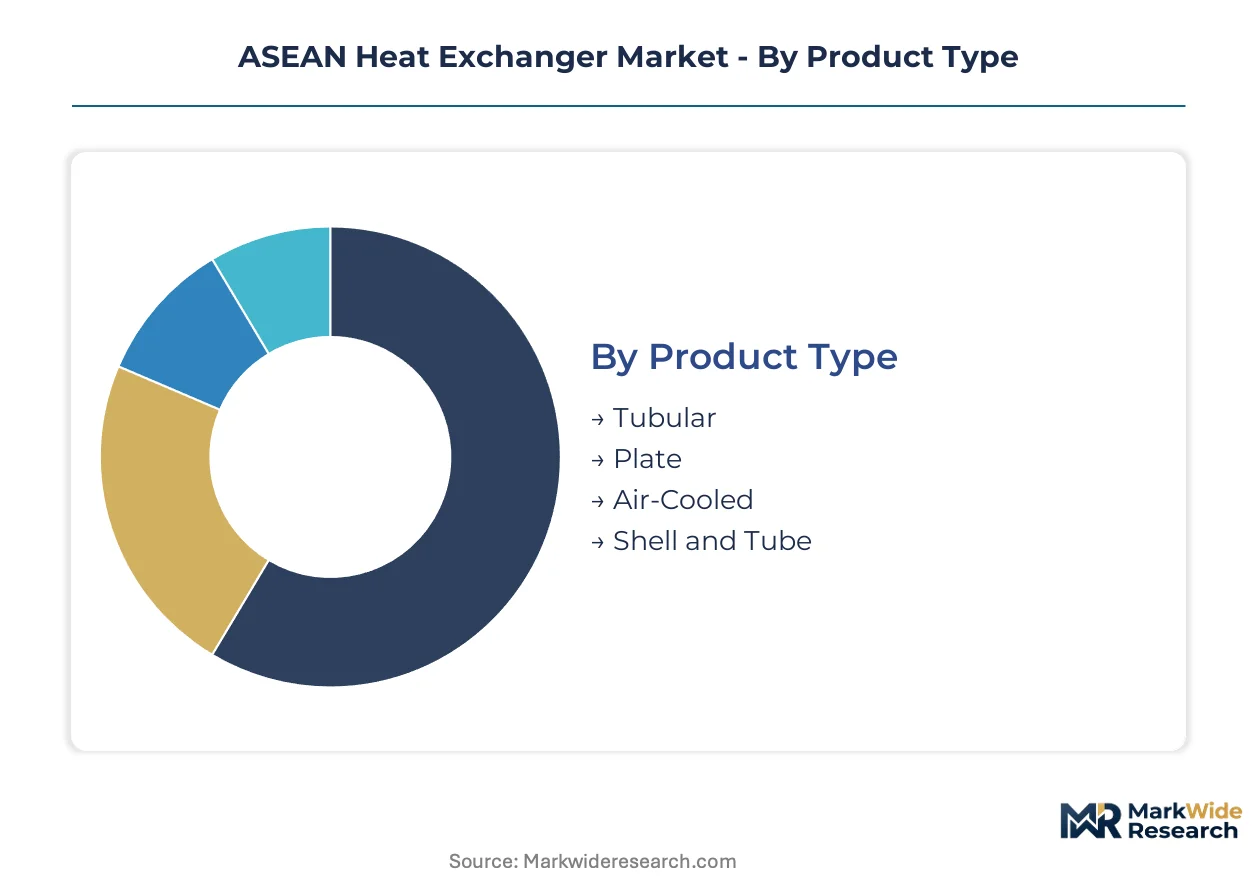
Heat exchanger procurement across ASEAN channels through distinct technical specifications and certification requirements. Each segment carries unique margin profiles and local content compliance obligations that reshape supplier positioning.
Product Type:
Distribution channels favor shell and tube bundles for petrochemical EPC contracts, while plate configurations move through HVAC and food processing distributors with shorter sales cycles.
- Shell and Tube:High-pressure alloy construction withstands refinery service conditions above 150 bar. Thai petrochemical complexes in Map Ta Phut and Vietnam's Dung Quat refinery anchor replacement demand as emissions monitoring tightens replacement cycles.
- Plate:Corrugated stainless steel plates enable compact footprint and thermal efficiency above 85%. Singapore's district cooling networks and Malaysia's food processing clusters specify brazed plate units for cleanability and modularity.
- Tubular:Coiled or straight-tube designs serve moderate-pressure chemical service across Indonesian fertilizer plants. Procurement flows through domestic fabricators meeting Ministry of Industry local content thresholds.
- Air-Cooled:Finned tube bundles address water-scarce locations in Indonesian and Thai industrial zones. Power generation projects in Vietnam's southern provinces specify air-cooled condensers for LNG-to-power installations.
By volume, shell and tube leads. By growth pace, plate configurations are expanding most quickly.
Application:
Cost tier stratification separates premium-specification energy infrastructure from standardized commercial HVAC replacements.
- Oil and Gas:ASME Section VIII certified units handle sour gas service with titanium-clad tube sheets. Indonesia's Pertamina refineries and Vietnam's Nghi Son complex drive procurement through multinational EPC contractors with stringent metallurgical requirements.
- Chemical Processing:Corrosion-resistant alloys address aggressive acid and caustic streams. Singapore's Jurong Island petrochemical hub and Malaysia's Kerteh processing cluster specify specialized materials for continuous operation cycles.
- HVAC:Compact plate and frame units serve commercial building retrofits. Singapore's Building and Construction Authority efficiency mandates accelerate chiller replacement schedules in the central business district.
- Power Generation:Feedwater heaters and condensers integrate into combined-cycle gas turbine plants. Vietnam's LNG-to-power pipeline in Ba Ria-Vung Tau and Binh Thuan provinces concentrates procurement activity.
Power generation commands the highest unit values. HVAC retrofit activity is climbing the fastest.
End User:
Customer type determines specification authority—multinational manufacturers set technical standards while domestic operators prioritize local content compliance.
- Manufacturing:Process cooling for electronics and precision assembly in Vietnam's southern industrial provinces. Microchannel heat exchangers serve automotive and semiconductor fabrication lines with tight temperature control requirements.
- Food and Beverage:Sanitary plate designs with CIP capability serve dairy and beverage processing. Thailand's concentrated food industry cluster in Pathum Thani and Indonesia's growing packaged food sector specify stainless steel brazed units.
- Automotive:Compact aluminum microchannel cores for engine and battery thermal management. Assembly plants in Thailand's Eastern Economic Corridor and Vietnam's Vinh Phuc province integrate heat exchangers into production lines.
- Healthcare:Steam-to-water heat exchangers for sterilization and HVAC in hospital infrastructure. Singapore's public hospital expansion and Malaysia's specialist medical centers drive specification demand.
Manufacturing absorbs the greatest unit volume. Food and beverage is gaining share fastest.
Technology:
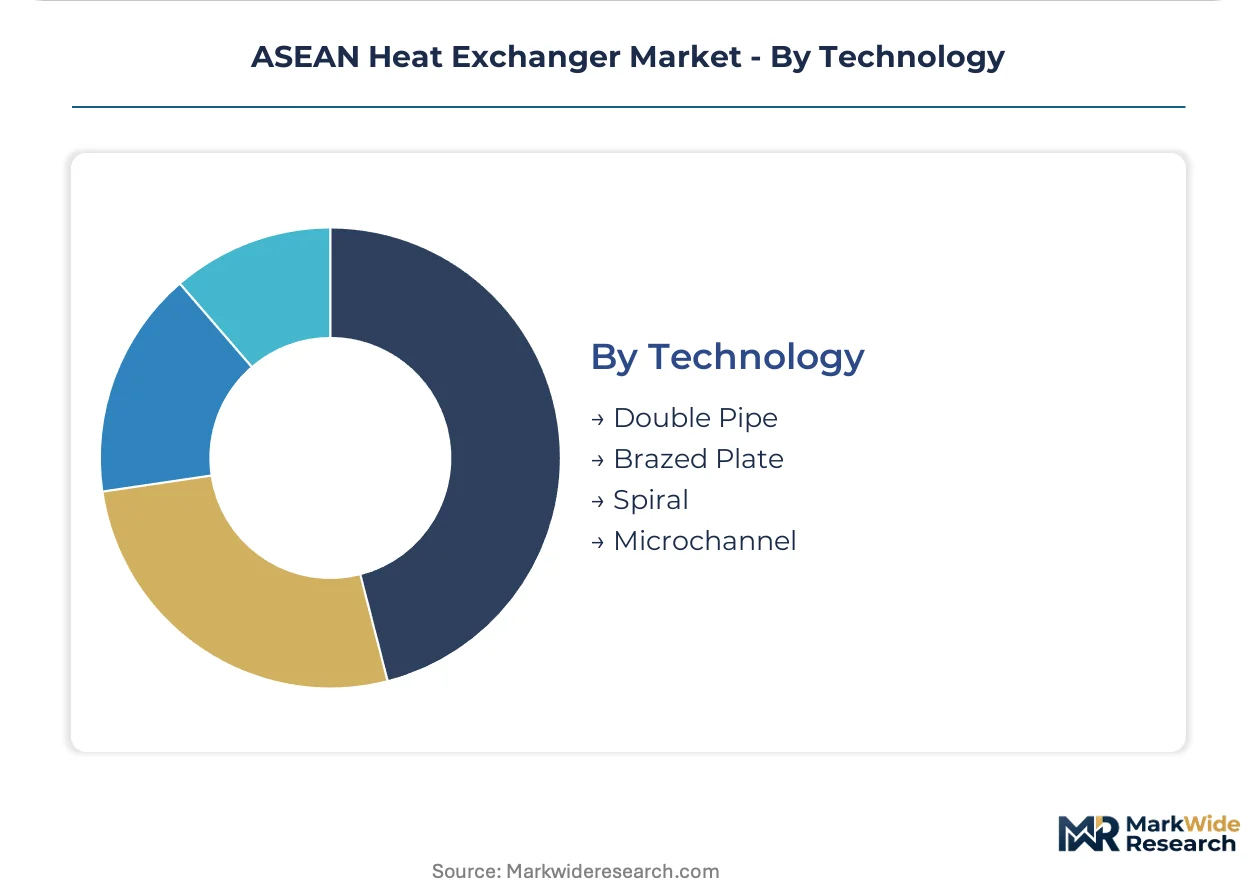
Supply concentration varies by fabrication complexity—brazed plate requires specialized furnace capacity while microchannel demands precision stamping and assembly.
- Microchannel:Multi-port aluminum extrusions achieve heat transfer coefficients above 5,000 W/m²K in compact footprints. Automotive and electronics cooling in Vietnam's precision manufacturing corridors specify these units for space-constrained installations.
- Brazed Plate:Vacuum-brazed stainless steel plates with copper or nickel filler metal create permanent bonds. HVAC and food processing applications across Thailand and Malaysia favor this technology for reliability and leak resistance.
- Spiral:Continuous channel geometry handles fouling-prone slurry service. Indonesian palm oil processing and Thai tapioca starch plants deploy spiral heat exchangers for cleanability in viscous applications.
- Double Pipe:Simple concentric tube design serves low-flow, high-temperature differential service. Small-scale chemical processors and pilot plants across ASEAN use this technology for capital-constrained projects.
By installed base, brazed plate leads. By expansion trajectory, microchannel technology is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ASEAN heat exchanger market draws structural support from Vietnam's 1,000-kilometer North-South power transmission spine, which connects LNG regasification terminals in Ba Ria-Vung Tau to industrial load centers in the Red River Delta.
Vietnam
LNG-to-power projects in Binh Thuan and Ba Ria-Vung Tau provinces drive cryogenic heat exchanger procurement for regasification terminals. The Ministry of Industry and Trade's Power Development Plan VIII prioritizes gas-fired capacity additions. Foreign fabricators partner with domestic engineering firms to meet local content requirements at the Nghi Son refinery expansion.
Thailand
Petrochemical complexes in Map Ta Phut and Rayong anchor replacement demand for high-pressure shell and tube bundles. The Department of Industrial Works mandates continuous emissions monitoring, accelerating retirement of inefficient heat transfer equipment. Eastern Economic Corridor automotive assembly plants specify compact microchannel units for precision cooling loops.
Indonesia
State-linked LNG projects face domestic procurement thresholds enforced by the Ministry of Industry. Pertamina's refinery modernization in Cilacap and Balikpapan redirects sourcing toward certified local fabricators. Surabaya-based engineering clusters develop welding capabilities for ASME Section VIII pressure vessel construction.
Singapore
Jurong Island petrochemical hub specifies corrosion-resistant alloys for acid and caustic service in continuous operation cycles. The Building and Construction Authority mandates granular energy efficiency disclosure for commercial retrofits, compressing payback thresholds for advanced plate heat exchanger upgrades in district cooling networks across the central business district.
Malaysia
Kerteh and Gebeng processing clusters drive demand for specialized materials in chemical service. The Sustainable Energy Development Authority's efficiency incentives accelerate chiller replacements in commercial buildings. Penang's electronics manufacturing corridor specifies microchannel heat exchangers for semiconductor fabrication cooling.
ASEAN Heat Exchanger Market Competitive Environment
Listed leaders compete with private specialists across certification depth and local content compliance. The vendor base stratifies between multinational OEMs holding ASME Section VIII accreditation and domestic fabricators meeting Indonesia's Ministry of Industry procurement thresholds. Three archetypes dominate: premium-certified OEMs serving multinational EPC contracts, mid-scale regional assemblers with hybrid sourcing footprints, and domestic specialists capturing state-mandated local content share. Competitive moves concentrate on strategic partnerships with domestic engineering firms and portfolio diversification into aftermarket service contracts.
Within the premium-certified tier, Alfa Laval AB and Kelvion Holding GmbH exemplify multinational OEMs leveraging established ASME accreditation to anchor positions in petrochemical and power infrastructure contracts. Hisaka Works Ltd occupies a corrosion-resistant specialization niche for chemical processing applications. These three represent the competitive anchor points around which regional assemblers and domestic fabricators position for local content-compliant procurement opportunities.
| Leading Market Players |
|---|
| Alfa Laval AB |
| General Electric Company |
| Danfoss AB |
| Xylem Inc. |
| Kelvion Holding GmbH |
| Hisaka Works Ltd |
| SPX FLOW Inc |
| Thermax Limited |
| Chart Industries Inc |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for high-grade titanium and superalloy plate lock ASEAN fabricators into fixed input costs while insulating them from spot market volatility, yet these same agreements constrain pricing flexibility when Indonesian local content mandates redirect procurement toward domestic suppliers with higher alloy sourcing expenses.
Pricing Analysis
Volume-discount tiering separates ASME Section VIII certified OEMs from regional assemblers and domestic fabricators. Premium pricing rests on accreditation depth and metallurgical specialization for sour gas service, while standard tiers compete on delivery speed for replacement bundles. Price erosion runs through the economy tier as Vietnamese and Indonesian fabricators expand brazed plate capacity. Multinational EPC contractors show least price sensitivity given specification authority, whereas domestic operators in state-linked projects prioritize local content compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant alloys dominates procurement behavior among Thai and Singaporean petrochemical operators facing extended lead times from Japanese and European specialty mills. High-grade titanium plate and superalloy feedstock concentrate in Japan, Germany, and Sweden. Single-source vulnerability concentrates in ASME Section IX welding certification capacity across ASEAN fabricators. Distribution runs through multinational EPC contractors for greenfield projects and domestic engineering firms for local content-compliant state contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN heat exchanger market is recovering from cyclical compression in refinery capital expenditure, with replacement demand accelerating as Thailand's emissions monitoring mandates force equipment turnover regardless of new-build investment cycles.
For Market Incumbents: Fortify certification depth through ASME Section VIII inspector training partnerships in Surabaya and Bangkok to counter the welding certification shortage threatening capacity expansion. Deepen backward integration into alloy plate sourcing through offtake agreements with Japanese specialty mills, reducing exposure to input cost volatility that squeezes margins on fixed-price EPC contracts. For New Entrants and Emerging Players: Aftermarket service unbundling in Vietnam's petrochemical corridor presents white-space opportunity where end-users separate spare parts procurement from OEM maintenance agreements. Target localized inventory positions for replacement bundles in Ba Ria-Vung Tau and Map Ta Phut. Pursue digital twin integration partnerships with predictive maintenance software providers to capture outcome-based service contracts. For Investors and Strategic Acquirers: Capital is best deployed toward domestic fabricators with ASME Section VIII accreditation and established relationships with Indonesia's Ministry of Industry for local content compliance. Long-term viability hinges on positioning for Vietnam's LNG-to-power buildout and Singapore's district cooling retrofit mandates. Watch for inflection when cryogenic heat exchanger qualification data from additive manufacturing pilots achieves petrochemical operator acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Expansion | Training partnerships in Surabaya and Bangkok address inspector scarcity constraining project timelines. |
| Alloy Supply Agreement | Long-term offtake with Japanese specialty mills reduces input cost volatility for high-pressure construction. |
| Digital Twin Integration | IoT sensor deployment enables predictive maintenance contracts for refinery fleet management. |
| Local Content Compliance | Domestic engineering partnerships unlock Indonesia's state-linked LNG procurement thresholds. |
| Additive Manufacturing Pilot | Complex channel geometries from selective laser melting improve thermal performance qualification data. |
Study Parameters
Cross-validation between primary interviews with EPC procurement officers, plant engineers at Thai and Vietnamese refineries, and aftermarket service managers anchors the qualitative findings against secondary sources including customs trade data, ASME certification registries, and Indonesia's Ministry of Industry procurement disclosures. Bottom-up triangulation aggregates unit-level procurement patterns across LNG-to-power projects, while top-down analysis cross-checks against national energy infrastructure investment frameworks.
Sensitivity analysis tests forecast robustness across alloy price volatility scenarios and local content threshold variations. The modeling framework segments by product architecture, application severity, and end-user specification authority across the projection horizon. CAGRs derive from replacement cycle acceleration rates tied to emissions monitoring enforcement and new-build procurement tied to power development plans. Cryogenic heat exchanger demand from Vietnam's regasification terminals and microchannel adoption in precision manufacturing corridors serve as key demand-side inputs.
Underlying assumptions cover continuous enforcement of Indonesia's domestic procurement thresholds and sustained Thailand emissions monitoring compliance, with deviation risk concentrated in ASME Section IX welding certification capacity expansion and additive manufacturing qualification timelines. Forecasts reflect these conditions with acknowledgment that alloy supply disruptions or regulatory threshold modifications could compress or extend replacement cycles. Revision becomes warranted when local content compliance costs exceed price premiums commanded by multinational OEMs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Cooling Tower Market