
 Cooling Tower Fans Market | 2026-2036
Cooling Tower Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Tower Fans Market Analysis
The gap between premium engineered axial fans and commodity belt-drive units is expanding as data center operators and combined-cycle power plants demand precision airflow control and predictive maintenance integration. Johnson Controls leverages its building automation ecosystem to bundle smart fan packages with HVAC system contracts. SPX Cooling Technologies sustains dominance in heavy industrial applications through proprietary composite blade designs that resist corrosive cooling tower environments. Munters Group differentiates via energy-efficient direct-drive technology that eliminates belt maintenance in continuous-operation facilities.
Cooling tower fans are mechanical air-moving devices designed to induce or force airflow through heat exchange media in evaporative cooling systems, typically operating at static pressures between 0.5 and 2.0 inches of water column and tip speeds engineered to minimize drift loss while maximizing thermal transfer efficiency. Axial fan configurations occupy the largest installed base across power generation and petrochemical applications where high-volume, low-pressure airflow matches cooling load requirements. Belt-drive technology retains significant share in retrofit markets where facility managers prioritize initial cost over lifecycle efficiency, while variable-speed direct-drive systems capture margin pools in data center and pharmaceutical cleanroom installations demanding precise temperature modulation.
The EPA regulates cooling water intake structures under Section 316(b), compelling utilities to document reduced environmental impact through upgraded fan and fill systems that lower recirculation rates. OSHA ventilation standards and ASHRAE thermal guidelines shape product certification requirements for indoor and outdoor cooling tower installations across commercial and industrial sites. Stakeholders must monitor evolving state-level water conservation mandates and carbon disclosure frameworks that will increasingly tie cooling system efficiency to operating permits and capital access.
Market Dynamics
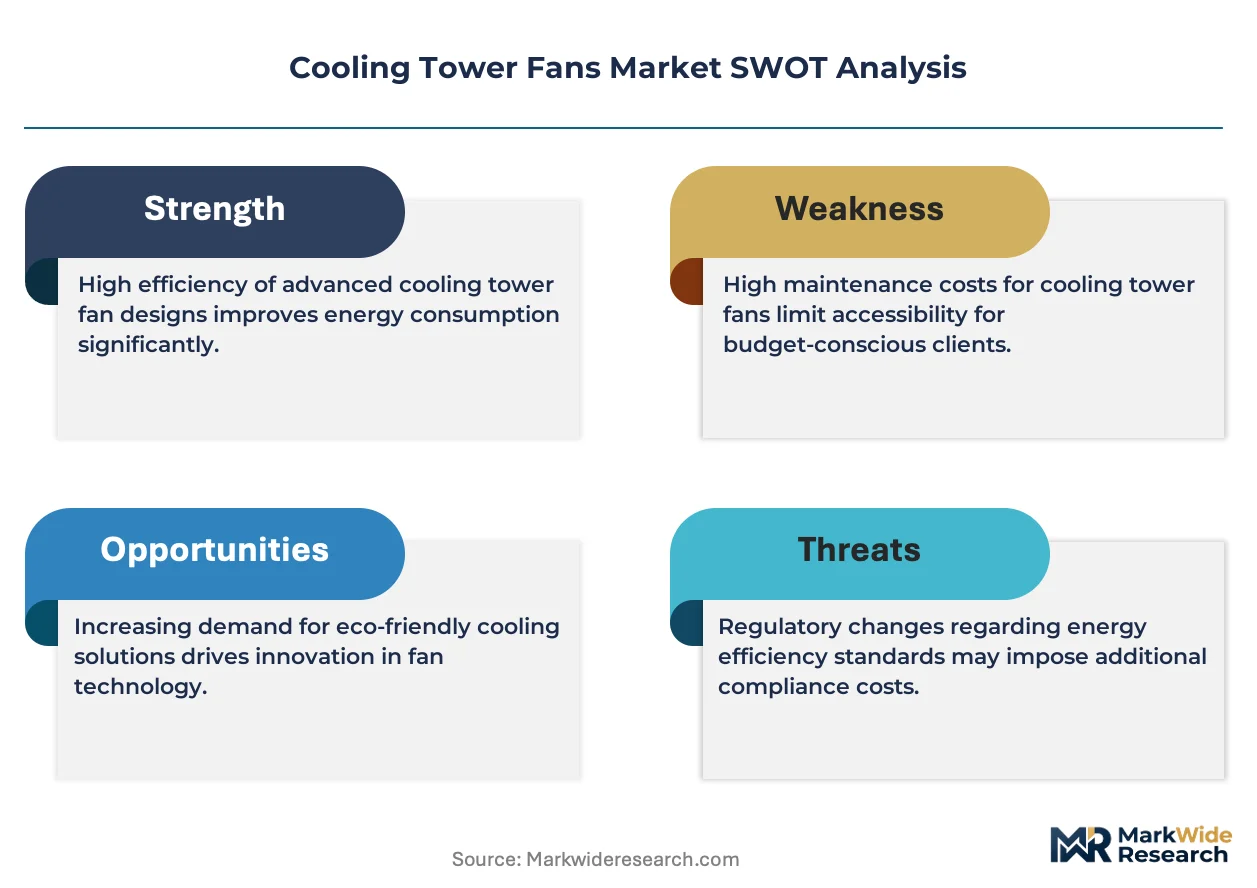
The EPA's Section 316(b) cooling water intake regulations are forcing utilities and industrial operators to replace legacy fan systems with higher-efficiency designs that reduce entrainment and impingement impacts. This regulatory pressure is compressing replacement cycles and favoring precision-engineered axial fans over commodity belt-drive units.
Growth Catalysts
- EPA Section 316(b) Compliance:Power generation facilities across the United States face mandated upgrades to cooling water intake structures, driving systematic replacement of aging fan systems with high-efficiency alternatives that reduce environmental impact.
- Data Center Thermal Loads:Hyperscale computing facilities require variable-speed direct-drive fans capable of precise temperature modulation, creating sustained demand for premium engineered systems with predictive maintenance integration.
- Gulf Coast Petrochemical Expansion:Ethylene and LNG facility construction along the Texas-Louisiana corridor requires massive evaporative cooling capacity, concentrating procurement of corrosion-resistant composite blade systems.
Market Restraints
- Aluminum and Copper Price Volatility:Motor housings and electrical windings face input cost pressure from commodity metal markets, squeezing margins on mid-tier belt-drive fan assemblies.
- Composite Blade Supply Concentration:Proprietary fiberglass and carbon fiber formulations for corrosive cooling tower environments rely on a limited supplier base concentrated in North American specialty chemical processors.
- Legacy Belt-Drive Obsolescence Risk:Continuous-operation facilities face stranded asset exposure as direct-drive technology eliminates maintenance-intensive belt systems from new procurement specifications.
Strategic Opportunities
- India Industrial Cooling:Steel, cement, and fertilizer capacity expansion under the PLI scheme creates demand for heavy-duty induced-draft fans in high-dust, high-humidity operating environments.
- Predictive Maintenance Convergence:Integration of vibration sensors and edge computing with direct-drive motors enables condition-based maintenance contracts, shifting revenue from equipment sales to service subscriptions.
- EU F-Gas Regulation Alignment:Cooling tower efficiency upgrades qualify for carbon disclosure framework credits, creating procurement preference for fan systems with documented energy performance certification.
Industry Challenges
- Aerodynamic Engineering Talent Scarcity:Blade design optimization for specific cooling tower geometries requires specialized computational fluid dynamics expertise concentrated among senior engineers at incumbent manufacturers.
- Legacy Control System Integration:Variable-frequency drive retrofits into existing building automation networks face protocol incompatibility with 1990s-era SCADA installations in municipal and institutional facilities.
- OSHA Confined Space Certification:Fan installation and maintenance inside cooling tower plenums requires specialized safety training and documentation, extending project timelines and contractor qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Tower Fans Market |
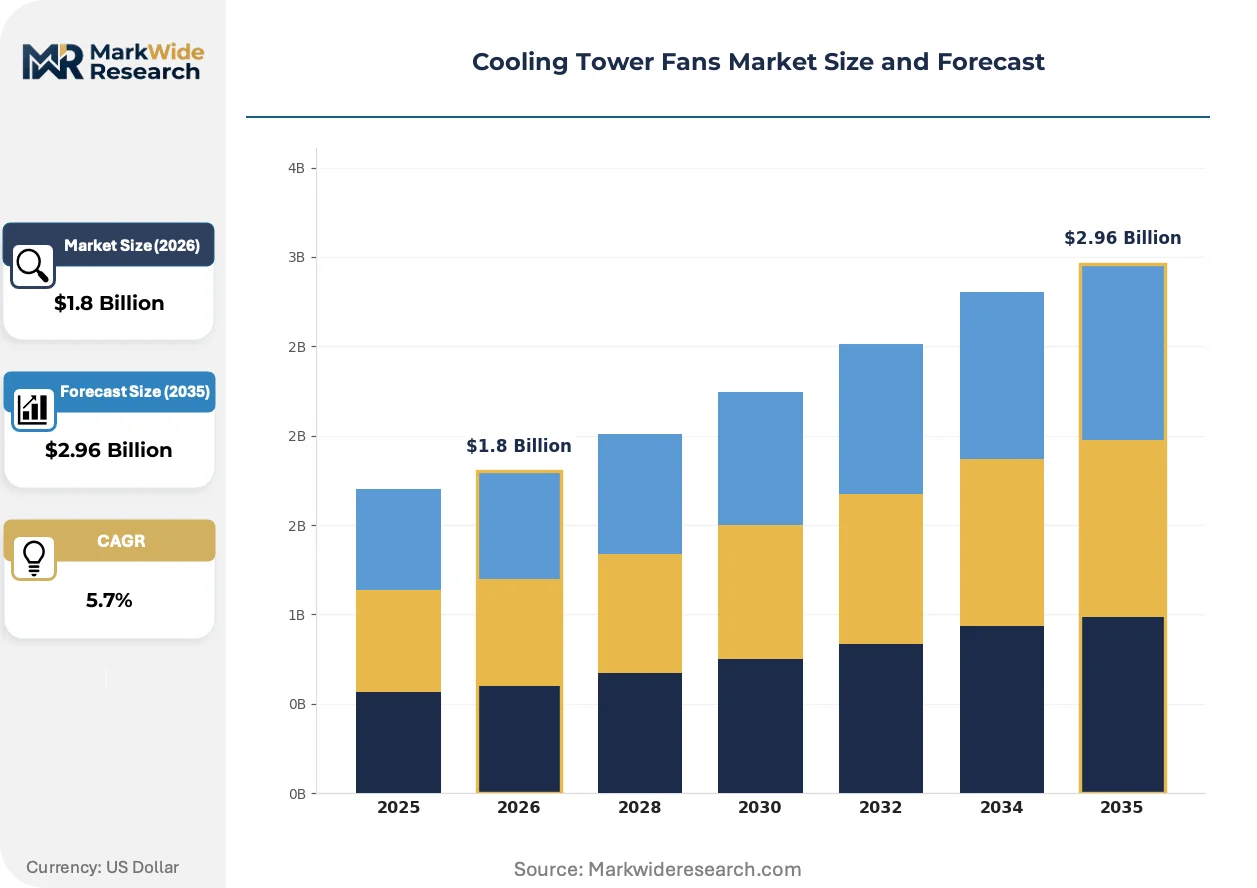
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Axial, Centrifugal, Mixed Flow, Cross Flow Application: Power Generation, HVAC Systems, Industrial Processes, Wastewater Treatment Material: Aluminum, Stainless Steel, Fiberglass, Plastic Technology: Direct Drive, Belt Drive, Variable Speed, Energy Efficient |
| Companies Covered | Johnson Controls, Ebara Corporation, SPX Cooling Technologies, Delta Cooling Towers, Munters Group, Baltimore Aircoil Company, Howden, Paharpur Cooling Towers, EVAPCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Tower Fans Market Emerging Trajectories
Digital twin technology and edge-based condition monitoring are compressing maintenance intervals and enabling performance-based service contracts. Equipment suppliers are repositioning from component vendors to thermal management partners.
Computational fluid dynamics software coupled with additive manufacturing is automating custom blade profile generation for site-specific cooling tower geometries. Combined-cycle power plants in the United States are adopting these digitally optimized fans at accelerated replacement cycles. This capability is automating the shift from standardized catalog products to engineered-to-order systems with documented efficiency guarantees.
The EPA's tightened interpretation of Section 316(b) best technology available standards is compelling utilities to document reduced impingement mortality through upgraded fan and fill combinations. Industrial facilities must now submit comprehensive cooling water intake structure studies as part of operating permit renewals. Power generators in the Ohio River Valley and Great Lakes regions are responding with systematic fan system replacements ahead of regulatory deadlines.
Facility managers are unbundling aftermarket service from original equipment procurement, selecting third-party maintenance providers with specialized cooling tower expertise. This fragmentation is displacing manufacturer-captive service networks in the commercial HVAC segment. Data center operators in Northern Virginia and Phoenix are most visible in this shift, negotiating multi-site service agreements independent of initial fan system suppliers.
Cooling Tower Fans Market Segmentation
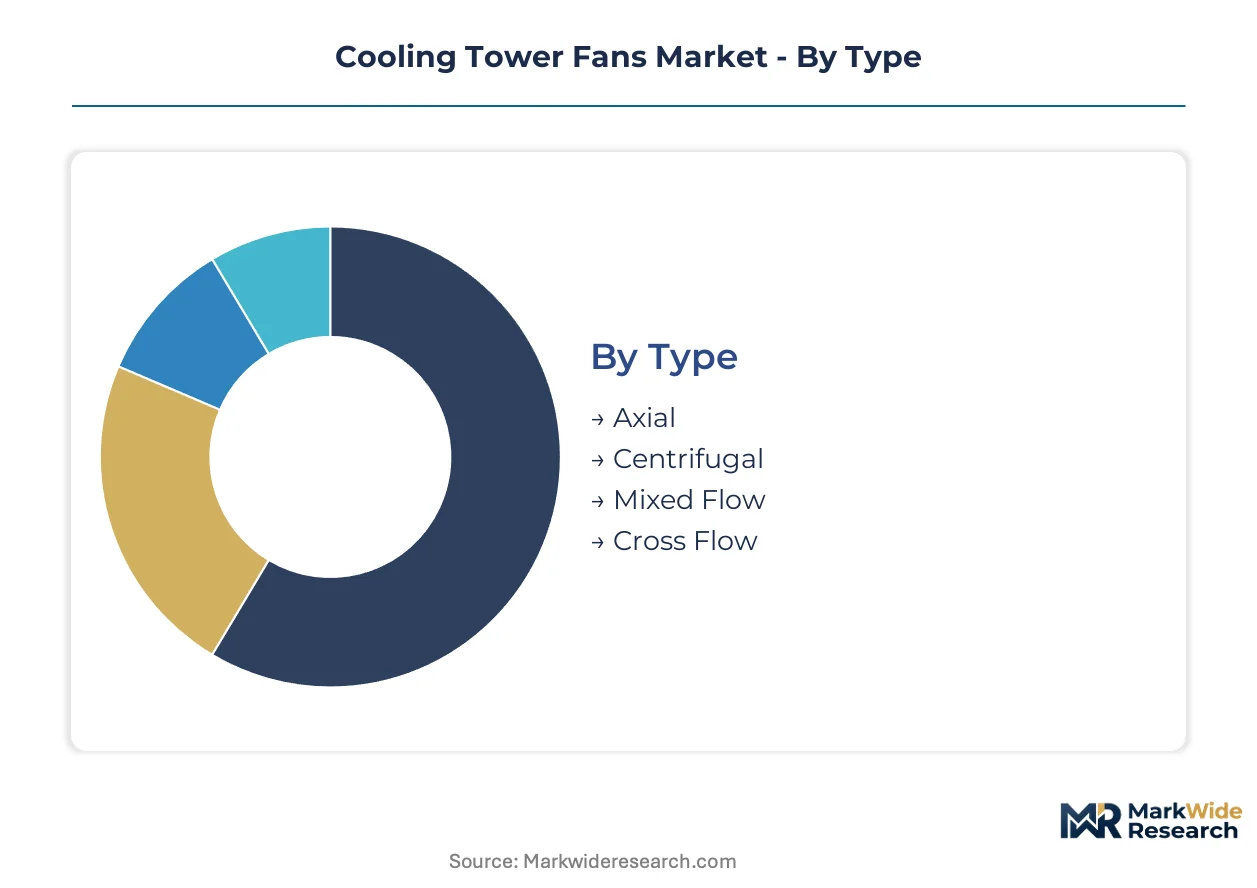
Cooling tower fan procurement hinges on matching aerodynamic performance to thermal load profiles while navigating regulatory compliance timelines. Buyers segment choices across four intersecting dimensions where material selection and drive technology determine lifecycle economics.
Type:
Facility engineers prioritize pressure-drop characteristics and footprint constraints when selecting fan configurations for specific cooling tower geometries.
- Axial:Propeller-style blades generate high-volume airflow at low static pressure, typically 0.5–2.0 inches water column. Power generation facilities across the United States favor axial configurations for induced-draft cooling towers where minimal pressure differential maximizes thermal transfer efficiency.
- Centrifugal:Radial blade designs produce higher pressure differentials suitable for compact plenum spaces or contaminated airstreams. HVAC systems in urban commercial buildings specify centrifugal fans where ductwork constraints demand pressure capability over raw airflow volume.
- Mixed Flow:Hybrid geometry combining axial throughput with centrifugal pressure characteristics serves retrofit applications with non-standard tower dimensions.
- Cross Flow:Horizontal airflow orientation accommodates low-profile cooling tower designs common in rooftop installations with height restrictions.
Volume sits with Axial; growth tilts toward Mixed Flow.
Application:
End-use thermal loads dictate fan duty cycles, corrosion exposure, and control system complexity.
- Power Generation:Continuous-operation thermal power plants require induced-draft fans engineered for 20-year service intervals with minimal maintenance access. EPA Section 316(b) compliance deadlines are compressing replacement cycles across coal and nuclear facilities in the Ohio River Valley.
- HVAC Systems:Commercial building automation demands variable-speed capability for part-load efficiency. Data center operators in Northern Virginia and Phoenix specify direct-drive systems with predictive maintenance integration.
- Industrial Processes:Petrochemical and steel production facilities expose fans to corrosive atmospheres and particulate loading.
- Wastewater Treatment:Odor control and biological process cooling impose intermittent duty cycles with high humidity exposure.
Power Generation commands installed base; HVAC Systems expand most quickly.
Material:
Corrosion resistance and weight tradeoffs dominate material selection for specific cooling water chemistries.
- Aluminum:Cast and extruded alloys offer favorable strength-to-weight ratios for large-diameter fan assemblies. Coastal petrochemical facilities specify marine-grade aluminum with anodized finishes to withstand salt-laden atmospheres.
- Stainless Steel:Austenitic grades provide maximum corrosion resistance in aggressive chemical environments. Pharmaceutical cleanrooms and food processing plants mandate stainless construction for hygienic compliance.
- Fiberglass:Composite blade formulations resist chemical attack and electrolytic corrosion in cooling towers with aggressive water treatment chemistry.
- Plastic:Engineered polymers serve small-diameter fans in light-duty commercial applications with minimal structural loading.
Aluminum holds volume leadership; Fiberglass gains share fastest.
Technology:
Drive system selection separates lifecycle efficiency from first-cost procurement decisions.
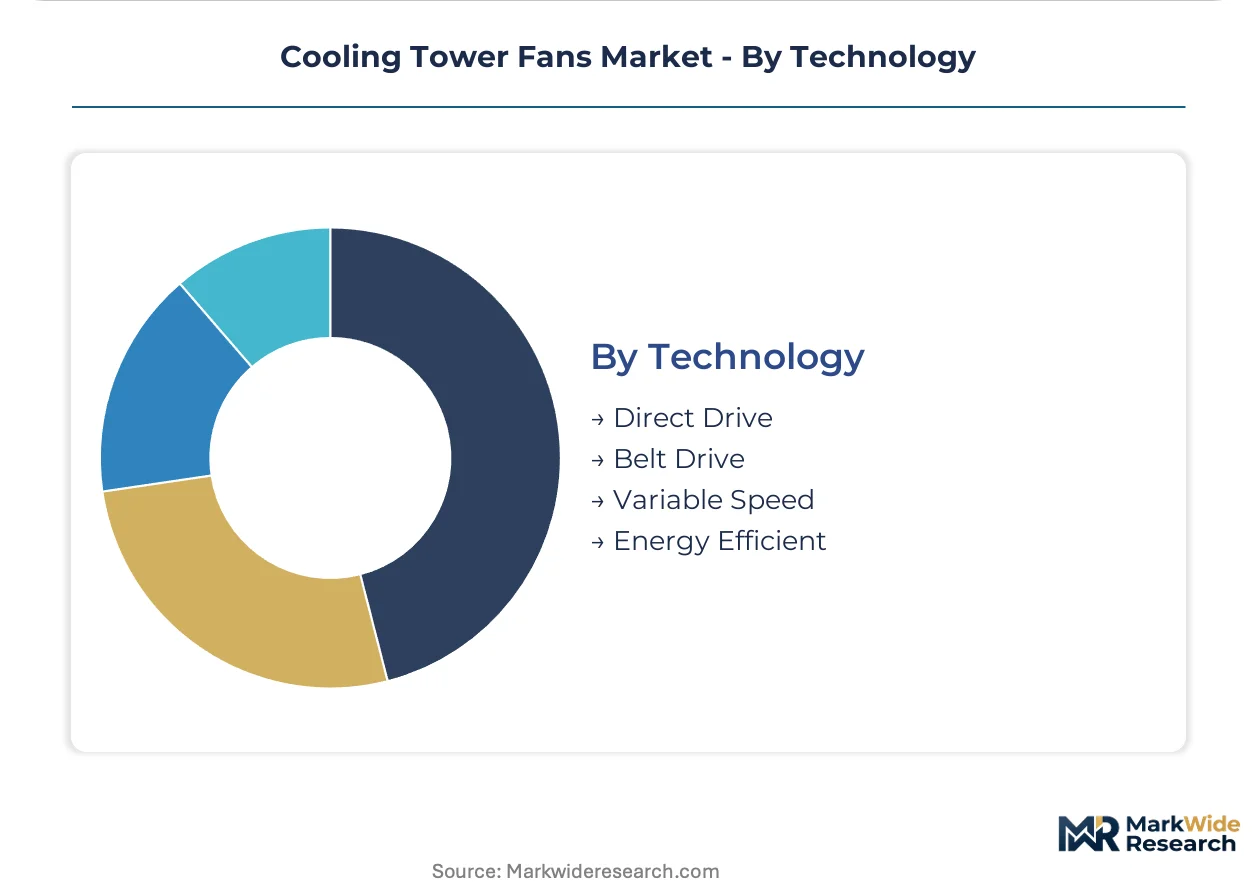
- Direct Drive:Motor shaft connects directly to fan hub, eliminating belt maintenance and slip losses. Continuous-operation facilities in the Gulf Coast petrochemical corridor specify direct-drive systems to eliminate belt replacement downtime.
- Belt Drive:Pulley and V-belt arrangements allow motor placement outside the airstream with flexible speed ratios. Retrofit markets prioritize belt-drive configurations where existing motor mounts constrain direct-drive conversion.
- Variable Speed:Variable-frequency drives modulate airflow to match thermal load, reducing energy consumption at part-load conditions.
- Energy Efficient:Premium efficiency motor classifications and aerodynamically optimized blade profiles reduce power draw for carbon disclosure frameworks.
Belt Drive retains retrofit volume; Direct Drive climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Louisiana Gulf Coast petrochemical corridor anchors procurement intensity for corrosion-resistant cooling tower fans, with ethylene crackers and LNG export terminals driving specification of composite-blade direct-drive systems.
United States
Power generators in the Ohio River Valley and Great Lakes regions face compressed replacement cycles from EPA Section 316(b) compliance deadlines. The EPA's tightened cooling water intake regulations mandate systematic upgrades to reduce impingement mortality. Data center clusters in Northern Virginia and Phoenix specify variable-speed direct-drive systems with predictive maintenance integration.
Germany
Chemical producers along the Rhine corridor demand cooling tower fans aligned with EU F-Gas Regulation carbon disclosure frameworks. The EU Green Deal efficiency standards create procurement preference for documented energy performance certification. Industrial facilities in North Rhine-Westphalia and Baden-Württemberg are retrofitting legacy belt-drive systems ahead of regulatory deadlines.
China
Steel and cement capacity expansion under national dual carbon goals drives demand for heavy-duty induced-draft fans. The Ministry of Ecology and Environment enforces stricter thermal efficiency standards for industrial cooling systems. Manufacturing clusters in the Yangtze River Delta and Shandong Peninsula concentrate procurement of aluminum-blade axial configurations.
India
Steel, cement, and fertilizer capacity expansion under the PLI scheme creates demand for cooling tower fans in high-dust, high-humidity environments. The Central Electricity Authority mandates efficiency upgrades for thermal power plant auxiliary systems. Industrial corridors in Gujarat and Maharashtra specify corrosion-resistant fiberglass blade systems for coastal and chemical zone installations.
Saudi Arabia
Petrochemical complexes in the Eastern Province require massive evaporative cooling capacity for ethylene and derivative production. The Saudi Standards, Metrology and Quality Organization implements energy efficiency labeling for industrial cooling equipment. Jubail Industrial City and Yanbu concentrate procurement of direct-drive systems designed for continuous operation in high-salinity atmospheres.
Cooling Tower Fans Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cooling tower fan market. Integrated manufacturers with captive composite formulation and blade molding capabilities command premium positioning in corrosive environment applications. The vendor base separates into three archetypes: diversified building automation conglomerates bundling smart fan packages, specialized cooling tower OEMs with proprietary aerodynamic designs, and regional metal fabrication shops serving retrofit belt-drive demand. Consolidation pressure is accelerating through strategic partnerships between motor manufacturers and blade designers, while geographic expansion into India's industrial corridor attracts new entrants.
Within the diversified conglomerate tier, Johnson Controls leverages building automation ecosystem integration. Among specialized cooling OEMs, SPX Cooling Technologies and Munters Group exemplify contrasting technology bets—composite blade durability versus direct-drive energy efficiency. These three companies anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Johnson Controls |
| Ebara Corporation |
| SPX Cooling Technologies |
| Delta Cooling Towers |
| Munters Group |
| Baltimore Aircoil Company |
| Howden |
| Paharpur Cooling Towers |
| EVAPCO |
| Others |
Supply Flow & Price Mechanics
EPA Section 316(b) compliance documentation gates both qualified supply and premium-tier pricing access for cooling tower fan manufacturers, as utilities and industrial operators demand certified efficiency guarantees that only engineered-to-order suppliers can deliver. This regulatory filter compresses procurement pools to vendors with proven aerodynamic design capabilities and composite blade formulation expertise, concentrating pricing power among integrated producers while squeezing commodity belt-drive assemblers.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for direct-drive axial fans in continuous-operation power plants, where thermal transfer reliability outweighs capital expenditure concerns. Three-tier pricing structure across premium engineered systems, mid-tier belt-drive retrofits, and economy standard units separates procurement pools by certification grade and predictive maintenance integration. Cost compression in mid-tier assemblies is intensifying because aluminum and copper motor housing volatility squeezes margin buffers for regional metal fabricators. Municipal utilities and institutional facilities exhibit highest price sensitivity, while hyperscale data center operators in Northern Virginia and Phoenix prioritize lifecycle efficiency over first-cost procurement.
Supply Chain Analysis
Refurbishment flows for legacy belt-drive systems create secondary market circulation that buffers raw material demand spikes and extends composite blade replacement cycles. Manufacturing concentration centers on the United States, Germany, and China, where captive composite formulation capabilities and precision motor winding expertise cluster. Supply chains draw from specialized fiberglass and carbon fiber processors, premium efficiency motor suppliers, and precision bearing manufacturers. Single-source vulnerability concentrates in proprietary composite blade formulations for corrosive cooling tower environments. Distribution runs through OEM-direct specification for large industrial projects and regional HVAC distributors for commercial retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cooling tower fan market is consolidating around integrated manufacturers with captive composite capabilities, as EPA compliance complexity and predictive maintenance integration requirements force weaker regional fabricators toward exit or acquisition.
For Market Incumbents: Lock in exclusive supply agreements with Gulf Coast petrochemical operators before 316(b) replacement cycles peak, securing multi-year direct-drive system contracts with embedded service subscriptions. Deepen backward integration into proprietary composite blade molding to defend margin position against motor manufacturer forward integration. Capture stranded belt-drive retrofit demand through certified remanufacturing programs that extend asset life for municipal utilities with constrained capital budgets. For New Entrants and Emerging Players: Begin with India industrial corridor penetration, where PLI scheme capacity expansion creates demand for heavy-duty induced-draft fans in high-dust steel and cement environments with limited incumbent service presence. Target pharmaceutical cleanroom and food processing segments requiring stainless steel construction with documented hygienic compliance, bypassing saturated power generation procurement. Establish go-to-market partnerships with regional HVAC distributors already embedded in commercial building automation networks rather than competing for direct OEM specification. For Investors and Strategic Acquirers: First-mover adoption of digital twin-enabled predictive maintenance contracts by data center operators is the leading indicator that service revenue models are displacing equipment sales across premium tier demand. Position acquisition screening toward mid-cap composite blade specialists with EPA certification track records and installed base in Ohio River Valley power generation. Monitor state-level water conservation mandate announcements for early signals of accelerated replacement cycle compression beyond federal 316(b) deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Blade Molding | Captive supply of corrosion-resistant formulations secures margin pools in Gulf Coast petrochemical procurement. |
| Predictive Maintenance Platform Launch | Vibration sensor integration with direct-drive motors shifts revenue from equipment sales to recurring service subscriptions. |
| EPA 316(b) Certification Fast-Track | Expedited compliance documentation accelerates specification for compressed utility replacement cycles in Great Lakes regions. |
| India Industrial Corridor Expansion | Local production presence captures PLI scheme steel and cement capacity expansion in Gujarat and Maharashtra. |
| Remanufacturing Service Network Buildout | Certified belt-drive refurbishment extends asset life for municipal utilities with constrained capital budgets. |
Methodological Framework
Multi-period observation of EPA compliance deadline progression, utility capital expenditure disclosures, and petrochemical facility commissioning anchored the trend analysis, supplemented by interviews with cooling tower OEM procurement directors, plant maintenance engineers at continuous-operation power facilities, composite materials suppliers, and HVAC distribution channel managers. Secondary validation drew from EPA Section 316(b) regulatory filings, FERC generator interconnection queues, EIA power plant operating data, and SEC 10-K equipment supplier disclosures. Bottom-up unit demand modeling across installation type and drive technology converged with top-down thermal load capacity expansion estimates.
Input-output matrices mapped cooling tower fan procurement to underlying thermal infrastructure investment cycles, segmenting volume and value across axial/centrifugal configurations, direct-drive/belt-drive technology, aluminum/fiberglass/stainless steel material grades, and power generation/HVAC/industrial process end-use applications. CAGRs were derived from regression analysis of historical replacement rates against regulatory compliance timelines and capacity expansion announcements. Forecast inputs incorporated hyperscale data center power density trajectories and dual carbon policy enforcement intensity in China and India.
Underlying measurement precision varies by segment; power generation replacement demand carries tighter precision than emerging data center procurement given visible regulatory deadlines. Forecasts reflect assumptions about EPA enforcement continuity, commodity metal price stability, and composite material supply expansion that could shift with tariff policy or specialty chemical processor consolidation. Practitioners should monitor state-level water conservation mandate announcements and hyperscale data center power density disclosures for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
North America Scrubber System Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Air Pressure Booster System Market