
 Roof Insulation Market | 2026-2036
Roof Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Roof Insulation Market Outlook
Data center construction is realigning roof insulation specifications toward higher thermal resistance and fire-rated assemblies. Owens Corning leverages its fiberglass manufacturing scale to serve hyperscale facility projects across North America. Saint-Gobain anchors European supply through integrated mineral wool production networks. ROCKWOOL International specializes in non-combustible stone wool solutions for jurisdictions with strict fire safety protocols.
Roof insulation comprises thermal barrier materials installed above structural decks to reduce heat transfer, typically specified by R-value per inch and compressive strength for load-bearing applications. Fiberglass dominates residential retrofits due to cost accessibility and installer familiarity, while polyurethane spray foam captures premium commercial projects where air sealing and high R-value per inch justify material cost. Mineral wool commands institutional and industrial specifications where fire resistance ratings exceed polymer-based alternatives, and rigid board polystyrene maintains position in low-slope commercial roofing assemblies.
EPA Energy Star certification and the EU Green Deal building renovation targets shape product efficiency thresholds and retrofit timelines across multiple jurisdictions. OSHA workplace exposure limits and REACH chemical compliance constrain formulation choices for spray foam contractors and manufacturers. Stakeholders must monitor evolving R-value requirements and embodied carbon disclosure rules as procurement criteria shift toward lifecycle performance metrics.
Market Dynamics
Building energy codes are tightening across multiple jurisdictions, forcing specification upgrades from legacy batt insulation toward higher-performance assemblies that meet elevated R-value mandates and fire safety ratings.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory efficiency retrofits across Germany, France, and Italy are pulling mineral wool and rigid board volumes into multi-family housing stock.
- Data center thermal management:Hyperscale facility operators in the United States are specifying stone wool and spray foam assemblies to meet stringent fire resistance and cooling load requirements.
- Polyurethane spray foam chemistry advances:Low-global-warming-potential blowing agents are expanding commercial applicability where high thermal resistance per inch remains critical.
Market Restraints
- Petrochemical input volatility:Isocyanate and polyol price swings compress spray foam contractor margins and destabilize project bidding.
- Mineral wool supply concentration:European stone wool production clusters in Denmark and Germany create geographic vulnerability to energy cost shocks.
- REACH chemical compliance:ECHA restrictions on certain flame retardants force formulation changes that extend product recertification timelines.
Strategic Opportunities
- China dual carbon goals:Building efficiency mandates in Beijing and Shanghai are opening specification windows for imported mineral wool and rigid foam technologies.
- Prefabricated roof panel integration:Offsite construction channels in the United States are creating bundled insulation-structural assembly demand.
- OSHA workplace exposure rule evolution:Tighter isocyanate handling protocols favor contractors with certified spray foam application training and enclosed mixing systems.
Industry Challenges
- Spray foam installer certification gaps:Shortage of SPF-PCA credentialed technicians constrains contractor capacity in high-growth metro corridors.
- Embodied carbon disclosure compliance:EPD documentation requirements demand lifecycle data collection that smaller mineral wool fabricants lack systems to generate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roof Insulation Market |
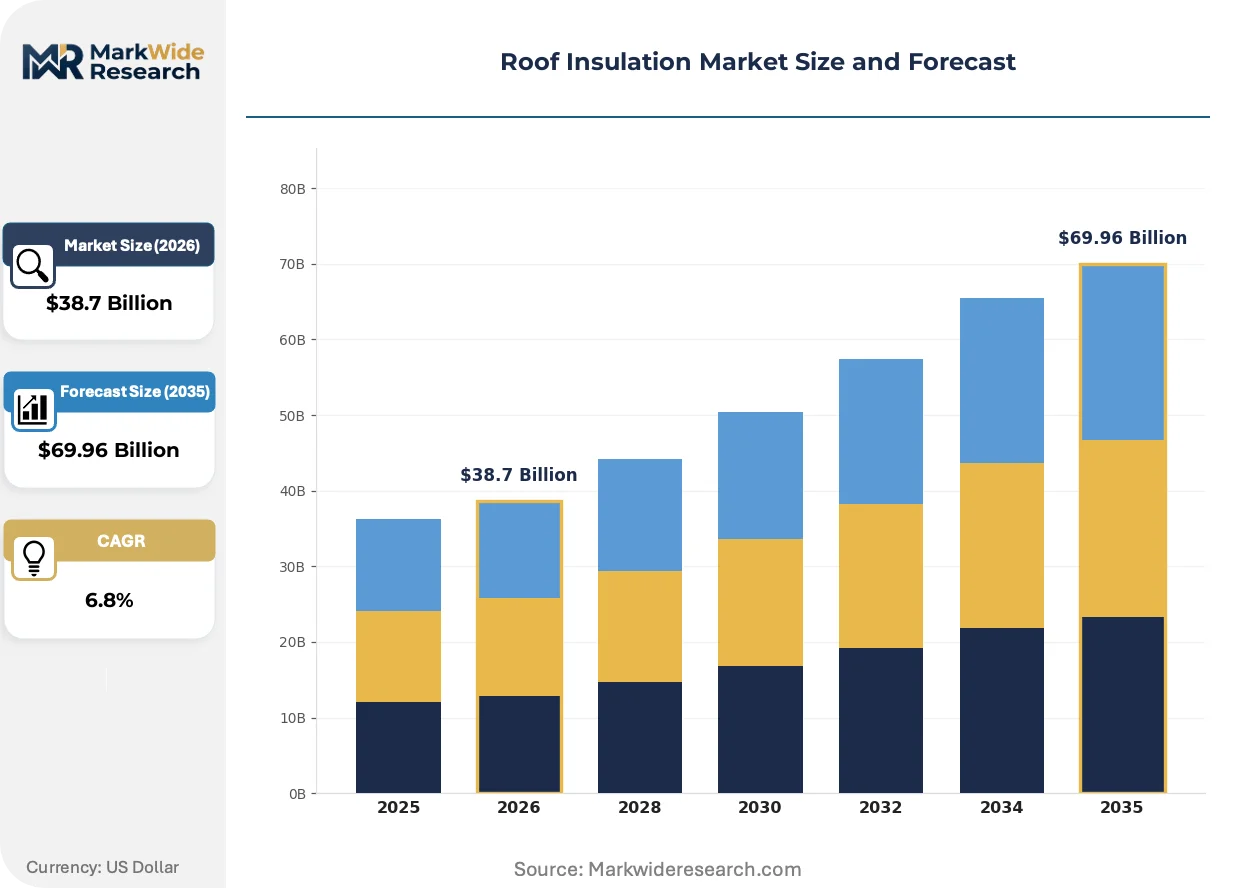
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Polystyrene, Polyurethane, Mineral Wool Installation Method: Spray Foam, Rigid Board, Batt, Loose Fill End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Agricultural Structures Thermal Resistance: R-Value 10, R-Value 20, R-Value 30, R-Value 40 |
| Companies Covered | Owens Corning, Saint-Gobain, ROCKWOOL International, Knauf Insulation, BASF, Kingspan Group, Johns Manville, Dow Inc., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roof Insulation Market Strategic Shifts
Aerogel and vacuum insulation panels are compressing thermal envelope thickness requirements, while digital specification tools are accelerating material selection cycles for complex commercial assemblies.
Aerogel blanket systems are rewriting roof insulation performance benchmarks by delivering R-values exceeding ten per inch in space-constrained retrofit applications. Data center operators and urban high-rise developers are specifying these materials where structural load limits and ceiling height restrictions prevent conventional thick insulation. The technology is compressing the tradeoff between thermal performance and usable interior volume that has governed commercial roofing design for decades.
EPA Energy Star certification updates are mandating whole-roof assembly testing rather than material-only R-value claims. Roofing contractors must now submit thermal bridging calculations and air leakage documentation that extends pre-bid engineering timelines. Commercial retrofit projects in California and New York are experiencing specification delays as design teams adapt to assembly-level compliance verification.
Building information modeling integration is shifting material selection from catalog-based specification to parametric optimization driven by energy simulation outputs. Architects and mechanical engineers are running real-time thermal performance scenarios that automatically surface insulation alternatives meeting cost and carbon targets. This behavior is most visible in United States commercial office retrofits where LEED v4.1 and WELL certification requirements demand documented envelope performance.
Roof Insulation Market Segmentation
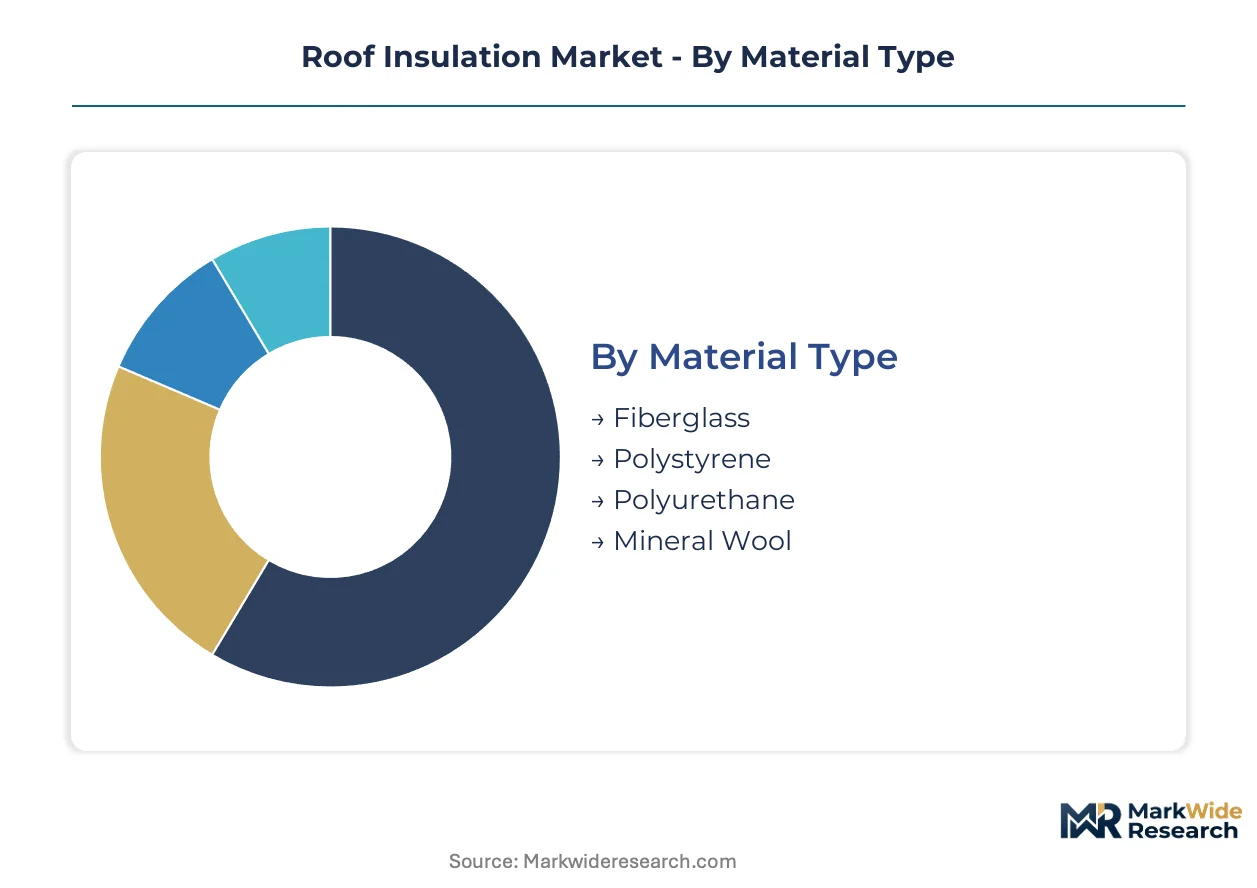
Roof insulation procurement splits across material chemistry, installation logistics, and performance specifications. Contractors and specifiers navigate tradeoffs between thermal efficiency, fire safety ratings, and labor skill requirements when selecting from these intersecting categories.
Material Type:
Standardization dominates commodity grades while engineered formulations command premium positioning across this category.
- Fiberglass:Composed of fine glass fibers bound with thermosetting resins, available in batt and loose-fill densities. Residential retrofits in the United States concentrate demand here as contractor familiarity and material accessibility reduce installation friction. Cost sensitivity in single-family housing reinforces fiberglass's volume position despite lower R-value per inch versus alternatives.
- Mineral Wool:Manufactured from molten rock or slag spun into fibers, delivering non-combustible performance with melting points exceeding 1000°C. Commercial and institutional specifications in Germany and Denmark favor this material where building codes mandate stringent fire resistance ratings. EU Green Deal renovation targets are accelerating specification shifts toward stone wool in multi-family housing retrofits.
- Polystyrene:Rigid cellular plastic boards produced via extrusion or expansion processes, valued for compressive strength in load-bearing roof assemblies.
- Polyurethane:Closed-cell spray foam or rigid board configurations delivering highest thermal resistance per inch among mainstream materials.
Most installed capacity flows through fiberglass. Expansion is steepest in mineral wool.
Installation Method:
Labor intensity and equipment requirements create distinct cost tiers across application techniques.
- Spray Foam:Two-component chemical systems that expand and cure in place, creating monolithic air barriers with superior thermal bridging control. Hyperscale data center projects in the United States specify spray foam where complex roof geometries and stringent air leakage limits justify premium material and labor costs. OSHA isocyanate exposure regulations are tightening contractor certification requirements and constraining available installation capacity.
- Rigid Board:Pre-formed panels installed above structural decks, enabling predictable thermal performance and simplified quality verification. Low-slope commercial roofing assemblies in North America rely heavily on polystyrene and polyisocyanurate boards where compressive strength and dimensional stability matter. Offsite prefabrication trends are bundling rigid insulation with structural panels in United States construction channels.
- Batt:Flexible fiber blankets cut to fit between framing members, representing the most labor-accessible installation pathway.
- Loose Fill:Blown or poured particulate insulation suited to irregular cavities and retrofit applications.
Volume concentrates in batt installations. Spray foam is gaining share fastest in commercial segments.
End User:
Building type dictates fire rating requirements, energy code stringency, and lifecycle performance expectations.
- Residential Buildings:Single-family and multi-family housing where first cost sensitivity and installer availability shape material selection. Fiberglass batt dominates retrofits across the United States due to established distribution channels and familiar application protocols. EPA Energy Star certification requirements are elevating minimum R-value thresholds in new construction.
- Commercial Buildings:Office, retail, and hospitality structures where building energy codes mandate higher thermal performance and fire safety ratings. Urban high-rise developments in China specify mineral wool and spray foam assemblies to meet dual carbon efficiency targets and strict fire protocols. Whole-building energy modeling is shifting specification decisions from catalog browsing to parametric optimization.
- Industrial Facilities:Manufacturing and warehouse structures with specialized requirements for thermal stability and process protection.
- Agricultural Structures:Barns, greenhouses, and storage buildings where cost minimization often overrides performance optimization.
Residential channels absorb the greatest material volume. Commercial retrofits are expanding most quickly.
Thermal Resistance:
Code mandates and climate zone requirements stratify demand across R-value tiers.
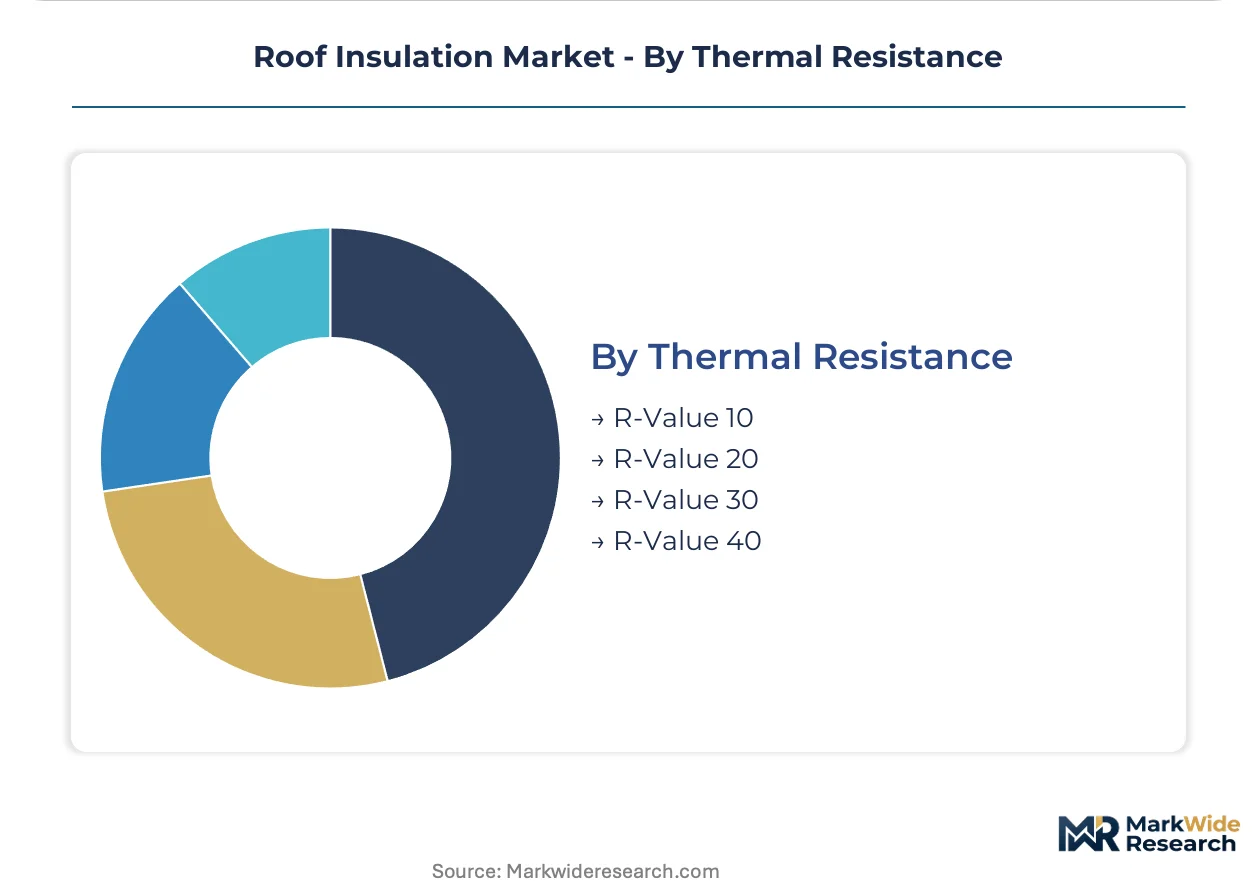
- R-Value 30:Mid-tier performance specification meeting current energy code baselines in moderate climate zones across the United States. Production homebuilders in Texas and Florida specify this tier to balance compliance cost with thermal performance. Building code evolution is pushing this category toward minimum acceptable rather than aspirational positioning.
- R-Value 40:High-performance tier addressing stringent energy codes in cold climate zones and net-zero building targets. Deep energy retrofits in Germany and the northern United States specify R-40 assemblies where heating degree days justify substantial insulation investment. Aerogel and vacuum panel technologies are compressing the thickness required to achieve this performance threshold.
- R-Value 10:Entry-level specification for mild climate zones and non-conditioned spaces.
- R-Value 20:Intermediate tier common in commercial roofing and mixed climate applications.
R-Value 30 represents the largest installed base. R-Value 40 is climbing the fastest as codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European mineral wool production capacity. Building energy codes in the United States and China are tightening procurement specifications. Data center construction clusters in Northern Virginia, Frankfurt, and Shanghai are pulling premium insulation volumes.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth is specifying stone wool and spray foam assemblies for fire resistance and thermal management. EPA Energy Star certification updates mandate whole-roof assembly testing rather than material-only R-value claims. California and New York metro areas are experiencing specification delays as design teams adapt to assembly-level compliance verification.
Germany
EU Green Deal building renovation targets are accelerating mineral wool specification in multi-family housing retrofits across Berlin and Hamburg. REACH chemical compliance through ECHA constrains formulation choices for spray foam contractors. The Rhine-Ruhr industrial cluster hosts integrated stone wool production networks serving Central European demand.
China
Dual carbon goals in Beijing and Shanghai are opening specification windows for imported mineral wool and rigid foam technologies. National building efficiency mandates through MEE tighten envelope performance requirements. Yangtze River Delta construction corridors are specifying higher R-value assemblies for commercial high-rise developments.
Denmark
Stone wool production clusters concentrate manufacturing capacity for European export markets. National building codes exceed EU baseline efficiency requirements. Copenhagen and Aarhus metro areas are piloting deep energy retrofit programs with R-40 assembly specifications.
France
Mandatory efficiency retrofits under EU Green Deal targets are pulling mineral wool volumes into Paris and Lyon multi-family housing stock. ANSM workplace exposure protocols constrain spray foam application contractor pools. The Île-de-France region is consolidating specification authority around lifecycle carbon disclosure metrics.
Roof Insulation Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to code-driven specification upgrades. The vendor base organizes around three tiers: integrated building materials conglomerates with captive mineral wool production, specialty chemical producers supplying polyurethane systems, and regional fabricators serving retrofit contractor channels. Two strategic archetypes predominate: scale-driven mineral wool producers leveraging vertical integration into raw material sourcing, and technology-focused spray foam specialists differentiating through certified installer networks. M&A activity and capacity expansion represent the dominant competitive moves as players position for EU Green Deal and China dual carbon procurement windows.
Among North American building materials conglomerates, Owens Corning and Johns Manville occupy positions anchored in fiberglass manufacturing scale. European specialists ROCKWOOL International and Saint-Gobain exemplify the mineral wool archetype with production networks concentrated in Denmark and France. Within the chemical systems tier, BASF represents the polyurethane feedstock supplier position serving spray foam formulators.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| ROCKWOOL International |
| Knauf Insulation |
| BASF |
| Kingspan Group |
| Johns Manville |
| Dow Inc. |
| Huntsman Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal building renovation targets gate qualified supply and premium-tier pricing access, as contractors meeting ECHA REACH compliance and EPD documentation standards command material premiums while uncertified fabricants face specification exclusion across German and French procurement channels.
Pricing Analysis
Distributor margins absorb 12-18 points on mineral wool and rigid board sales to regional contractor networks, compressing to 6-10 points for direct-to-OEM volumes serving hyperscale data center developers. Three-tier pricing structure across premium, standard, and economy levels separates fire-rated stone wool assemblies from commodity fiberglass batts from reclaimed-content economy grades. Cost compression in spray foam contractor tiers is intensifying because isocyanate and polyol feedstock volatility destabilizes project bidding. Single-family residential retrofits exhibit highest price sensitivity, while data center operators demonstrate lowest sensitivity given fire resistance and thermal performance imperatives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for stone wool and spray foam assemblies in Northern Virginia and Dallas-Fort Worth data center corridors. Manufacturing gravity centers on Denmark and Germany for mineral wool, the United States for fiberglass, and China for expanded polystyrene board production. Raw material flows draw from basalt and slag feedstocks for stone wool, isocyanate and polyol chemicals for polyurethane systems, and petrochemical derivatives for polystyrene. Single-source vulnerability concentrates in European stone wool production clusters exposed to energy cost shocks. Distribution runs through building materials wholesalers, specialty insulation distributors, and direct contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Energy Star certification updates and EU Green Deal enforcement timelines mechanically expand addressable demand for qualified suppliers.
For Market Incumbents: Anticipate REACH chemical compliance escalation forcing formulation recertification investments that smaller competitors cannot fund. Prioritize backward integration into basalt and slag raw material sourcing to defend mineral wool margin structure against energy cost volatility. Expand certified installer training capacity to capture spray foam share constrained by OSHA isocyanate handling protocol enforcement.
For New Entrants and Emerging Players: E-commerce specification platforms targeting independent roofing contractors offer lower customer acquisition friction than traditional distribution relationships. White-space concentrates in China's Yangtze River Delta commercial high-rise segment where imported mineral wool and rigid foam technologies face limited domestic competition. Pursue prefabricated roof panel integration partnerships with United States offsite construction channels to bypass established contractor network barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional insulation fabricants because EPD documentation requirements and REACH compliance costs disproportionately burden sub-scale operators without captive technical resources. Target stone wool and spray foam specialists with established certified installer networks and ECHA-compliant product portfolios. Watch EPA Energy Star whole-roof assembly testing mandate enforcement as inflection indicator accelerating specification consolidation toward integrated suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Stone wool production additions in Denmark and Germany serve EU Green Deal retrofit demand acceleration. |
| Backward Integration | Captive basalt and slag sourcing insulates ROCKWOOL and Saint-Gobain from energy cost volatility. |
| Green Manufacturing Transition | Low-global-warming-potential blowing agent conversion expands polyurethane spray foam commercial applicability. |
| Long-term Supply Agreement | Direct data center developer contracts bypass distributor margin layers for hyperscale projects. |
| Joint Venture | Prefabricated panel partnerships with United States offsite construction channels bundle insulation with structural assemblies. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary fieldwork encompassed interviews with commercial roofing contractors, building materials procurement managers, spray foam application technicians, EPC contractors specializing in data center construction, and regulatory compliance officers at insulation manufacturers. Secondary sources included EPA Energy Star certification databases, ECHA REACH substance restriction filings, EU Green Deal implementation progress reports, and customs trade data tracking mineral wool and polystyrene board flows. Bottom-up volume estimates from installation method segments were triangulated against top-down construction spending allocations.
Rate-of-change decomposition anchored the analytical framework, isolating volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include material chemistry, installation logistics, end-use building type, and thermal resistance tier. CAGRs were derived from regression analysis against building code stringency indices and retrofit target enforcement schedules. Industry-specific forecast inputs incorporated heating and cooling degree day projections, data center construction pipeline tracking, and REACH chemical restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for aerogel and vacuum insulation panel cost reduction would alter the outlook by compressing conventional material specification windows. Forecasts reflect base-case assumptions regarding regulatory enforcement intensity and construction labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Global Tunnel and Metro Ventilation Market