
 Global Ductless Heating and Cooling Systems Market | 2026-2036
Global Ductless Heating and Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ductless Heating and Cooling Systems Market Analysis
Modular multi-zone bundling is recalibrating how commercial buyers evaluate lifecycle costs against upfront capital outlay. Daikin Industries leverages its captive compressor manufacturing to control cost curves across VRF configurations. Mitsubishi Electric Corporation anchors its position through deep specialization in hyper-heating performance for cold-climate zones. LG Electronics competes by extending smart-home integration capabilities that reduce commissioning complexity for installers.
Ductless heating and cooling systems are refrigerant-based HVAC units that deliver conditioned air directly to individual zones without ductwork, typically operating through inverter-driven compressors with coefficient of performance ratings exceeding conventional central systems. These systems serve commercial and residential applications where duct installation proves structurally impractical or economically prohibitive. Mini-split configurations dominate installed base volumes across residential channels, while VRF systems command concentrated margin pools in commercial new construction. Smart control technology represents the fastest-expanding segment as building automation mandates tighten operational efficiency requirements. Electric power source systems sustain the broadest addressable market, though hybrid configurations are gaining specification share in markets with time-of-use electricity tariffs.
The US Department of Energy appliance efficiency standards and the EPA SNAP program governing refrigerant transitions collectively shape product roadmaps and compliance timelines for manufacturers accessing North American markets. Japan's METI enforces Top Runner standards that continuously ratchet minimum efficiency thresholds, forcing R&D investment cycles that ripple through global product portfolios. The EU F-Gas Regulation and CE marking requirements under the MDR framework constrain market access for systems employing high-global-warming-potential refrigerants. Stakeholders must monitor refrigerant chemistry transitions and efficiency standard convergence across jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
Refrigerant chemistry transitions under the Kigali Amendment are compressing product development cycles while forcing manufacturers to requalify entire portfolios across multiple efficiency regimes simultaneously.
Growth Catalysts
- Retrofit demand in aging urban housing:Residential buildings in Japan, South Korea, and the United States lack ductwork infrastructure, creating structural pull for mini-split installations where central systems prove structurally impractical.
- METI Top Runner standards:Japan's continuous efficiency ratcheting forces R&D investment cycles that ripple through global product portfolios, accelerating performance improvements in inverter-driven compressor technology.
- Smart control integration:Building automation mandates are tightening operational efficiency requirements, expanding specification pull for connected thermostat and zone-control configurations in commercial new construction.
Market Restraints
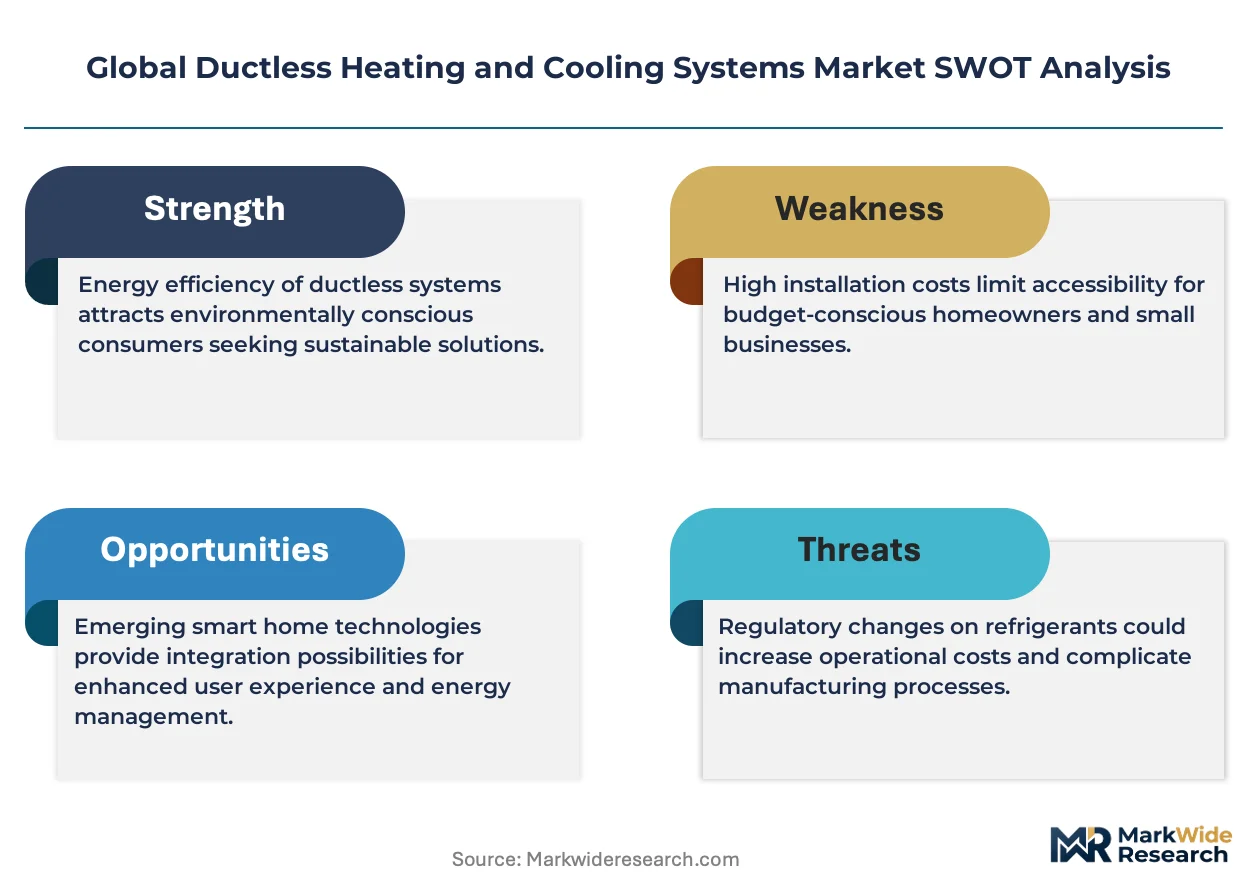
- Refrigerant input cost volatility:Transition to lower-global-warming-potential chemistries under EPA SNAP and EU F-Gas Regulation is compressing margins while suppliers scale alternative production.
- Supply concentration in compressor manufacturing:Captive production capabilities at Japanese and South Korean integrated manufacturers create sourcing bottlenecks for independent system assemblers.
- Technical limitation in extreme cold-climate performance:Coefficient of performance degradation below minus fifteen degrees Celsius constrains addressable market penetration in Nordic and northern-tier US applications without hyper-heating variants.
Strategic Opportunities
- Underpenetrated Indian residential market:Rising middle-class housing stock and BIS efficiency mandates create specification windows for inverter-driven mini-splits as primary cooling infrastructure.
- Hybrid electric-thermal configurations:Time-of-use electricity tariffs in Germany and California are creating demand for dual-source systems that arbitrage thermal storage against peak pricing.
- VRF convergence with building energy management:Integration with BACnet and Modbus protocols is opening specification channels in LEED-certified commercial construction across Singapore and Australia.
Industry Challenges
- Refrigerant handling certification gaps:EPA Section 608 technician requirements and equivalent EU F-Gas personnel certification are constraining installer availability, extending commissioning timelines.
- Legacy system integration complexity:Retrofit projects require structural assessment of electrical capacity and mounting infrastructure, fragmenting project economics and extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ductless Heating and Cooling Systems Market |
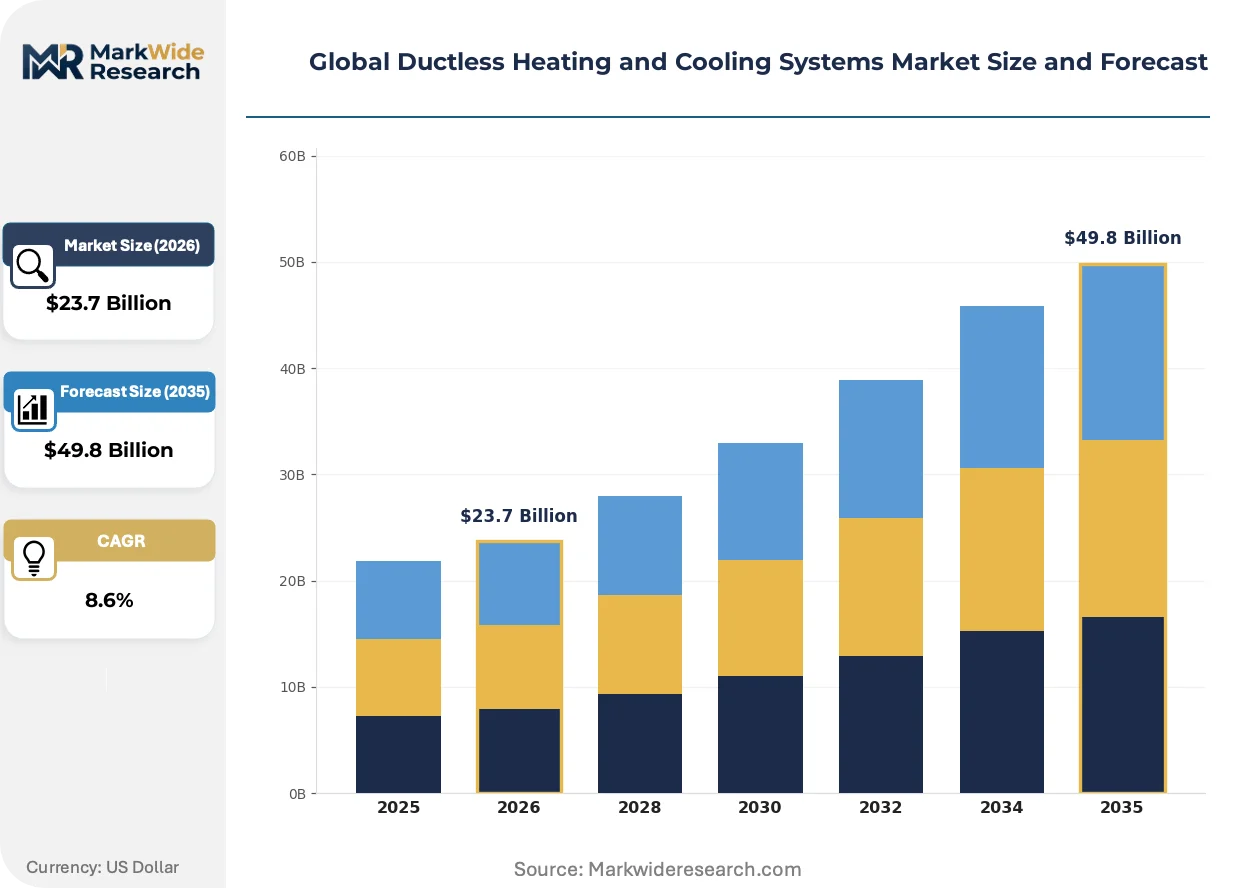
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini-Split, Multi-Split, VRF, Window Units Installation Type: Residential, Commercial, Industrial, Portable Control Technology: Manual, Remote, Smart, Programmable Power Source: Electric, Solar, Hybrid, Gas |
| Companies Covered | Daikin Industries, Mitsubishi Electric Corporation, LG Electronics, Carrier Global Corporation, Panasonic Corporation, Fujitsu General, Samsung Electronics, Trane Technologies, Gree Electric Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ductless Heating and Cooling Systems Market Emerging Trajectories
Product roadmaps are converging on refrigerant transitions, connected controls, and cold-climate performance boundaries as manufacturers navigate divergent regulatory timelines across North America, Europe, and Asia-Pacific.
R32 refrigerant is electrifying product portfolios as a lower-global-warming-potential alternative to R410A. Commercial buyers in the United States and Japan are specifying R32-compatible systems to preempt EPA SNAP phase-down deadlines. This chemistry transition is compressing inventory carrying costs for distributors managing dual-refrigerant pipelines.
EU F-Gas Regulation is tightening quota allocations for hydrofluorocarbons, forcing importers to secure pre-registration for CE-marked equipment. European system manufacturers are accelerating R290 propane development for split systems under five kilowatts. Cold-climate VRF specifications in Germany and Poland are shifting toward CO2-based heat pumps for commercial applications above fifty kilowatts.
After-sales service unbundling is disrupting traditional distribution economics in the United States. Independent commissioning agents are capturing margin pools previously retained by manufacturer-authorized dealers. This channel fragmentation is most visible in California and Texas multi-family residential retrofits, where property management firms directly procure equipment and separately contract installation through bid platforms.
Global Ductless Heating and Cooling Systems Market Segmentation
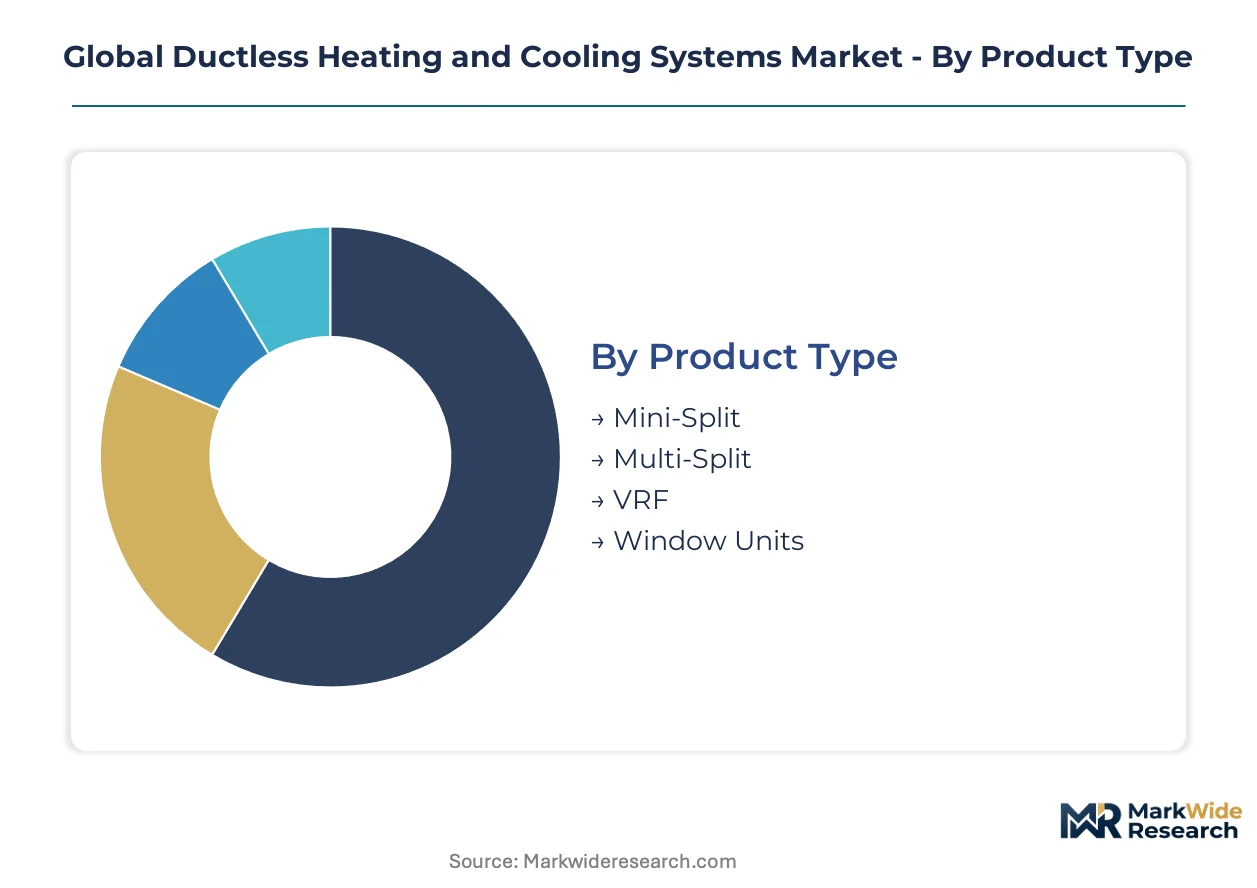
Segmentation in the ductless systems market determines which regulatory frameworks apply to specific product configurations. Certification requirements diverge sharply across refrigerant types, voltage classes, and connectivity tiers, creating distinct compliance pathways for manufacturers.
Product Type:
Mini-Split systems require EPA Section 608 technician certification for refrigerant handling in the United States, while VRF configurations trigger additional CE marking complexity under EU F-Gas Regulation quota allocations.
- Mini-Split:Single-zone inverter-driven units with wall-mounted indoor evaporators and outdoor condensing units connected by refrigerant lines. Residential retrofits in Japan and South Korea drive specification volumes where aging apartment stock lacks ductwork infrastructure. Leading the category by volume: Mini-Split. Growing fastest: VRF.
- Multi-Split:Configurations connecting multiple indoor units to a single outdoor compressor, reducing exterior equipment footprint in dense urban installations.
- VRF:Variable refrigerant flow systems modulate compressor speed to match zone-level load variations, commanding premium specification in Singapore commercial towers and Australian LEED-certified construction.
- Window Units:Self-contained through-wall systems with integrated compressors, serving rental housing and temporary cooling applications where permanent installation is restricted.
Margin concentration follows installation complexity, with VRF systems capturing disproportionate value pools despite lower unit volumes.
Installation Type:
Commercial deployments face stricter electrical inspection protocols than residential channels, particularly in Germany where VdS certification governs fire safety integration.
- Residential:Single-family and multi-family housing applications where structural constraints prohibit ductwork retrofit. METI Top Runner standards in Japan force continuous efficiency upgrades in this channel.
- Commercial:Office buildings, retail spaces, and hospitality installations specifying BACnet-connected zone control. Demand concentrates in Singapore and Australia where building automation mandates tighten operational requirements.
- Industrial:Process cooling and supplemental climate control in manufacturing facilities, requiring heavy-duty electrical infrastructure and specialized mounting.
- Portable:Mobile units with temporary installation flexibility, serving construction sites and event venues where permanent systems are impractical.
Residential channels dominate unit shipments. Commercial installations generate the highest revenue per project.
Control Technology:
Smart control configurations trigger additional cybersecurity compliance in South Korea under KISA certification requirements for networked building systems.
- Manual:Basic dial or button interfaces without remote capability, specified primarily in cost-sensitive replacement markets.
- Remote:Infrared or radio-frequency handheld controllers enabling basic temperature and mode adjustment from distance.
- Smart:Wi-Fi and Bluetooth-enabled systems with smartphone integration, voice assistant compatibility, and energy monitoring dashboards. Fastest-expanding segment as California Title 24 building codes mandate connected thermostat capability in new construction.
- Programmable:Schedule-based temperature setback controls reducing runtime during unoccupied periods, specified in German and Polish markets with time-of-use electricity tariffs.
Smart controls are displacing programmable units in premium residential specifications across Japan and the United States.
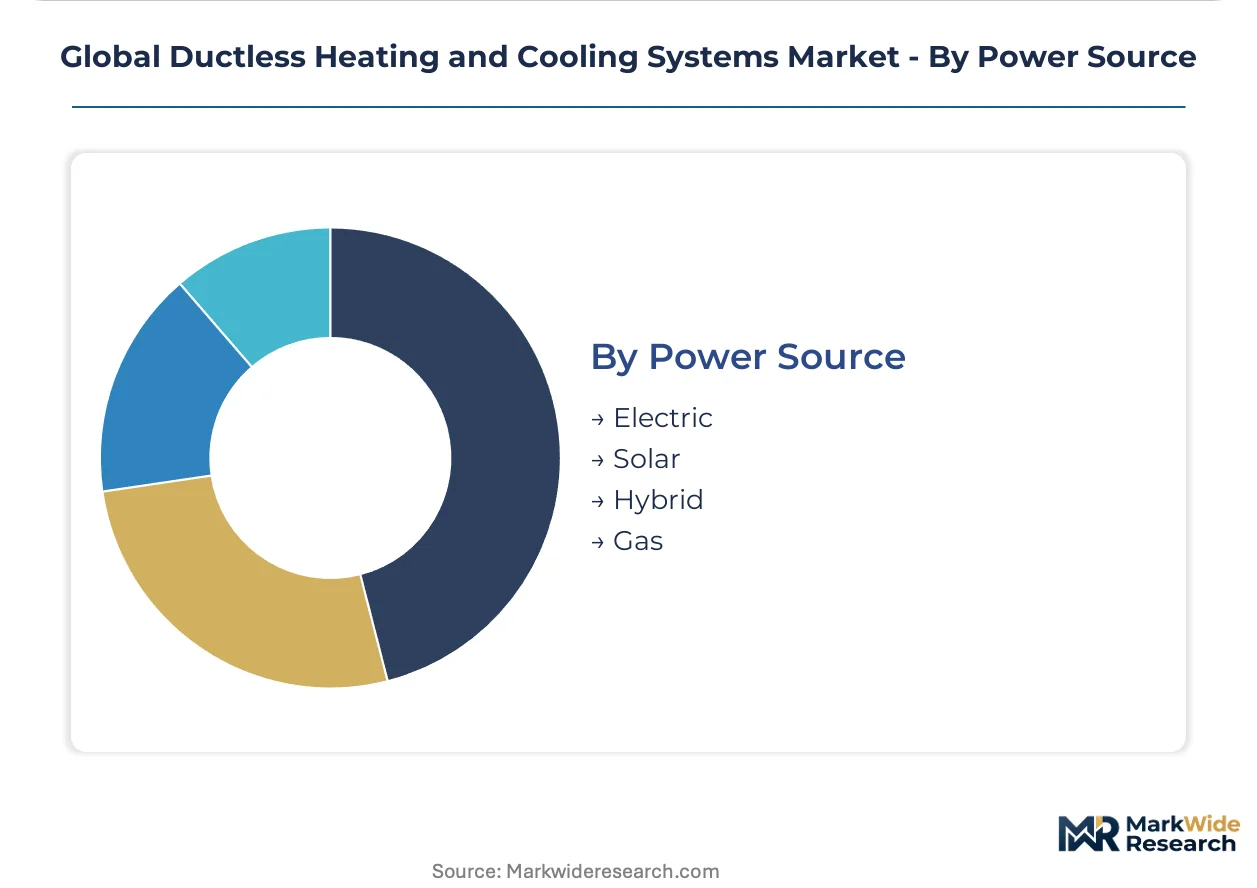
Power Source:
Hybrid configurations face dual certification requirements under both electrical safety standards and gas appliance regulations in jurisdictions with mixed-fuel deployment.
- Electric:Grid-powered inverter-driven compressors serving the broadest addressable market, constrained only by available panel capacity and local utility rates.
- Solar:DC-coupled units operating directly from photovoltaic arrays or battery storage, gaining specification in Australian off-grid residential construction and California net-zero mandates.
- Hybrid:Dual-source systems combining electric heat pump operation with gas-fired backup, optimizing operating costs under time-of-use tariffs in Germany and Texas.
- Gas:Absorption cooling and direct-fired heating configurations for commercial applications where gas infrastructure exceeds electrical service capacity.
Electric systems anchor volume. Hybrid configurations are climbing fastest in markets with volatile electricity pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Top Runner zones concentrate manufacturing excellence in inverter compressor technology, driving efficiency benchmarks that cascade through global product portfolios.
Japan
Residential retrofit demand in aging Tokyo and Osaka apartment stock sustains mini-split volumes where ductwork installation remains structurally prohibitive. METI's Top Runner program mandates continuous efficiency ratcheting that forces R&D investment cycles. Nagoya industrial corridors host captive compressor manufacturing operations that control cost curves across VRF configurations.
United States
Multi-family housing retrofits in California and Texas drive specification pull for smart-connected systems under Title 24 building codes. EPA SNAP program deadlines and Section 608 technician certification requirements constrain installer availability. Southeast metropolitan clusters see rising adoption of hyper-heating variants as cold-climate performance boundaries expand.
Germany
Time-of-use electricity tariffs in Bavaria and North Rhine-Westphalia create demand for hybrid electric-thermal configurations that arbitrage thermal storage against peak pricing. EU F-Gas Regulation quota allocations force R290 propane development for sub-five-kilowatt split systems. Berlin commercial construction specifies BACnet-integrated VRF for LEED-certified towers.
India
Rising middle-class housing stock in Maharashtra and Gujarat creates specification windows for inverter-driven mini-splits as primary cooling infrastructure. BIS efficiency mandates compress product development cycles for manufacturers entering this underpenetrated residential channel. Tamil Nadu industrial zones attract assembly operations serving domestic demand and export markets.
Australia
Net-zero mandates in New South Wales and Victoria accelerate specification of DC-coupled solar-powered units operating directly from photovoltaic arrays. Building automation requirements in Sydney and Melbourne commercial towers tighten operational efficiency standards. Queensland off-grid residential construction sustains demand for battery-integrated climate systems.
Global Ductless Heating and Cooling Systems Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a consolidated structure where captive manufacturing capabilities determine margin capture. Japanese and South Korean integrated manufacturers control compressor supply chains, generating sourcing bottlenecks for independent assemblers. Three archetypes dominate: vertically integrated conglomerates with captive component production, specialist HVAC pure-plays with deep cold-climate expertise, and diversified electronics groups leveraging smart-home ecosystems. Competitive moves center on refrigerant chemistry transitions and connected control platform development.
Within the integrated conglomerate tier, Daikin Industries and Mitsubishi Electric Corporation exemplify manufacturers controlling upstream compressor production. LG Electronics occupies a position representing diversified electronics groups extending smart-home integration capabilities. These three anchors demonstrate how geographic concentration in Japanese and South Korean industrial bases shapes competitive positioning through captive supply advantages and regulatory compliance velocity across multiple jurisdictions.
| Leading Market Players |
|---|
| Daikin Industries |
| Mitsubishi Electric Corporation |
| LG Electronics |
| Carrier Global Corporation |
| Panasonic Corporation |
| Fujitsu General |
| Samsung Electronics |
| Trane Technologies |
| Gree Electric Appliances |
| Others |
Supply Flow & Price Mechanics
Commercial property management firms in California and Texas multi-family retrofits increasingly procure equipment directly through bid platforms, compressing traditional dealer margins and forcing manufacturers toward transparent project-based pricing models that unbundle after-sales service.
Pricing Analysis
Short lead-time premiums dominate commercial VRF transactions in Singapore and Australia, where LEED-certified construction deadlines compress procurement windows and contractors pay markup to secure inventory. Three-tier pricing structure across premium hyper-heating, standard inverter, and economy fixed-speed levels separates cold-climate performance tiers. Cost compression in R32-compatible portfolios is intensifying because refrigerant transition timelines compress inventory carrying costs for distributors managing dual-chemistry pipelines. Residential retrofit channels in Japan exhibit highest price sensitivity, while commercial new construction in Germany shows lowest sensitivity due to lifecycle cost evaluation frameworks.
Supply Chain Analysis
Inverter compressor supply rests on captive manufacturing operations concentrated in Japan, South Korea, and China, where integrated conglomerates control cost curves across VRF configurations. Copper refrigerant tubing, electronic expansion valves, and rare-earth magnet materials for high-efficiency motors constitute critical input dependencies. Single-source vulnerability in Japanese compressor technology creates procurement bottlenecks for independent system assemblers lacking backward integration. Distribution runs through manufacturer-authorized dealer networks in developed markets, while direct procurement platforms fragment channel economics in United States multi-family residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive compressor manufacturing capacity constrains supply elasticity, propping pricing power for integrated producers while independent assemblers face margin compression from sourcing bottlenecks.
For Market Incumbents: Cement control over refrigerant chemistry transitions by accelerating R290 and CO2 development ahead of EU F-Gas quota tightening, while securing EPA Section 608 certification pipelines to constrain installer availability for emerging competitors. Deepen captive production of hyper-heating compressor variants to defend against cold-climate pure-play specialists. For New Entrants and Emerging Players: Capture specification windows in India's underpenetrated residential market by aligning inverter-driven mini-split portfolios with BIS efficiency mandates and establishing assembly partnerships in Tamil Nadu industrial zones. Lead with solar-DC-coupled configurations targeting Australian off-grid construction and California net-zero mandates. For Investors and Strategic Acquirers: The window for entry favors pure-play cold-climate specialists with deep hyper-heating IP and established METI Top Runner compliance velocity. Monitor refrigerant handling certification gap resolution as inflection indicator for installer capacity expansion and market penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | R32 and R290 development secures EPA SNAP and EU F-Gas compliance ahead of quota deadlines. |
| Cold-Climate Performance Expansion | Hyper-heating variants below minus fifteen degrees Celsius unlock Nordic and northern-tier US specifications. |
| Smart Control Platform Integration | BACnet and Modbus compatibility penetrates LEED-certified commercial construction in Singapore and Australia. |
| Backward Integration into Compressors | Captive inverter manufacturing controls cost curves and insulates against Japanese supply concentration. |
| Direct Procurement Channel Development | Bid platform partnerships capture margin pools from fragmented US multi-family residential retrofits. |
Methodological Framework
Multi-period observation of METI efficiency standard ratcheting, EPA SNAP refrigerant phase-down timelines, and BIS mandate implementation anchored the trend analysis, supplemented by interviews with HVAC manufacturer product managers, commercial contractor procurement leads, refrigerant handling certification trainers, and building automation systems integrators. Secondary validation drew from EPA Section 608 technician registration databases, EU F-Gas Regulation quota allocation records, METI Top Runner product listings, and customs trade data for compressor and heat exchanger imports. Bottom-up shipment modeling triangulated against top-down construction spending and housing stock retrofit penetration estimates.
Segment-weighting applied product type, installation channel, control technology tier, and power source configurations across the modeling period, with regional regulatory cluster overlays for Japan, United States, Germany, India, and Australia. CAGRs derived from fitted growth curves applied to base-year market sizing, incorporating inverter adoption rates, refrigerant transition velocity, and smart control penetration assumptions specific to each jurisdiction's building code evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant chemistry transition delays, compressor supply concentration shifts, and technician certification pipeline expansion. Assumptions reflect documented regulatory timelines and manufacturer product roadmap disclosures. A small set of named triggers warrants ongoing watch: EPA SNAP enforcement acceleration, EU F-Gas quota allocation tightening, and METI Top Runner standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Europe Boiler System Market