
 Residential Hydronic Underfloor Heating Market | 2026-2036
Residential Hydronic Underfloor Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Hydronic Underfloor Heating Market Insights
Modular manifold kits paired with pre-insulated pipe bundles is pivoting contractor procurement toward bundled system packages rather than component-level sourcing. Uponor Corporation leverages its polymer extrusion expertise to sustain captive supply of cross-linked polyethylene tubing across European project channels. REHAU Group anchors its position through backward integration into synthetic rubber compounding for flexible connector lines. Warmup Plc differentiates via digital thermostat integration that extends its control hardware into specification-driven renovation segments.
Residential hydronic underfloor heating circulates warmed water through embedded pipe networks typically operating at 35–55°C flow temperature, distributing thermal energy across floor slabs to eliminate convective drafts and reduce stratification losses in living zones. Manifold systems and pipe tubing together constitute the core hardware envelope where material specification determines installation labor and long-term reliability. Heat pump technology within the boiler category is capturing specification share as flow-temperature optimization aligns with air-source and ground-source equipment. Single-family homes dominate application volumes, though passive house construction imposes tighter hydronic design constraints that concentrate margin pools in engineering-intensive project tiers.
The EU Green Deal and F-Gas Regulation are reshaping boiler replacement timelines across member states, while Ecodesign requirements under the CE marking framework mandate minimum efficiency thresholds for circulating pumps and control equipment. National building codes in Denmark and Sweden enforce low-temperature heating compatibility that directly favors hydronic underfloor distribution over conventional radiator systems. Stakeholders must monitor heat pump capacity factors and local installer certification density when prioritizing regional deployment sequences.
Market Dynamics
Heat pump flow-temperature optimization is compressing the traditional boiler-replacement pipeline across European residential construction, forcing manifold and pipe manufacturers to redesign for 35–45°C operating envelopes.
Growth Catalysts
- EU Green Deal boiler mandates:Member-state heat pump compatibility requirements redirect replacement flows toward low-temperature distribution systems.
- Nordic district heating integration:Denmark and Sweden enforce low-temperature heating compatibility in national building codes, standardizing underfloor loops.
- German new-build acceleration:Wet-screed system specification concentrates in single-family residential permits across Bavaria and Baden-Württemberg.
Market Restraints
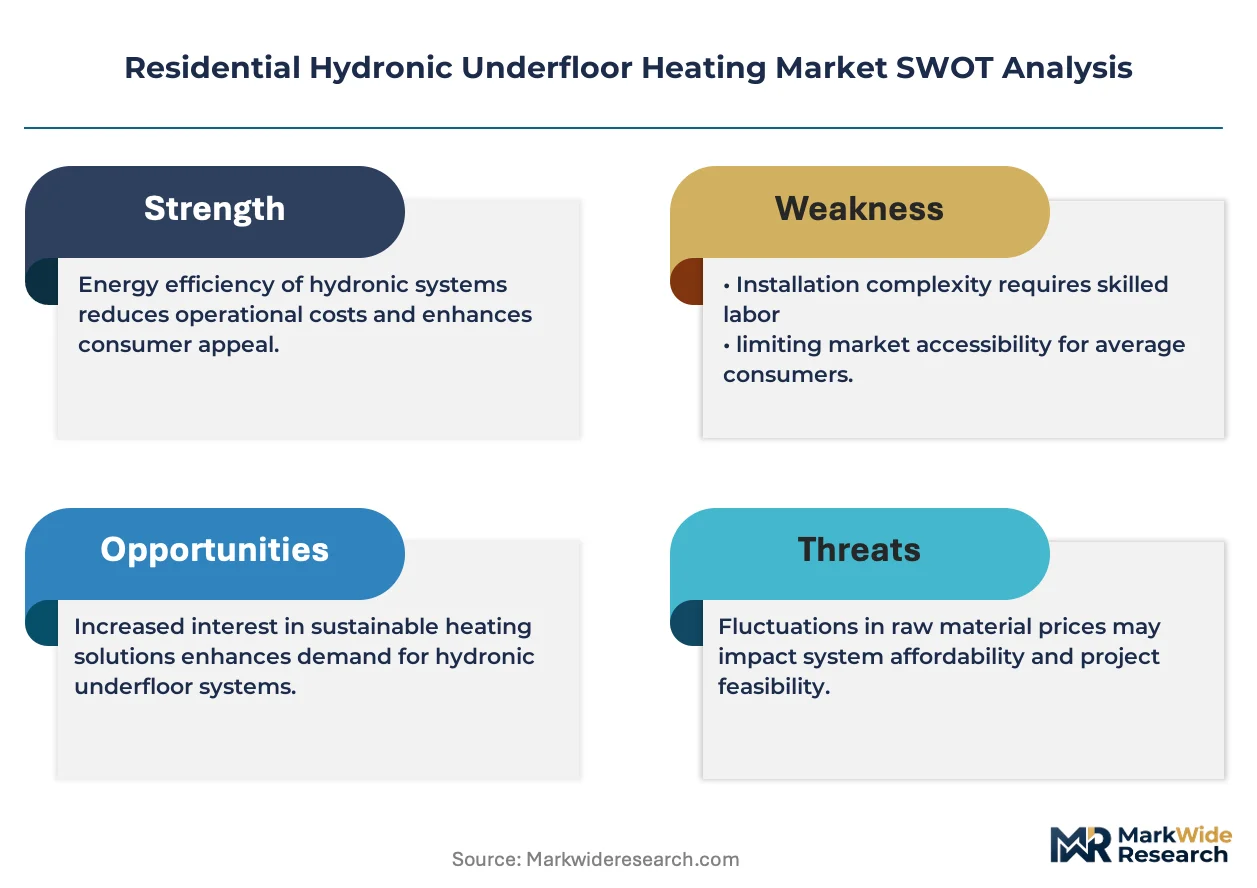
- Copper and polymer input volatility:Cross-linked polyethylene resin prices fluctuate with ethylene feedstock costs, squeezing tubing margins.
- Installer certification scarcity:F-Gas-qualified technicians concentrate in Germany and France, leaving Poland and Romania underserved.
- Radiator retrofit substitution:Panel radiator upgrades require lower capital outlay in Eastern European renovation segments.
Strategic Opportunities
- Passive house construction tier:Engineering-intensive projects in Austria and Switzerland command specification premiums for integrated controls.
- Digital thermostat convergence:Smart-home integration partnerships open renovation channels beyond new-build specification.
- CE marking Ecodesign pumps:Efficiency thresholds for circulating equipment create upgrade cycles in existing installations.
Industry Challenges
- Wet-screed installation skill gaps:Screed pouring and pipe-laying coordination requires cross-trade certification density that lags demand.
- Legacy boiler integration complexity:Hybrid systems combining heat pumps with retained gas boilers demand control architecture redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Hydronic Underfloor Heating Market |
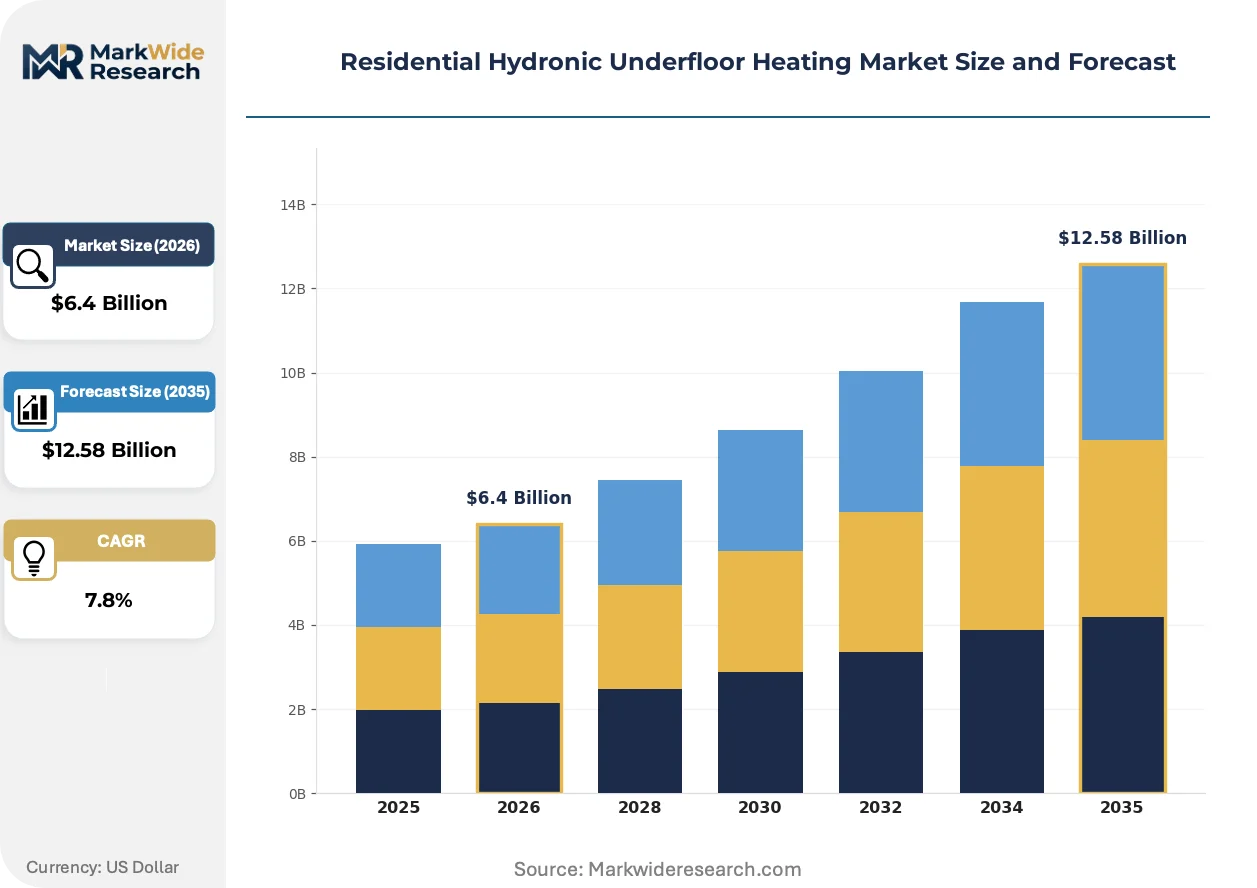
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manifold Systems, Pipe Tubing, Control Valves, Heat Pumps, Pumps, Insulation Boards Technology: Electric Boilers, Gas Boilers, Solar Thermal, Condensing Boilers, Biomass Boilers, Radiant Panels Application: Single-Family Homes, Multi-Family Dwellings, Luxury Villas, Low-Rise Buildings, Passive Houses End User: Homeowners, Property Managers, Real Estate Developers, Installation Contractors |
| Companies Covered | Warmup Plc, Mitsubishi Electric Corporation, Uponor Corporation, nVent Electric plc, Robert Bosch GmbH, REHAU Group, Honeywell International Inc., Watts Water Technologies Inc., Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Hydronic Underfloor Heating Market Trends and Innovations
Product bundling and pre-assembly are compressing project timelines while regulatory chemistry restrictions reshape material specifications across the supply base.
Pre-insulated pipe bundles paired with modular manifold kits is overtaking component-level sourcing in contractor procurement. Mid-sized installation firms across the Netherlands and Belgium now specify complete system packages rather than sourcing tubing, insulation, and manifolds separately. This shift compresses on-site labor hours and reduces field-assembly error rates.
The F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in heat pump equipment, accelerating R-32 and propane adoption in air-source units. This chemistry transition tightens compatibility requirements for underfloor distribution systems operating at reduced flow temperatures. German and French HVAC distributors report specification delays as installers await certified heat pump-underfloor pairings.
Builder procurement teams increasingly demand digital commissioning documentation with embedded warranty registration. This documentation requirement shifts specification influence from wholesale distributors toward manufacturers with integrated control platforms. The trend concentrates in UK and Irish renovation segments where retrofit certification affects property valuation.
Residential Hydronic Underfloor Heating Market Segmentation
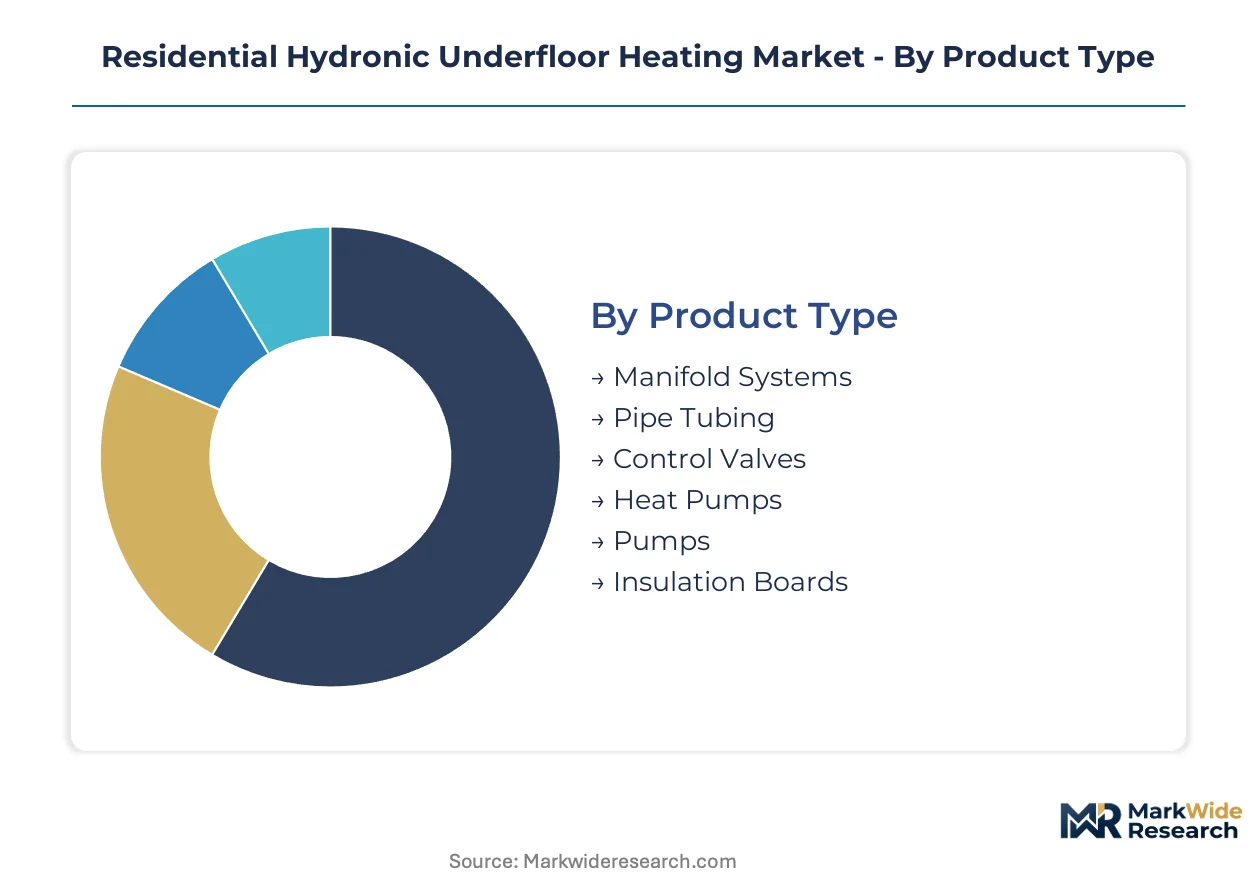
Segmentation in the Residential Hydronic Underfloor Heating Market reveals distinct procurement patterns across hardware categories and specification tiers. Material selection and heat source compatibility determine project economics and regulatory compliance trajectories.
Product Type:
Volume concentrates in commodity pipe and manifold hardware, while premium margins pool in integrated control systems and heat pump pairings.
- Manifold Systems:Brass or stainless steel distribution headers regulate flow across multiple heating zones. German and Austrian new-build specifications favor pre-assembled modular kits with integrated flow meters to reduce commissioning time.
- Pipe Tubing:Cross-linked polyethylene and PEX-AL-PEX composite tubing form the embedded distribution network. Nordic district heating integration drives demand for oxygen-barrier grades in Denmark and Sweden where corrosion protection is mandatory.
- Control Valves:Thermostatic and motorized zone valves manage individual room temperatures. Smart-home integration partnerships are expanding specification in UK renovation channels.
- Heat Pumps:Air-source and ground-source equipment supplies low-temperature flow compatible with underfloor loops. EU Green Deal mandates are accelerating replacement of legacy gas boilers in Germany and France.
- Pumps:High-efficiency circulating pumps move heated water through distribution networks. CE marking Ecodesign requirements mandate minimum efficiency thresholds across European member states.
- Insulation Boards:Extruded polystyrene and composite boards reduce downward heat loss in screed installations. Wet-screed system specification in Bavaria and Baden-Württemberg concentrates demand for high-compression grades.
Mature deployment sits with Pipe Tubing and Manifold Systems. Newer deployment is concentrated in Heat Pumps and smart-integrated Control Valves.
Technology:
Heat source selection follows regulatory chemistry restrictions and building code efficiency mandates across national jurisdictions.
- Electric Boilers:Resistance heating elements provide flow temperatures suited to underfloor distribution. Rural properties in France and Spain specify electric units where grid connectivity exceeds gas infrastructure density.
- Gas Boilers:Condensing and standard efficiency natural gas units retain installed base in Eastern European renovation segments. Polish and Romanian replacement cycles lag Western European heat pump transition timelines.
- Solar Thermal:Roof-mounted collectors supplement underfloor heating during shoulder seasons. Austrian and Swiss alpine installations pair solar thermal with biomass backup for year-round coverage.
- Condensing Boilers:High-efficiency gas units recover latent heat from flue gases. German building codes still permit condensing gas in hybrid configurations with heat pumps.
- Biomass Boilers:Wood pellet and chip combustion systems serve rural properties with fuel supply access. Forested regions of Austria and Finland maintain specification density for off-grid installations.
- Radiant Panels:Ceiling and wall-mounted radiant surfaces complement or substitute floor-based distribution. Retrofit applications in multi-family dwellings use panels where floor construction prohibits embedded tubing.
Condensing Boilers and Gas Boilers dominate existing installation stock. Solar Thermal and Biomass Boilers are climbing the fastest in passive house and off-grid construction tiers.
Application:
Construction type determines screed system compatibility and control complexity requirements.
- Single-Family Homes:Detached residential properties permit wet-screed installation during ground-up construction. German permit acceleration across Bavaria and Baden-Württemberg concentrates volume in this segment.
- Multi-Family Dwellings:Apartment buildings require centralized manifold rooms and vertical distribution risers. Danish building codes mandate low-temperature heating compatibility in new multi-family stock.
- Luxury Villas:High-specification residences demand zoned control and premium material finishes. Swiss and Austrian alpine markets command engineering premiums for integrated smart-home systems.
- Low-Rise Buildings:Two-to-four story residential structures balance screed load constraints with distribution efficiency. Belgian and Dutch mid-density construction favors dry-system alternatives to reduce structural weight.
- Passive Houses:Ultra-low-energy buildings impose tight hydronic design constraints and precise load matching. Certification requirements in Germany and Austria concentrate margin pools in engineering-intensive project tiers.
Single-Family Homes anchor current installation volumes. Passive Houses are gaining share fastest as efficiency standards tighten across Central European building codes.
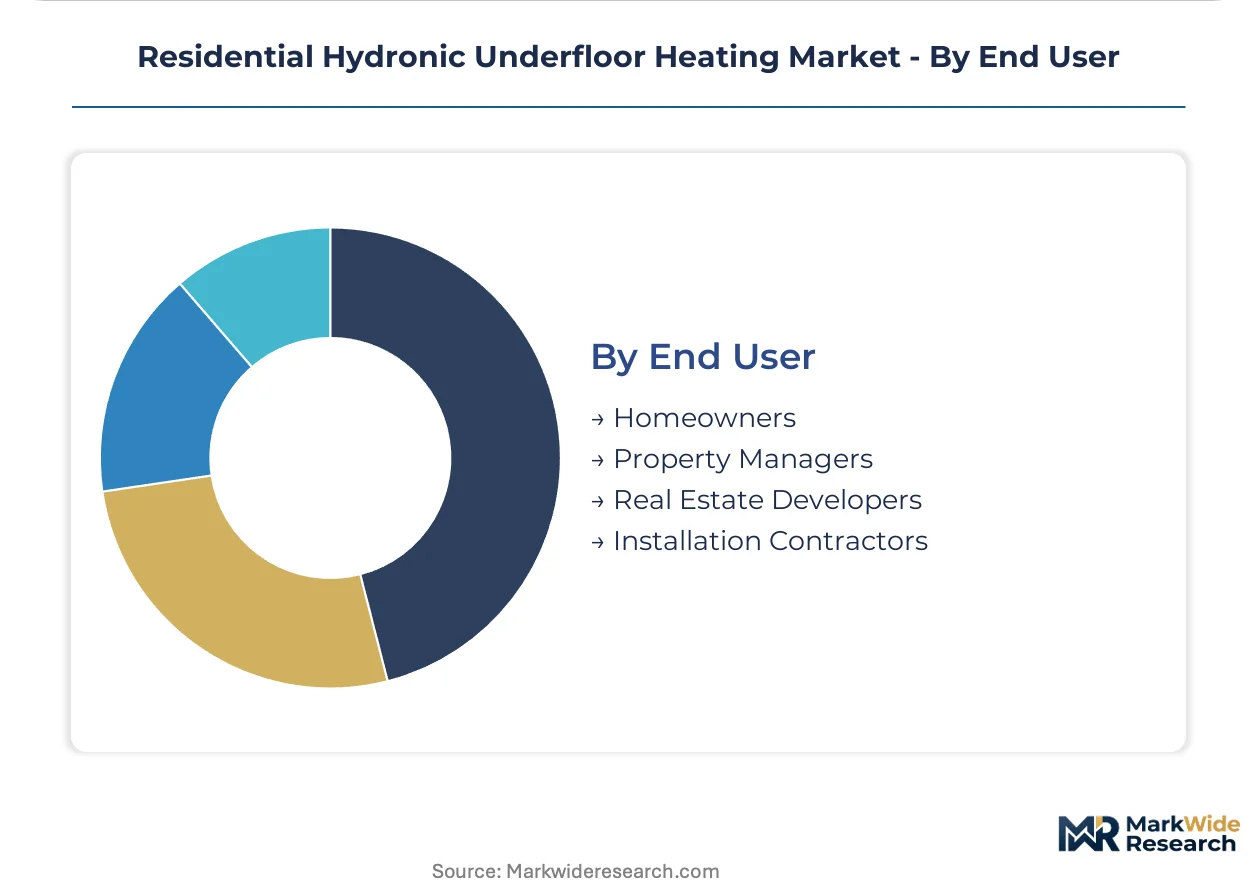
End User:
Procurement authority shifts between specification influencers and purchasing decision-makers across project types.
- Homeowners:Individual property owners drive renovation decisions and system upgrades. UK and Irish retrofit certification requirements are shifting influence toward manufacturers with digital commissioning platforms.
- Property Managers:Multi-family building operators prioritize lifecycle cost and maintenance accessibility. Scandinavian housing associations standardize on district heating-compatible underfloor loops.
- Real Estate Developers:Volume builders specify bundled system packages to compress construction timelines. German developer procurement teams increasingly demand pre-insulated pipe bundles with warranty documentation.
- Installation Contractors:Trade professionals influence material selection through distributor relationships. F-Gas-qualified technician scarcity in Poland and Romania constrains heat pump specification in those markets.
Real Estate Developers concentrate new-build specification volume. Homeowners represent the steepest expansion trajectory as renovation incentives expand across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of cross-linked polyethylene tubing concentrates in Germany and Austria, while specification demand clusters in Nordic and German residential construction. Consumption patterns diverge sharply between new-build markets with wet-screed compatibility and renovation segments favoring dry-system alternatives.
Germany
Bavaria and Baden-Württemberg drive wet-screed specification in single-family permits. The EU Green Deal mandates heat pump compatibility in boiler replacements, redirecting distribution system selection toward low-temperature loops. Installer certification density in Stuttgart and Munich supports faster project commissioning than eastern states.
Denmark
National building codes enforce low-temperature heating compatibility in multi-family new builds. District heating integration with underfloor loops represents standard practice across Copenhagen and Aarhus housing associations. The country's energy agency subsidizes heat pump pairing with hydronic distribution in renovation segments.
Sweden
Stockholm and Gothenburg concentrate passive house construction requiring tight hydronic design constraints. Nordic district heating networks supply flow temperatures optimized for embedded pipe distribution. Swedish building regulations mandate corrosion-resistant oxygen-barrier tubing in all district heating connections.
United Kingdom
Retrofit certification requirements in England and Wales shift specification influence toward manufacturers with digital commissioning platforms. London and Southeast renovation channels prioritize smart-thermostat integration for property valuation uplift. The country's F-Gas transition timeline lags Continental Europe, delaying heat pump-underfloor pairing specification.
France
Rural properties in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur specify electric boilers where gas infrastructure remains sparse. French HVAC distributors report specification delays as installers await certified heat pump-underfloor pairings. The national low-carbon renovation scheme directs subsidies toward heat pump-compatible distribution systems.
Residential Hydronic Underfloor Heating Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across manifold, pipe, and control hardware tiers. The vendor base organizes into three strategic archetypes: polymer extrusion specialists with captive tubing supply, diversified HVAC conglomerates with heat pump integration capabilities, and control-focused players with digital platform differentiation. Dominant competitive moves include backward integration into synthetic rubber compounding and partnerships with smart-home ecosystem providers.
Among Nordic polymer specialists, Uponor Corporation and REHAU Group occupy positions anchored by extrusion expertise and compounding integration respectively. Warmup Plc exemplifies the control-centric archetype through thermostat hardware extension into specification-driven renovation channels. These three entities represent distinct vectors of competitive positioning: captive material supply, backward integration into connector manufacturing, and digital commissioning platform development.
| Leading Market Players |
|---|
| Warmup Plc |
| Mitsubishi Electric Corporation |
| Uponor Corporation |
| nVent Electric plc |
| Robert Bosch GmbH |
| REHAU Group |
| Honeywell International Inc. |
| Watts Water Technologies Inc. |
| Danfoss A/S |
| Others |
Pricing and Supply Chain Analysis
Captive polymer extrusion in Germany and Austria anchors both supply security and pricing power for cross-linked polyethylene tubing manufacturers serving project channels. This backward integration into resin compounding and pipe production insulates major suppliers from ethylene feedstock volatility while compressing margins for component-level distributors lacking comparable upstream control.
Pricing Analysis
Margin tightening in standard-grade pipe tubing reflects ethylene derivative cost pass-through limitations and contractor bundling demands. Project-based pricing dominates, with three-tier differentiation across CE-marked premium systems, standard wet-screed packages, and economy dry-system alternatives. Price differentiation hinges on oxygen-barrier certification grade and F-Gas heat pump pairing documentation. Cost-down pressure accelerates as German developers consolidate procurement around pre-insulated bundles. Installation contractors exhibit highest price sensitivity, while passive house developers prioritize engineering premiums over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Copenhagen, and Manchester orchestrate hub-and-spoke delivery patterns for manifold kits and pipe bundles. Manufacturing concentrates in Germany, Austria, and Finland. Raw material dependencies include ethylene-based polyethylene resin, brass alloys for distribution headers, and synthetic rubber compounds for flexible connectors. Supply chain risk centers on single-source vulnerability for specialized oxygen-barrier resin grades. Distribution runs through HVAC wholesale channels with direct-to-contractor specification increasingly common for bundled system packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal mandates and F-Gas qualification requirements force out undercapitalized component distributors lacking heat pump pairing capabilities.
For Market Incumbents: Acquire F-Gas-certified installation networks to secure specification influence in heat pump transition markets. Defensive moves require captive supply of oxygen-barrier tubing grades and digital commissioning platform deployment. The threat of radiator retrofit substitution in Eastern Europe demands channel control through pre-insulated bundle pricing. Capacity addition in Poland and Romania addresses installer certification scarcity. For New Entrants and Emerging Players: EU Green Deal boiler mandates in Germany and France open a window for low-temperature distribution system specialists. White-space targets include smart-thermostat integration for UK renovation channels and dry-system alternatives for Belgian mid-density construction. The most penetrable segment is multi-family district heating integration in Denmark. Go-to-market positioning should emphasize heat pump-underfloor pairing certification documentation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified HVAC conglomerates seeking heat pump integration capabilities. Long-term viability favors manufacturers with backward integration into polymer compounding and established CE marking infrastructure. Acquisition target archetype: control-focused players with digital platform differentiation. The signal to watch is F-Gas technician certification density by national market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply secures margin stability against ethylene feedstock volatility. |
| Digital Commissioning Platform Deployment | Embedded warranty registration shifts specification influence from distributors to manufacturers. |
| Heat Pump Pairing Certification Investment | F-Gas compatibility documentation accelerates specification in German and French replacement cycles. |
| Pre-insulated Bundle Assembly Capacity | Complete system packaging compresses on-site labor hours and reduces field-assembly errors. |
| Smart-home Integration Partnership | Thermostat ecosystem alliances open UK and Irish renovation channels beyond new-build. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with HVAC distributors, installation contractors, heat pump manufacturers, and building code officials combined with secondary validation from EU Ecodesign documentation, F-Gas Regulation implementation reports, and national construction permit databases. Bottom-up project pipeline enumeration and top-down equipment shipment analysis provided triangulation across the analysis window.
Data-stream reconciliation across manufacturer shipment reports, distributor inventory positions, and end-user specification surveys informed the analytical framework. Segmentation dimensions modeled include product hardware category, heat source technology, construction application type, and regional regulatory cluster. CAGRs derived from unit volume trajectory analysis and average selling price evolution across the projection horizon. Heat pump capacity factor assumptions and installer certification density by geography served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for propane refrigerant heat pumps would alter the outlook for flow-temperature optimization requirements. Forecasts reflect documented assumptions regarding EU member state transposition timelines for Green Deal mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Roof Vents Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Aeration System Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Cold Insulation Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market