
 North America Scrubber System Market | 2026-2036
North America Scrubber System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Scrubber System Market Insights
Power generation is pivoting toward flue gas desulfurization upgrades as coal plants retrofit for mercury and acid gas compliance. Babcock & Wilcox Enterprises anchors its position through boiler-integrated scrubber engineering for utility clients. Donaldson Company leverages filtration media expertise across industrial exhaust streams. CECO Environmental Corp. competes on turnkey system design for chemical processing facilities.
Scrubber systems are gas-liquid or gas-solid contact devices that remove particulate matter and acid gases from industrial exhaust streams through absorption, adsorption, or chemical reaction, typically operating at pressure drops between 2-10 inches of water column and removal efficiencies exceeding 95% for sulfur oxides. Wet scrubber configurations dominate the installed base across power and marine segments due to established performance on high-sulfur streams, while dry scrubber variants gain traction in water-scarce regions and applications where wastewater handling costs erode project economics. Absorption technology leads the technology category through mature limestone-gypsum chemistry, though ion exchange approaches are carving niche positions in metals recovery and closed-loop process applications.
EPA Mercury and Air Toxics Standards, NHTSA marine engine emission regulations, and Coast Guard ballast water treatment mandates collectively tighten compliance horizons for scrubber procurement decisions. State-level renewable portfolio standards in California and New York indirectly redirect scrubber investment toward biomass and waste-to-energy facilities rather than traditional coal infrastructure. Stakeholders must weigh scrubber technology selection against impending carbon border adjustments and evolving clean hydrogen production standards that could redefine stack emission profiles across the region.
Market Dynamics
EPA sulfur dioxide standards are compressing compliance timelines for refinery operators across the Gulf Coast, forcing accelerated wet scrubber procurement cycles and reshaping vendor qualification criteria around integrated engineering capabilities.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:Coal-fired power plants in the Ohio River Valley face mandated retrofit deadlines, driving flue gas desulfurization upgrade volumes.
- Limestone-gypsum chemistry maturity:Established absorption processes reduce commissioning risk for utility procurement teams evaluating wet scrubber configurations.
- Texas-Louisiana petrochemical cluster density:Concentrated refining and chemical processing capacity generates sustained dry scrubber demand for acid gas control.
Market Restraints
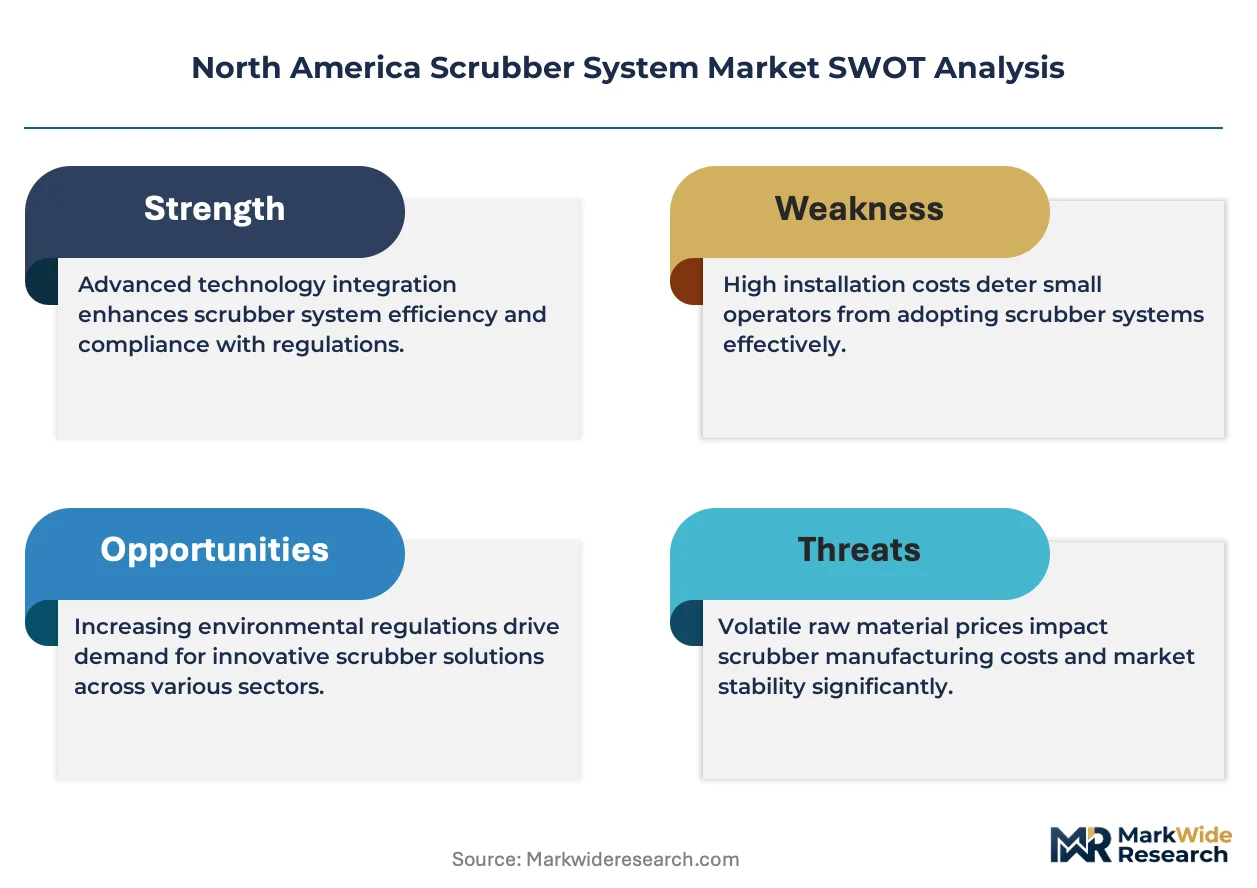
- Stainless steel alloy cost volatility:Scrubber vessel fabrication depends on nickel and molybdenum price stability, which fluctuates with mining supply disruptions.
- Wastewater handling economics:Wet scrubber installations in water-scarce regions face eroded project returns due to treatment and discharge cost structures.
- Limestone supply concentration:High-purity absorbent sourcing clusters in specific mining districts, creating logistics vulnerability for inland power generators.
Strategic Opportunities
- Biomass and waste-to-energy facilities:California and New York renewable portfolio standards redirect scrubber investment toward non-coal thermal infrastructure.
- Ion exchange metals recovery:Closed-loop process applications in chemical processing enable differentiated positioning against commodity absorption systems.
- Carbon border adjustment anticipation:Early-mover industrial facilities are pre-positioning scrubber investments ahead of potential embodied carbon tariffs on imported goods.
Industry Challenges
- Wet-dry scrubber technology selection:Procurement teams lack standardized decision frameworks for comparing water consumption against removal efficiency trade-offs across site-specific conditions.
- Legacy boiler integration complexity:Retrofit projects face structural constraints from existing stack configurations and foundation load limits.
- Coast Guard ballast water coordination:Marine scrubber installations must align with concurrent treatment system mandates, compressing shipyard scheduling windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Scrubber System Market |
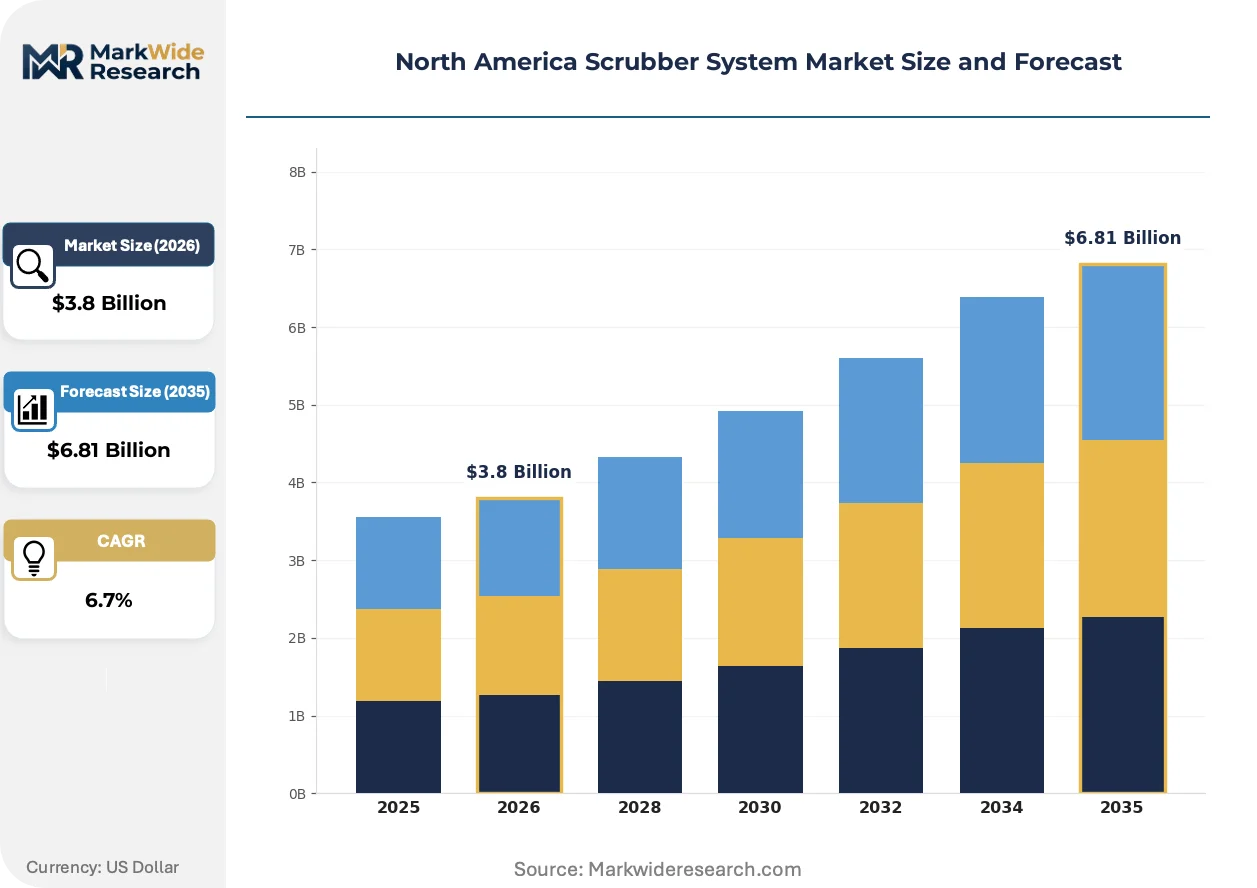
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wet Scrubber, Dry Scrubber, Electrostatic Precipitator, Chemical Scrubber Application: Industrial Processes, Waste Gas Treatment, Marine Applications, Power Generation End User: Manufacturing, Oil & Gas, Marine, Power Plants Technology: Absorption, Adsorption, Ion Exchange, Filtration |
| Companies Covered | Donaldson Company, Inc., Tri-Mer Corporation, Babcock & Wilcox Enterprises, Inc., KCH Services Inc., Verantis Environmental Solutions Group, CECO Environmental Corp., Parker-Hannifin Corporation, Evoqua Water Technologies LLC, Ducon Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Scrubber System Market Trends and Innovations
Scrubber system architecture is pivoting toward modular, skid-mounted configurations that compress field installation timelines and reduce dependency on specialized construction labor pools.
Semi-dry scrubber technology is integrating hydrated lime injection systems with fabric filter particulate capture to achieve dual acid gas and particulate control in a single vessel train. Cement producers in the Great Lakes region are piloting these configurations to consolidate emission control footprints. This convergence is integrating sorbent handling and filtration stages into unified process designs that reduce capital intensity for mid-scale industrial boilers.
EPA enforcement patterns under the Clean Air Act are tightening consent decree timelines for refinery flare and furnace emission sources. Operators in the Houston Ship Channel corridor face compressed compliance windows that favor turnkey engineering-procurement-construction contracts over component sourcing strategies. The regulatory pressure is concentrating procurement authority with integrated technology licensors rather than equipment fabricators.
Industrial buyers are unbundling after-sales service contracts from initial equipment supply, creating standalone maintenance and reagent supply markets. Chemical processing facilities in the Delaware Valley are sourcing limestone and hydrated lime through separate long-term agreements rather than bundled scrubber vendor contracts. This disintermediation is visible across the Gulf Coast where procurement teams negotiate sorbent supply independently to optimize logistics costs against spot market pricing.
North America Scrubber System Market Segmentation
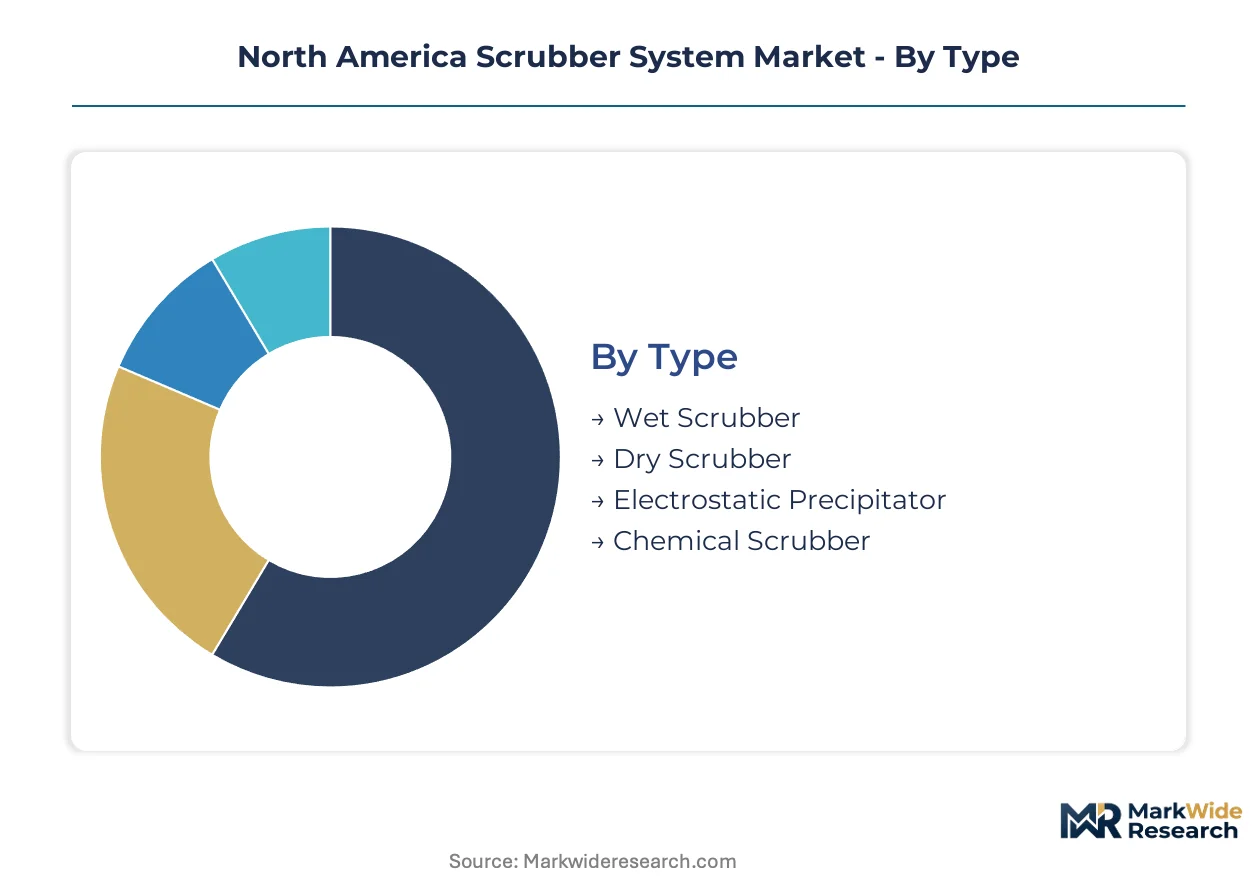
Scrubber system procurement in North America follows distinct technical and commercial logics across type, application, end user, and technology dimensions. Each segmentation axis reveals where engineering specifications, regulatory pressure, and operational economics intersect to drive vendor selection and system configuration decisions.
Type:
Supply concentration for scrubber vessels clusters with specialized fabricators in the Gulf Coast industrial corridor, where proximity to petrochemical demand shapes manufacturing footprints and delivery timelines.
- Wet Scrubber:Gas-liquid contact devices utilizing aqueous reagents to capture acid gases and particulate matter through absorption chemistry. Demand concentrates across Ohio River Valley coal plants facing EPA Mercury and Air Toxics Standards retrofit deadlines, where limestone-gypsum process maturity reduces commissioning risk for utility procurement teams.
- Dry Scrubber:Gas-solid contact systems injecting dry sorbents for acid gas neutralization without wastewater generation. Texas and Louisiana petrochemical clusters drive procurement volumes for acid gas control, with water-scarce site conditions favoring configurations that eliminate liquid effluent handling costs.
- Electrostatic Precipitator:Electrostatic charge-based particulate collection systems operating at high voltage differentials. Cement producers in the Great Lakes region pilot integrated configurations for dual emission control.
- Chemical Scrubber:Specialized systems employing reactive chemical solutions for targeted contaminant removal. Niche demand emerges from semiconductor fabrication facilities requiring ultra-high purity exhaust treatment.
Wet scrubbers absorb the bulk of installed capacity across power and marine segments; dry scrubbers are expanding most quickly in water-constrained industrial regions.
Application:
Cost tier differentiation separates turnkey engineering-procurement-construction contracts from component sourcing strategies, with compressed compliance timelines in refinery sectors favoring integrated vendor relationships over fragmented procurement.
- Industrial Processes:Emission control for chemical manufacturing, metals processing, and cement production operations. Gulf Coast refinery operators facing EPA sulfur dioxide standards drive wet scrubber installation cycles with accelerated procurement timelines.
- Waste Gas Treatment:Systems targeting volatile organic compounds, hazardous air pollutants, and odor control from municipal and industrial waste streams. California and New York renewable portfolio standards redirect investment toward biomass and waste-to-energy facilities.
- Marine Applications:Exhaust gas cleaning systems for vessel compliance with NHTSA marine engine emission regulations. Coast Guard ballast water treatment mandates compress shipyard scheduling windows for concurrent installation projects.
- Power Generation:Flue gas desulfurization and mercury control for coal-fired and biomass thermal plants. Ohio River Valley utilities anchor demand for boiler-integrated scrubber engineering upgrades.
Power generation retains the largest installed base; waste gas treatment climbs the fastest on renewable portfolio standard redirection toward non-coal thermal infrastructure.
End User:
Customer type segmentation distinguishes between owner-operators with captive engineering capabilities and facilities relying on external technology licensors for system design and commissioning support.
- Manufacturing:Chemical processing, food and beverage, and pharmaceutical production facilities requiring particulate and acid gas control. Delaware Valley chemical processing facilities source limestone and hydrated lime through separate long-term agreements rather than bundled vendor contracts.
- Oil & Gas:Refinery flare and furnace emission sources across the Houston Ship Channel corridor. EPA Clean Air Act enforcement patterns tighten consent decree timelines, concentrating procurement authority with integrated technology licensors.
- Marine:Commercial shipping lines and vessel operators installing exhaust gas cleaning systems. Shipyard capacity constraints in Gulf and Atlantic ports limit simultaneous scrubber and ballast water treatment installations.
- Power Plants:Utility and independent power producers retrofitting coal and biomass boilers for mercury and acid gas compliance. Babcock & Wilcox Enterprises anchors position through boiler-integrated scrubber engineering for utility clients.
Oil and gas absorbs dominant procurement volume; manufacturing is gaining share fastest on disintermediation trends separating equipment supply from reagent sourcing.
Technology:
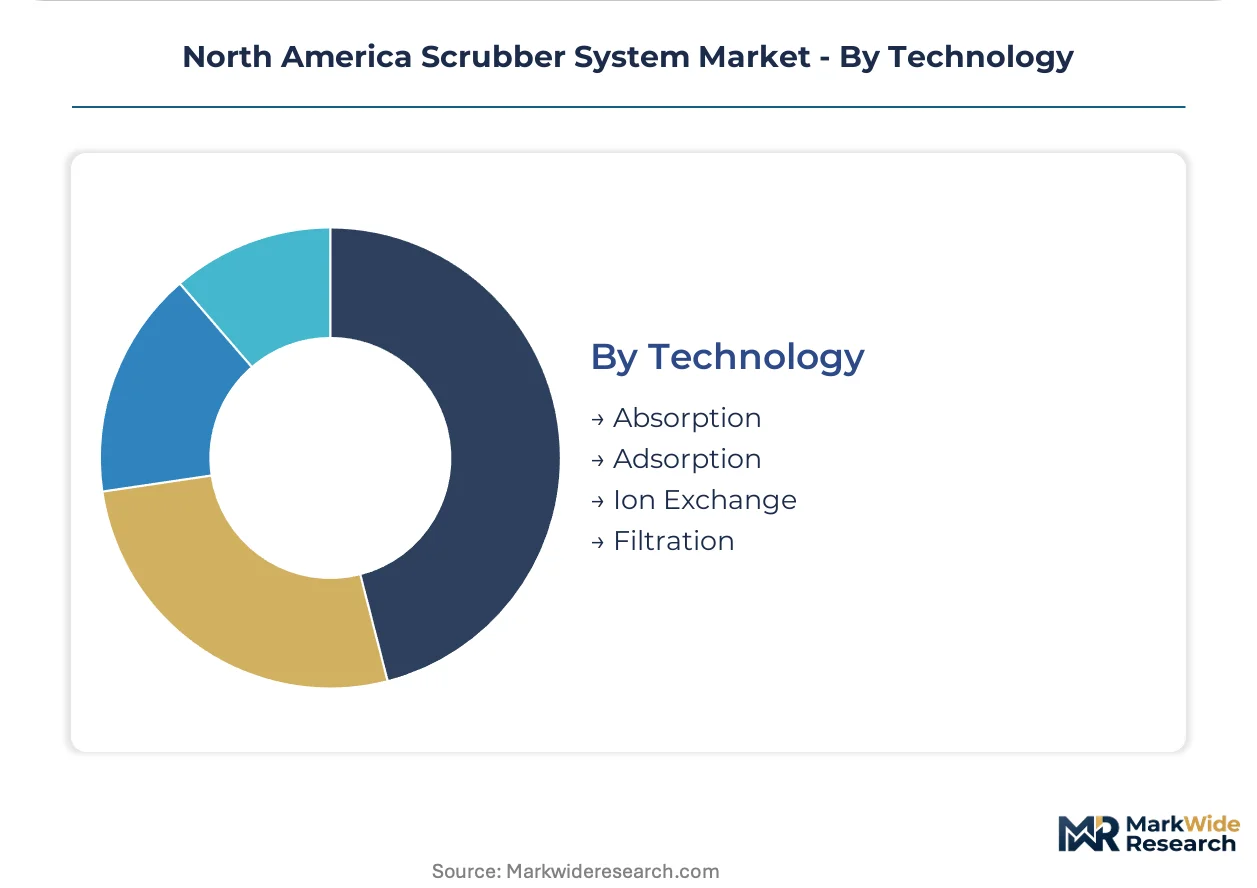
Maturity gradients separate established absorption processes with decades of operational history from emerging ion exchange approaches carving niche positions in metals recovery applications.
- Absorption:Gas-liquid mass transfer processes utilizing limestone-gypsum chemistry for sulfur oxide capture. Mature process designs reduce commissioning risk for utility procurement teams evaluating wet scrubber configurations.
- Adsorption:Surface-based contaminant capture using activated carbon or zeolite media. Activated carbon injection systems serve mercury control requirements at coal plants.
- Ion Exchange:Selective ion transfer processes enabling metals recovery and closed-loop process applications. Chemical processing facilities deploy differentiated configurations against commodity absorption systems.
- Filtration:Physical particulate separation through fabric filters or cartridge systems. Donaldson Company leverages filtration media expertise across industrial exhaust streams.
Absorption technology commands the dominant share of operational installations; ion exchange shows steepest expansion trajectory in closed-loop process applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Opportunity Zone tax incentives concentrate scrubber procurement authority along the Texas-Louisiana industrial corridor. EPA enforcement patterns under the Clean Air Act compress compliance timelines for refinery operators. State renewable portfolio standards in coastal markets redirect investment toward biomass and waste-to-energy facilities.
United States
Ohio River Valley coal plants face EPA Mercury and Air Toxics Standards retrofit deadlines driving flue gas desulfurization upgrade volumes. The EPA sulfur dioxide standards compress procurement cycles for Gulf Coast refinery operators. Houston Ship Channel corridor facilities favor turnkey engineering-procurement-construction contracts over fragmented component sourcing.
Canada
Alberta oil sands operators deploy wet scrubber configurations for acid gas control in bitumen upgrading facilities. Environment and Climate Change Canada regulations tighten emission limits for oil and gas processing. Sarnia-Lambton petrochemical corridor in Ontario sustains demand for dry scrubber systems in chemical manufacturing.
Mexico
Refinery modernization at Pemex facilities drives scrubber procurement for sulfur recovery and acid gas control. SEMARNAT environmental standards align with US EPA benchmarks for cross-border industrial zones. Altamira petrochemical cluster on the Tamaulipas coast expands emission control infrastructure for polyethylene production.
North America Scrubber System Market Competitive Landscape
Top-tier vendors anchor integrated engineering-procurement-construction contracts, while mid-tier fabricators compete on vessel supply and aftermarket service. The vendor base stratifies between technology licensors with process chemistry expertise and specialized fabricators with alloy welding capabilities. Three archetypes dominate: boiler-integrated system designers, filtration media specialists, and turnkey environmental contractors. Competitive moves concentrate on strategic partnerships for reagent supply integration and geographic expansion into petrochemical corridor markets.
Among US-based industrial conglomerates, Donaldson Company, Inc. and Parker-Hannifin Corporation exemplify the filtration-centric archetype with cross-sector exhaust treatment positioning. Babcock & Wilcox Enterprises, Inc. occupies the boiler-integrated tier through utility-focused engineering capabilities. CECO Environmental Corp. represents the turnkey contractor model with chemical processing facility specialization.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Tri-Mer Corporation |
| Babcock & Wilcox Enterprises, Inc. |
| KCH Services Inc. |
| Verantis Environmental Solutions Group |
| CECO Environmental Corp. |
| Parker-Hannifin Corporation |
| Evoqua Water Technologies LLC |
| Ducon Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Compressed EPA compliance timelines for Ohio River Valley coal plants and Gulf Coast refineries force procurement teams toward premium-priced turnkey engineering-procurement-construction contracts, concentrating supply authority with integrated licensors and elevating vessel fabrication costs for specialized alloy welding capabilities.
Pricing Analysis
Expedited lead-time premiums dominate vendor quotations as shipyard scheduling windows compress under concurrent Coast Guard ballast water mandates. Three-tier pricing structure across premium, standard, and economy levels separates integrated EPC licensors from component fabricators and aftermarket service providers. Price differentiation hinges on reagent supply bundling and limestone logistics integration. Cost compression in standard-tier vessel supply is intensifying because nickel-molybdenum alloy volatility erodes fabricator margins. Small independent power producers exhibit highest price sensitivity; integrated petrochemical majors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Scrubber vessel refurbishment and alloy component remanufacturing flows are gaining traction as fabricators extend asset life cycles to offset stainless steel cost volatility. Manufacturing concentrates in the United States, Canada, and Mexico, with Gulf Coast proximity to petrochemical demand shaping delivery timelines. Production draws from nickel mining districts, high-purity limestone quarries, and specialized welding consumables. Single-source vulnerability clusters in high-grade absorbent sourcing regions. Distribution runs through EPC contractor networks and direct OEM relationships with utility procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alloy welding capacity constraints prop pricing power for incumbent fabricators, creating supply-constrained procurement dynamics across wet scrubber installations.
For Market Incumbents: Anticipate ion exchange technology displacement in metals recovery applications by accelerating closed-loop process R&D investment. Defend against emerging modular skid-mounted competitors through backward integration into limestone reagent supply. Capacity addition in Texas-Louisiana corridor anchors regional procurement authority. For New Entrants and Emerging Players: Regional EPC contractors represent the most accessible channel for market entry without incumbent fabrication assets. Target biomass and waste-to-energy facilities in California and New York renewable portfolio standard jurisdictions. White-space exists in aftermarket service unbundling and independent reagent supply contracting. Pursue joint-venture positioning with established filtration media specialists. For Investors and Strategic Acquirers: The window for entry favors ion exchange technology specialists with chemical processing facility relationships. Long-term viability rests on carbon border adjustment pre-positioning and clean hydrogen production standard alignment. Monitor EPA consent decree enforcement velocity as inflection indicator for turnkey contract demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reagent Supply | Limestone and hydrated lime sourcing control reduces procurement disintermediation risk for integrated vendors. |
| Modular Skid-Mounted Configuration Development | Compressed field installation timelines reduce dependency on specialized Gulf Coast construction labor pools. |
| Ion Exchange Technology Licensing | Metals recovery applications in chemical processing enable differentiation against commodity absorption competitors. |
| Biomass Facility Partnership Expansion | California and New York renewable portfolio standards redirect scrubber investment toward non-coal thermal infrastructure. |
| Turnkey EPC Capability Buildout | Integrated engineering-procurement-construction positioning captures compressed compliance timeline premiums from refinery operators. |
Research Methodology
EPA enforcement databases, FERC utility filings, and SEC 10-K disclosures formed the secondary backbone for regulatory timeline and procurement pattern validation. Primary interviews with refinery engineering directors, utility procurement managers, EPC contract officers, and vessel fabrication plant managers combined with bottom-up installation tracking and top-down market sizing triangulation. Trade data from customs records and petrochemical cluster development permits anchored geographic demand concentration analysis.
Historical trendline analysis of scrubber procurement cycles across coal retrofit and greenfield petrochemical installations established baseline demand patterns. The analytical framework modeled segmentation across scrubber type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from unit installation forecasts and average system value trajectories. Forecast inputs incorporated EPA Mercury and Air Toxics Standards compliance deadlines and state renewable portfolio standard adoption curves.
Caveats apply where nickel-molybdenum alloy price volatility, EPA enforcement pattern shifts, or carbon border adjustment implementation timing could materially shift the outlook. Forecasts reflect assumptions around regulatory compliance horizon stability and reagent supply logistics continuity. Practitioners should monitor EPA consent decree settlement velocity and limestone mining district labor actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Aeration System Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Marine HVAC Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
North America and GCC HVAC Insulation Market