
 Marine HVAC Market | 2026-2036
Marine HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Marine HVAC Market Foresight
Consolidation among cruise operators and offshore drilling contractors is realigning procurement leverage toward turnkey HVAC packages. Carrier Corporation leverages its refrigeration heritage to anchor positions on large cruise newbuilds. Daikin Industries competes through variable refrigerant flow expertise adapted for naval specifications. Heinen & Hopman specializes in custom chilled-water architectures for expedition and ice-class vessels.
Marine HVAC encompasses climate control, ventilation, and refrigeration systems engineered for salt-air corrosion resistance, vessel motion tolerance, and space-constrained machinery rooms. These installations maintain habitable conditions across engine compartments, accommodation blocks, cargo holds, and bridge environments while satisfying SOLAS fire-safety and MARPOL refrigerant protocols. Chilled water systems dominate commercial vessel specifications due to centralized redundancy and lower refrigerant charge volumes. Direct expansion configurations occupy niches in yacht and fast-ferry applications where weight minimization overrides efficiency priorities. Smart control technology represents the fastest-expanding segment as owners pursue fuel consumption optimization through integrated hotel load management.
The International Maritime Organization enforces MARPOL Annex VI emissions standards that directly constrain refrigerant selection and energy efficiency indexing for shipboard climate systems. Classification societies including DNV and Lloyd's Register administer HVAC fire-damper and insulation ratings that gate market access for component suppliers. Stakeholders must monitor refrigerant phase-down schedules and evolving carbon intensity indicator thresholds to align R&D roadmaps with compliance trajectories.
Market Dynamics
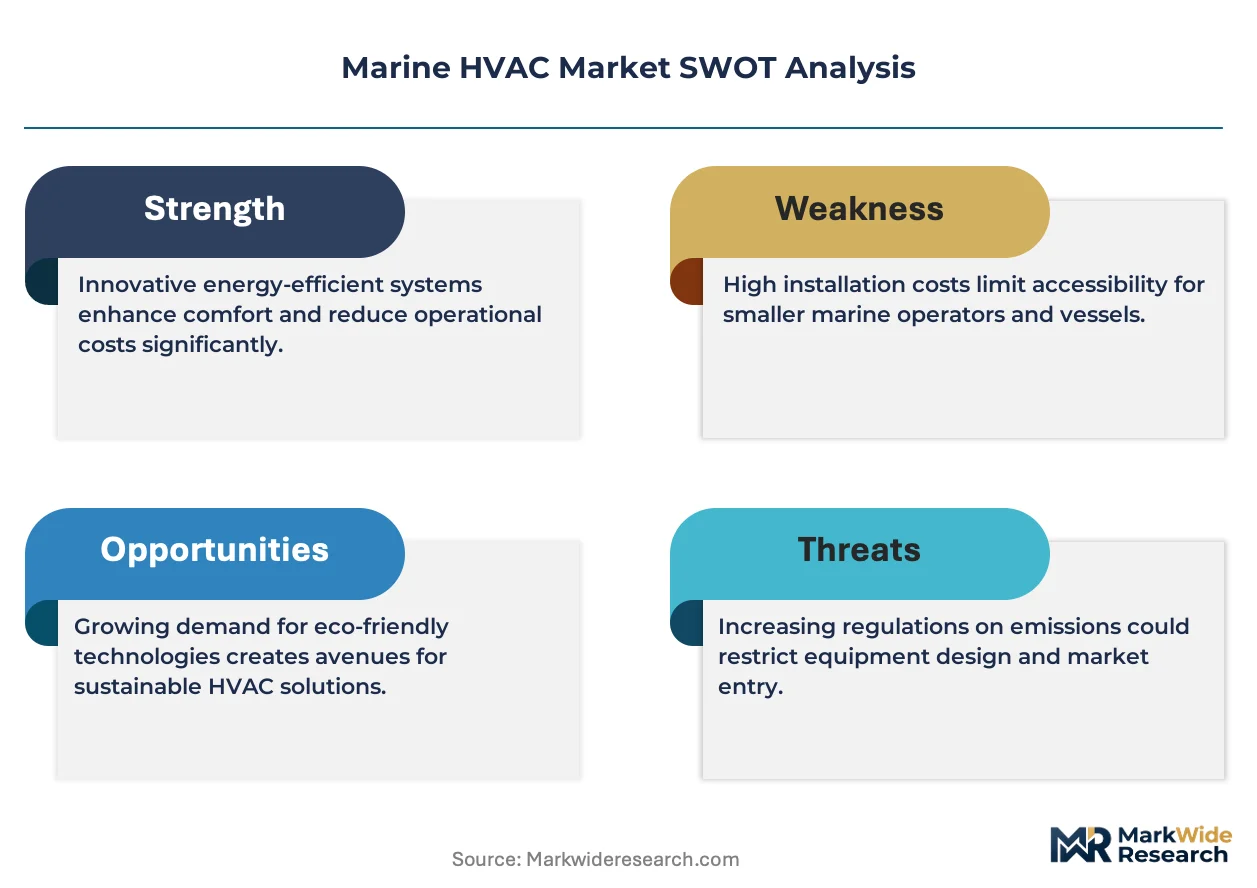
The International Maritime Organization's Kigali Amendment implementation is compressing refrigerant phase-down timelines, forcing shipyards and system integrators to redesign machinery room architectures around low-GWP alternatives before 2030 compliance deadlines.
Growth Catalysts
- Cruise Fleet Renewal:Major cruise operators are commissioning newbuild vessels with integrated HVAC specifications that exceed current efficiency baselines, creating demand for turnkey climate packages.
- EU F-Gas Regulation:The European Union's fluorinated gas phase-down mandates are accelerating retrofit demand across existing EU-flagged commercial fleets.
- Smart Control Adoption:Shipowners are deploying integrated hotel load management systems that optimize fuel consumption through real-time climate system modulation.
Market Restraints
- Copper-Nickel Alloy Costs:Specialized corrosion-resistant piping materials face price volatility tied to nickel commodity markets, squeezing fabrication margins for chilled-water system builders.
- South Korean Yard Concentration:Newbuild contracting clusters heavily around Hyundai Heavy Industries and Samsung Heavy Industries facilities, creating procurement bottleneck risk for HVAC suppliers.
- Refrigerant Supply Constraints:Limited global production capacity for HFO-1234yf and R-513A alternatives constrains system scaling for large cruise and offshore platform applications.
Strategic Opportunities
- India Shipbuilding Expansion:Cochin Shipyard and Mazagon Dock are developing specialized climate system capabilities for naval and coast guard contracts, opening localized supply chain entry points.
- Ammonia Refrigeration Convergence:Integration of CO2-ammonia cascade systems with waste heat recovery is creating viable pathways for ice-class and expedition vessel specifications.
- Digital Twin Integration:Remote monitoring platforms are enabling predictive maintenance contracts that extend supplier revenue streams beyond equipment delivery.
Industry Challenges
- Marine Refrigeration Certification:Lloyd's Register and DNV type-approval timelines for novel refrigerant systems extend 18-24 months, compressing newbuild delivery schedules.
- Legacy Control Integration:Retrofit installations must bridge proprietary communication protocols between 1990s-era ship automation and modern BACnet/IP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine HVAC Market |
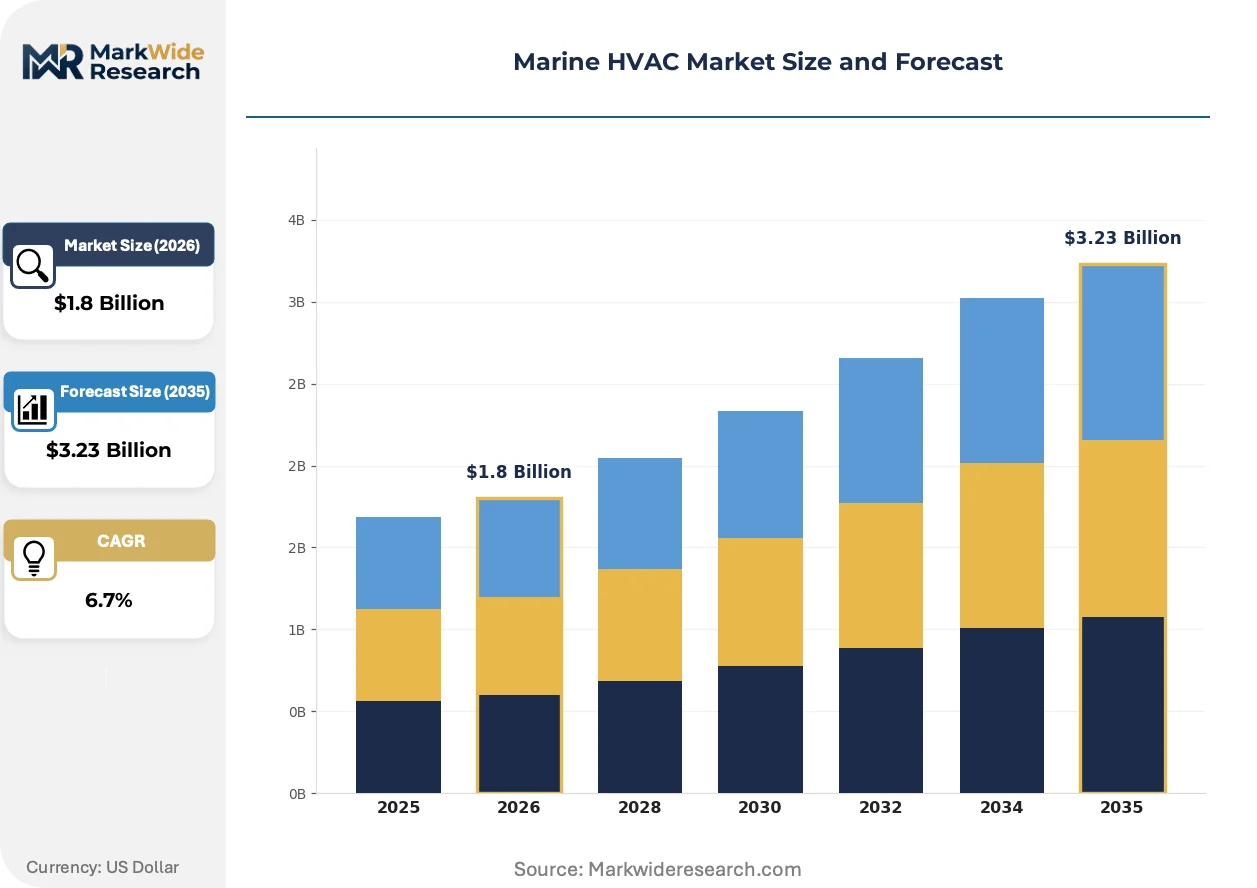
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Chilled Water, Direct Expansion, Hybrid, Ventilation Component: Compressors, Air Handlers, Condensers, Ducts Application: Commercial Vessels, Naval Ships, Offshore Platforms, Yachts Technology: Refrigeration, Heat Pump, Smart Control, Variable Speed Drive |
| Companies Covered | Heinen & Hopman, Brownswerk Marine Inc, Carrier Corporation, AF Group ASA, Drews Marine GmbH, Daikin Industries, Dometic Group, Bronswerk Marine Inc, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine HVAC Market Shifts & Advancements
Digitalization is penetrating marine climate systems through sensor-dense architectures that enable condition-based maintenance and autonomous load balancing across vessel operating profiles.
Variable refrigerant flow technology adapted for naval specifications is expanding into offshore support vessels and expedition yachts. Daikin Industries has secured multiple platform supply vessel contracts where weight reduction outweighs first-cost premiums. The technology is expanding into segments previously dominated by centralized chilled-water architectures.
Europe's F-Gas Regulation revision tightens refrigerant containment and service record requirements for vessels operating under EU member state flags. Shipowners must now maintain digital refrigerant logs accessible to port state control inspectors. German-flagged container fleets are responding by accelerating HFO conversions ahead of 2027 checkpoint dates.
Fleet operators are unbundling HVAC service contracts from original equipment procurement, creating standalone aftermarket revenue pools. Independent service providers in Singapore and Rotterdam are capturing multiyear maintenance agreements previously retained by manufacturers. This shift is most visible among Greek and Danish tanker operators managing aging vessel portfolios.
Marine HVAC Market Segmentation
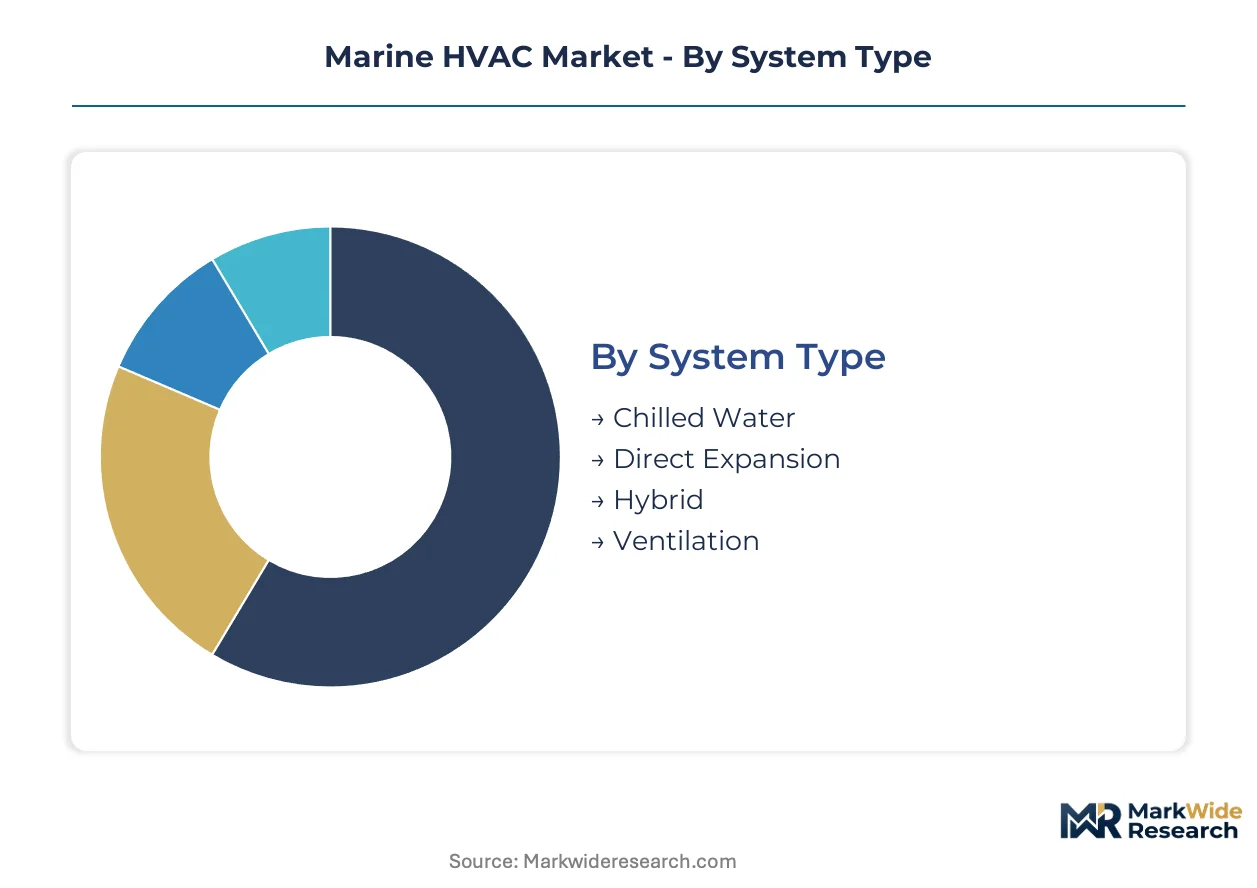
Marine HVAC procurement decisions hinge on vessel classification, operating environment, and regulatory compliance tier. System architecture varies sharply between cruise newbuilds requiring Lloyd's Register type-approval and naval contracts demanding MIL-STD shock qualification.
System Type:
DNV and Lloyd's Register certification timelines differ substantially across architectures, with chilled-water systems facing extended fire-damper testing protocols that compress shipyard delivery schedules.
- Chilled Water:Centralized architecture using corrosion-resistant Cu-Ni piping and redundant chiller arrays. Cruise operators in Germany and Norway specify these for accommodation blocks due to lower refrigerant charge volumes and SOLAS-compliant fire isolation. Lloyd's Register insulation ratings gate component market access.
- Direct Expansion:Distributed refrigerant circuits with compact outdoor condensing units. Fast-ferry operators in South Korea and yacht builders in Italy prioritize weight minimization over efficiency, accepting higher GWP refrigerant exposure for machinery room footprint reduction.
- Hybrid:Combined chilled-water and DX zones optimizing hotel load distribution across vessel profiles.
- Ventilation:Supply and exhaust systems with fire-damper integration for smoke control compliance.
Leading the category by volume: Chilled Water. Growing fastest: Hybrid configurations gaining share in expedition vessel specifications.
Component:
Cost tiers separate OEM-supplied integrated packages from third-party component sourcing, with compressors commanding premium pricing tied to refrigerant compatibility certification.
- Compressors:Semi-hermetic screw and centrifugal units adapted for vessel motion tolerance. HFO-1234yf compatibility requirements are forcing redesigns of sealing systems and lubricant specifications, extending DNV approval cycles.
- Air Handlers:Salt-air corrosion-resistant coils with variable speed fan arrays. South Korean yards specify these for accommodation climate zones in container ship newbuilds.
- Condensers:Shell-and-tube or plate heat exchanger configurations for seawater cooling circuits.
- Ducts:Pre-insulated galvanized or stainless steel distribution networks with A-60 fire rating.
Margin concentration: Compressors. Fastest expansion: Smart-integrated air handlers with BACnet/IP connectivity.
Application:
Customer procurement leverage varies by fleet scale, with cruise consolidates demanding turnkey packages and naval authorities fragmenting awards across domestic suppliers.
- Commercial Vessels:Container ships, tankers, and bulk carriers requiring SOLAS-compliant climate control for crew accommodation. Greek and Danish operators are unbundling service contracts from equipment procurement, creating standalone aftermarket revenue pools for independent providers in Rotterdam.
- Naval Ships:MIL-STD shock-qualified systems with electromagnetic interference shielding. India's Cochin Shipyard and Mazagon Dock are developing localized climate capabilities for coast guard contracts.
- Offshore Platforms:Modular HVAC for living quarters and process control rooms in North Sea and Gulf of Mexico installations.
- Yachts:Custom architectures prioritizing acoustic attenuation and space constraints over operational efficiency.
Dominant by contract value: Commercial Vessels. Steepest expansion trajectory: Naval Ships amid fleet modernization programs in India and South Korea.
Technology:
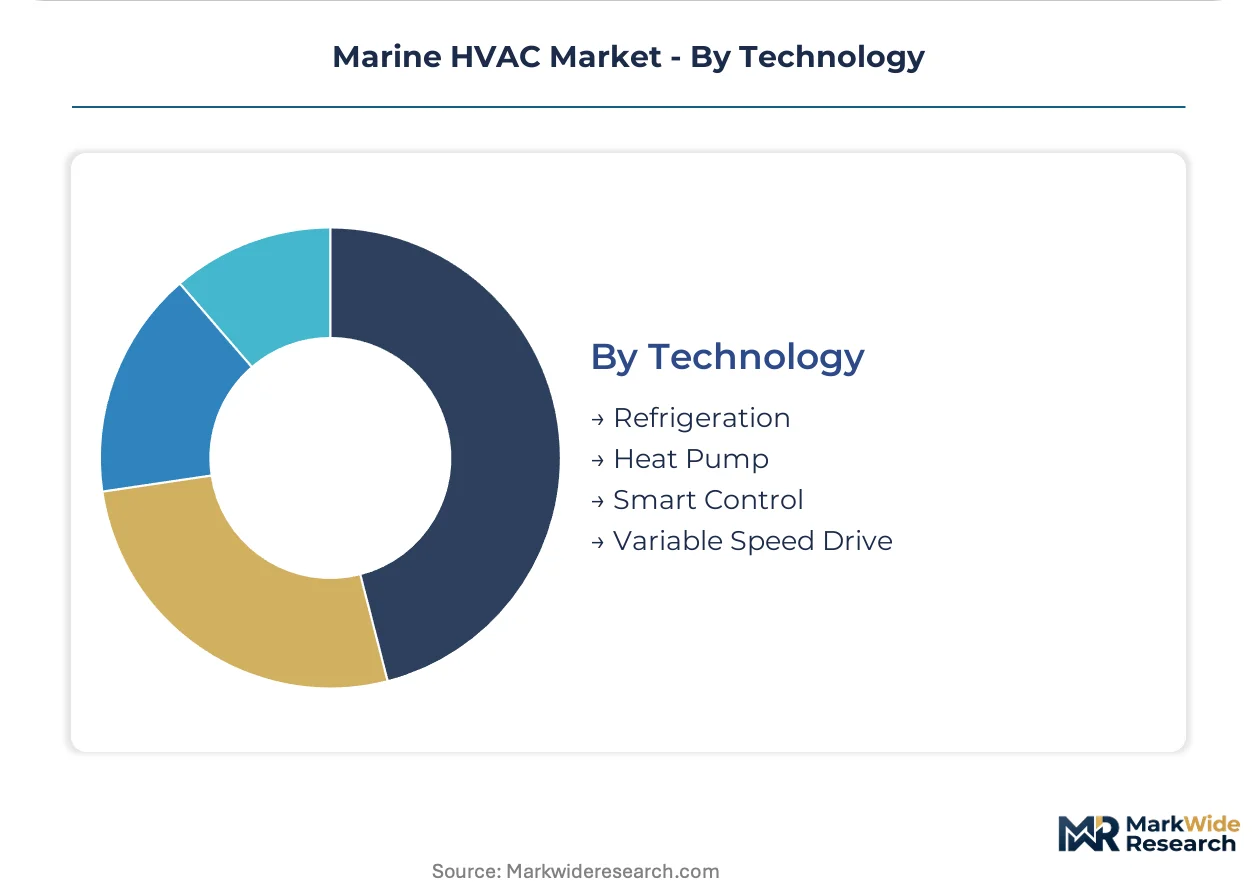
Maturity curves separate established refrigeration cycles from emerging digital integration layers, with smart control adoption accelerating fastest among fuel-cost-sensitive operators.
- Smart Control:Integrated hotel load management with real-time climate modulation and predictive maintenance algorithms. Shipowners deploying these systems capture fuel consumption optimization through autonomous load balancing across operating profiles.
- Refrigeration:Vapor compression cycles using low-GWP alternatives including HFO-1234yf and R-513A. EU F-Gas Regulation mandates are accelerating retrofit demand across German-flagged fleets.
- Heat Pump:Reversible cycles for heating and cooling using waste heat recovery integration.
- Variable Speed Drive:Motor control systems optimizing compressor and fan energy draw against load conditions.
Highest installed base: Refrigeration. Climbing the fastest: Smart Control as owners pursue carbon intensity indicator compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Norway, and South Korea where specialized marine engineering clusters dominate newbuild contracting for cruise, offshore, and commercial vessel programs.
Germany
Cruise operators headquartered in Hamburg and Rostock drive specifications for Lloyd's Register-certified chilled-water architectures. The EU F-Gas Regulation mandates refrigerant phase-downs that accelerate HFO conversions across German-flagged container fleets. Meyer Werft in Papenburg anchors production of expedition vessels requiring custom climate systems.
Norway
Offshore energy contractors in Stavanger and Bergen commission HVAC packages for platform supply vessels and ice-class expedition ships. Norwegian Maritime Authority enforcement of MARPOL Annex VI tightens emissions indexing for shipboard climate systems. Ulstein Group in Ulsteinvik integrates ammonia-ready refrigeration into newbuild specifications.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries in Ulsan and Geoje concentrate global newbuild contracting for container ships and LNG carriers. The MFDS refrigerant certification timeline compresses delivery schedules for low-GWP system integrations. Busan-based engineering firms specialize in direct expansion configurations for fast-ferry applications.
United States
Gulf of Mexico offshore platform operators in Houston procure modular HVAC for living quarters and process control rooms. EPA refrigerant management rules under SNAP program constrain HFC alternatives in coastal vessel retrofits. Seattle-area shipyards serving Alaska cruise routes specify corrosion-resistant ventilation for salt-air environments.
India
Cochin Shipyard and Mazagon Dock in Kochi and Mumbai develop localized climate capabilities for naval and coast guard fleet modernization. The Ministry of Defence's indigenization mandates under Make in India open procurement to domestic HVAC integrators. Visakhapatnam submarine construction programs require MIL-STD shock-qualified systems with electromagnetic shielding.
Marine HVAC Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart control integration and ammonia-ready architectures. The vendor base spans diversified industrial conglomerates, specialized marine engineering houses, and regional fabrication shops. Three archetypes dominate: refrigeration heritage players leveraging compressor expertise, naval specification specialists with shock-qualified portfolios, and system integrators bundling turnkey packages. Competitive moves center on certification acceleration for novel refrigerants and unbundling of service contracts from equipment procurement.
Among diversified conglomerates with refrigeration heritage, Carrier Corporation and Daikin Industries exemplify scale-driven positioning through variable refrigerant flow adaptations and compressor technology platforms. Heinen & Hopman occupies the specialist tier as a Dutch marine engineering house focused on custom chilled-water architectures. These three anchors illustrate divergent strategic postures: heritage leverage, technology transfer from adjacent sectors, and niche specification depth.
| Leading Market Players |
|---|
| Heinen & Hopman |
| Brownswerk Marine Inc |
| Carrier Corporation |
| AF Group ASA |
| Drews Marine GmbH |
| Daikin Industries |
| Dometic Group |
| Bronswerk Marine Inc |
| Johnson Controls |
| Others |
Supply & Pricing Matrix
Cruise operator consolidation into three major procurement consortia is compressing supplier margins and forcing HVAC integrators toward turnkey contract structures with embedded service obligations. This buyer concentration shifts pricing power toward volume-scale discounts while elevating certification and after-sales bundling as non-negotiable table stakes.
Pricing Analysis
Volume-scale contracting dominates commercial vessel procurement while margin capture concentrates in naval and expedition yacht specifications. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's Register-certified turnkey packages from component-only supply and basic retrofit kits. Price differentiation hinges on refrigerant compatibility certification and geographic delivery cost to South Korean yard clusters. Pricing pressure stems from copper-nickel alloy cost volatility squeezing chilled-water system fabricators. Greek and Danish tanker operators exhibit highest price sensitivity, while German cruise lines prioritize efficiency guarantees over first-cost minimization.
Supply Chain Analysis
Freight cost exposure runs through specialized compressor and heat exchanger movements from Germany, Japan, and South Korea to shipyard assembly points. Manufacturing concentrates in these three countries for semi-hermetic screw compressors, corrosion-resistant air handlers, and smart control modules. Raw material dependencies center on nickel for Cu-Ni piping, rare earth elements for variable speed drives, and specialized lubricants for HFO-compatible sealing systems. Single-source vulnerability in HFO-1234yf production creates bottleneck risk for large cruise newbuilds. Distribution feeds from OEM-integrated packages through shipyard procurement offices and independent service providers in Singapore and Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine HVAC vendor consolidation is accelerating as refrigerant phase-down deadlines and certification cost burdens force sub-scale fabricators toward exit or acquisition. The EU F-Gas Regulation and IMO Kigali Amendment implementation are the primary pressures eliminating weaker capitalized players.
For Market Incumbents: Deepen backward integration into compressor remanufacturing and refrigerant reclamation to capture aftermarket revenue streams unbundled from original equipment procurement. Invest in DNV and Lloyd's Register certification acceleration capabilities to compress 18-24 month approval timelines that currently constrain newbuild delivery schedules. Naval specification specialists with MIL-STD shock-qualified portfolios represent the most defensible moat against emerging smart-control entrants. For New Entrants and Emerging Players: Independent service providers in Singapore and Rotterdam offer the most penetrable channel entry point, as Greek and Danish tanker operators fragment maintenance contracts away from OEM captivity. Target ammonia-ready refrigeration architectures for ice-class and expedition vessel specifications where Ulstein Group and Meyer Werft are actively sourcing alternative systems. Digital twin integration for predictive maintenance contracts provides the clearest go-to-market angle with recurring revenue potential. For Investors and Strategic Acquirers: The window for entry favors specialized marine engineering houses with established naval relationships and refrigerant certification expertise over diversified industrial conglomerates lacking shipyard integration. Long-term viability rests on positioning ahead of 2030 low-GWP compliance deadlines when retrofit demand peaks. Acquisition targets should demonstrate existing Lloyd's Register or DNV type-approval pipelines rather than early-stage technology development. Watch for refrigerant supply allocation announcements from HFO-1234yf producers as the inflection signal for system integrator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Certification Acceleration | Compresses DNV and Lloyd's Register approval timelines that currently gate shipyard delivery schedules. |
| Aftermarket Service Unbundling | Captures multiyear maintenance agreements from Greek and Danish tanker operators fragmenting procurement. |
| Ammonia-Ready Architecture Development | Positions suppliers for Ulstein Group and Meyer Werft ice-class expedition vessel specifications. |
| Digital Twin Platform Integration | Enables predictive maintenance contracts extending revenue streams beyond equipment delivery. |
| Naval Specification Qualification | Secures MIL-STD shock certification for India's Cochin Shipyard and Mazagon Dock modernization programs. |
Research Methodology
Independent corroboration across shipyard procurement officers, HVAC system integrators, and classification society engineers underwrites the qualitative findings in this study. Primary interviews with marine engineering directors, refrigerant supply specialists, and fleet technical managers combined with secondary validation from Lloyd's Register type-approval databases, DNV certification registries, and EU F-Gas Regulation compliance filings. Customs data on Cu-Ni alloy imports and compressor trade flows anchored bottom-up and top-down triangulation across the analysis window.
Rate-of-change decomposition across vessel class, system architecture, refrigerant technology tier, and regional regulatory cluster structured the analytical framework. CAGRs derived from shipyard order book analysis, fleet age profiles, and retrofit cycle timing across the projection horizon. Industry-specific forecast inputs incorporated IMO MARPOL Annex VI enforcement trajectories and MFDS refrigerant certification timelines for South Korean yard deliveries.
Several conditions sit outside the modeled scope, including unannounced naval procurement cancellations, abrupt refrigerant supply disruptions, and shipyard bankruptcy events. Forecasts reflect documented assumptions about regulatory enforcement consistency and shipowner capital commitment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Roof Vents Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Aeration System Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Freeze and Thaw Systems Market