
 Air Conditioning Equipment Market | 2026-2036
Air Conditioning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Conditioning Equipment Market Outlook
Energy-efficiency tier upgrades from SEER 14 to SEER 16+ standards is collapsing the addressable market for legacy fixed-speed compressor models across North American replacement cycles. Daikin Industries leverages its captive refrigerant chemistry pipeline to anchor premium ductless positioning in Japan and Europe. Carrier Global Corporation sustains institutional trust through deep specification relationships with federal building contractors. Gree Electrical Appliances dominates mass-market window unit production through integrated motor and coil manufacturing in Zhuhai.
Air conditioning equipment comprises vapor-compression or absorption-cycle assemblies that transfer thermal energy between conditioned spaces and ambient environments, typically operating with refrigerants at saturated pressures between 100 and 450 psi to achieve target dew points. Split system configurations lead residential volume globally while ductless mini-split formats capture disproportionate margin pools in retrofit and multi-zone commercial applications. Inverter technology displaces traditional fixed-speed compressor architectures across efficiency-regulated markets, with smart thermostat integration emerging as a software-layer differentiator in premium hospitality and commercial end-user segments.
EPA Significant New Alternatives Policy determinations restrict HFC refrigerant eligibility in new equipment, compelling OEMs to qualify A2L-class lower-flammability substitutes or natural refrigerant architectures. EU F-Gas Regulation mandates stepped GWP reduction quotas that tighten market access for import-dependent distributors. California Title 24 building efficiency standards extend these constraints through state-level appliance mandates that shape manufacturer product planning cycles. Stakeholders must monitor refrigerant transition timelines against heat pump technology convergence to preserve component platform economics.
Market Dynamics
The Kigali Amendment's HFC phase-down schedule is compressing refrigerant chemistry choices across manufacturing footprints, forcing platform redesigns before natural refrigerant supply chains mature.
Growth Catalysts
- Hyperscale Data Center Buildouts:Cloud computing operators in Singapore and Australia are procuring precision cooling units at volumes that justify dedicated production lines.
- EU F-Gas Regulation:Stepped GWP quotas are pulling forward replacement demand as distributors rush to secure lower-flammability equipment before import restrictions tighten.
- Inverter Compressor Maturation:Variable-speed drive costs have fallen below fixed-speed parity in mass production, eliminating the efficiency premium barrier.
Market Restraints
- Copper and Aluminum Input Volatility:Coil assembly costs fluctuate with London Metal Exchange pricing, compressing margin buffers for contract manufacturers.
- Refrigerant Supply Concentration:Fluorochemical precursor production clusters in Chinese chemical parks, exposing OEMs to export licensing delays.
- A2L Flammability Standards:IEC 60335-2-40 compliance requires redesigned electrical enclosures and ventilation protocols, extending qualification timelines.
Strategic Opportunities
- Indian Residential Retrofit:Urban middle-class households in Mumbai and Delhi are upgrading from evaporative coolers to split systems as grid reliability improves.
- Heat Pump Convergence:Reversible cycle architectures are capturing cooling-only replacement cycles in European markets with gas heating phase-outs.
- Direct-to-Installer Platforms:Digital procurement channels are disintermediating traditional HVAC wholesale distributors in North American residential segments.
Industry Challenges
- Refrigerant Handling Certification:Technician licensing requirements for mildly flammable A2L blends are creating installation bottlenecks in markets with aging contractor workforces.
- Legacy Control System Integration:Smart thermostat protocols lack standardization, forcing OEMs to maintain multiple communication stacks for building automation compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Conditioning Equipment Market |
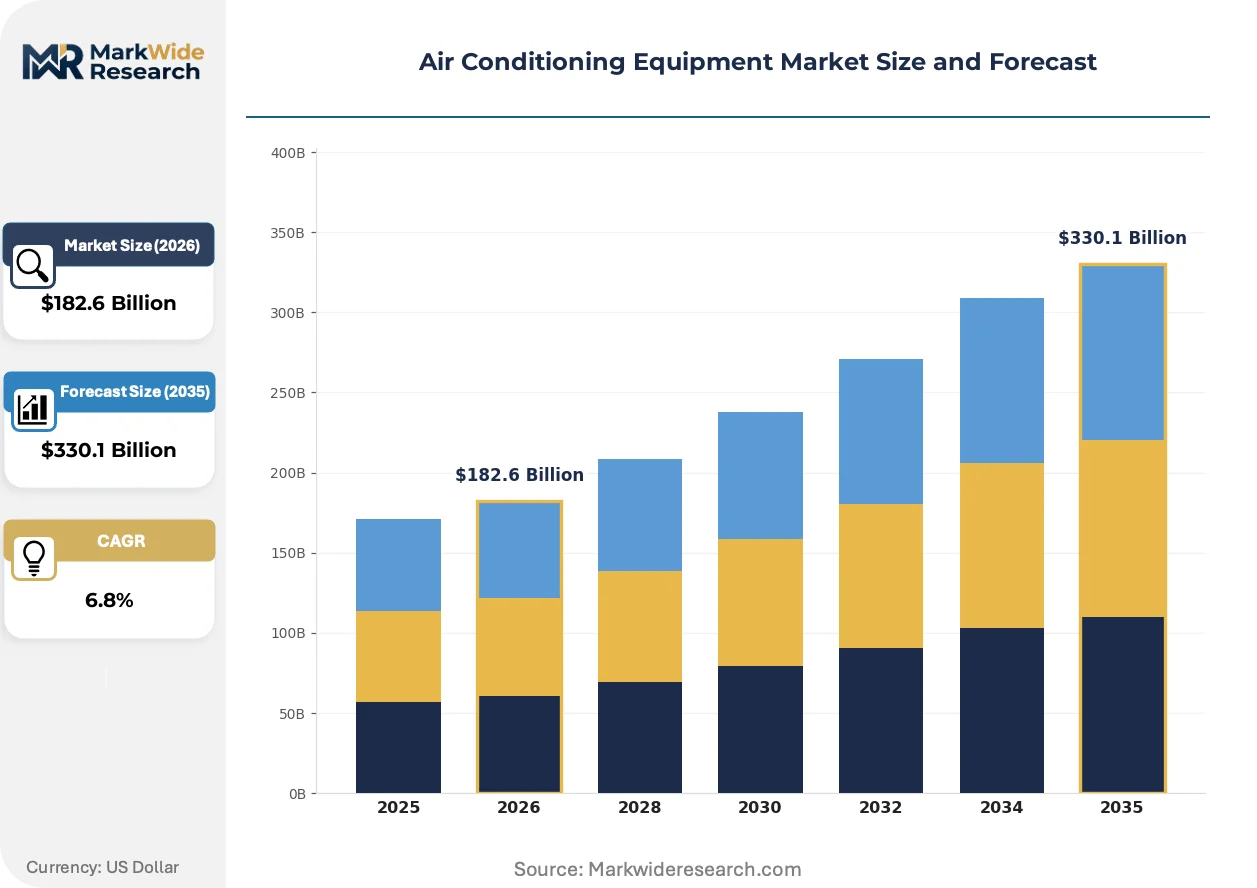
| Market Size in 2026 | $182.6 Billion |
| Market Size in 2035 | $330.1 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split System, Window Units, Portable Air Conditioners, Ductless Mini-Split Technology: Inverter, Traditional, Smart Thermostats, HVAC Control Systems End User: Residential, Commercial, Industrial, Hospitality Installation Type: Centralized, Rooftop, Self-Contained, Others |
| Companies Covered | Daikin Industries, Ltd., Carrier Global Corporation, Trane Technologies, Johnson Controls, Lennox International, Midea, Gree Electrical Appliances Inc., LG Electronics, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Conditioning Equipment Market Strategic Shifts
Software-defined thermal management is displacing hardware-centric product differentiation, while refrigerant chemistry transitions and channel restructuring compress traditional competitive moats.
Variable refrigerant flow systems are decomposing the conventional split-system category by enabling granular zone control without ductwork retrofit. Hospitality developers in Thailand and Vietnam are specifying VRF for new construction at rates that threaten centralized chiller specifications. The technology is decomposing margin pools away from traditional packaged rooftop units toward refrigerant distribution engineering services.
EPA Significant New Alternatives Policy determinations are disqualifying R-410A for new equipment submissions, compelling OEMs to validate R-454B or propane architectures. The industrial consequence is duplicated R&D expenditure across parallel refrigerant platforms during the transition window. Commercial rooftop manufacturers serving California Title 24 compliance markets are accelerating A2L qualification ahead of federal mandates.
Building owners are unbundling equipment procurement from installation and maintenance contracts, fragmenting vendor relationships that previously locked in decade-long service revenue. Mechanical contractors are responding by developing proprietary commissioning software to preserve attachment rates. This pattern is most visible in German commercial retrofit markets where energy performance contracting has separated capital and operational expenditure decisions.
Air Conditioning Equipment Market Segmentation
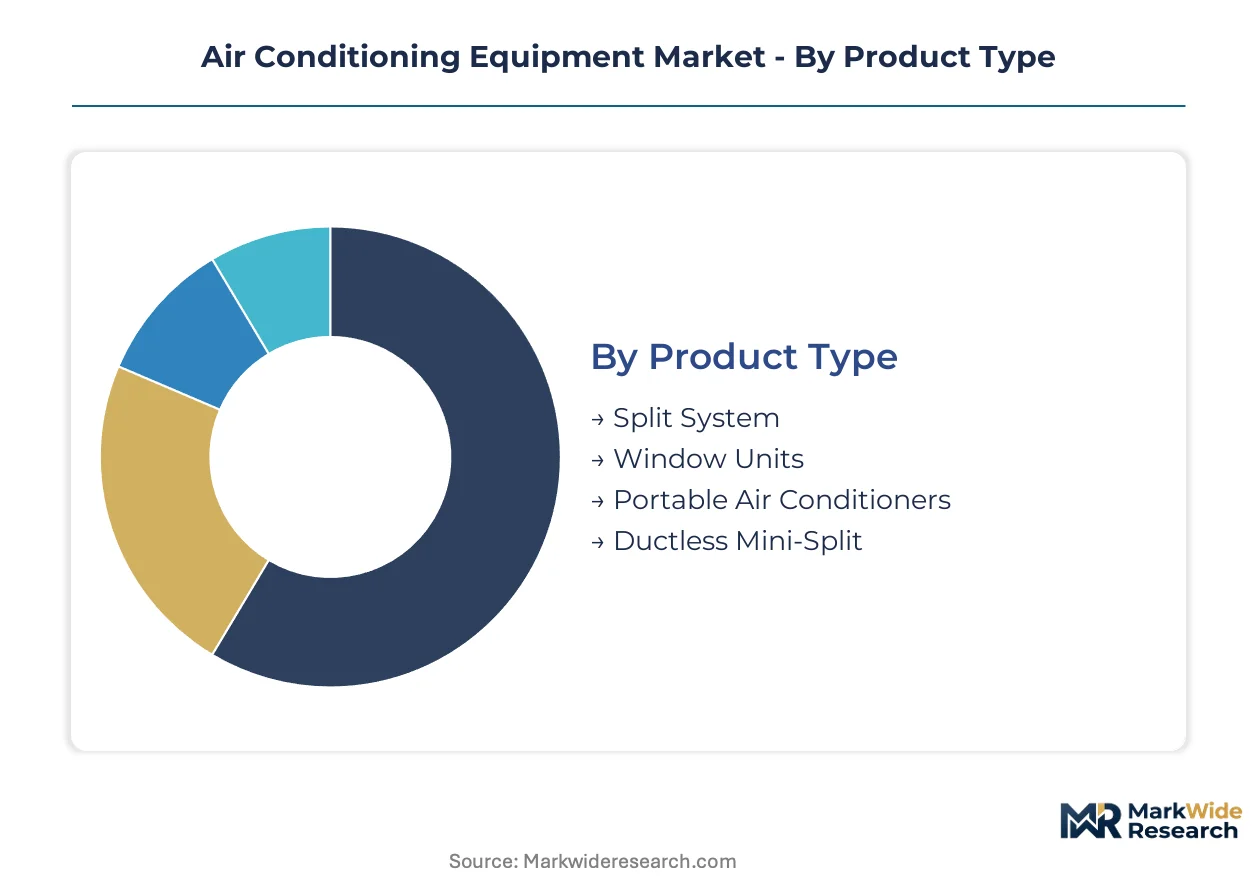
Segmentation in air conditioning equipment reveals how refrigerant chemistry transitions and installation complexity reshape channel economics. Product architecture determines whether units flow through retail DIY, mechanical contractor, or integrated project delivery channels.
Product Type:
Channel mix varies sharply by form factor: split systems and ductless mini-splits route through HVAC contractor networks requiring refrigerant handling certification, while window units and portables dominate big-box retail and e-commerce direct-to-consumer channels.
- Split System:Vapor-compression assemblies separate condensing and evaporating coils between outdoor and indoor enclosures, connected by refrigerant linesets. Demand concentrates in Indian and Indonesian residential new construction as urban middle-class households abandon evaporative cooling. The Kigali Amendment's HFC phase-down is accelerating R-32 adoption in these units.
- Ductless Mini-Split:Compact refrigerant distribution architectures enable multi-zone climate control without forced-air ductwork. Retrofit demand in Japanese and German existing building stock is displacing centralized boiler systems, particularly where gas heating phase-outs mandate reversible heat pump operation. These units command contractor-channel premiums for line-set installation and commissioning.
- Window Units:Self-contained through-wall assemblies with integrated compressors and coils. Mass-market penetration in North American rental housing and Southeast Asian urban apartments flows through retail and e-commerce channels with minimal installation service attachment.
- Portable Air Conditioners:Mobile units with exhaust hose ventilation for temporary cooling. Seasonal demand spikes in European and Australian markets without permanent installation infrastructure, sold predominantly through consumer electronics retailers.
By volume, split systems lead. By growth pace, ductless mini-split configurations are expanding most quickly.
Technology:
Cost tier stratification separates premium inverter and smart control platforms from economy traditional fixed-speed architectures, with mid-market convergence as variable-speed drive costs decline.
- Inverter:Variable-frequency drives modulate compressor speed against thermal load rather than cycling on-off. Regulatory mandates from California Title 24 and EU Ecodesign are collapsing demand for fixed-speed alternatives in premium replacement cycles.
- Smart Thermostats:Networked control interfaces enabling remote scheduling, occupancy sensing, and grid-responsive demand management. Hospitality developers in Singapore and Dubai are specifying these as standard for energy performance contracting separation of capital and operational expenditure.
- Traditional:Fixed-speed compressor cycling with electromechanical thermostatic control. Surviving in price-sensitive emerging market segments where electricity subsidies reduce efficiency payback calculus.
- HVAC Control Systems:Building automation integration for multi-unit commercial and industrial applications. Specification relationships with federal and institutional contractors in the US sustain incumbent vendor positions.
By installed base, traditional architectures dominate. By replacement velocity, inverter platforms are gaining share fastest.
End User:
Application-specific performance requirements create distinct margin pools: residential prioritizes first-cost and noise metrics, while commercial and industrial demand redundancy and precision control.
- Residential:Single-family and multi-family dwelling climate control. Indian grid reliability improvements are accelerating split-system adoption in Mumbai and Delhi middle-class households upgrading from evaporative coolers.
- Commercial:Office, retail, and institutional building climate management. EU F-Gas Regulation stepped quotas are pulling forward replacement demand as distributors rush to secure lower-flammability equipment before import restrictions tighten.
- Industrial:Process cooling and environmental control for manufacturing. Precision requirements in pharmaceutical and semiconductor cleanrooms sustain premium specification positions.
- Hospitality:Hotels, resorts, and food service climate control. Thai and Vietnamese developers are specifying variable refrigerant flow systems at rates threatening centralized chiller specifications in new construction.
By unit volume, residential leads. By specification value, commercial and hospitality segments show steepest expansion trajectory.
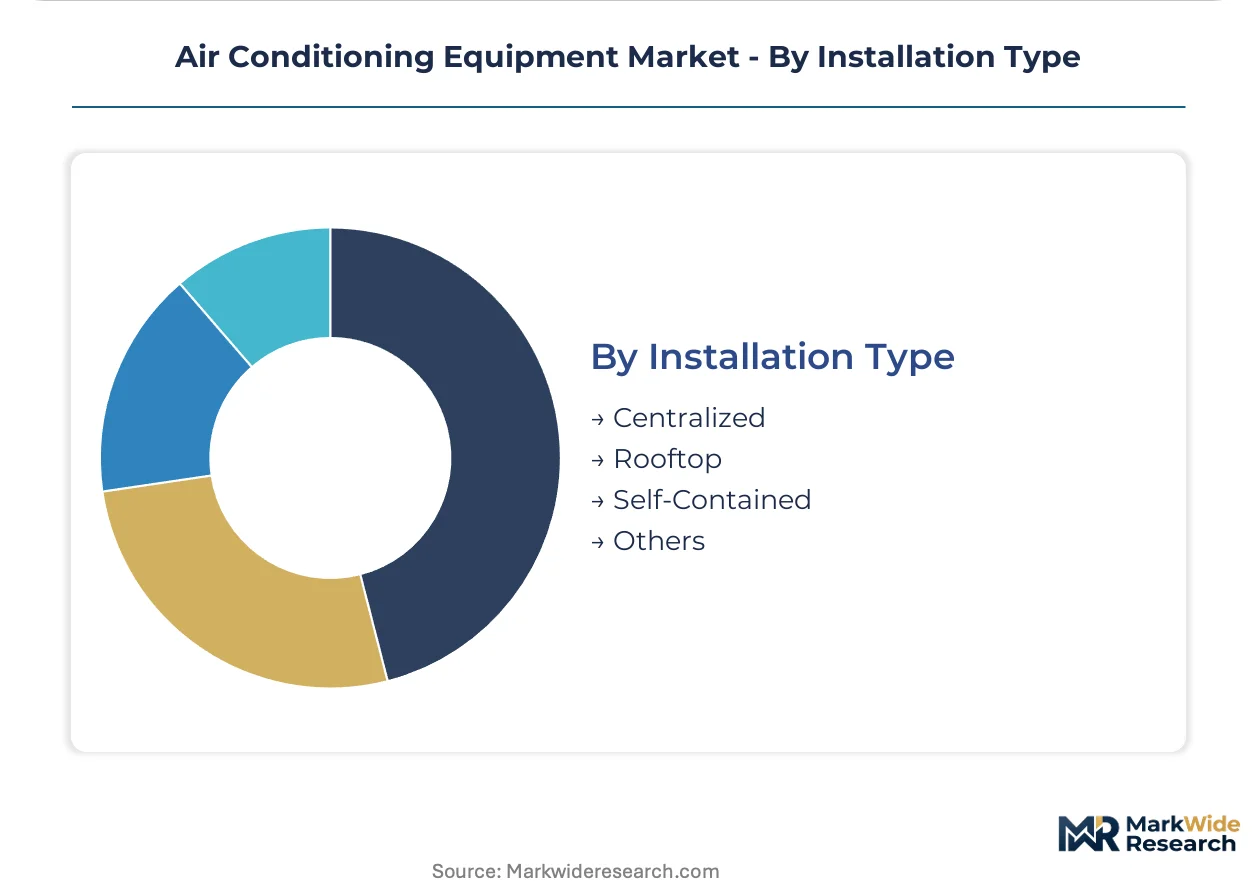
Installation Type:
Supply concentration clusters around coil and compressor manufacturing in Chinese chemical parks, with installation type determining logistics complexity and field labor requirements.
- Centralized:Chiller plants with distributed air handling for large commercial and institutional buildings. Deep specification relationships with federal contractors in the US sustain incumbent positions despite longer replacement cycles.
- Rooftop:Packaged units combining heating, cooling, and air distribution in weatherized enclosures. California Title 24 compliance markets are accelerating A2L refrigerant qualification ahead of federal mandates, compressing manufacturer R&D timelines.
- Self-Contained:Factory-charged units requiring only electrical and ventilation connections. Window and portable formats dominate this category with minimal contractor involvement.
- Others:Specialized configurations including split ductless, water-source heat pumps, and hybrid systems. Custom engineering services capture margin pools as building owners unbundle equipment procurement from installation contracts.
By current installed base, centralized systems lead. By retrofit activity, rooftop and self-contained formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in air conditioning equipment tilt toward manufacturing concentration in East Asian chemical parks, while regulatory divergence across major economies fragments product qualification requirements. Import dependency for fluorochemical precursors exposes OEMs to licensing volatility. Regional markets diverge sharply on refrigerant transition timelines and efficiency mandate enforcement.
China
Domestic demand for split-system replacements and data center precision cooling sustains factory utilization in Guangdong and Jiangsu provinces. MEE oversight of fluorochemical production quotas constrains HFC refrigerant availability for export markets. Zhuhai hosts integrated motor and coil manufacturing clusters serving mass-market window unit production.
United States
California Title 24 building efficiency standards accelerate SEER 16+ adoption in replacement cycles, collapsing demand for legacy fixed-speed compressors. EPA Significant New Alternatives Policy determinations restrict R-410A eligibility, compelling A2L refrigerant qualification. Federal building contractors in Washington D.C. and Texas sustain deep specification relationships with incumbent rooftop manufacturers.
Germany
EU F-Gas Regulation stepped GWP reduction quotas pull forward commercial replacement demand as distributors secure lower-flammability equipment ahead of import restrictions. Gas heating phase-outs in Berlin and Munich mandate reversible heat pump architectures in cooling-only replacement cycles. Bavaria-based mechanical contractors develop proprietary commissioning software to preserve service attachment rates.
India
Urban middle-class households in Mumbai and Delhi upgrade from evaporative coolers to split systems as grid reliability improves. BIS efficiency labeling programs accelerate inverter compressor adoption against fixed-speed alternatives. Tamil Nadu and Gujarat manufacturing corridors expand production capacity for residential new construction.
Japan
Retrofit demand in Tokyo and Osaka existing building stock displaces centralized boiler systems with ductless mini-split configurations. METI energy efficiency standards anchor premium positioning for domestic manufacturers. Nagoya industrial clusters maintain captive refrigerant chemistry pipelines supporting technology differentiation.
Air Conditioning Equipment Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized HVAC manufacturers competing across tiered efficiency segments. The vendor base separates into three archetypes: integrated refrigerant-to-equipment manufacturers, specification-driven institutional contractors, and mass-market scale producers. Dominant competitive moves include captive supply chain control over compressor and coil production, plus accelerated A2L refrigerant platform qualification ahead of regulatory deadlines.
Within the integrated conglomerate tier, Daikin Industries, Ltd. and Mitsubishi Electric Corporation represent Japanese manufacturers with in-house refrigerant chemistry capabilities. Carrier Global Corporation anchors the specification-driven institutional segment through federal contractor relationships. Gree Electrical Appliances Inc. exemplifies mass-market scale production with integrated component manufacturing in Zhuhai.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Carrier Global Corporation |
| Trane Technologies |
| Johnson Controls |
| Lennox International |
| Midea |
| Gree Electrical Appliances Inc. |
| LG Electronics |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
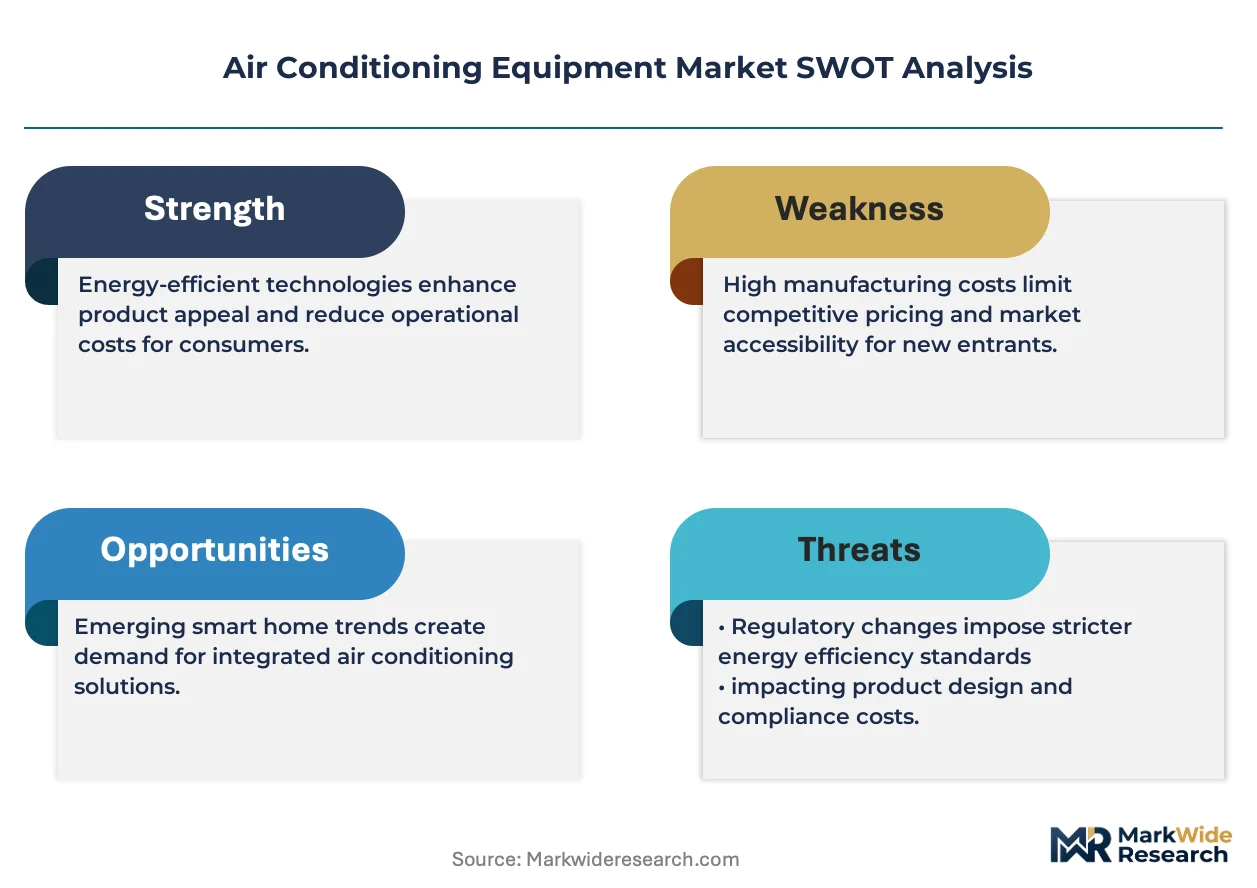
Factory utilization rates above 85 percent in Guangdong and Jiangsu coil assembly clusters compress marginal cost curves for compressor and heat exchanger production, anchoring price floors for mid-tier split systems while concentrating bargaining power among integrated manufacturers with captive refrigerant chemistry pipelines.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across premium SEER 20+ inverter platforms, standard SEER 16-18 mid-market units, and economy fixed-speed alternatives. Price differentiation rests on certification tier—California Title 24 compliance commands 15-25 percent premiums over federal baseline equipment—and after-sales service bundling through mechanical contractor channels. Cost compression in the economy tier is intensifying because copper and aluminum London Metal Exchange volatility erodes fixed-margin contracts. Residential replacement buyers in North America show highest price sensitivity, while data center precision cooling procurement teams prioritize redundancy specifications over first-cost.
Supply Chain Analysis
Strait of Malacca transit security underwrites fluorochemical precursor flows from Chinese chemical parks to Southeast Asian assembly plants. Geographic supply concentration centers on China for compressor motors and coil assemblies, Japan for variable-frequency drive inverters, and Germany for precision control electronics. Raw material dependencies draw from copper cathodes, aluminum billets, and HFC/HFO refrigerant blends. Single-source vulnerability in Chinese MEE-regulated fluorochemical quotas exposes OEMs to export licensing delays. Distribution runs through HVAC wholesale networks for contractor-channel products and direct-to-installer digital platforms for residential retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from reversible heat pump architectures capturing cooling-only replacement cycles as European gas heating phase-outs accelerate, requiring defensive repositioning around integrated thermal management platforms.
For Market Incumbents: Fortify captive refrigerant chemistry pipelines through backward integration into HFO precursor production or exclusive offtake agreements with Chinese chemical park operators. Accelerate A2L refrigerant platform qualification ahead of EPA SNAP determinations to collapse competitor R&D runway. Defensive capacity concentration in Tamil Nadu and Gujarat manufacturing corridors preserves cost position against emerging market entrants.
For New Entrants and Emerging Players: Differentiate on direct-to-installer digital procurement platforms disintermediating traditional HVAC wholesale channels in North American residential segments. Target Indian middle-class household retrofit demand in Mumbai and Delhi as grid reliability improvements accelerate split-system adoption from evaporative cooling baselines. White-space penetration runs through proprietary commissioning software preserving service attachment rates as building owners unbundle equipment from installation contracts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated refrigerant-to-equipment manufacturers with in-house compressor and coil production anchoring platform economics through refrigerant transition volatility. Long-term viability rests on qualification timelines for natural refrigerant architectures against HFC phase-down schedules. The signal to monitor is A2L technician certification bottlenecks constraining installation capacity in markets with aging contractor workforces.
| Strategic Initiative | Industry Significance |
|---|---|
| A2L Refrigerant Platform Qualification | EPA SNAP restrictions on R-410A compress manufacturer R&D timelines ahead of federal mandates. |
| Backward Integration into Coil Manufacturing | Guangdong and Jiangsu cluster control reduces copper price volatility exposure for mass-market production. |
| Direct-to-Installer Digital Platform Launch | Disintermediation of HVAC wholesale channels captures margin pools in North American residential retrofit. |
| VRF System Specification Relationships | Thai and Vietnamese hospitality developers threaten centralized chiller demand with zone-control alternatives. |
| Technician Certification Program Investment | A2L handling licensing bottlenecks constrain installation capacity in aging North American contractor bases. |
Study Parameters
The analysis maps split-system, ductless mini-split, window unit, and portable configurations, each validated through plant managers at coil and compressor facilities, procurement leads at OEM assembly operations, HVAC wholesale distribution heads, and aftermarket service technicians. Primary interview insights triangulate against customs and trade flow databases, SEC 10-K equipment segment disclosures, MEE fluorochemical production quota filings, and EU F-Gas Regulation compliance registries. Bottom-up unit shipment modeling cross-references top-down value estimates across product architecture, efficiency tier, and end-use application dimensions.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by product type, technology tier, end-user application, and installation complexity, with regional regulatory cluster as an overlay dimension. CAGRs derive from replacement cycle velocity, new construction penetration rates, and efficiency mandate enforcement timelines. Forecast inputs incorporate inverter compressor cost decline curves, refrigerant transition platform R&D expenditure patterns, and data center precision cooling procurement disclosures from hyperscale operators.
Material uncertainties—refrigerant chemistry transition delays, copper and aluminum commodity price spikes, and A2L technician certification bottlenecks—sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and supply chain licensing continuity. Practitioners should keep alternative scenarios live as Kigali Amendment phase-down schedules and EU F-Gas quota tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
India Chillers Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Global Industrial Fans and Blowers Market