
 Reverse Flame Steam Boiler Market | 2026-2036
Reverse Flame Steam Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Flame Steam Boiler Market Intelligence
The end-use application mix for reverse flame steam boilers is shifting from traditional textile manufacturing towards higher-value sectors like food processing and pharmaceuticals. Bosch Industriekessel GmbH leverages its engineering prowess to serve these demanding applications with high-efficiency systems. Spirax-Sarco Engineering differentiates through its comprehensive steam system management solutions, while ICI Caldaie S.p.A. specializes in compact, modular designs for small to medium enterprises.
A reverse flame steam boiler is a type of fire-tube boiler characterized by a three-pass heat exchange design. The flame reverses within a large-diameter, fully submerged furnace, maximizing thermal transfer before exhaust gases pass through the smoke tubes. Natural gas and biomass are displacing coal as the dominant fuel types due to emissions regulations. Within applications, the food processing segment represents the fastest-growing opportunity, driven by its need for consistent, high-quality steam for sterilization and cooking processes.
Market access and product design are heavily influenced by regional standards, including the European Union's CE marking for pressure equipment and China's GB standards for boiler efficiency. In the United States, EPA regulations on industrial emissions further shape boiler fuel choices and combustion technology. Future competitiveness depends on manufacturers' ability to integrate advanced digital controls and IoT connectivity for remote monitoring and predictive maintenance.
Market Dynamics
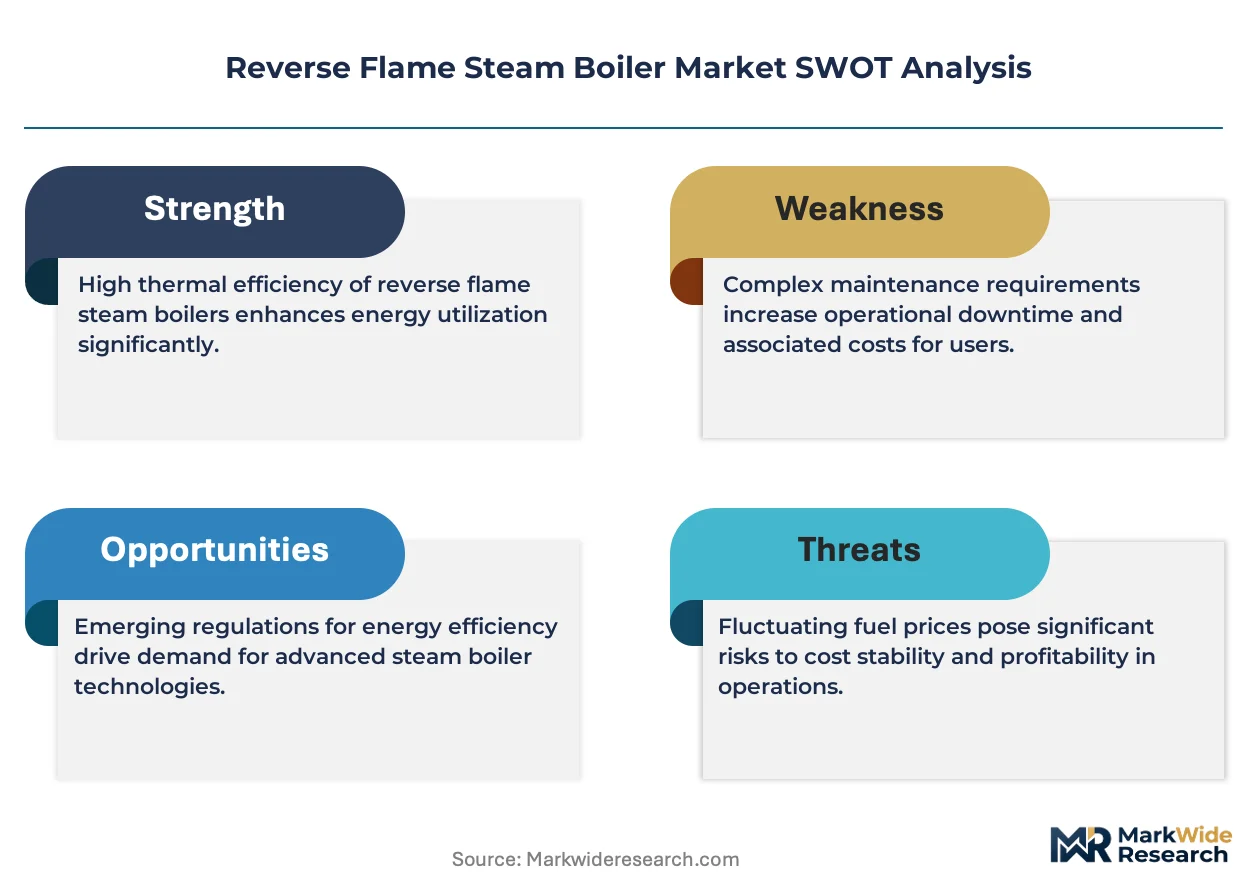
The push for industrial decarbonization, codified in regulations like the EU's Ecodesign Directive and China's GB standards, is the central force compelling a shift towards higher-efficiency, lower-emission reverse flame steam boilers across multiple manufacturing sectors.
Growth Catalysts
- Food Processing Demand:The global food and beverage industry requires consistent, high-purity steam for sterilization and cooking processes, driving the adoption of reliable and efficient reverse flame boilers.
- Efficiency Mandates:Stricter industrial boiler efficiency standards under frameworks like the EU's Ecodesign Directive are compelling operators across Europe to replace older, less efficient systems with modern technology.
- Industrialization in India:Rapid expansion of industrial clusters in India, particularly for textiles and food processing, creates significant greenfield demand for new boiler installations to support manufacturing growth.
Market Restraints
- High Capital Outlay:The significant upfront investment required for high-efficiency reverse flame boilers presents a substantial barrier for small and medium-sized enterprises with limited capital budgets.
- Electric Boiler Competition:In regions with decarbonized electricity grids and supportive policies, electric steam boilers are emerging as a viable, emissions-free alternative, challenging the market for combustion-based systems.
- Fuel Price Volatility:Fluctuations in the global prices of natural gas and biomass, the primary fuels for modern boilers, directly impact operational expenditure and create long-term cost uncertainty for end-users.
Strategic Opportunities
- Digital Service Integration:Integrating IoT sensors and advanced controls enables new revenue streams from predictive maintenance, remote monitoring, and performance optimization services, creating long-term customer relationships.
- Biomass Conversion Projects:A substantial opportunity exists to retrofit or replace aging coal-fired boilers in industrial facilities throughout Eastern Europe and parts of Asia with systems designed for biomass fuels.
- Southeast Asia Expansion:Underpenetrated markets in countries like Vietnam and Indonesia offer significant growth potential as their manufacturing sectors industrialize and require more advanced steam generation technology.
Industry Challenges
- Technician Skill Gaps:A shortage of technicians trained to install, operate, and service modern boilers featuring sophisticated digital control systems hinders optimal performance and reliability for end-users.
- Regulatory Fragmentation:Manufacturers face significant complexity in designing products that comply with a diverse array of regional codes, including CE marking in Europe, EPA rules in the US, and specific GB standards in China.
- Legacy System Integration:Integrating new, high-efficiency boilers into older industrial plants with existing, and sometimes outdated, steam piping and distribution networks can be technically challenging and costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Flame Steam Boiler Market |
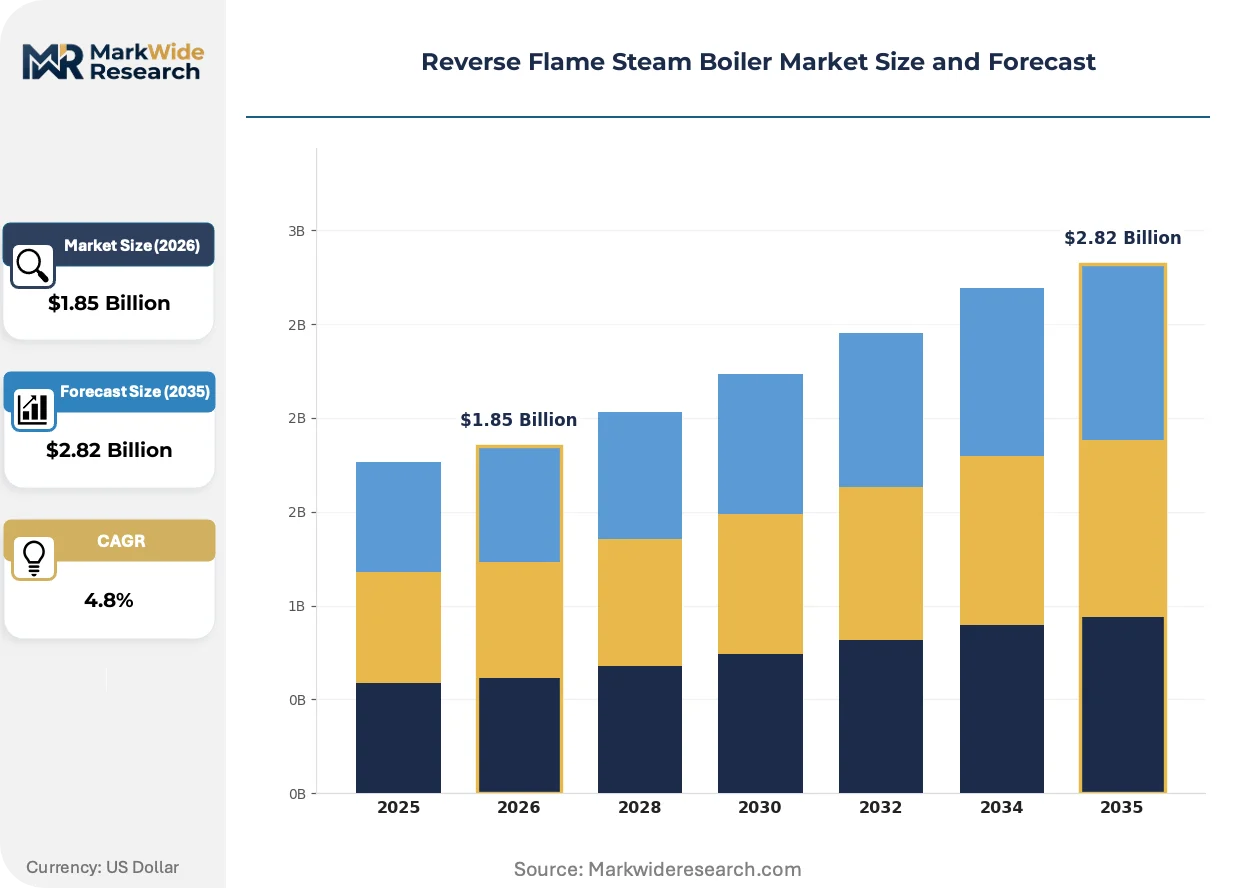
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Fire Tube, Water Tube, Electric Fuel Type: Coal, Biomass, Natural Gas, Oil, Electricity Application: Textile Manufacturing, Food Processing, Chemical Processing, Paper Production, Pharmaceuticals End User: Industrial Plants, Power Generation Units, Commercial Laundries, Processing Facilities, Institutional Buildings |
| Companies Covered | Atlantic Boilers, ATTSU, BoilerTech Pty Ltd, Bosch Industriekessel GmbH, Byworth Boilers, ICI Caldaie S.p.A, Spirax-Sarco Engineering, Viessmann Werke GmbH & Co. KG, Zhengzhou Boiler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Flame Steam Boiler Market Strategic Shifts & Innovations
The intersection of sustainability mandates and digitalization is fundamentally altering boiler design and operation. This evolution focuses on maximizing thermal efficiency and fuel flexibility while embedding intelligence directly into control systems for autonomous performance and predictive oversight.
Digital twin technology is being integrated into boiler control systems to model real-time performance and predict component wear. The pharmaceutical and food processing sectors are key adopters, demanding precise control over steam quality for validation-sensitive processes. This integration of predictive analytics is automating boiler tuning and fault detection, minimizing the need for constant manual oversight.
China's "dual carbon" goals and updated GB standards for boiler efficiency are accelerating the phase-out of inefficient, high-emission coal-fired units. This policy directly impacts heavy industrial sectors, forcing investment in cleaner gas-fired or advanced biomass combustion technologies. Boiler manufacturers are responding by optimizing designs specifically for natural gas to meet these stringent new performance and emissions benchmarks.
A shift towards "Steam-as-a-Service" contracts is gaining traction, particularly among large industrial users. This model transfers the responsibility for equipment uptime, fuel management, and maintenance from the end-user to a specialized service provider, converting a capital expense into a predictable operational cost. This trend is most visible in mature industrial markets in Western Europe, where companies seek to offload non-core operational risks.
Reverse Flame Steam Boiler Market Segmentation
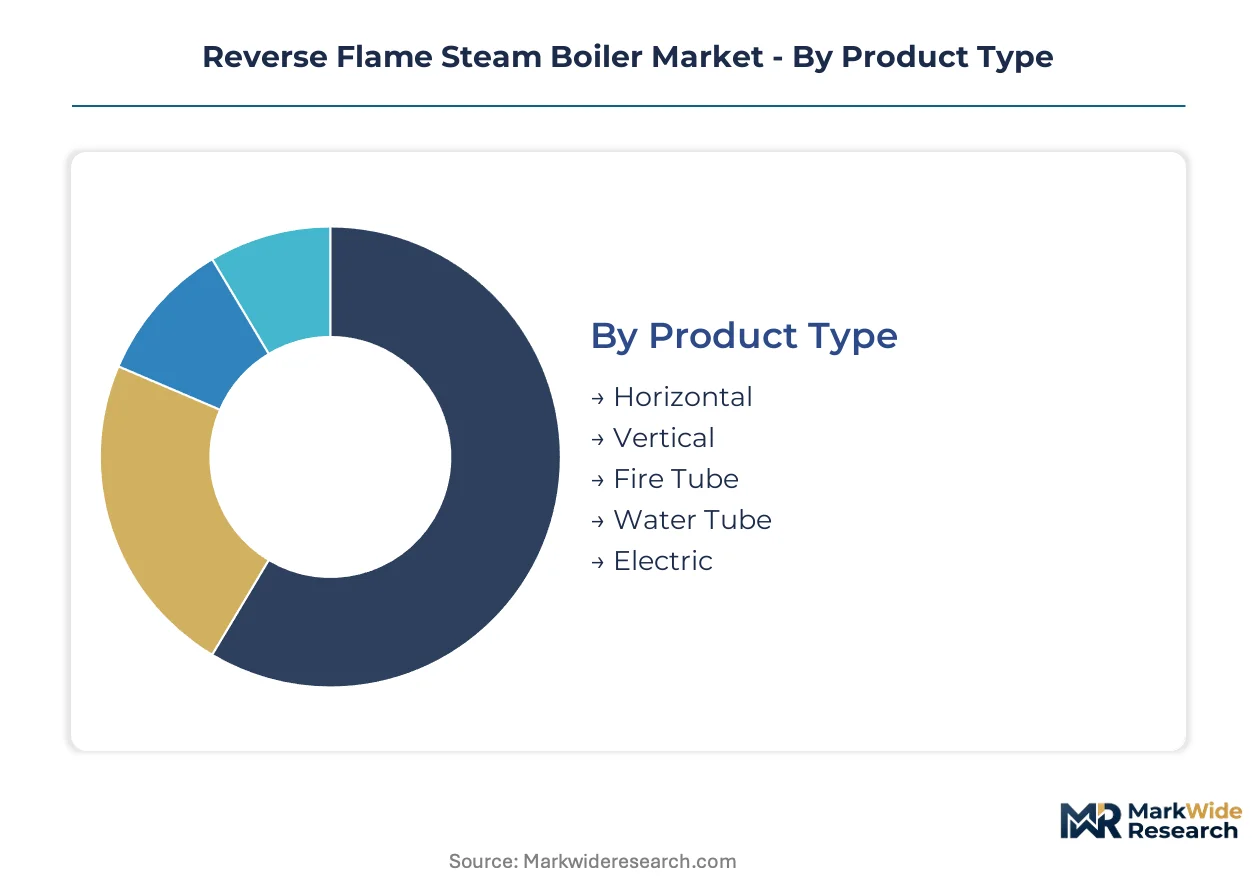
The Reverse Flame Steam Boiler market segmentation provides a granular view of demand drivers, technological preferences, and regulatory influences across diverse industrial landscapes. Understanding these distinct segments helps manufacturers tailor product offerings and navigate complex market access requirements for specialized applications.
Product Type:
The product type segmentation highlights the varied regulatory compliance pathways, from the EU's CE marking for pressure equipment to China's GB standards, that manufacturers must navigate for different boiler designs.
- Fire Tube:This design features combustion gases passing through tubes surrounded by water, maximizing heat transfer efficiency. Demand concentrates in sectors requiring robust, high-pressure steam, such as food processing and chemical manufacturing, driven by reliability needs.
- Electric:These boilers generate steam using electricity, offering zero on-site emissions and precise control, particularly appealing in regions with decarbonized grids. Growth is accelerating in pharmaceutical facilities and areas with stringent air quality regulations, where clean operation is paramount.
- Horizontal:These boilers feature a cylindrical shell with tubes running horizontally, offering a compact footprint and ease of maintenance for many industrial applications.
- Vertical:Vertical boilers are favored for their small installation area, making them suitable for sites with limited space, often found in smaller processing facilities.
- Water Tube:Water tube boilers circulate water through tubes surrounded by hot combustion gases, enabling higher pressures and capacities for large-scale industrial operations.
Fire Tube boilers sit at the top of the volume ranking, with Electric boilers climbing the fastest.
Fuel Type:
Fuel type segmentation reflects the diverse operational requirements and environmental mandates across industrial applications, influencing boiler selection.
- Natural Gas:This fuel type dominates new installations due to its cleaner combustion and high energy density, aligning with global decarbonization goals. Demand is strong across Europe and North America, driven by EPA regulations and the EU's Ecodesign Directive favoring lower emissions.
- Biomass:Biomass fuels offer a renewable energy source, supporting circular economy initiatives and reducing reliance on fossil fuels. Retrofit projects in Eastern Europe and India are driving its adoption, replacing older coal-fired systems under new emissions standards.
- Coal:Historically a primary fuel, coal use is declining due to stringent emission regulations and carbon pricing mechanisms, though it persists in some heavy industries in Asia.
- Oil:Oil-fired boilers provide flexibility and are often used as backup or in regions where natural gas infrastructure is limited, offering a reliable energy source.
- Electricity:Electric boilers are gaining traction in areas with abundant renewable electricity, providing an ultra-low emission solution for steam generation.
The shift towards Natural Gas is driven by emission reduction goals, while Biomass maintains its base in regions targeting circular economy initiatives.
Application:
Application segmentation reveals how different industrial volumes and process sensitivities dictate specific boiler configurations and steam quality demands.
- Food Processing:This segment requires consistent, high-purity steam for sterilization, cooking, and sanitation processes, making reliable boiler performance critical. The need for precise temperature control and hygiene standards drives investment in advanced reverse flame systems.
- Pharmaceuticals:Pharmaceutical manufacturing demands extremely high-quality, often sterile, steam for drug production, sterilization of equipment, and environmental control. This sector prioritizes precision, validation, and minimal contamination risk, impacting boiler design and material selection.
- Textile Manufacturing:Textile operations utilize steam for dyeing, drying, and finishing processes, requiring significant volumes of medium-pressure steam for efficient production.
- Chemical Processing:The chemical industry uses steam for heating reactors, distillation, and driving turbines, demanding boilers capable of handling corrosive environments and high thermal loads.
- Paper Production:Paper mills are energy-intensive, relying on steam for pulp digestion, drying, and power generation within integrated facilities.
High-purity steam requirements in Pharmaceuticals dictate specific boiler designs, distinguishing it from the volume demands of Textile Manufacturing.
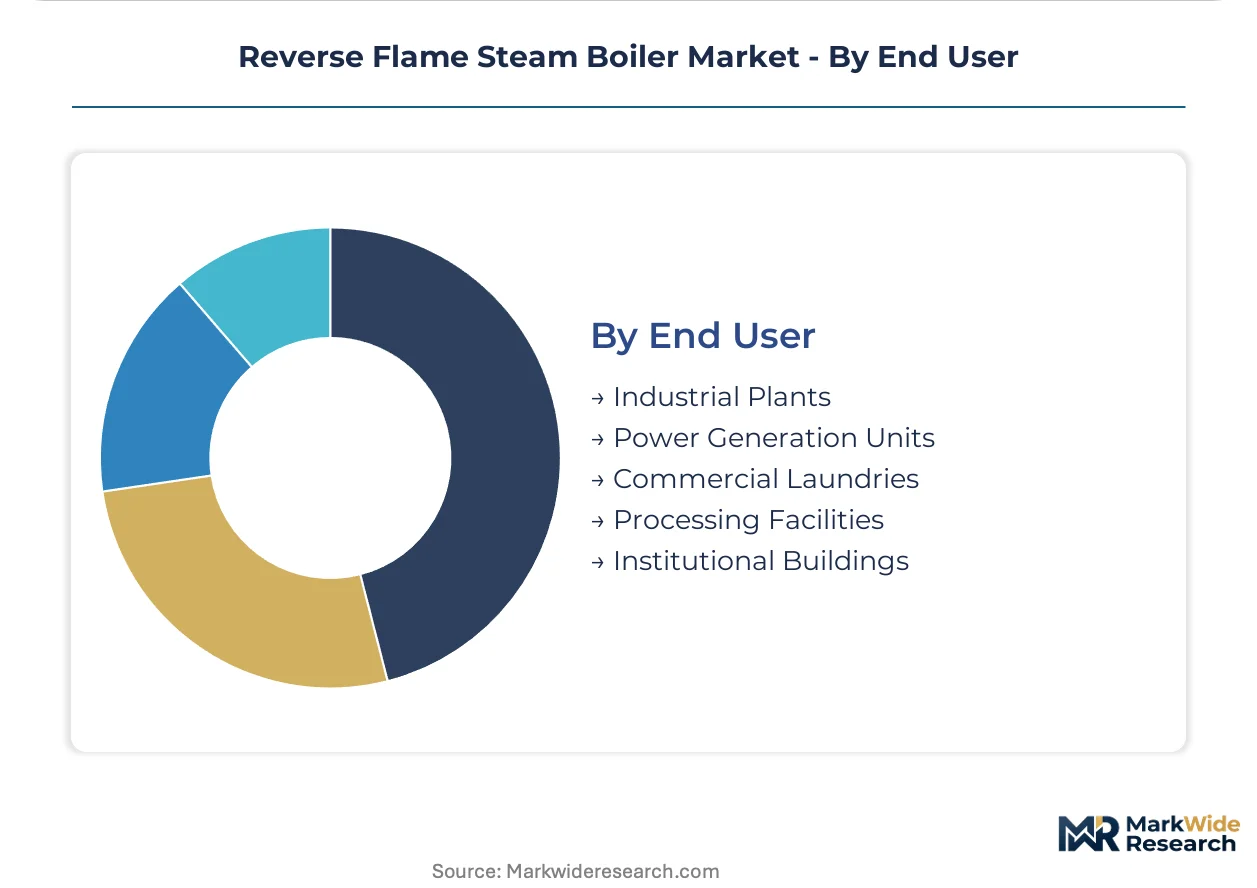
End User:
End user segmentation illustrates the varied maturity levels and investment profiles across sectors, influencing boiler technology adoption cycles.
- Industrial Plants:This broad category encompasses manufacturing facilities across diverse sectors, representing the largest end-user group for steam boilers. These plants prioritize efficiency, reliability, and compliance with local environmental regulations such as those from the EPA in the United States.
- Processing Facilities:These specialized facilities, particularly in food and beverage or chemical production, require boilers tailored for specific process steam needs. Investment decisions are often driven by product quality, safety, and operational uptime, demanding robust and precise systems.
- Power Generation Units:While primary power generation often uses larger utility boilers, smaller reverse flame units can support auxiliary processes or distributed generation in specific industrial contexts.
- Commercial Laundries:Laundries require consistent, high-temperature steam for washing and drying operations, often favoring compact and energy-efficient boiler solutions.
- Institutional Buildings:Hospitals, universities, and other large institutions use steam for heating, hot water, and sterilization, prioritizing safety, efficiency, and long-term operational costs.
While Industrial Plants represent a mature segment with established infrastructure, Commercial Laundries offer opportunities for specialized, smaller-scale solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial clusters within India represent a significant driver for reverse flame steam boiler adoption. Diverse regional demand across Europe, Asia, and North America necessitates localized product offerings and regulatory compliance. Decarbonization initiatives and industrial expansion shape boiler market trajectories across these key geographies.
India
Rapid expansion of industrial clusters in India, particularly for textiles and food processing, creates significant greenfield demand for new boiler installations. The country's Production Linked Incentive (PLI) schemes encourage domestic manufacturing, further stimulating industrial growth. Manufacturing hubs like Maharashtra and Gujarat require reliable steam generation for their expanding production capacities.
China
China's "dual carbon" goals and updated GB standards for boiler efficiency are accelerating the phase-out of inefficient coal-fired units. This policy directly impacts heavy industrial sectors, forcing investment in cleaner gas-fired or advanced biomass combustion technologies. The Yangtze River Delta region, a major industrial hub, is seeing substantial investment in modern, high-efficiency boiler systems.
Germany
Stricter industrial boiler efficiency standards under the EU's Ecodesign Directive compel operators across Germany to replace older, less efficient systems. Manufacturers like Bosch Industriekessel GmbH leverage engineering prowess to serve demanding applications such as food processing and pharmaceuticals. Industrial areas in North Rhine-Westphalia prioritize high-efficiency and low-emission steam generation for their advanced manufacturing base.
United States
Demand from industrial plants and processing facilities across the United States requires consistent, high-purity steam for various operations. EPA regulations on industrial emissions further shape boiler fuel choices and combustion technology in the country. The Gulf Coast region, with its extensive chemical processing and refining industries, seeks robust and compliant steam solutions.
Vietnam
Underpenetrated markets in countries like Vietnam offer significant growth potential as their manufacturing sectors industrialize. The government's focus on sustainable development encourages adoption of more advanced and environmentally friendly steam generation technology. Manufacturing zones around Ho Chi Minh City are increasingly investing in modern boiler systems to support export-oriented production.
Reverse Flame Steam Boiler Market Key Industry Players
Technology integration dominates the current landscape, with manufacturers focusing on advanced digital controls and IoT connectivity to enhance product offerings. The market exhibits a tiered structure, encompassing global specialists, regional providers, and niche solution providers. Strategic archetypes include high-efficiency system providers, comprehensive steam management solution developers, and compact design specialists. Geographic expansion into underpenetrated markets and portfolio diversification into biomass solutions represent key competitive moves.
Specialists in high-efficiency systems, such as Bosch Industriekessel GmbH, leverage engineering prowess to serve demanding applications. Spirax-Sarco Engineering exemplifies companies offering comprehensive steam system management solutions, integrating various components for optimized performance. ICI Caldaie S.p.A. occupies a position among manufacturers specializing in compact, modular designs tailored for small to medium enterprises.
| Leading Market Players |
|---|
| Atlantic Boilers |
| ATTSU |
| BoilerTech Pty Ltd |
| Bosch Industriekessel GmbH |
| Byworth Boilers |
| ICI Caldaie S.p.A |
| Spirax-Sarco Engineering |
| Viessmann Werke GmbH & Co. KG |
| Zhengzhou Boiler |
| Others |
Cost & Logistics Intelligence
Stricter industrial boiler efficiency standards, such as the EU's Ecodesign Directive, compel manufacturers to invest in advanced designs, which translates into higher production costs and impacts end-user pricing.
Pricing Analysis
Fluctuations in natural gas and biomass prices directly impact the operational expenditure of reverse flame steam boilers, influencing the final purchase price. Project-based pricing dominates the market, reflecting the customized nature of industrial installations. Price differentiation stems from the level of customization required for specific industrial processes and the comprehensiveness of integrated after-sales service packages. Pricing pressure stems from the increasing competitive viability of electric boiler alternatives in regions with decarbonized grids. Small and medium-sized enterprises exhibit the highest price sensitivity, while pharmaceutical manufacturers prioritize precision and validation over initial capital outlay.
Supply Chain Analysis
Component supply for high-efficiency reverse flame boilers largely draws from specialized manufacturers in Germany, Italy, and China for critical pressure vessel components and advanced control systems. Raw material dependencies include specialized steel alloys for pressure parts and sophisticated electronic components for digital controls. A key structural risk is single-source vulnerability for highly specialized burner technologies. Distribution primarily runs through a direct sales model, supplemented by a network of specialized distributors and engineering procurement construction firms for complex industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Reverse Flame Steam Boiler market functions as a late-cycle quality story, driven by a demand shift towards premium specifications for high-purity steam in pharmaceutical applications.
For Market Incumbents:
Anchor existing market share by investing in advanced digital controls and IoT connectivity to enhance predictive maintenance service offerings. Secure long-term contracts with key industrial clients in food processing to mitigate competitive electric boiler threats. Focus R&D efforts on increasing fuel flexibility for biomass and hydrogen co-firing solutions. Invest in certification upgrades to meet evolving global efficiency and emissions standards, such as China's GB standards.
For New Entrants and Emerging Players:
Enter via underpenetrated markets in Southeast Asia, focusing on countries like Vietnam and Indonesia with rapidly industrializing manufacturing sectors. Target small to medium enterprises with compact, modular boiler designs that offer lower capital outlay. Develop a "Steam-as-a-Service" model to convert capital expenditure into predictable operational costs for customers. Emphasize localized support and rapid deployment capabilities to address regional infrastructure challenges.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized mid-cap manufacturers proficient in advanced biomass combustion technologies and digital service integration. The long-term viability of the market is underpinned by global decarbonization and efficiency mandates. Target companies with strong intellectual property in modular designs or proprietary control systems that enable remote monitoring. Acceleration of industrial decarbonization policies in emerging markets serves as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Bolsters supply capabilities to meet growing industrial demand in India and other emerging economies. |
| Digital Service Integration | Creates recurring revenue streams through remote monitoring and predictive maintenance for end-users. |
| Biomass Conversion Technology | Addresses regulatory pressure for lower emissions in Eastern Europe and parts of Asia. |
| Modular Design Development | Caters to space-constrained small to medium enterprises in developing markets. |
| Strategic Partnerships | Expands market access and localized support for complex installations in China and the United States. |
Research Approach
Multiple input streams — primary interviews with plant engineers, procurement managers, and R&D directors, alongside secondary validation from regulatory filings and industry association reports — were reconciled for this market analysis. Stakeholder insights from boiler manufacturers, service providers, and industrial end-users were integrated. Bottom-up market sizing and top-down validation ensured data accuracy across the value chain, drawing from customs data and EPA reports.
Historical market performance was cross-referenced with expert panel input to construct a robust analytical framework across the projection horizon. Segmentation dimensions modeled included product type, fuel type, application, end-user, and regional policy frameworks. Compound Annual Growth Rates were derived from an assessment of demand drivers, technology adoption curves, and regulatory impacts. Key industry-specific forecast inputs included industrialization rates in emerging economies and global decarbonization targets.
Inputs from boiler manufacturers and industrial end-users were available through the study window; gaps in comprehensive global emissions data introduce uncertainty bands. Forecasts reflect assumptions regarding fuel price stability and technological advancements, particularly in digital controls. Geopolitical events impacting energy supply or shifts in industrial policy could revise projections. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Water Saving Shower Heads Market