
 Hydronic Control Market | 2026-2036
Hydronic Control Market Size, Share, and Industry Trends Forecast 2026-2036
Hydronic Control Market Intelligence
The proliferation of energy-as-a-service (EaaS) financing for building retrofits is fragmenting the traditional sales model for hydronic systems. Siemens Aktiengesellschaft leverages its building automation platforms to capture these performance-based contracts. Danfoss A/S specializes in high-efficiency components like control valves and actuators, supplying both retrofit and new build projects. Meanwhile, Belimo International AG differentiates through its expertise in actuator technology and strong relationships with HVAC contractors.
Hydronic controls are systems that manage the flow, pressure, and temperature of water or other fluids in heating and cooling circuits. These systems utilize components to precisely regulate energy transfer, optimizing comfort and minimizing consumption in buildings. Within the technology landscape, digital controls with wireless capabilities are rapidly displacing legacy pneumatic and mechanical controls. Demand for sophisticated actuators and smart control valves continues to grow as they are integral to achieving higher efficiency ratings.
The EU's Energy Performance of Buildings Directive (EPBD) and F-Gas Regulation create stringent requirements for system efficiency. In the United States, EPA guidelines and state-level building codes influence component selection, while ISO 50001 provides a global framework for energy management. Stakeholders must now decide how to invest in interoperable smart technologies while ensuring backward compatibility with existing building infrastructure.
Market Dynamics
The central dynamic shaping the hydronic control market is the push for building decarbonization, driven by stringent energy performance regulations. This force compels an industry-wide migration from analog, standalone components to digitally integrated, network-aware systems for optimized energy use.
Growth Catalysts
- Data Center Expansion:The construction of new hyperscale data centers requires precise and reliable liquid cooling systems, creating substantial demand for advanced hydronic controls to manage thermal loads and ensure operational uptime.
- Regulatory Mandates:The European Union's Green Deal and its associated building directives compel upgrades to energy-inefficient HVAC systems, creating a non-discretionary replacement cycle for older hydronic components in commercial and public buildings.
- New Construction Standards:Advanced building codes in markets like Germany and the United States specify high-efficiency hydronic systems for new commercial projects, making smart valves, sensors, and automated controls a default requirement.
Market Restraints
- High Upfront Cost:The initial capital expenditure for advanced digital and smart hydronic control systems is significantly higher than for traditional mechanical or pneumatic controls, deterring cost-sensitive building owners from undertaking retrofits.
- Integration with Legacy Systems:A large installed base of older buildings with aging, non-standardized infrastructure presents significant technical hurdles for integrating modern, IP-based hydronic controls, increasing project complexity and cost.
- Skilled Labor Scarcity:A shortage of HVAC technicians and system integrators with the requisite expertise in digital controls, networking, and building automation software hinders the effective deployment and commissioning of sophisticated systems.
Strategic Opportunities
- Energy-as-a-Service (EaaS) Models:Offering hydronic controls as part of a performance-based EaaS contract allows building owners to upgrade systems with minimal upfront capital, paying for guaranteed energy savings over time.
- Retrofit Market in Public Buildings:Government initiatives to improve the energy efficiency of public assets like schools, hospitals, and municipal offices create a large, accessible market for hydronic control upgrades and retrofits.
- IoT and AI Integration:Developing controls that integrate seamlessly with building-wide IoT platforms and leverage AI for predictive maintenance and autonomous optimization opens new value streams beyond basic temperature regulation.
Industry Challenges
- Interoperability and Standardization:The lack of a universal communication protocol across different manufacturers' devices complicates system design and creates vendor lock-in, frustrating efforts to build cohesive, best-of-breed building automation systems.
- Cybersecurity Vulnerabilities:As hydronic controls become more connected to building networks and the internet, they represent a potential attack vector, requiring robust cybersecurity measures to protect critical building operations from threats.
- Component Supply Chain Constraints:The reliance on specialized semiconductors and electronic components for smart actuators and controllers exposes manufacturers to supply chain disruptions and price volatility, impacting production schedules and product availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydronic Control Market |
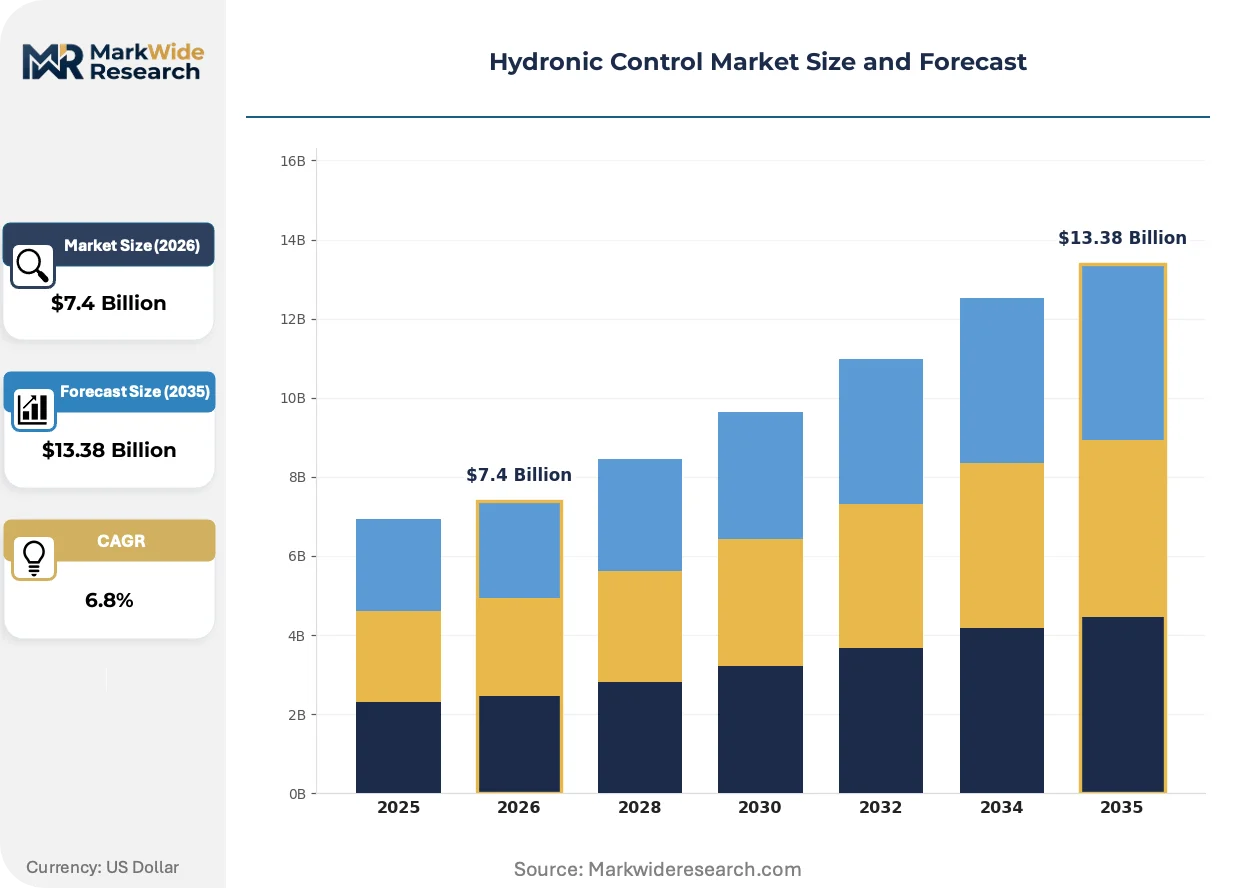
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Controllers, Flow Meters, Actuators, Control Valves, Thermostats Technology: Digital Controls, Pneumatic Controls, Electronic Controls, Mechanical Controls, Wireless Controls, Manual Controls Application: Commercial Buildings, Industrial Facilities, Educational Institutes, Government Complexes, Hospitality Venues, Data Centers End User: Building Management, Facility Managers, HVAC Contractors, Energy Service Companies, System Integrators, Maintenance Providers |
| Companies Covered | Danfoss A/S, Belimo International AG, Siemens Aktiengesellschaft, Xylem Inc., Emerson Electric Co., Johnson Controls International plc, Schneider Electric SE, Watts Water Technologies Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydronic Control Market Strategic Shifts & Innovations
The evolution of hydronic controls is defined by the convergence of operational technology with information technology. This integration is enabling a shift from reactive, manual adjustments to predictive, data-driven automation that optimizes building performance and energy consumption in real time.
Digital twin technology creates a dynamic, virtual replica of a building's complete hydronic circuit for simulation and analysis. Facility managers in large commercial and institutional buildings are adopting this to model energy usage and test control strategies without impacting physical operations. This technology is virtualizing system commissioning and performance diagnostics, enabling remote optimization and reducing the need for costly onsite interventions.
Europe's F-Gas Regulation imposes strict limits on the use of hydrofluorocarbons, prompting a shift toward heating and cooling systems that use natural refrigerants or water. This directly benefits the hydronic control market by necessitating new or upgraded systems that can manage these alternative fluids effectively. The commercial refrigeration and heat pump sectors are most impacted, driving demand for specialized control valves and sensors compatible with substances like CO2 or ammonia.
A transition from one-time equipment purchases to subscription-based access to managed services is altering the market's commercial model. This approach unbundles hardware from ongoing optimization services, allowing system integrators and specialized service providers to offer continuous commissioning and energy management. This trend is most prominent in the United States' commercial real estate sector, where building owners prioritize operational outcomes and predictable costs over capital ownership.
Hydronic Control Market Segmentation
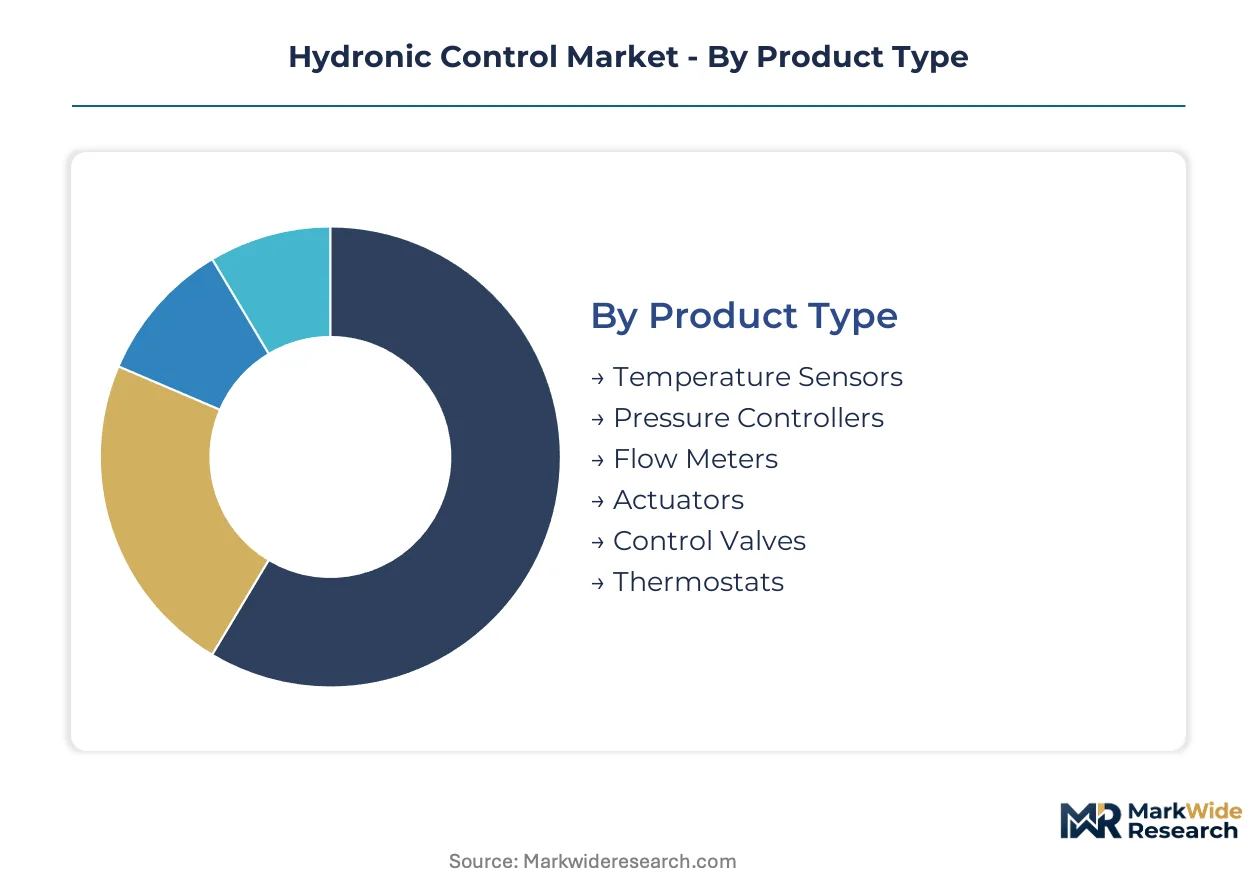
The hydronic control market segmentation illuminates the diverse requirements and technological preferences driving investment across various building types and operational models. Understanding these distinct segments allows stakeholders to tailor product development and service offerings for optimal market penetration and sustained growth.
Product Type:
The after-sales-service intensity varies significantly across hydronic control product types, influencing overall lifecycle costs and maintenance requirements for building operators.
- Actuators:These electromechanical or pneumatic devices convert control signals into mechanical motion, precisely positioning valves or dampers to regulate fluid flow. Demand for advanced actuators is concentrating in new commercial construction projects in Germany, driven by stringent energy performance standards.
- Control Valves:Designed to modulate or shut off fluid flow in hydronic systems, these components are critical for maintaining desired temperatures and pressures. Europe's Green Deal mandates are accelerating the replacement of older control valves in public buildings, particularly in France and Italy.
- Temperature Sensors:These devices measure fluid temperature, providing essential data for control systems to maintain setpoints and optimize energy use.
- Pressure Controllers:Components that manage and stabilize fluid pressure within hydronic circuits, preventing system overloads and ensuring efficient operation.
- Flow Meters:Instruments that measure the rate of fluid flow, enabling precise energy accounting and system balancing in large commercial facilities.
- Thermostats:User interfaces that allow occupants to set desired temperature levels, sending signals to the central control system.
By volume, control valves lead. By growth pace, actuators represent the fastest-growing trajectory.
Technology:
The cost tier associated with different hydronic control technologies significantly impacts adoption rates, particularly for retrofit projects where budget constraints are common.
- Digital Controls:These microprocessor-based systems offer advanced programmability, data logging, and network connectivity for comprehensive building automation. Demand for digital controls is concentrated in new data center construction in the United States, prioritizing real-time optimization.
- Wireless Controls:Utilizing radio frequency communication, these systems reduce installation complexity and offer flexible deployment in existing building infrastructure. European Union mandates for energy efficiency in commercial buildings are driving adoption of wireless solutions for non-invasive upgrades.
- Pneumatic Controls:Operating on compressed air, these legacy systems provide robust and reliable control in industrial settings, though they lack digital integration capabilities.
- Electronic Controls:Analog or early digital systems that use electrical signals for control, offering more precision than mechanical but less flexibility than modern digital.
- Mechanical Controls:Simple, non-electric devices that rely on physical principles like thermal expansion to regulate flow or temperature.
- Manual Controls:Basic, human-operated valves and switches that require direct intervention for system adjustments.
Integration complexity differentiates demand across these technology types.
Application:
The volume of hydronic control systems deployed varies considerably across application segments, reflecting building size, operational complexity, and regulatory compliance needs.
- Data Centers:These facilities require ultra-precise liquid cooling systems to manage high thermal loads, making advanced hydronic controls indispensable for uptime and energy efficiency. Hyperscale data center expansion in Ireland and the Netherlands is creating substantial demand for these specialized systems.
- Commercial Buildings:Office complexes, retail centers, and mixed-use developments represent a large installed base for hydronic heating and cooling systems, driven by occupant comfort and energy performance mandates. The EU's Energy Performance of Buildings Directive compels upgrades in commercial properties across Germany and France.
- Industrial Facilities:Manufacturing plants and processing facilities utilize hydronic systems for process heating, cooling, and climate control in production areas.
- Educational Institutes:Schools and universities implement hydronic controls to manage HVAC systems, balancing comfort with energy conservation mandates.
- Government Complexes:Public administration buildings require efficient hydronic systems to meet sustainability goals and reduce operational costs.
- Hospitality Venues:Hotels and resorts use hydronic controls for guest comfort and central plant efficiency, often integrating with property management systems.
Efficiency gains drive investment across all application segments.
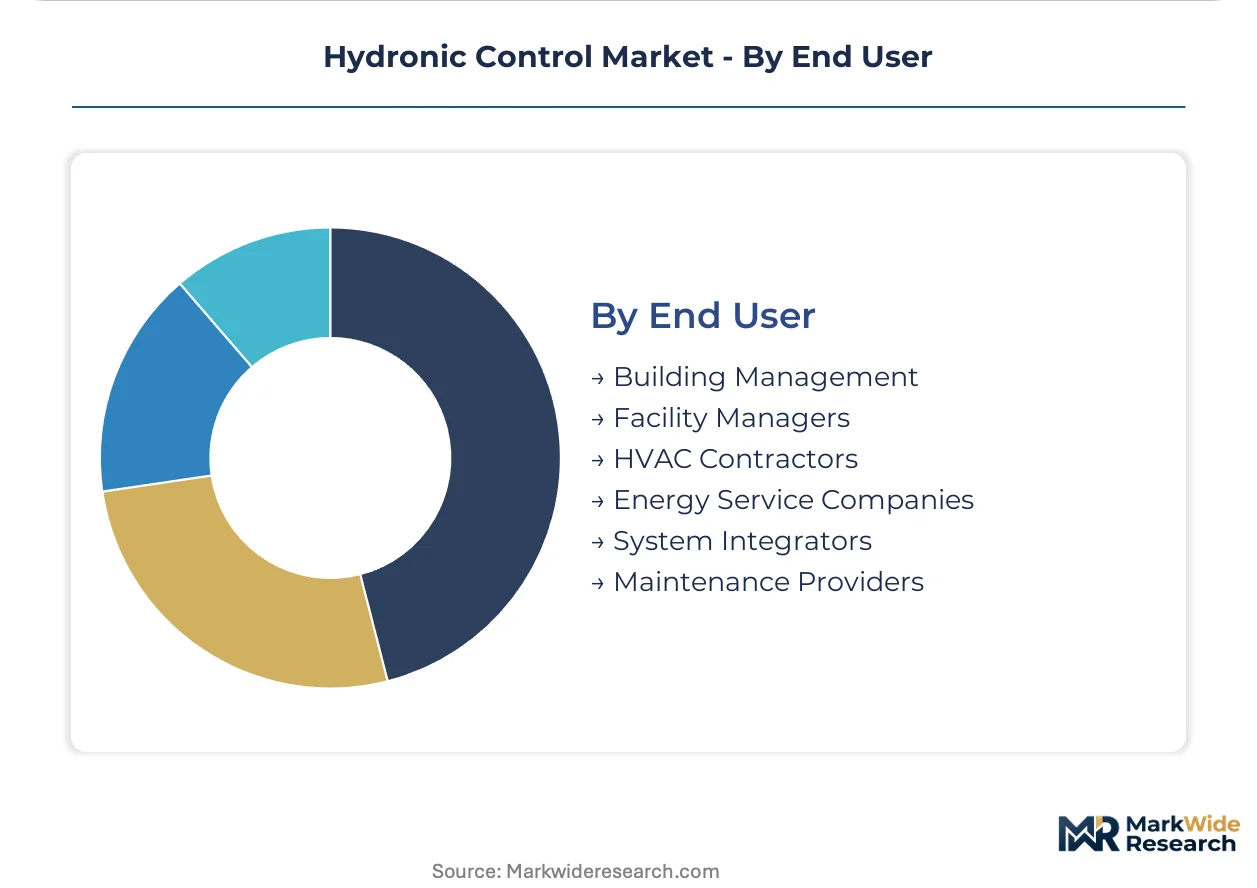
End User:
The customer type for hydronic controls defines the sales channels and support structures required, ranging from direct procurement to service-based partnerships.
- HVAC Contractors:These professionals are responsible for the installation, commissioning, and maintenance of hydronic control systems in new construction and retrofit projects. Belimo International AG maintains strong relationships with HVAC contractors globally.
- Energy Service Companies:ESCOs offer comprehensive energy management solutions, often including hydronic control upgrades as part of performance-based contracts. Siemens Aktiengesellschaft leverages its platforms to capture these EaaS opportunities in the United States.
- Building Management:Property owners and facility managers make strategic decisions regarding system upgrades and ongoing operational efficiency.
- Facility Managers:On-site personnel responsible for the daily operation, maintenance, and optimization of building systems, including hydronic controls.
- System Integrators:Specialists who combine various building technologies, including hydronic controls, into a unified and interoperable automation platform.
- Maintenance Providers:Companies that offer routine servicing and emergency repairs for hydronic systems, ensuring their continued performance.
Long-term partnerships are critical for market penetration within these end-user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The push for building decarbonization and stringent energy performance regulations are significantly influencing the hydronic control market across diverse geographies. European Union mandates, such as the Green Deal, compel widespread upgrades to energy-inefficient HVAC systems. This creates a non-discretionary replacement cycle for older components in commercial and public buildings, particularly in developed economies.
Germany
Demand for advanced actuators is concentrating in new commercial construction projects across Germany, driven by stringent energy performance standards. The EU's Energy Performance of Buildings Directive (EPBD) compels high-efficiency system installations. Major construction hubs like Berlin and Munich are seeing increased deployment of smart hydronic controls for optimized energy use.
United States
New construction standards in the United States specify high-efficiency hydronic systems for commercial projects, making smart valves and automated controls a default requirement. EPA guidelines and state-level building codes influence component selection for energy efficiency. Hyperscale data center expansion in states like Virginia and Texas creates substantial demand for precise liquid cooling systems.
Ireland
Hyperscale data center expansion in Ireland is creating substantial demand for specialized hydronic control systems to manage thermal loads. The EU's F-Gas Regulation and Green Deal mandates require efficient cooling solutions. Data center clusters around Dublin and Cork are driving investment in advanced digital controls for operational uptime.
France
Replacement of older control valves in public buildings is accelerating across France due to the EU's Green Deal mandates and EPBD. Government initiatives to improve the energy efficiency of public assets create a large, accessible market. Public sector retrofits in cities like Paris and Lyon prioritize modern, high-efficiency hydronic components.
China
Rapid industrial and commercial building growth in China drives demand for hydronic controls to manage large-scale heating and cooling systems. The country's dual carbon goals promote energy efficiency across new and existing infrastructure. Major urban centers like Shanghai and Shenzhen are implementing advanced building management systems for optimized energy consumption.
Hydronic Control Market Key Industry Players
Channel-controlling players compete with product-specialist players across the hydronic control market, creating a tiered competitive environment. The market exhibits a blend of large, diversified industrial conglomerates and specialized component manufacturers. Strategic archetypes include integrated solution providers, high-efficiency component specialists, and technology-focused innovators. Dominant competitive moves include strategic partnerships to expand solution offerings and portfolio diversification into smart building technologies.
Specialists in actuator technology and strong relationships with HVAC contractors include Belimo International AG. Within the integrated solution provider tier, Siemens Aktiengesellschaft leverages its building automation platforms to capture performance-based contracts. Danfoss A/S exemplifies a high-efficiency component specialist, supplying both retrofit and new build projects with control valves and actuators.
| Leading Market Players |
|---|
| Danfoss A/S |
| Belimo International AG |
| Siemens Aktiengesellschaft |
| Xylem Inc. |
| Emerson Electric Co. |
| Johnson Controls International plc |
| Schneider Electric SE |
| Watts Water Technologies Inc. |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Component supply chain constraints, particularly for specialized semiconductors, directly determine pricing tier spreads and the geographic shape of hydronic control system manufacturing. This volatility influences both product availability and cost structures across the market.
Pricing Analysis
Certification level, such as ISO 50001 compliance and EU Green Deal mandates, creates the primary spread in hydronic control system pricing. The market predominantly uses a project-based pricing model for integrated systems, with transactional sales for individual components. Price differentiation stems from high-efficiency ratings, digital integration capabilities, and established brand premiums. Pricing pressure often stems from cost-sensitive building owners undertaking retrofits, while hyperscale data centers prioritize performance over initial capital expenditure, exhibiting lower price sensitivity.
Supply Chain Analysis
Export-control regimes on critical electronic components, particularly from East Asian manufacturing hubs, influence the hydronic control supply chain. Manufacturing of advanced components concentrates in Germany for precision engineering and China for electronic sub-assemblies. The supply chain relies on specialized semiconductors and precision-machined metals. Single-source vulnerability for specific smart valve controllers represents a structural risk. Distribution runs primarily through HVAC contractors, energy service companies, and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydronic control market is experiencing a buyer-power shift, driven by the proliferation of Energy-as-a-Service (EaaS) models that reduce upfront capital expenditure for building owners. Hyperscale data center operators also consolidate significant purchasing influence for advanced systems.
For Market Incumbents: Insulate core market share by investing in interoperable smart building platforms to counter integration complexity from legacy systems. Expand Energy-as-a-Service models to capture performance-based contracts, mitigating the high upfront cost threat to building owners. Deepen relationships with HVAC contractors for channel control and prioritize R&D in AI for predictive maintenance.
For New Entrants and Emerging Players: Establish a beachhead in the retrofit market for public buildings across the European Union, leveraging wireless control solutions for non-invasive upgrades. Target specialized control valves and sensors compatible with natural refrigerants in commercial refrigeration and heat pump sectors. Partner with system integrators to offer niche, high-efficiency solutions to address specific regulatory compliance needs.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-focused innovators and specialized component manufacturers. Long-term viability remains strong, driven by global building decarbonization mandates and the ongoing shift to smart building technologies. Target agile mid-cap companies with expertise in advanced actuators, smart valves, or robust IoT integration platforms. The signal to watch is the accelerating adoption rate of digital twin technology in large commercial facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Energy-as-a-Service Offerings | Captures recurring revenue streams and reduces upfront capital barriers for building owners. |
| Invest in Interoperable Digital Platforms | Addresses vendor lock-in concerns and integrates seamlessly with diverse building automation systems. |
| Develop Natural Refrigerant Compatible Controls | Meets F-Gas Regulation mandates and serves the growing heat pump sector. |
| Strengthen HVAC Contractor Partnerships | Ensures effective deployment and ongoing maintenance of complex hydronic control systems. |
| Integrate AI for Predictive Maintenance | Optimizes system performance and reduces operational downtime for data centers. |
Research Approach
Operator-level perspectives from HVAC contractors, facility managers, system integrators, and energy service companies anchored the qualitative base for this study. Primary interviews with industry stakeholders were triangulated with extensive secondary validation from EU directives, EPA guidelines, and ISO standards. This approach ensured a robust bottom-up and top-down data synthesis.
Scenario-bracketing defined the forecast framework, integrating various market drivers and restraints across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory impact. Compound Annual Growth Rates were derived from historical trends and projected growth catalysts. Key industry-specific forecast inputs included data center expansion rates and evolving building energy performance mandates.
Sensitivities concentrate around shifts in energy performance regulations, unforeseen technological breakthroughs, and persistent component supply chain disruptions. Forecasts reflect current assumptions regarding market dynamics and adoption rates. Material shifts in global energy policy or critical component availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Aeration System Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Europe District Cooling Pipeline Network Market