
 Corrugated Air Duct Market | 2026-2036
Corrugated Air Duct Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Air Duct Market Analytics
The EU Green Deal's building efficiency mandates is hardening material specifications for commercial and industrial duct installations across Europe. Thermaflex leverages its fabric duct technology leadership to capture specification-driven replacement cycles in Nordic commercial buildings. Lindab Group anchors steel duct supply through manufacturing scale across Central European industrial corridors. Novaflex Group specializes in flexible aluminum configurations that compete on weight and thermal performance in retrofit-intensive markets.
Corrugated air duct refers to a mechanically formed, helically or annularly profiled conduit manufactured from metals, polymers, or composite fabrics, typically ranging from 50 mm to 2000 mm in diameter, designed to convey conditioned air with minimal pressure loss while accommodating thermal expansion and seismic movement in building infrastructure. Its primary industrial purpose centers on distributing ventilation, heating, cooling, and controlled airflow within commercial, industrial, residential, and automotive environments where spatial constraints or vibration tolerance preclude rigid ductwork. Aluminum ducts lead product type demand in weight-sensitive suspended installations across multi-story commercial developments, while fabric ducts represent the fastest-growing category due to their even air dispersion and reduced cleaning burden in cleanroom and food processing applications. The installation type dimension shows flexible and modular configurations capturing margin pools in retrofit markets where existing structural envelopes limit rigid duct routing.
The US EPA and OSHA shape demand through indoor air quality enforcement and workplace ventilation requirements that mandate specific duct material fire ratings and leakage thresholds. The EU F-Gas Regulation and REACH framework further constrain polymer composition and sealing technologies permissible in cross-border building systems. Stakeholders must monitor how evolving national building codes in Germany, France, and the United States integrate embodied carbon metrics into duct specification protocols.
Market Dynamics
The EU Green Deal's building efficiency mandates are hardening material specifications and compressing specification cycles across commercial and industrial duct installations. This regulatory pressure is forcing rapid substitution of legacy steel systems with lighter aluminum and fabric alternatives in retrofit-intensive corridors.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases in HVAC systems are accelerating specification changes toward fabric and aluminum duct configurations with lower thermal bridging.
- Commercial building HVAC retrofits:Aging infrastructure across North American multi-story developments is generating sustained replacement demand for flexible duct systems that navigate spatial constraints.
- District heating modernization:Germany's pipeline rehabilitation programs are driving specification upgrades for thermally efficient corrugated duct materials in industrial facility connections.
Market Restraints
- Aluminum input cost volatility:Primary aluminum price swings tied to energy-intensive smelting operations in China and Russia are compressing margin stability for duct fabricators.
- REACH compliance friction:Polymer-based flexible ducts face extended certification timelines and restricted substance lists that delay product launches across EU member states.
- Rigid spiral duct substitution:Standardized steel spiral ductwork retains cost advantages in new-build commercial construction where structural flexibility is not required.
Strategic Opportunities
- Cleanroom and food processing:Fabric ducts with antimicrobial coatings and even air dispersion profiles are capturing specification share from metal systems in pharmaceutical manufacturing environments.
- US IRA building efficiency incentives:Tax credits for commercial building envelope upgrades are expanding retrofit budgets for HVAC contractors specifying lightweight duct alternatives.
- Seismic zone construction codes:Updated standards in Japan and California are mandating flexible duct connections that accommodate building movement without leakage.
Industry Challenges
- Fire-rated fabric certification timelines:Obtaining UL 181 and EN 13501-1 approvals for novel textile compositions extends product development cycles by 18-24 months.
- Installation labor scarcity:Qualified sheet metal and fabric duct technicians are concentrated in aging trade populations across Germany and the northeastern United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Air Duct Market |
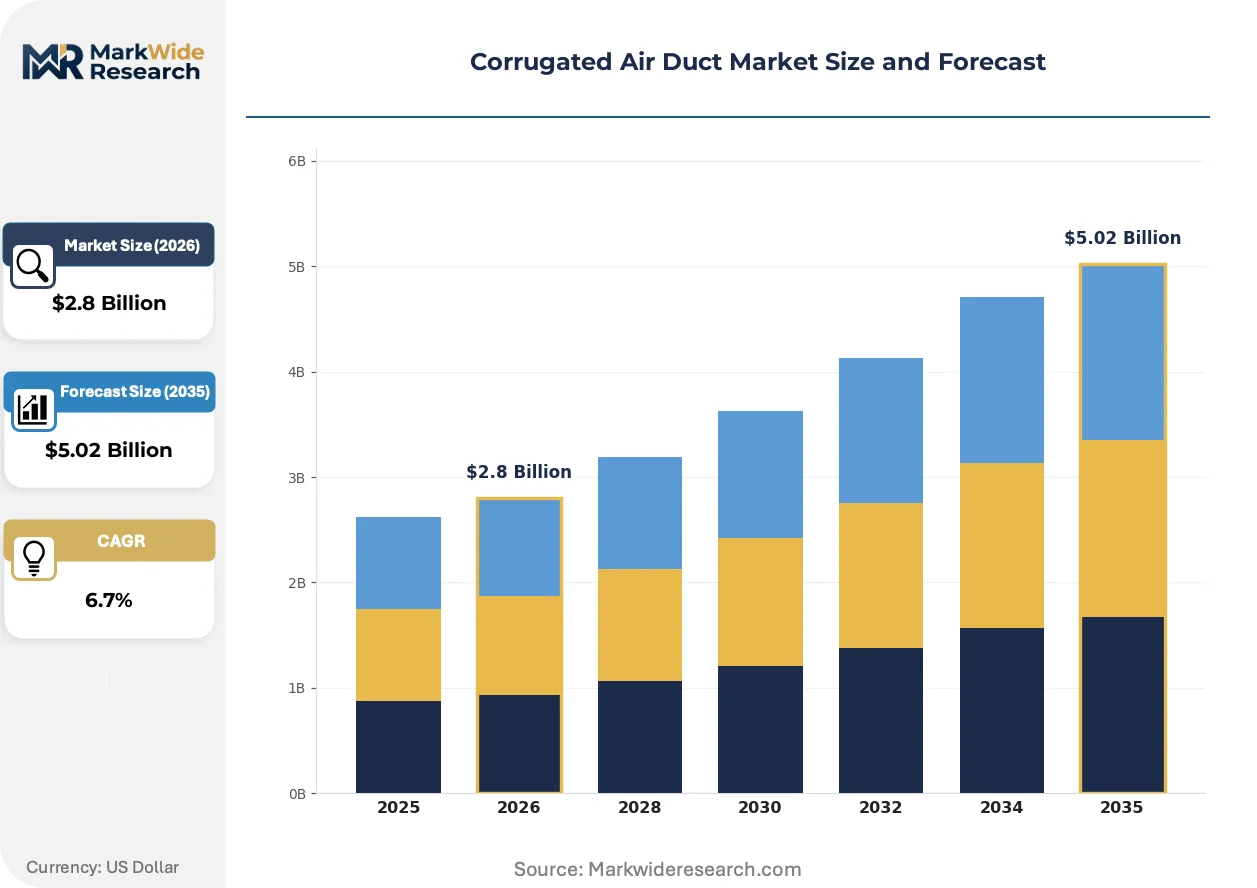
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Ducts, Aluminum Ducts, Steel Ducts, Fabric Ducts End User: Commercial Buildings, Industrial Facilities, Residential Applications, Automotive Sector Installation Type: Suspend, Rigid, Flexible, Modular Application: Ventilation, Heating, Cooling, Airflow Management |
| Companies Covered | Thermaflex, Novaflex Group, Deflecto, M&M Manufacturing, Dundas Jafine, Lindab Group, US Duct, Durkeesox, Tin Man Sheet Metal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Air Duct Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape competitive positioning across duct system categories. Specification decisions increasingly hinge on embodied carbon metrics and lifecycle performance rather than first-cost economics.
Antimicrobial-coated fabric duct systems are electrifying specification conversations in healthcare and pharmaceutical cleanrooms. Hospital facility managers in Germany and the Netherlands are specifying these systems to reduce particulate accumulation and cleaning downtime. The technology is electrifying margin pools previously captured by stainless steel alternatives by enabling premium pricing for hygiene-critical applications.
The EU Green Deal's building renovation wave is mandating deep energy retrofits across commercial building stocks. Member states must transpose these directives into national codes by specific deadlines, creating synchronized replacement cycles. France and Germany are responding fastest, with building codes now integrating duct leakage testing requirements that favor fabric and precision-formed aluminum over traditional galvanized steel.
Facility managers are consolidating vendor relationships around single-source accountability for HVAC envelope performance. This behavior is compressing the traditional specification chain where engineers, contractors, and material suppliers operated independently. The shift is most visible in Nordic commercial buildings, where integrated design-build contracts now bundle duct selection with energy performance guarantees.
Corrugated Air Duct Market Segmentation
Corrugated air duct specification diverges sharply across building vintages and operational requirements. Retrofit contractors navigate legacy constraints that new-build projects rarely encounter. Material selection increasingly hinges on embodied carbon metrics and leakage testing protocols rather than first-cost economics.
Product Type:
Replacement cycles are shortening as EU Green Deal mandates force rapid substitution of legacy steel systems with lighter alternatives in retrofit-intensive corridors.
- Aluminum Ducts:Helically wound aluminum profiles deliver weight advantages in suspended multi-story installations. German district heating modernization and Dutch commercial retrofits are concentrating specification share here due to thermal performance and seismic flexibility requirements.
- Fabric Ducts:Composite textile conduits with antimicrobial coatings enable even air dispersion in hygiene-critical environments. Pharmaceutical cleanrooms in Germany and food processing facilities across the Netherlands are displacing stainless steel alternatives, driven by reduced cleaning burden and particulate control.
- PVC Ducts:Polymer-based flexible configurations serve cost-sensitive residential and light commercial applications where fire rating requirements remain moderate.
- Steel Ducts:Galvanized spiral ductwork retains specification in new-build industrial construction where structural flexibility is not required and first-cost pressure dominates.
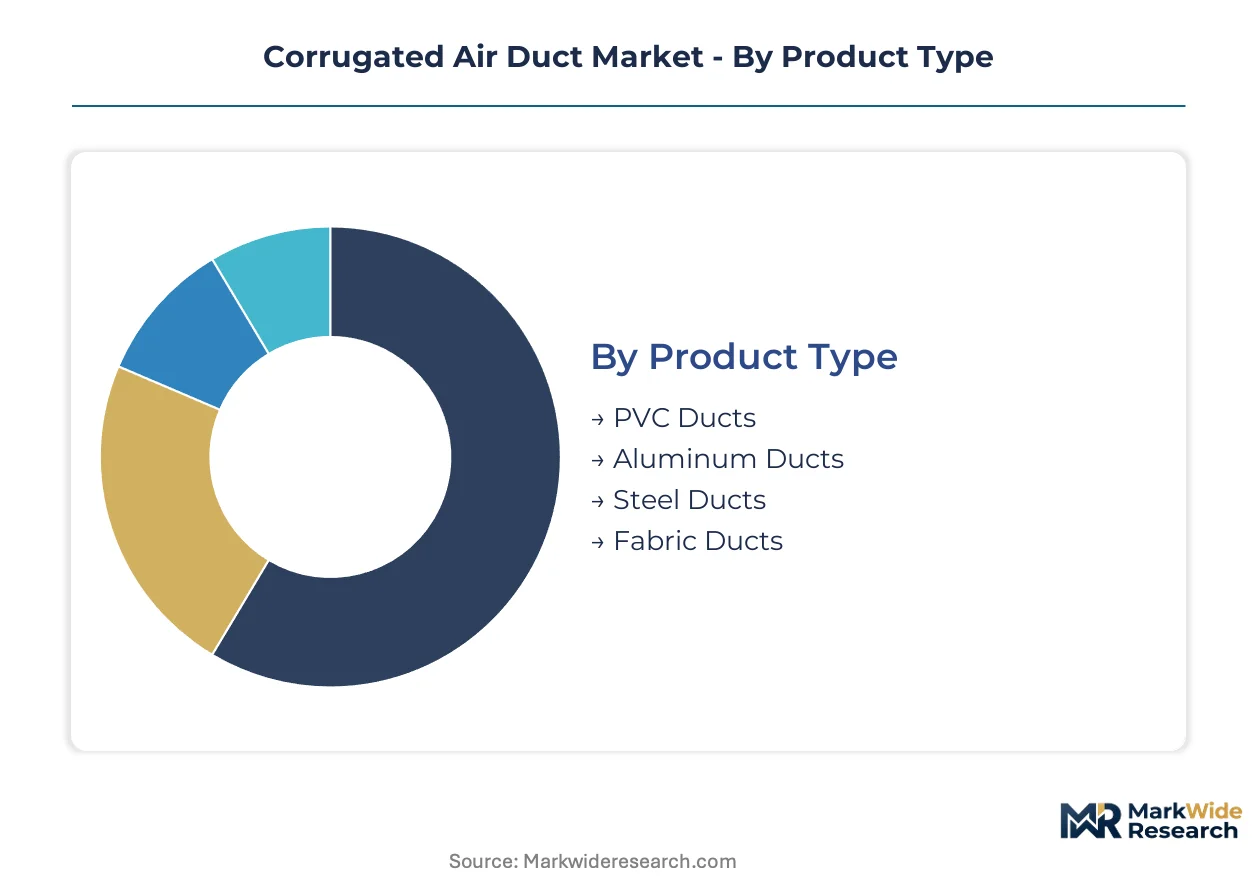
Aluminum Ducts sits at the top of the volume ranking, with Fabric Ducts climbing the fastest.
End User:
Customer procurement patterns are consolidating around single-source accountability for HVAC envelope performance, compressing traditional specification chains.
- Commercial Buildings:Multi-story office and retail developments generate sustained replacement demand as aging infrastructure across North America and Western Europe reaches end-of-service. US IRA tax credits for envelope upgrades are expanding retrofit budgets.
- Industrial Facilities:Manufacturing plants and warehouse complexes specify thermally efficient corrugated materials for process ventilation and climate control. Germany's pipeline rehabilitation programs are driving specification upgrades in facility connections.
- Residential Applications:Single-family and multi-family housing deploy flexible polymer and aluminum configurations where spatial constraints preclude rigid routing.
- Automotive Sector:Vehicle manufacturing plants and paint booths require specialized duct systems for fume extraction and controlled atmosphere management.
Commercial Buildings commands the largest installed base, while Industrial Facilities is expanding most quickly on the back of manufacturing reshoring and facility modernization.
Installation Type:
Margin pools are shifting toward flexible and modular configurations as existing structural envelopes limit rigid duct routing in renovation work.
- Flexible:Compressible, bendable duct segments navigate tight ceiling plenums and irregular structural geometries. North American HVAC retrofits are concentrating demand here where aging multi-story developments present access challenges.
- Modular:Prefabricated, field-assembled systems reduce on-site labor requirements and enable rapid deployment. Nordic design-build contracts are bundling modular duct selection with energy performance guarantees.
- Suspend:Overhead-mounted configurations using cable or rod supports dominate open-ceiling industrial and commercial applications.
- Rigid:Fixed-profile ductwork retains cost advantages in new construction where routing paths are unobstructed and seismic movement is not a design factor.
Flexible installation commands the greatest retrofit penetration, with Modular gaining share fastest through integrated design-build procurement.
Application:
Functional requirements are tightening as building codes integrate duct leakage testing and embodied carbon metrics into specification protocols.
- Ventilation:Fresh air distribution and exhaust systems constitute the foundational use case across all building types. French and German building codes are mandating leakage testing requirements that favor precision-formed configurations.
- Cooling:Chilled air conveyance demands materials with low thermal bridging to prevent condensation and energy loss. EU F-Gas Regulation restrictions are accelerating specification toward fabric and aluminum alternatives.
- Heating:Warm air distribution systems in commercial and residential settings require thermal expansion tolerance and fire-rated materials.
- Airflow Management:Precision-controlled air distribution for cleanrooms, laboratories, and specialized industrial processes demands even dispersion profiles and particulate control.
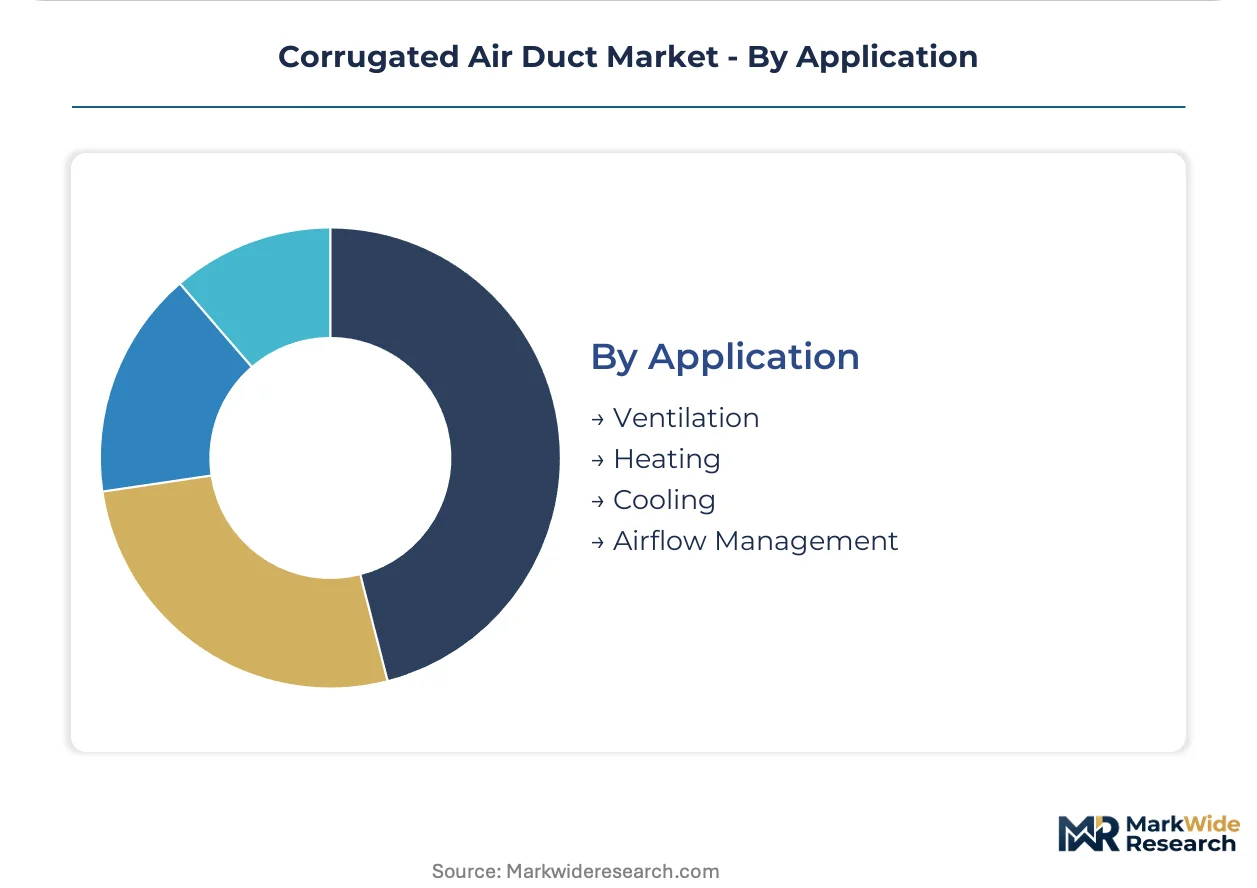
Ventilation holds the broadest installed base, with Cooling experiencing the steepest specification shift due to regulatory pressure on thermal efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The corrugated air duct industry traces its modern scaling to post-war German industrial reconstruction, where Lindab Group pioneered helically wound steel duct fabrication for European manufacturing corridors. This German foundation established material standards and installation protocols that diffused across Western European building codes and later into North American commercial construction practices.
Germany
District heating modernization and industrial facility upgrades concentrate specification demand in the Ruhr industrial belt and Bavarian manufacturing zones. The EU Green Deal's building efficiency mandates are compressing replacement cycles for legacy galvanized steel systems. Berlin and Hamburg commercial retrofits are driving adoption of fabric and aluminum alternatives with lower embodied carbon profiles.
United States
Multi-story commercial HVAC retrofits across aging northeastern and midwestern building stocks generate sustained flexible duct demand. US IRA tax credits for building envelope upgrades are expanding contractor budgets for lightweight aluminum configurations. Chicago and New York City facility managers are consolidating vendor relationships around single-source energy performance guarantees.
Netherlands
Pharmaceutical cleanrooms and food processing facilities in the Randstad corridor are displacing stainless steel with antimicrobial-coated fabric duct systems. Dutch building codes transposing EU F-Gas Regulation requirements favor precision-formed aluminum with reduced thermal bridging. Eindhoven's high-tech manufacturing cluster anchors specification conversations for even air dispersion technologies.
France
Deep energy retrofit mandates under the EU Green Deal's renovation wave are synchronizing replacement cycles across Parisian commercial portfolios. French building codes now integrate duct leakage testing requirements that disadvantage traditional steel spiral ductwork. Lyon and Marseille industrial zones are driving specification upgrades for thermally efficient corrugated materials in process ventilation applications.
Japan
Updated seismic zone construction codes in Tokyo and Osaka are mandating flexible duct connections that accommodate building movement without leakage. METI efficiency standards for commercial HVAC systems are accelerating specification of lightweight aluminum configurations. Nagoya's automotive manufacturing plants require specialized duct systems for paint booth atmosphere management and fume extraction.
Corrugated Air Duct Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material technology and certification depth, with fabric and precision-formed aluminum specialists commanding pricing power over standardized steel fabricators. The vendor base stratifies into three tiers: integrated European industrial conglomerates with manufacturing scale, mid-cap specialists focused on antimicrobial textile innovations, and regional metal fabricators competing on installation proximity. Dominant competitive moves include backward integration into polymer and aluminum supply chains, plus strategic partnerships with HVAC contractors for design-build procurement bundling.
Within the European industrial tier, Lindab Group and Thermaflex occupy positions exemplifying divergent specialization vectors—Lindab representing scale-driven steel and aluminum fabrication across Central European corridors, Thermaflex anchoring fabric duct technology leadership in Nordic commercial building retrofits. Novaflex Group sits within the North American flexible aluminum specialist archetype, competing on weight and thermal performance in retrofit-intensive markets where seismic flexibility and spatial constraints preclude rigid routing.
| Leading Market Players |
|---|
| Thermaflex |
| Novaflex Group |
| Deflecto |
| M&M Manufacturing |
| Dundas Jafine |
| Lindab Group |
| US Duct |
| Durkeesox |
| Tin Man Sheet Metal |
| Others |
Value Network & Pricing Analysis
Commercial HVAC contractors in Germany and the Netherlands are consolidating procurement around single-source energy performance guarantees, compressing traditional multi-vendor bidding and concentrating pricing power with fabric and aluminum specialists who bundle installation accountability. This buyer consolidation favors vendors with backward integration into polymer and aluminum supply chains, as raw material cost pass-through becomes a competitive differentiator in retrofit-intensive corridors.
Pricing Analysis
Three-tier pricing structure across premium antimicrobial fabric, standard aluminum, and economy-grade PVC levels dominates specification conversations, with differentiation anchored in UL 181 and EN 13501-1 certification depth plus after-sales service bundling. Cost compression in the steel tier is intensifying because rigid spiral ductwork faces displacement by lighter alternatives in seismic-zone retrofits. Commercial building facility managers exhibit the highest price sensitivity, while pharmaceutical cleanroom operators accept premium positioning for particulate control guarantees.
Supply Chain Analysis
Dual-sourcing requirements from German and French general contractors mandate qualified supplier pools across at least two of Germany, the Netherlands, and Belgium for critical duct fabrication. Raw material flows draw from Norwegian and Icelandic primary aluminum, German steel coil, and Belgian polymer compounding operations. Single-source vulnerability concentrates in helical winding equipment and antimicrobial textile coating technologies. Distribution runs through HVAC wholesale cooperatives in the Rhine-Ruhr corridor and direct-to-contractor channels in Nordic design-build markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through aluminum input cost stabilization and premium-tier antimicrobial fabric displacement of stainless steel in hygiene-critical applications. Specification-driven procurement consolidation rewards vendors who control material conversion and installation labor quality.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Deepen UL 181 and EN 13501-1 approval portfolios to extend product development timelines for challengers by 18-24 months. Anchor capacity in the Ruhr industrial belt to capture German district heating modernization cycles and compress logistics costs for Benelux retrofit contractors facing aluminum price volatility. For New Entrants and Emerging Players: The mid-tier price gap between premium fabric and economy PVC creates entry space for hybrid aluminum-polymer configurations targeting French commercial retrofits. Focus specification conversations on embodied carbon metrics where EU Green Deal mandates disadvantage legacy steel. Pursue design-build contractor partnerships in Nordic markets where integrated procurement bundles duct selection with energy performance guarantees. For Investors and Strategic Acquirers: HVAC service conglomerates are the most active acquirer in this space, seeking fabric technology capabilities to complete envelope-performance offerings. Five-to-ten year viability hinges on regulatory tightening around leakage testing and embodied carbon protocols. Watch German building code transposition deadlines as inflection indicators for synchronized replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Supply | Captive sourcing from Norwegian smelters insulates margin stability against energy price volatility. |
| Antimicrobial Coating Technology Licensing | Pharmaceutical cleanroom specifications in Eindhoven and Rotterdam reward particulate control premiums. |
| Design-Build Contractor Partnership | Nordic commercial retrofits bundle duct selection with energy performance guarantees, compressing sales cycles. |
| EU Green Deal Compliance Certification | French and German leakage testing mandates favor precision-formed aluminum over traditional galvanized steel. |
| Seismic Zone Product Line Extension | Tokyo and Osaka building codes mandate flexible connections that accommodate structural movement without leakage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with HVAC contractors, facility managers, and specification engineers with secondary validation through EU F-Gas Regulation filings, national building code transposition documents, and customs data on aluminum and steel coil trade flows. Bottom-up project pipeline analysis across German district heating programs and US IRA-funded retrofits was triangulated against top-down spending estimates from construction industry associations.
Segment-weighting approaches applied product type, installation configuration, end-use vertical, and regional regulatory cluster dimensions across the modeling period. CAGRs were derived from fitted growth curves anchored to disclosed project timelines and replacement cycle assumptions. Forecast inputs incorporated aluminum price elasticity coefficients and EU member state building code adoption schedules.
Caveats apply where primary aluminum smelter energy costs or REACH substance restriction expansions could materially shift the outlook. Deviation in German building code enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Aeration System Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Cold Insulation Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Marine HVAC System Market