
 Global Building Thermal Insulation Material Market | 2026-2036
Global Building Thermal Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Building Thermal Insulation Material Market Analysis
Passive House certification standards are reorganizing procurement priorities across the Global Building Thermal Insulation Material Market. Owens Corning leverages its fiberglass manufacturing scale to dominate North American residential retrofits. Kingspan Group anchors its position through backward integration into rigid polyurethane foam core production. Rockwool International specializes in fire-resistant mineral wool systems for commercial high-rises, competing on regulatory compliance rather than thermal performance alone.
Building thermal insulation material encompasses engineered substances designed to reduce conductive heat flow through building envelopes, typically quantified by thermal conductivity values measured in watts per meter-kelvin. These materials function by trapping air or gas within cellular, fibrous, or granular matrices to impede heat transfer between conditioned interior spaces and ambient exterior environments. Mineral wool leads commercial applications due to its non-combustible classification under EN 13501-1, while spray polyurethane foam captures the fastest growth trajectory in airtightness-critical retrofits. Polystyrene boards maintain mature volume positions in below-grade and cavity wall applications where cost sensitivity dominates specification decisions.
The EU Green Deal's Renovation Wave strategy, enforced through national building codes transposing the Energy Performance of Buildings Directive, mandates stepwise thermal performance upgrades across Germany, France, and Italy. ECHA's REACH restrictions on flame retardant chemistries in polystyrene systems are forcing reformulation investments that favor mineral wool alternatives in certain jurisdictions. Stakeholders must monitor evolving carbon border adjustment mechanisms and embodied carbon disclosure requirements under the CSRD, as these frameworks will progressively advantage lower-carbon insulation feedstocks and penalize high-emission manufacturing pathways regardless of operational thermal performance.
Market Dynamics
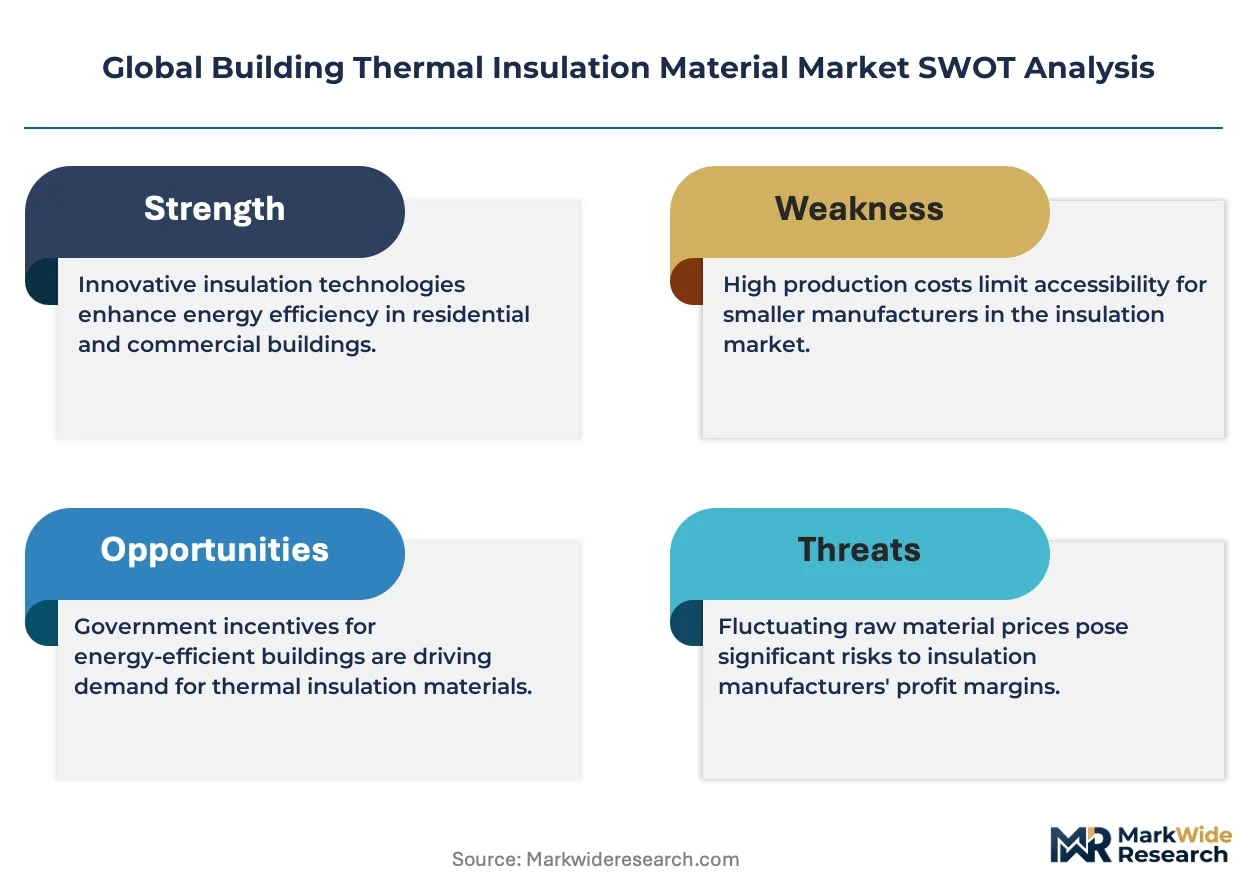
EU Green Deal retrofit mandates are compressing specification cycles across building envelopes, forcing asset owners to replace legacy facade systems ahead of planned maintenance schedules. This regulatory compression is restructuring procurement priorities toward fire-rated mineral wool and low-carbon feedstocks.
Growth Catalysts
- EU Green Deal Renovation Wave:National building codes transposing the Energy Performance of Buildings Directive mandate stepwise thermal upgrades across Germany, France, and Italy.
- District heating integration:Germany's Rhine-Ruhr corridor drives premium insulation specifications as urban energy networks require compatible building envelope performance.
- Passive House certification:Stringent airtightness standards accelerate specification-grade mineral wool adoption in commercial high-rise construction.
Market Restraints
- Feedstock cost volatility:Benzene and methylene diphenyl diisocyanate price swings compress rigid polyurethane foam margins unpredictably.
- Flame retardant restrictions:ECHA's REACH limitations on halogenated chemistries in polystyrene systems force costly reformulation investments.
- Manufacturing concentration:Glass fiber supply clusters in specific industrial regions create vulnerability to energy price shocks.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU CBAM implementation progressively advantages lower-carbon insulation feedstocks over high-emission pathways.
- Embodied carbon disclosure:CSRD requirements create competitive differentiation for manufacturers with verified lifecycle assessments.
- Deep energy retrofits:Poland and Romania present underpenetrated markets where pre-1990 building stock requires comprehensive envelope upgrades.
Industry Challenges
- Installer certification gaps:Spray polyurethane foam application requires trained technicians, creating bottlenecks in retrofit project timelines.
- Legacy system compatibility:Integrating high-performance insulation with existing masonry structures demands specialized detailing and moisture management expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Building Thermal Insulation Material Market |
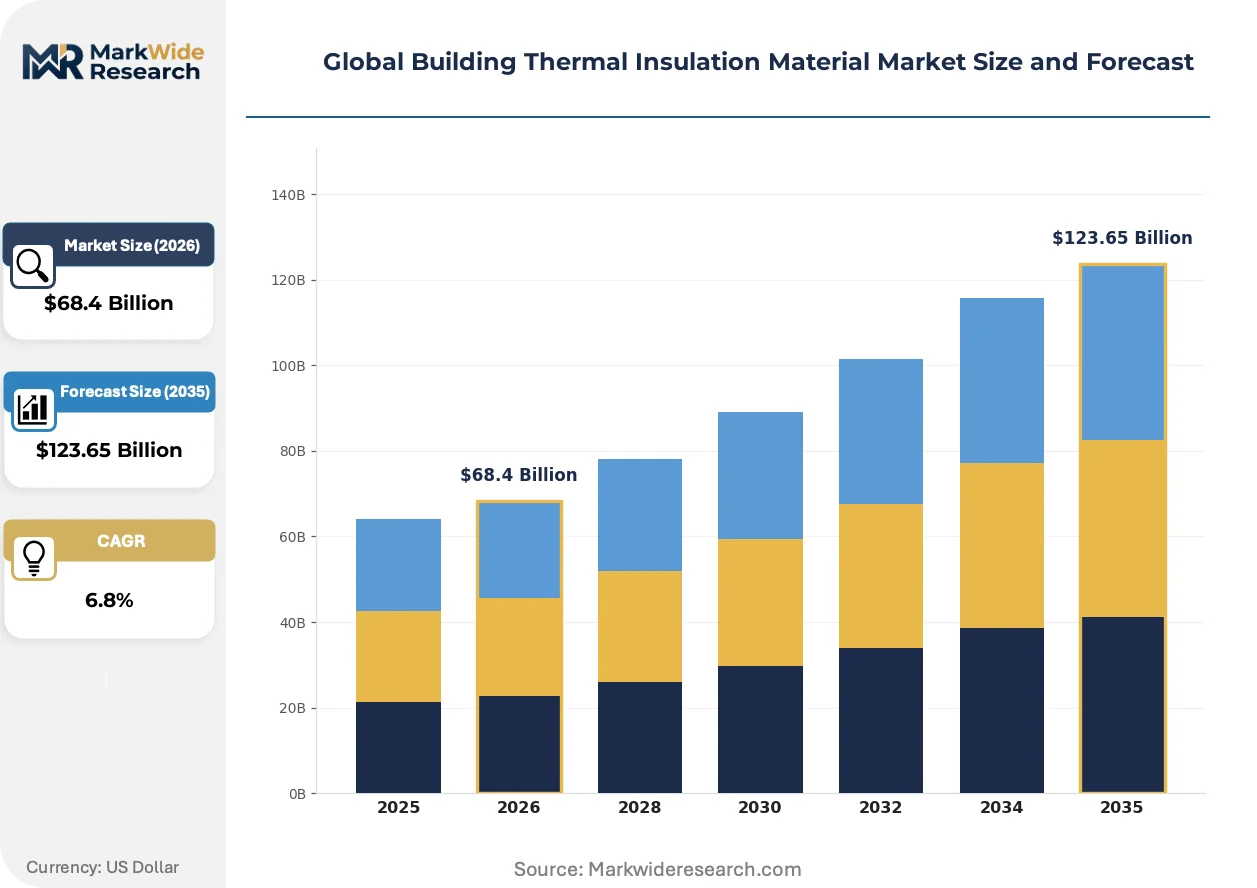
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Fiberglass, Mineral Wool, Polystyrene Application: Residential Buildings, Commercial Structures, Industrial Facilities, Hospitality Sector Form: Boards, Batts, Spray, Rolls End User: Contractors, Architects, Project Developers, Homeowners |
| Companies Covered | Owens Corning, Kingspan Group, Knauf Insulation, Rockwool International, Saint-Gobain, BASF SE, Dow Inc., Johns Manville, Armacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Building Thermal Insulation Material Market Emerging Trajectories
Bio-based feedstocks and circular manufacturing processes are reorganizing competitive advantage in thermal insulation. Material science advances now enable performance parity with petroleum-derived alternatives at reduced embodied carbon intensity.
Aerogel-enhanced blankets are displacing conventional rigid boards in space-constrained commercial retrofits. Building owners in Japan and South Korea specify these materials for high-value curtain wall upgrades where thickness constraints previously limited thermal performance. The technology is displacing multi-layer mineral wool systems in premium segments where installed depth is restricted by structural or aesthetic requirements.
CSRD disclosure requirements are mandating granular embodied carbon reporting across EU member states. Manufacturers must now document cradle-to-gate emissions for every product category sold into commercial construction. German and French specification teams increasingly screen insulation products on global warming potential metrics before thermal conductivity values.
Performance-based procurement contracts now dominate public sector retrofit tenders in Nordic markets. Contractors assume energy savings risk rather than delivering materials-only specifications. Denmark and Sweden lead this shift, with municipal housing authorities bundling insulation installation with guaranteed heating load reductions over fifteen-year contract terms.
Global Building Thermal Insulation Material Market Segmentation
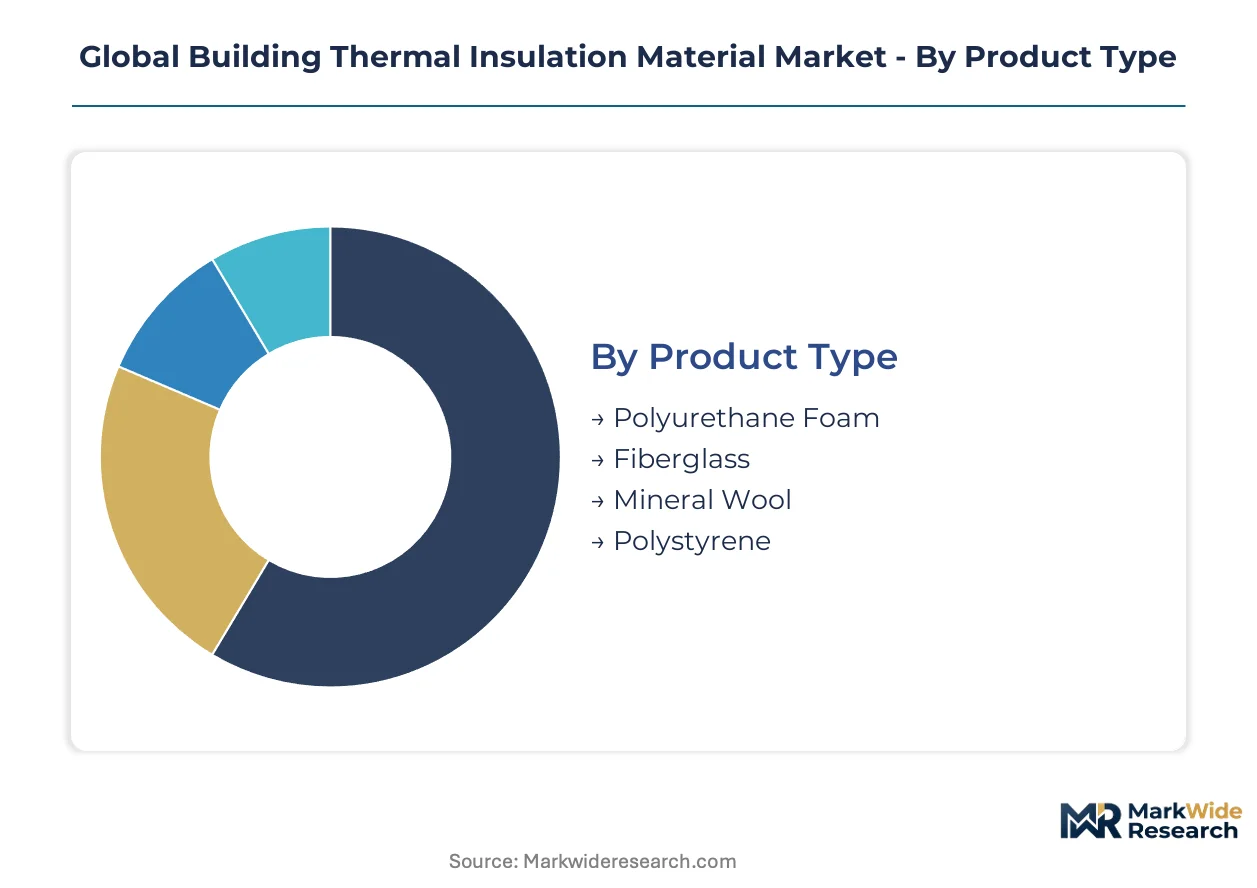
Thermal insulation procurement varies sharply across building typologies and specification hierarchies. Regulatory fire-safety classifications and embodied carbon disclosure requirements now override pure thermal conductivity in material selection. Understanding these segment boundaries clarifies where specification power concentrates and where margin compression threatens.
Product Type:
ECHA REACH flame retardant restrictions and EU Green Deal carbon accounting rules differentiate material viability across building codes.
- Mineral Wool:Non-combustible rock and slag fibers classified A1 under EN 13501-1 dominate commercial high-rise specifications in Germany, France, and the United Kingdom. EU retrofit mandates are compressing specification cycles toward fire-rated systems regardless of thermal performance premiums.
- Polyurethane Foam:Rigid closed-cell structures deliver superior R-value per inch but face feedstock volatility from benzene and methylene diphenyl diisocyanate price swings. Deep energy retrofits in Poland and Romania favor this material for space-constrained envelope upgrades where thickness limits apply.
- Fiberglass:Glass fiber batts and loose-fill dominate North American residential construction cost tiers. Manufacturing concentration in specific industrial regions creates vulnerability to natural gas price shocks.
- Polystyrene:Expanded and extruded boards maintain mature volume in below-grade and cavity wall applications. ECHA restrictions on halogenated flame retardants force costly reformulation investments that disadvantage this material in certain EU jurisdictions.
Mineral wool handles the majority of throughput in commercial construction; polyurethane foam is gaining share fastest in airtightness-critical retrofits.
Application:
Building typology determines fire-rating requirements, thermal bridging complexity, and procurement authority concentration.
- Commercial Structures:High-rise office and mixed-use developments in Germany's Rhine-Ruhr corridor specify premium mineral wool systems. District heating integration demands compatible envelope performance that standard residential specifications cannot satisfy.
- Residential Buildings:Single-family and multi-family retrofits concentrate demand for cost-optimized fiberglass and polystyrene solutions. Passive House certification standards in Austria and Belgium reorganize procurement priorities toward airtightness-grade materials.
- Industrial Facilities:Process heat management and cold storage applications specify rigid polyurethane foam for thermal efficiency in operational cost-sensitive environments.
- Hospitality Sector:Hotel renovations prioritize acoustic and thermal performance bundles, particularly in urban cores where guest comfort ratings drive capital allocation.
Commercial structures command the highest specification intensity; residential buildings move the largest absolute volume.
Form:
Installation method constraints and skilled labor availability shape form factor adoption curves.
- Batts:Pre-cut fibrous sections dominate residential contractor channels where speed of installation outweighs thermal bridging concerns. Standardized dimensions align with North American stud spacing conventions.
- Boards:Rigid panels serve commercial facade systems and below-grade waterproofing assemblies. Japanese and South Korean curtain wall retrofits specify aerogel-enhanced variants where structural depth is restricted.
- Spray:On-site polyurethane application delivers seamless air barriers but requires certified technician availability that bottlenecks project timelines in underpenetrated markets.
- Rolls:Continuous fibrous products optimize material yield in large-surface applications such as attic spaces and metal building insulation.
Boards retain the dominant installed base; spray formats are expanding most quickly in deep retrofit segments.
End User:
Specification authority and risk allocation vary across the construction value chain.
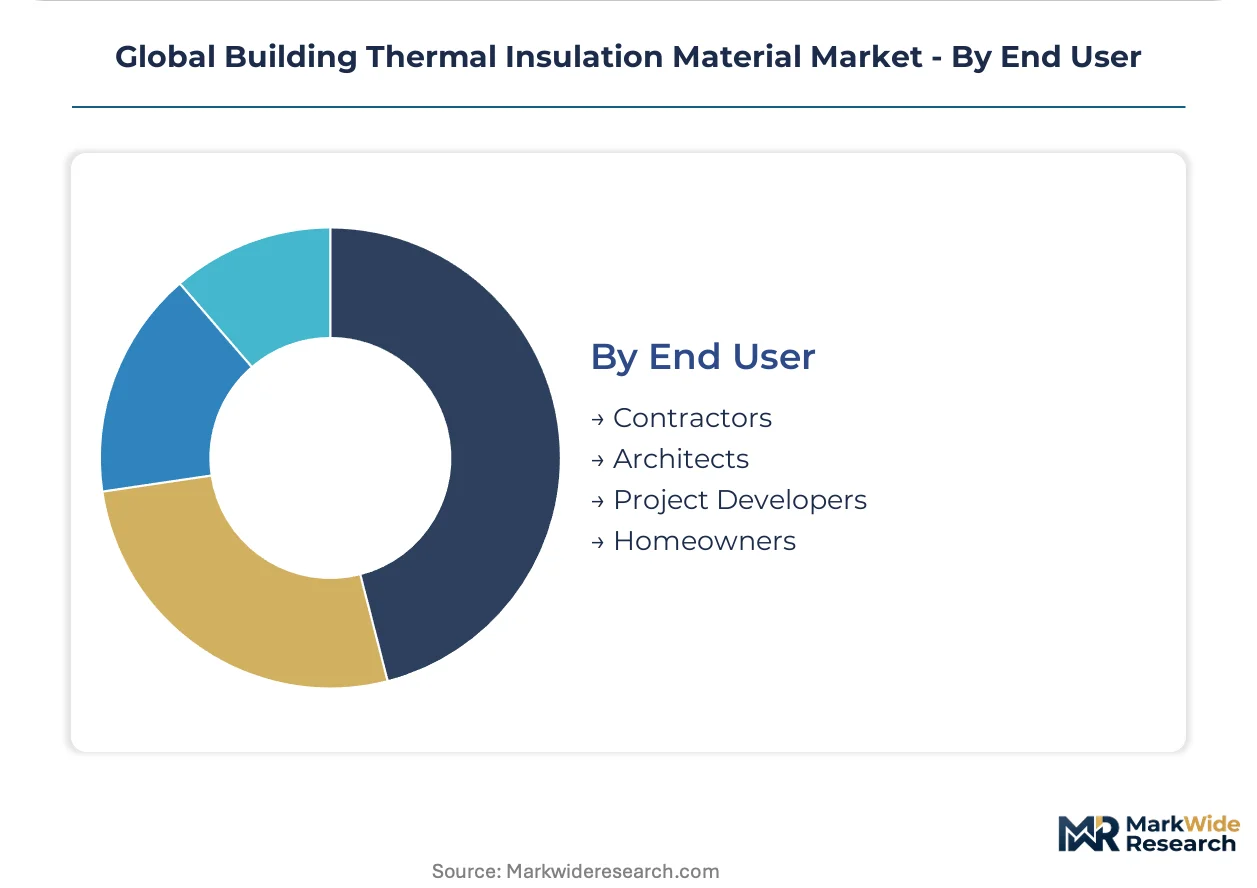
- Architects:Design-phase material selection in France and the Netherlands increasingly screens products on CSRD-mandated embodied carbon metrics before thermal conductivity values. Performance-based procurement contracts in Denmark and Sweden transfer energy savings risk to contractors rather than architects.
- Contractors:Installation-phase purchasing concentrates on material availability and crew productivity. Installer certification gaps for spray polyurethane foam create procurement bottlenecks in Nordic municipal housing retrofits.
- Project Developers:Capital allocation decisions weigh lifecycle energy cost against upfront material expenditure. EU carbon border adjustment mechanisms progressively advantage lower-carbon feedstocks in developer financial models.
- Homeowners:Retail-channel purchasing responds to utility rebate programs and contractor recommendations rather than independent technical evaluation.
Architects control specification in premium commercial segments; contractors dominate residential retrofit procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber manufacturing clusters concentrate in specific industrial corridors across Ohio, North Rhine-Westphalia, and Shandong Province, creating asymmetric exposure to regional energy price shocks. This geographic concentration shapes procurement vulnerability and margin compression patterns.
United States
Residential retrofit programs under the Inflation Reduction Act channel federal tax credits toward fiberglass batt upgrades in Midwest and Southeast housing stock. EPA energy efficiency guidelines influence state-level building code adoptions. Manufacturing concentrates in Ohio and Indiana, where Owens Corning and Johns Manville operate integrated glass fiber furnaces serving continental distribution networks.
Germany
The EU Green Deal Renovation Wave mandates stepwise thermal performance upgrades across pre-1990 building stock, compressing specification cycles toward fire-rated mineral wool. ECHA REACH restrictions on halogenated flame retardants disadvantage certain polystyrene formulations. The Rhine-Ruhr corridor drives premium insulation specifications as district heating integration demands compatible envelope performance standards.
France
ANSM and national building authorities enforce transposed Energy Performance of Buildings Directive requirements through stepped renovation obligations on commercial landlords. CSRD disclosure mandates require granular embodied carbon reporting from insulation suppliers. Greater Paris and Lyon metropolitan areas concentrate deep retrofit activity in social housing portfolios.
China
MIIT dual carbon goals and GB standards for building energy efficiency accelerate specification-grade mineral wool adoption in tier-one city commercial construction. NMPA-equivalent building material safety classifications influence fire-rated system procurement. Manufacturing gravity centers on Shandong and Jiangsu provinces, where integrated glass fiber and mineral wool complexes serve domestic and export demand.
Japan
METI building energy conservation standards tighten thermal performance requirements for commercial high-rise renovations in Tokyo and Osaka metropolitan areas. JIS certification requirements structure insulation material procurement in public sector construction. Aerogel-enhanced blanket specifications concentrate in premium curtain wall retrofits where structural depth constraints limit conventional mineral wool thickness.
Global Building Thermal Insulation Material Market Vendor Landscape
Concentration sits with diversified building materials conglomerates and specialized insulation pure-plays rather than chemical majors or construction generalists. The vendor base organizes around three strategic archetypes: integrated glass fiber manufacturers with captive raw material supply, rigid foam specialists controlling polyurethane chemistry pathways, and fire-resistant mineral wool producers competing on regulatory compliance certification. Dominant competitive moves include backward integration into core feedstock production and geographic expansion through regional manufacturing footprint replication.
Within the integrated glass fiber tier, Owens Corning and Johns Manville occupy positions anchored to North American residential distribution channels. Kingspan Group exemplifies the rigid foam specialist archetype through its backward integration into polyurethane core production. Rockwool International represents the fire-rated mineral wool segment, competing on EN 13501-1 certification compliance rather than thermal conductivity metrics alone. Saint-Gobain and BASF SE sit within diversified materials conglomerate structures where insulation serves as one vertical among multiple building product categories.
| Leading Market Players |
|---|
| Owens Corning |
| Kingspan Group |
| Knauf Insulation |
| Rockwool International |
| Saint-Gobain |
| BASF SE |
| Dow Inc. |
| Johns Manville |
| Armacell |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety day order-to-delivery cycles for specification-grade mineral wool concentrate pricing power with German and French distributors serving EU Green Deal retrofit mandates, compressing margin buffers for project developers facing fixed-price contracting obligations.
Pricing Analysis
EU Green Deal Renovation Wave mandates dictate the pricing tier structure across the Global Building Thermal Insulation Material Market, separating fire-rated A1 mineral wool systems from economy-grade fiberglass batts through EN 13501-1 certification premiums. Three-tier pricing structure across premium, standard, and economy levels reflects embodied carbon disclosure grades under CSRD requirements and district heating compatibility specifications. Cost compression in rigid polyurethane foam is intensifying because benzene and methylene diphenyl diisocyanate feedstock volatility erodes contractor margins on fixed-price deep retrofit contracts. Residential homeowners exhibit highest price sensitivity, selecting polystyrene boards based on utility rebate eligibility rather than lifecycle thermal performance; commercial developers in Germany's Rhine-Ruhr corridor demonstrate lowest sensitivity, prioritizing district heating integration compatibility over unit cost.
Supply Chain Analysis
Ninety-day inventory positions for glass fiber feedstock expose North American manufacturers to natural gas price shocks concentrated in Ohio and Indiana furnace operations. Manufacturing gravity centers on Germany, China, and the United States, with Shandong Province mineral wool complexes and North Rhine-Westphalia integrated glass fiber sites serving regional demand clusters. Raw material sourcing draws from petrochemical benzene derivatives, post-industrial slag for mineral wool, and silica sand for fiberglass production. Single-source vulnerability concentrates in halogenated flame retardant chemistries facing ECHA REACH phase-out timelines. Distribution runs through specification-grade distributor networks for commercial projects and retail contractor channels for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Building Thermal Insulation Material Market sits in early-cycle recovery as EU Green Deal enforcement compresses replacement timelines for pre-1990 building stock across member states.
For Market Incumbents: Shield margin positions in mineral wool through backward integration into slag feedstock supply and captive EN 13501-1 testing laboratory accreditation, neutralizing ECHA REACH-driven substitution threats from reformulated polystyrene competitors. Prioritize capacity discipline in glass fiber to prevent oversupply erosion during Inflation Reduction Act residential retrofit demand peaks. For New Entrants and Emerging Players: Anchor in Poland and Romania deep energy retrofit segments where installer certification gaps for spray polyurethane foam create procurement bottlenecks that regional training academy investments can resolve. Target municipal housing authority performance-based contracting in Denmark and Sweden where fifteen-year energy savings guarantees transfer technology risk away from balance-sheet-constrained entrants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across rigid polyurethane foam manufacturing as benzene derivative volatility forces working capital expansion and hedging infrastructure. Long-term viability over the next decade favors mineral wool specialists with verified lifecycle assessments and district heating integration expertise. Monitor EU carbon border adjustment mechanism implementation schedules as the critical signal for feedstock cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slag Feedstock | Captive supply of blast furnace slag secures mineral wool margins against scrap metal price volatility. |
| EN 13501-1 Certification Investment | A1 fire rating unlocks commercial high-rise specifications in Germany, France, and United Kingdom. |
| Regional Training Academy Network | Certified spray polyurethane foam technician pipelines resolve Nordic municipal housing retrofit bottlenecks. |
| Embodied Carbon Verification Program | CSRD-compliant lifecycle assessments differentiate products in French and Dutch architect specifications. |
| District Heating Compatibility Testing | Rhine-Ruhr corridor envelope performance validation commands premium positioning in urban energy network retrofits. |
Methodological Framework
The analysis maps mineral wool, rigid polyurethane foam, fiberglass, and polystyrene product categories, each validated through specification architects, contractor procurement leads, district heating network engineers, and building envelope consultants. Primary interviews with plant managers at integrated glass fiber facilities, EPC contractors executing deep energy retrofits, and municipal housing authority technical officers combined with secondary validation through EU ECHA REACH regulatory filings, national building code transpositions of the Energy Performance of Buildings Directive, and customs trade data for insulation material flows. Bottom-up project pipeline assessments and top-down construction spend forecasts underwent triangulation against disclosed capacity utilization rates at major manufacturing complexes.
Consistency checks validated volume and value outputs against external benchmarks including construction permit databases for commercial high-rise activity in Germany's Rhine-Ruhr corridor, residential retrofit subsidy claim patterns under the Inflation Reduction Act, and disclosed district heating network expansion capex across EU member states. The analytical framework modeled product type, application, form factor, and end-user specification authority dimensions across the projection horizon. CAGRs derived from segment-level demand elasticity coefficients applied to regulatory mandate enforcement schedules and building stock age demographics. Forecast inputs incorporated EU carbon border adjustment mechanism phase-in assumptions and ECHA flame retardant restriction timelines.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and feedstock price volatility assumptions; material deviation in regulatory implementation pace or petrochemical cost trajectories would warrant model refresh. Specific risk factors include halogenated flame retardant phase-out acceleration, natural gas price shocks affecting glass fiber furnace economics, and installer certification program expansion rates in underpenetrated markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Europe Boiler System Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Roof Vents Market