
 Thermostatic Faucet Market | 2026-2036
Thermostatic Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
Thermostatic Faucet Market Intelligence
The capability gap between digital thermostat R&D and scaled mechanical valve manufacturing is reorganizing competitive dynamics. LIXIL Corporation leverages its extensive brand portfolio to capture diverse regional preferences, while Kohler Co. differentiates through integrated smart home ecosystem compatibility. Grohe AG sustains its premium position with a focus on precision engineering and design leadership, particularly in European markets.
A thermostatic faucet is a plumbing fixture that automatically mixes hot and cold water to a pre-set, constant temperature. These devices utilize a thermostatic mixing valve, often with a wax or bimetallic element, to ensure temperature stability within ±1°C, preventing scalding. While residential applications form the largest end-user segment by volume, the hospitality and healthcare sectors provide higher-margin opportunities. In terms of product type, sensor-activated and digital thermostat models represent the fastest-growing categories, displacing traditional single-handle units.
Product design and market access are heavily influenced by safety and water efficiency regulations. Standards like the US EPA's WaterSense program, the EU's CE marking requirements for safety, and Australia's WELS scheme dictate performance benchmarks. These frameworks mandate features like anti-scald protection and flow rate limits. Consequently, manufacturers must navigate a complex matrix of regional certifications to secure market entry and build consumer trust.
Market Dynamics
The thermostatic faucet market's evolution is defined by the tension between advanced digital control systems and the established scale of mechanical valve manufacturing. This dynamic forces a strategic choice between precision-engineered mechanical components and integrated smart home electronics.
Growth Catalysts
- Water Conservation Mandates:Regulations like the EU's Ecodesign Directive and the US EPA's WaterSense program create a durable replacement cycle, pushing consumers and businesses toward more efficient thermostatic models to meet water usage targets.
- Hospitality Sector Investment:Hotels and resorts are increasingly installing thermostatic faucets to enhance guest safety, improve water and energy efficiency, and elevate the overall user experience, creating a high-volume, specification-driven demand source.
- Renovation and Building Codes:In mature markets such as Germany, extensive renovation activities combined with stringent building codes that prioritize safety and efficiency are accelerating the adoption of thermostatic fixtures in residential and commercial properties.
Market Restraints
- Higher Initial Cost:The premium price point of thermostatic faucets compared to traditional single-lever mixers remains a significant barrier to adoption, particularly in the price-sensitive residential new construction and DIY renovation segments.
- Water Quality Sensitivity:The performance of thermostatic elements, especially wax-based cartridges, can be degraded by hard water and mineral buildup, leading to higher maintenance requirements and potential performance issues in certain geographic regions.
- Component Sourcing Concentration:A reliance on a limited number of specialized manufacturers for critical thermostatic mixing valve components creates potential supply chain bottlenecks and limits the bargaining power of faucet assemblers.
Strategic Opportunities
- Smart Home Integration:There is a significant opportunity in developing thermostatic faucets that integrate seamlessly with digital assistants and smart home ecosystems, offering features like voice control, personalized presets, and water usage monitoring.
- Healthcare Application Expansion:Moving beyond basic anti-scald functions, manufacturers can target healthcare facilities with advanced models featuring touchless controls and automated disinfection cycles to address stringent infection control protocols.
- Emerging Market Penetration:Rapid urbanization and a growing middle class in Southeast Asian and Latin American countries present untapped markets for mid-range thermostatic faucets as safety standards and consumer expectations rise.
Industry Challenges
- Navigating Regulatory Fragmentation:Manufacturers face significant costs and administrative burdens in securing and maintaining multiple country-specific certifications, such as CE marking in Europe, WELS in Australia, and WaterSense in the United States.
- Retrofitting Legacy Plumbing:Installing modern thermostatic faucets in older buildings can be complex and expensive due to incompatible plumbing configurations, pressure imbalances, and pipe dimensions, slowing down the replacement market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermostatic Faucet Market |
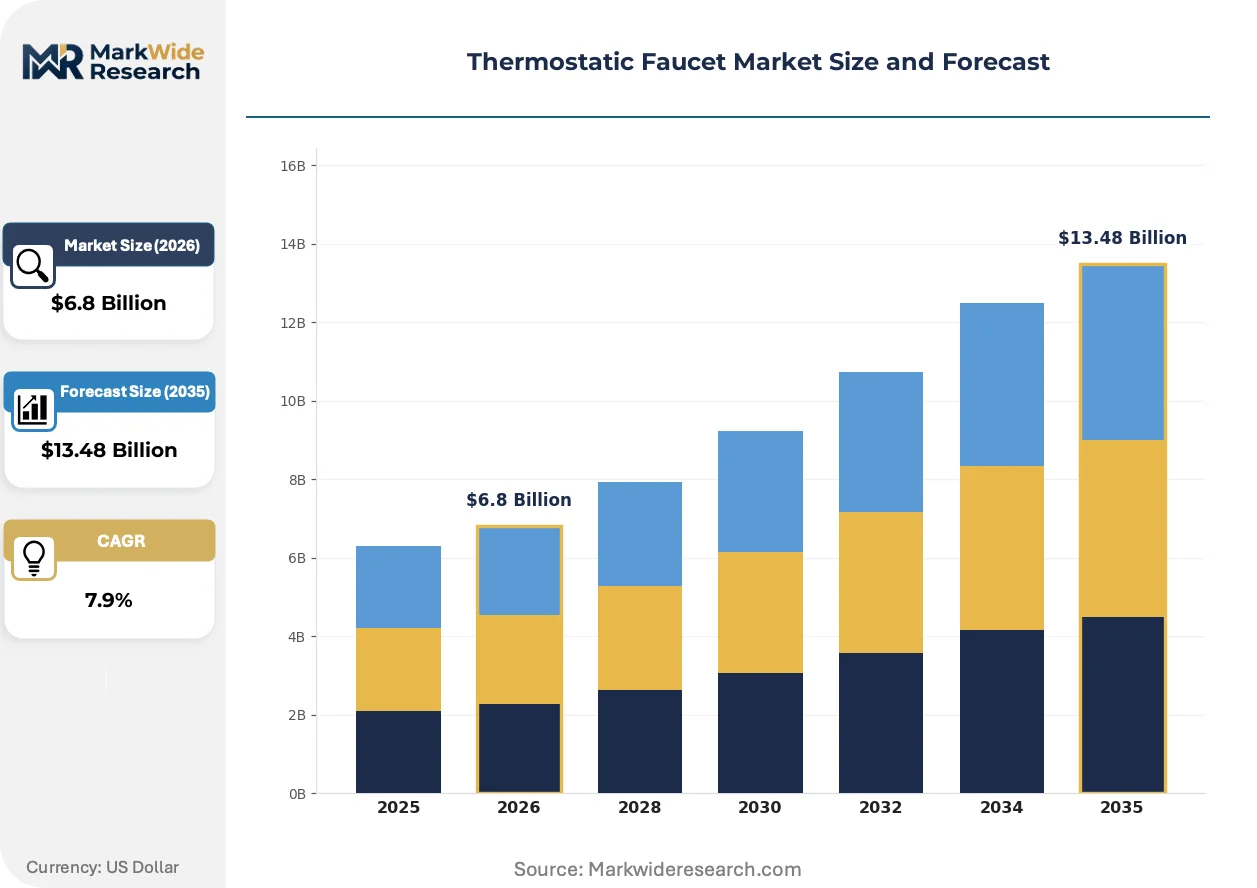
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Handle, Double-Handle, Sensor-Activated, Digital Thermostat Installation Type: Wall-Mounted, Deck-Mounted, Freestanding, Under-Counter Feature: Temperature Control, Safety Locks, Water Conservation, User Programmed Settings End User: Residential, Commercial, Hospitality, Healthcare Facilities |
| Companies Covered | Grohe AG, Kohler Co., Moen Incorporated, Cera Sanitaryware Ltd., Roca Sanitario S.A.U., Jaquar Global, Geberit AG, LIXIL Corporation, Masco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermostatic Faucet Market Strategic Shifts & Innovations
The market's trajectory is shifting from a focus on mechanical reliability to an emphasis on digital precision and system intelligence. This transition alters the definition of a premium product, linking it to connectivity and data rather than just material quality.
Digital thermostatic valves, which use electronic sensors and microprocessors, provide nearly instantaneous and highly accurate temperature adjustments. High-end residential properties and commercial projects like smart hotels are the primary adopters of this technology. This advanced electronic control is displacing traditional wax and bimetallic element-based valves in the market's premium and luxury tiers.
Australia's Water Efficiency Labelling and Standards (WELS) scheme imposes stringent flow rate limits and performance ratings on plumbing fixtures sold in the country. This regulation compels manufacturers to engineer faucets that deliver consistent temperature and user comfort at reduced water volumes. The WELS framework directly influences product development for the Australian market and increasingly serves as a benchmark for other water-scarce regions.
A notable behavioral shift is the rising consumer and commercial demand for integrated hygiene features that go beyond basic temperature control. This trend elevates purchasing criteria to include sensor-based touchless activation, anti-microbial surface finishes, and automated flushing cycles. This preference is most pronounced in healthcare, hospitality, and public facilities, but is also gaining traction in premium residential applications.
Thermostatic Faucet Market Segmentation
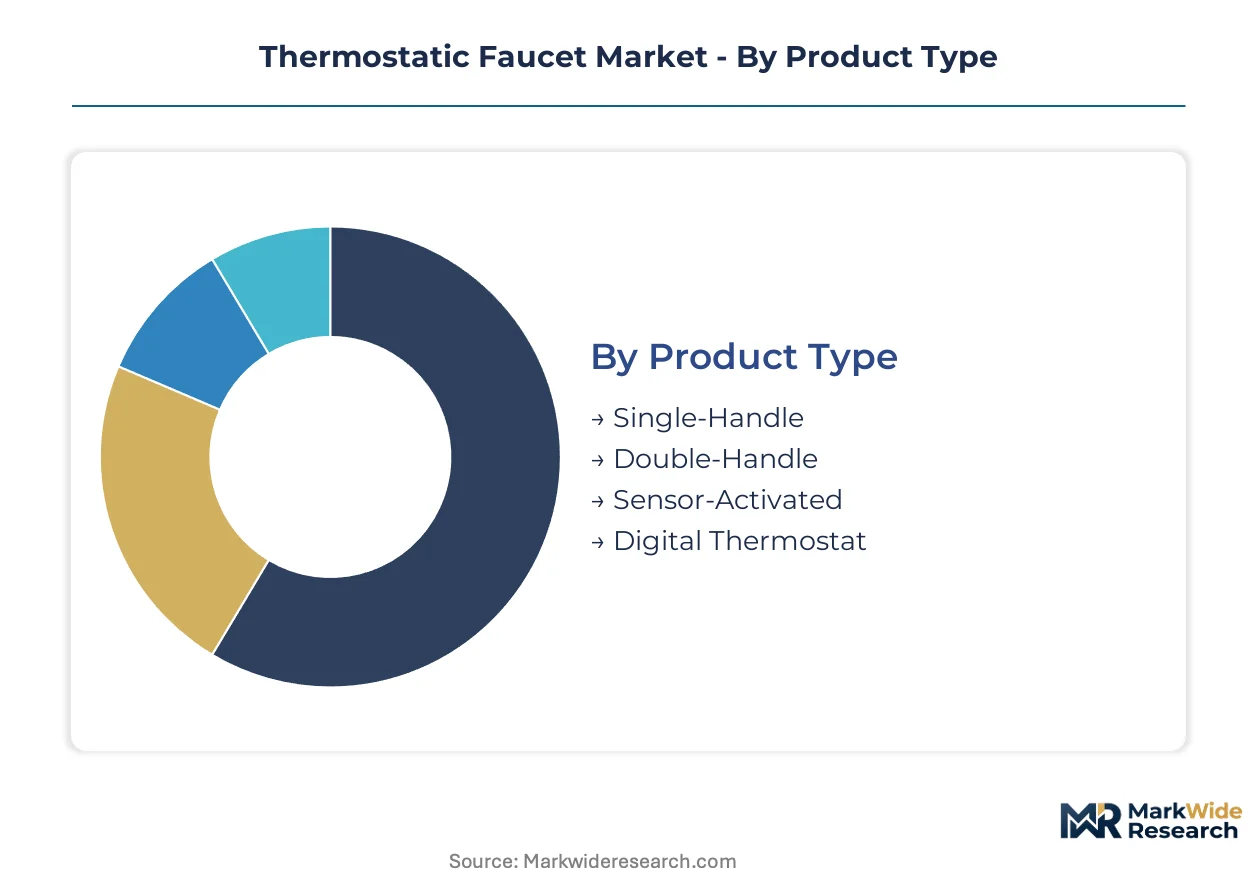
The thermostatic faucet market delineates across several critical dimensions, reflecting both technological evolution and varied end-user requirements. Understanding these segments clarifies the distinct value propositions and competitive pressures influencing product development. This granular analysis facilitates targeted strategic planning for manufacturers.
Product Type:
The market for thermostatic faucets faces significant substitution pressure from advanced digital and sensor-based technologies displacing traditional mechanical units.
- Sensor-Activated:Sensor-Activated models incorporate infrared or capacitive sensors for touchless operation, enhancing hygiene and convenience. Demand concentrates in public facilities and healthcare settings, driven by stringent infection control protocols and user experience improvements.
- Digital Thermostat:Digital Thermostat faucets utilize electronic sensors and microprocessors for precise temperature control, offering features like personalized presets and remote activation. High-end residential and smart hospitality projects in Germany increasingly adopt these units for their advanced functionality and integration capabilities.
- Single-Handle:Single-Handle units combine temperature and flow control in one lever, representing a foundational, cost-effective product category.
- Double-Handle:Double-Handle faucets offer separate controls for hot and cold water, providing traditional aesthetics and manual temperature mixing.
Single-Handle faucets anchor the volume base while Digital Thermostat models gain share at the steepest rate.
Installation Type:
Installation types for thermostatic faucets are primarily dictated by the architectural design and functional requirements of the specific application environment.
- Wall-Mounted:Wall-Mounted faucets are installed directly into the wall, offering a sleek, minimalist aesthetic and simplifying cleaning around the basin. Commercial and hospitality projects frequently specify these for their durability and space-saving design.
- Deck-Mounted:Deck-Mounted faucets are fitted onto the countertop or basin, representing the most common installation method for residential and standard commercial bathrooms. Their ease of installation contributes to broad market penetration.
- Freestanding:Freestanding faucets stand independently on the floor, typically paired with bathtubs or large basins in luxury residential settings.
- Under-Counter:Under-Counter installations conceal the main faucet body beneath the counter, leaving only the spout and controls visible for a clean look.
Deck-Mounted installations maintain their mature market presence, while Wall-Mounted options demonstrate consistent growth in modern construction projects.
Feature:
The feature set of thermostatic faucets directly correlates with their value proposition and potential for higher margins, particularly in specialized applications.
- Temperature Control:Temperature Control is the core functionality, ensuring consistent water output within ±1°C to prevent scalding and enhance user comfort. This fundamental feature underpins adoption across all end-user segments, from residential to healthcare.
- Water Conservation:Water Conservation features incorporate flow rate limiters and efficient aerators, aligning with mandates like the US EPA's WaterSense program and Australia's WELS scheme. These features are critical for commercial buildings and hotels aiming to reduce operational costs.
- Safety Locks:Safety Locks prevent accidental temperature adjustments beyond a safe threshold, crucial for child safety and anti-scald protection.
- User Programmed Settings:User Programmed Settings allow individuals to pre-set preferred temperatures and flow rates, enhancing personalization and convenience in smart home systems.
Temperature Control remains a non-negotiable feature, with Water Conservation increasingly influenced by global regulatory frameworks.
End User:
End-user segmentation reveals distinct purchasing behaviors and specification drivers, with volume varying significantly across residential and commercial applications.
- Residential:Residential applications represent the largest segment by volume, driven by new construction and renovation projects focused on comfort, safety, and water efficiency. Homeowners increasingly seek advanced features for daily convenience.
- Hospitality:The Hospitality sector demands thermostatic faucets to enhance guest safety, improve operational efficiency, and elevate the overall user experience. This segment offers higher-margin opportunities due to bulk purchasing and premium specifications.
- Commercial:Commercial end-users, including offices and public buildings, prioritize durability, water efficiency, and compliance with local building codes.
- Healthcare Facilities:Healthcare Facilities require advanced hygiene features, anti-scald protection, and touchless operation to meet stringent infection control protocols.
Residential installations form the foundational demand, while Hospitality and Healthcare Facilities demonstrate accelerated adoption for specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for thermostatic faucets exhibits regional asymmetry, with mature European markets like Germany commanding higher value due to premium demand. Conversely, emerging economies in Southeast Asia often prioritize mid-range affordability, influencing product specifications. This divergence shapes market entry strategies and product development across different regions.
Germany
Extensive renovation activities and stringent building codes drive demand for advanced thermostatic faucets in Germany. The EU's Ecodesign Directive influences product development, mandating water and energy efficiency standards. Major manufacturing hubs in Bavaria focus on precision engineering and high-end digital thermostat models for both domestic and export markets.
United States
Residential and commercial new construction projects in the United States demand thermostatic faucets for comfort and water efficiency. The US EPA's WaterSense program sets performance benchmarks for flow rate limits and conservation. Green building initiatives in California accelerate the adoption of efficient plumbing fixtures, influencing national trends.
Australia
Water scarcity and high safety standards propel the adoption of thermostatic faucets across Australian residential and commercial sectors. Australia's WELS scheme imposes stringent flow rate limits, compelling manufacturers to engineer efficient products. High-end residential developments in Sydney frequently specify advanced thermostatic units for their efficiency and modern design.
India
Rapid urbanization and a growing middle class in India generate demand for mid-range thermostatic faucets, emphasizing safety and convenience. BIS standards increasingly influence product quality and performance benchmarks for plumbing fixtures. Booming real estate developments in the Delhi-NCR region are integrating modern bathroom solutions, including thermostatic options.
France
Renovation activities and a strong hospitality sector in France contribute significantly to thermostatic faucet demand, prioritizing design and efficiency. CE marking requirements ensure product safety and compliance with European Union construction product regulations. Luxury hotel projects in Paris are increasingly specifying premium thermostatic fixtures to enhance guest experience.
Thermostatic Faucet Market Key Industry Players
Concentration sits with established plumbing fixture manufacturers possessing extensive distribution networks and brand recognition. The market structure exhibits a tiered consolidation, with a few global leaders dominating the premium segments. Strategic archetypes include precision engineering specialists, smart home ecosystem integrators, and broad portfolio managers. Dominant competitive moves involve portfolio diversification, technology integration to capture diverse market needs, and strategic partnerships to expand geographic reach.
Within the precision engineering and design leadership archetype, Grohe AG, a German-based company, sustains its premium position, particularly in European markets. Kohler Co., an American-based corporation, exemplifies smart home ecosystem compatibility, differentiating its offerings through integrated technology solutions. LIXIL Corporation, a Japanese-based entity, represents the broad portfolio manager archetype, leveraging its extensive brand collection to capture diverse regional preferences across various price points.
| Leading Market Players |
|---|
| Grohe AG |
| Kohler Co. |
| Moen Incorporated |
| Cera Sanitaryware Ltd. |
| Roca Sanitario S.A.U. |
| Jaquar Global |
| Geberit AG |
| LIXIL Corporation |
| Masco Corporation |
| Others |
Cost & Logistics Intelligence
Project-based procurement for high-volume commercial installations locks in both supply access and price visibility for thermostatic faucets. This structured approach mitigates volatility in component costs and ensures delivery timelines for large-scale developments.
Pricing Analysis
Configured-to-order pricing for advanced digital thermostat models commands a premium over standard, transactional per-unit pricing for single-handle units. Price differentiation stems from brand recognition and specific regional certifications like CE marking. Pricing softness reflects intense competition in the cost-sensitive residential new construction segment. Hospitality and healthcare facilities exhibit lower price sensitivity due to specialized feature requirements.
Supply Chain Analysis
Component sourcing concentration in specialized manufacturers for critical thermostatic mixing valves creates a supply chain chokepoint. Geographic supply for precision parts centers in Germany and China, with broader assembly across Europe and Asia. Raw material dependencies include brass, stainless steel, and specialized polymers for wax elements. Single-source vulnerability for these core components represents a significant structural risk, while distribution runs through established plumbing wholesalers and direct-to-project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermostatic faucet market faces a critical capability gap in integrating digital thermostat R&D with scaled mechanical valve manufacturing. Bridging this skill disparity is essential for unlocking future growth and maintaining competitive advantage.
For Market Incumbents:Secure intellectual property rights for advanced digital control algorithms to counter emerging smart home ecosystem integrators. Deepen vertical integration into specialized thermostatic mixing valve components to mitigate single-source vulnerability. Invest in R&D for touchless controls and automated disinfection cycles, addressing the rising hygiene demands from healthcare and hospitality sectors. Maintain strong relationships with regulatory bodies to influence future water efficiency standards.
For New Entrants and Emerging Players:Certification fast-track programs for WELS and WaterSense compliance offer a clear entry point into regulated markets like Australia and the US. Target the mid-range residential renovation segment in rapidly urbanizing Southeast Asian countries with cost-effective, safety-focused models. Leverage digital-first go-to-market strategies, emphasizing smart home compatibility and personalized user settings. Focus on modular designs to simplify installation in diverse legacy plumbing configurations.
For Investors and Strategic Acquirers:Technology-forward innovators specializing in digital thermostatic valves represent attractive acquisition targets for long-term growth. The market offers viable opportunities over a five to ten-year window as digital precision displaces mechanical reliability. Seek companies with strong patent portfolios in sensor technology or smart home integration capabilities. The signal to watch is the accelerating adoption rate of digital thermostat models in high-end commercial projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Control Platform Development | Establishes a proprietary ecosystem, differentiating offerings for smart home compatibility and personalized settings. |
| Component Vertical Integration | Secures critical thermostatic mixing valve supply, reducing reliance on external specialized manufacturers. |
| Global Certification Expansion | Broadens market access by meeting diverse regional regulations like CE marking and WELS schemes. |
| Healthcare-Specific Product Line | Addresses stringent infection control protocols with touchless controls and automated disinfection features for hospitals. |
| Emerging Market Distribution Partnerships | Penetrates untapped regions like Southeast Asia, leveraging local networks for mid-range product delivery. |
Research Approach
A spread of perspectives from R&D directors, procurement leads, hospitality managers, and regulatory compliance officers converged on the working assumptions for this thermostatic faucet market analysis. Primary interviews were combined with secondary validation from governmental reports, industry association publications, and company financial disclosures. This approach ensured comprehensive data collection and robust bottom-up and top-down triangulation.
Product type, installation type, feature set, and end-user segmentation dimensions were rigorously modeled across the analysis window. The analytical framework integrated historical market trends with projected adoption rates to derive compound annual growth rates. Key forecast inputs included new construction starts in Germany and water conservation mandate updates like the EU's Ecodesign Directive.
Decision-makers should treat outputs as directional under current regulatory stability and supply chain configurations; material deviation would warrant model refresh. Forecasts reflect these base assumptions. Practitioners should keep alternative scenarios live as component sourcing and smart home integration trends evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Reverse Flame Steam Boiler Market