
 HVAC and Fire Protection Insulation Market | 2026-2036
HVAC and Fire Protection Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC and Fire Protection Insulation Market Outlook
Multi-source procurement for engineered insulation systems is realigning how contractors manage project risk across commercial and industrial builds. Owens Corning leverages its fiberglass manufacturing scale to serve large-format HVAC ductwork contracts. Rockwool International anchors its position through stone wool formulations that address combined thermal and fire-rated specifications. Armacell International specializes in elastomeric foam solutions for chilled water and refrigeration lines where condensation control determines material selection.
HVAC and fire protection insulation comprises engineered thermal barriers and intumescent or non-combustible materials designed to retard heat transfer, inhibit flame propagation, and maintain system operating temperatures within specified ranges, typically rated by ASTM E84 surface burning characteristics or EN 13501 reaction-to-fire classifications. Mineral wool dominates fire-stopping and high-temperature HVAC applications due to its melting point above 1,000°C and non-combustible fiber matrix. Foam board insulation captures margin pools in commercial envelope assemblies where continuous insulation requirements outpace cavity-fill alternatives. Spray foam insulation competes for retrofit projects and complex geometries where air sealing performance offsets higher installed costs.
OSHA mandates workplace exposure limits for synthetic mineral fibers, while the EPA regulates blowing agents and VOC emissions from spray foam formulations, pushing manufacturers toward low-GWP alternatives. The EU Green Deal and F-Gas Regulation collectively tighten embodied carbon thresholds and thermal transmittance requirements across member states, redirecting specification decisions toward verified Environmental Product Declarations. Stakeholders must monitor evolving fire safety codes alongside decarbonization timelines, as jurisdictions begin linking building performance certificates to financing access and occupancy permits.
Market Dynamics
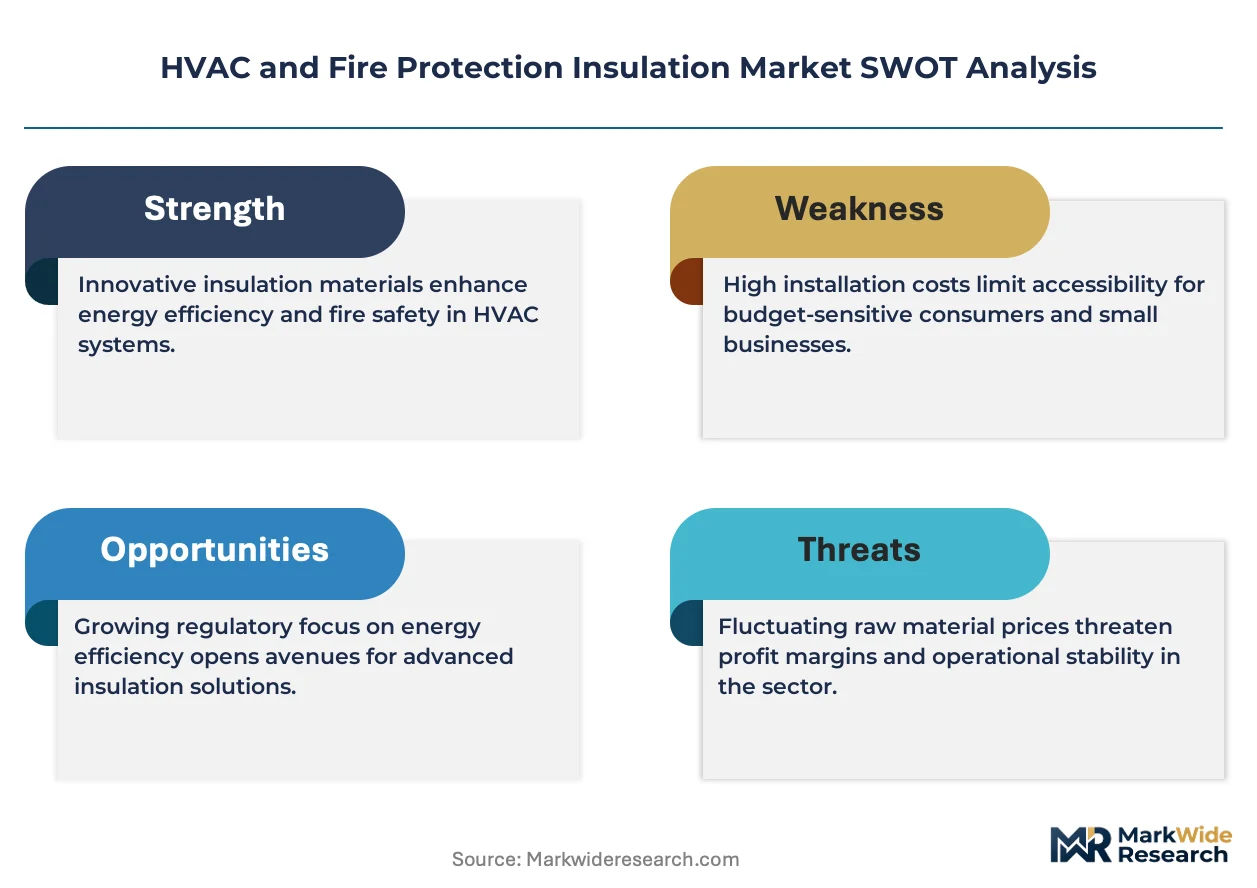
District heating retrofits across Germany and passive house mandates are compressing specification cycles for mineral wool and foam board systems, forcing contractors to pre-qualify multi-material suppliers before bid submission.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon blowing agents are redirecting foam insulation procurement toward low-GWP alternatives and certified Environmental Product Declarations.
- Data center construction:Hyperscale campus builds in Virginia, Frankfurt, and Singapore are expanding mechanical insulation procurement for chilled water distribution and fire-rated containment systems.
- Stone wool formulations:Combined thermal and fire-rated performance in a single specification is reducing contractor material-handling complexity on high-rise commercial envelopes.
Market Restraints
- Mineral fiber input volatility:Basalt and slag availability fluctuates with steel production cycles, compressing margin predictability for stone wool manufacturers.
- OSHA exposure limits:Synthetic mineral fiber workplace thresholds raise compliance costs for installation crews and retrofit contractors in the US.
- Spray foam substitution ceiling:High installed costs and VOC emission controls limit penetration in cost-sensitive residential HVAC retrofits.
Strategic Opportunities
- India commercial build-out:Bureau of Indian Standards fire safety upgrades and cooling degree-day expansion are creating specification windows for elastomeric and mineral wool systems.
- Building performance certificates:EU member states linking energy ratings to financing access and occupancy permits are accelerating premium insulation upgrades.
- Prefabrication convergence:Off-site panel assembly with integrated MEP routing is expanding factory-applied insulation demand for ductwork and piping modules.
Industry Challenges
- Certification timeline compression:EN 13501 and ASTM E84 testing backlogs delay product launches and contract eligibility for reformulated materials.
- Multi-material integration:Coordinating mineral wool fire-stopping with foam board thermal continuity creates detailing conflicts at envelope penetrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC and Fire Protection Insulation Market |
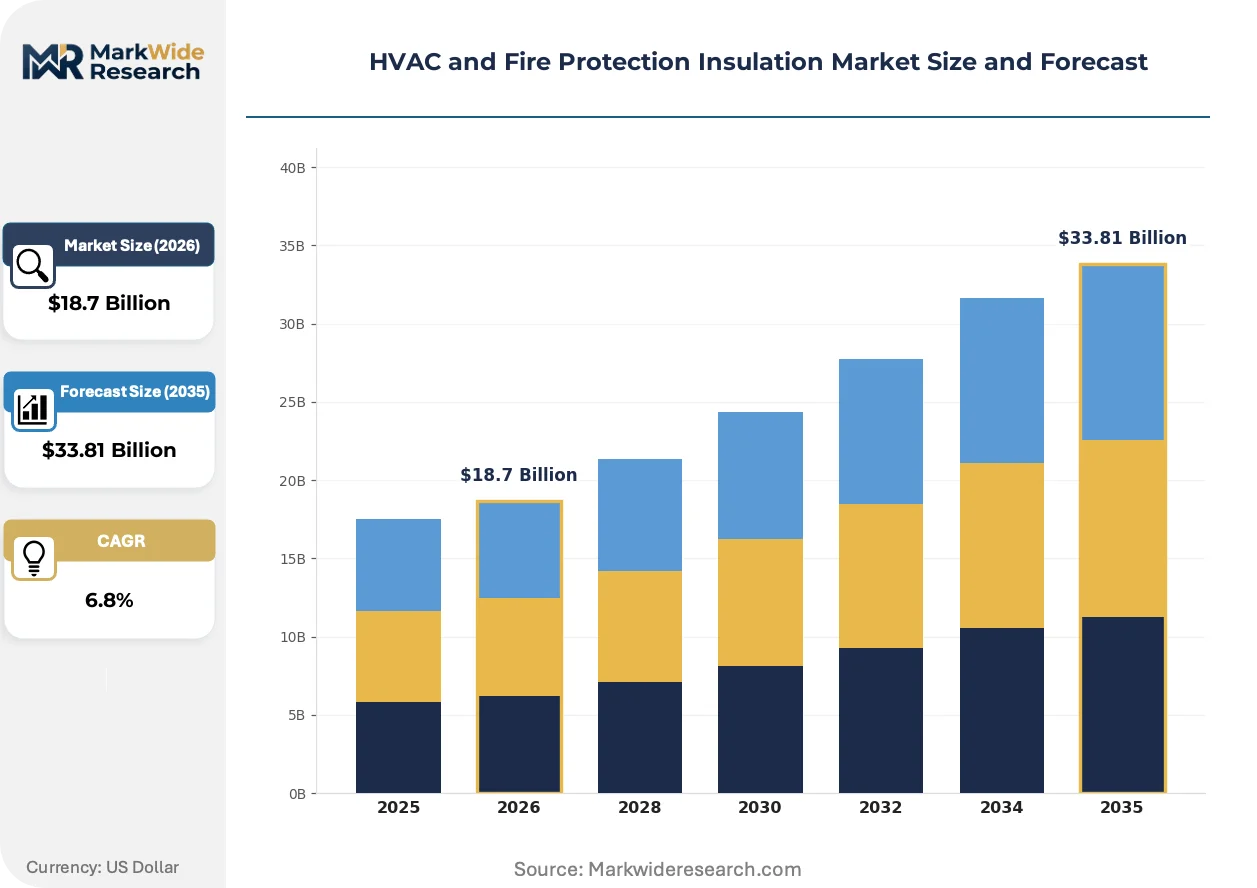
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass Insulation, Foam Board Insulation, Mineral Wool, Spray Foam Insulation Application: Residential Buildings, Commercial Spaces, Industrial Facilities, HVAC Systems End User: Contractors, Architects, Facility Managers, Building Owners Installation Method: New Construction, Retrofit Projects, DIY Installations, Professional Installations |
| Companies Covered | Johns Manville, Kingspan Group, Owens Corning, PPG Industries, Armacell International, Rockwool International, Saint-Gobain, Glassrock Insulation, Knauf Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC and Fire Protection Insulation Market Strategic Shifts
Aerogel composites and bio-based blowing agents are repositioning material hierarchies as embodied carbon metrics enter procurement scorecards alongside thermal performance.
Aerogel blanket insulation is expanding into high-value HVAC applications where space constraints and thermal bridging control outweigh premium pricing. Pharmaceutical cleanrooms and semiconductor fabrication facilities in Switzerland and South Korea specify these materials for compact mechanical shafts. The technology is expanding into territory previously held by multi-layer mineral wool assemblies, compressing installed thickness requirements by half.
The EU Green Deal's embodied carbon thresholds are tightening thermal transmittance requirements across member states, redirecting specification decisions toward verified Environmental Product Declarations. Manufacturers must now submit cradle-to-grave lifecycle data alongside traditional performance metrics. Commercial envelope assemblies in Germany and the Netherlands face the steepest compliance ramps, with building codes updating every 24-36 months.
Buyer consolidation among mechanical contractors is compressing supplier qualification cycles and favoring multi-product distributors over single-material specialists. Large-format HVAC contractors in Texas and Bavaria now demand turnkey insulation packages spanning duct liner, pipe wrap, and fire-stopping from one source. This pattern is most visible in data center and healthcare verticals where single-source accountability reduces interface risk.
HVAC and Fire Protection Insulation Market Segmentation
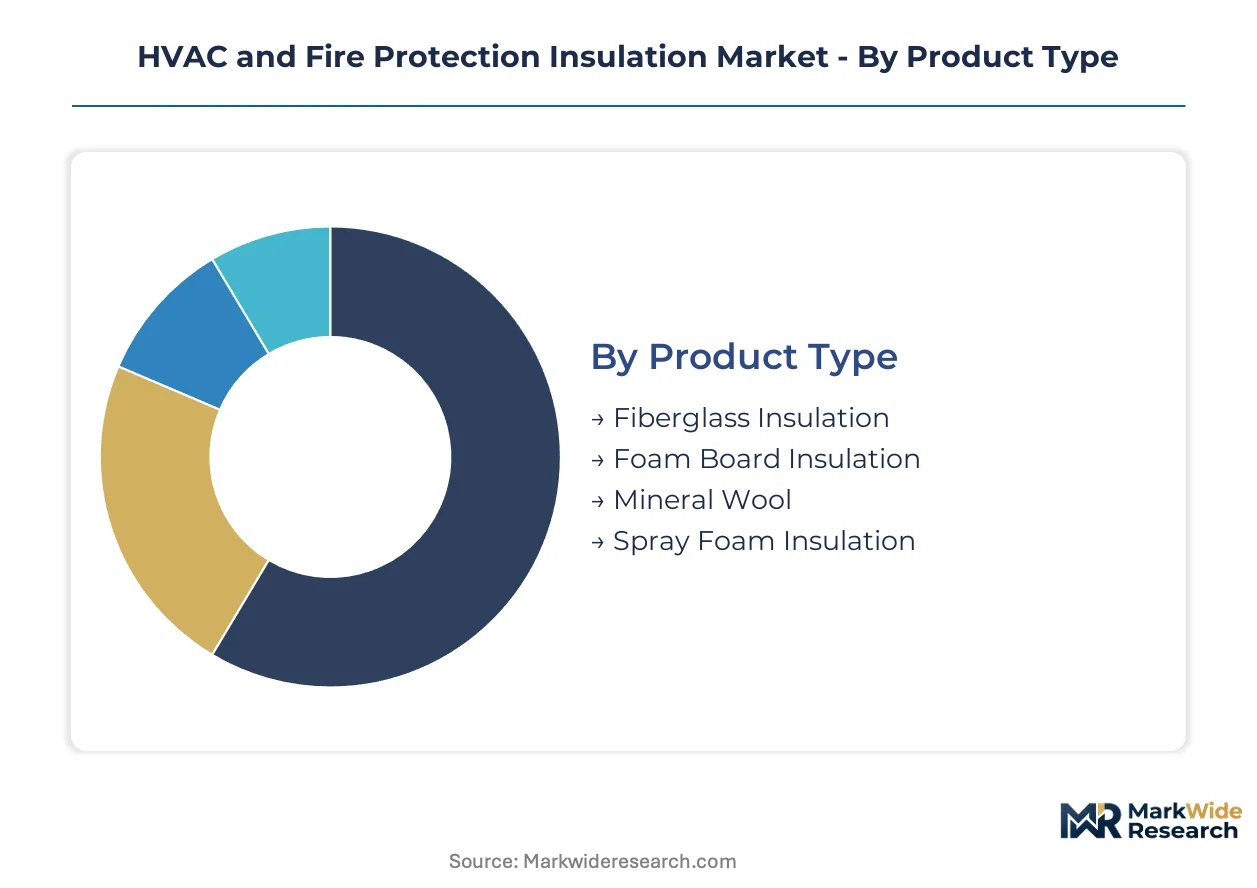
Material selection in HVAC and fire protection insulation hinges on thermal performance ratings, fire resistance classifications, and installation constraints that vary sharply across building types and regulatory environments. Specification decisions cascade through supply chains differently for new construction versus retrofit work, creating distinct procurement patterns within each segment cluster.
Product Type:
Supply concentration among mineral wool and fiberglass manufacturers shapes availability and pricing dynamics across specification tiers.
- Mineral Wool:Non-combustible stone wool fibers withstand temperatures exceeding 1,000°C, making this material mandatory for fire-stopping penetrations and high-temperature HVAC ductwork in Germany and other EU member states with stringent reaction-to-fire requirements under EN 13501. District heating retrofits across German cities compress procurement cycles for stone wool systems as contractors pre-qualify suppliers before bid submission.
- Fiberglass Insulation:Lightweight glass fiber matrices dominate large-format HVAC ductwork contracts where thermal resistance and acoustic dampening converge in single specifications. Owens Corning and similar scaled manufacturers serve hyperscale data center campuses in Virginia and Frankfurt through high-volume supply agreements that lock in multi-year procurement schedules.
- Foam Board Insulation:Rigid polyisocyanurate and extruded polystyrene boards capture commercial envelope assemblies where continuous insulation requirements outpace cavity-fill alternatives. The EU F-Gas Regulation's hydrofluorocarbon phase-down redirects procurement toward low-GWP blowing agent formulations with certified Environmental Product Declarations.
- Spray Foam Insulation:Polyurethane formulations compete for complex geometries and air sealing performance in retrofit projects where installed thickness must minimize. VOC emission controls and high material costs limit penetration in cost-sensitive residential HVAC applications.
Mineral wool absorbs the bulk of installed capacity in fire-rated specifications; spray foam insulation is expanding most quickly in retrofit niche applications where air tightness premiums justify material costs.
Application:
Cost tier differentiation separates specification cycles, with industrial and data center projects commanding premium material grades while residential builds face sharper price sensitivity.
- Commercial Spaces:High-rise envelopes and mixed-use developments require coordinated fire-stopping and thermal continuity across envelope penetrations, creating detailing conflicts that contractors resolve through multi-material supplier consolidation. Building performance certificates linked to financing access in the Netherlands and Germany accelerate specification upgrades.
- HVAC Systems:Chilled water distribution, refrigeration lines, and mechanical shafts demand materials selected for condensation control and space constraints. Pharmaceutical cleanrooms in Switzerland and semiconductor fabrication facilities in South Korea specify aerogel composites where thermal bridging control outweighs premium pricing.
- Industrial Facilities:Process piping and equipment insulation must withstand mechanical abuse and chemical exposure while maintaining thermal performance across wide temperature differentials.
- Residential Buildings:Cost-sensitive single-family and multifamily construction favors fiberglass batts and blown-in cellulose alternatives, with spray foam penetration limited to high-performance builds targeting passive house certification.
Commercial spaces command the largest material volumes; HVAC systems applications are climbing the fastest as data center construction expands mechanical insulation procurement.
End User:
Volume concentration among large mechanical contractors compresses supplier qualification cycles and favors turnkey insulation packages over single-material sourcing.
- Contractors:Large-format HVAC contractors in Texas and Bavaria demand single-source accountability spanning duct liner, pipe wrap, and fire-stopping to reduce interface risk on data center and healthcare verticals. Buyer consolidation forces distributors to carry multi-product portfolios or exit specification-driven segments.
- Facility Managers:Building operations teams prioritize lifecycle cost and ease of replacement access in retrofit decisions, often selecting materials with established maintenance protocols over higher-performing alternatives.
- Architects:Design professionals specify materials based on embodied carbon metrics and Environmental Product Declarations as EU Green Deal thresholds tighten across member states, particularly in Germany and the Netherlands where building codes update every 24-36 months.
- Building Owners:Institutional and corporate owners link insulation specification to energy rating targets that affect asset valuation and financing terms, creating procurement urgency around certified performance data.
Contractors absorb the bulk of installed capacity through direct procurement; building owners are gaining share fastest as performance certificates tie insulation grades to financing access.
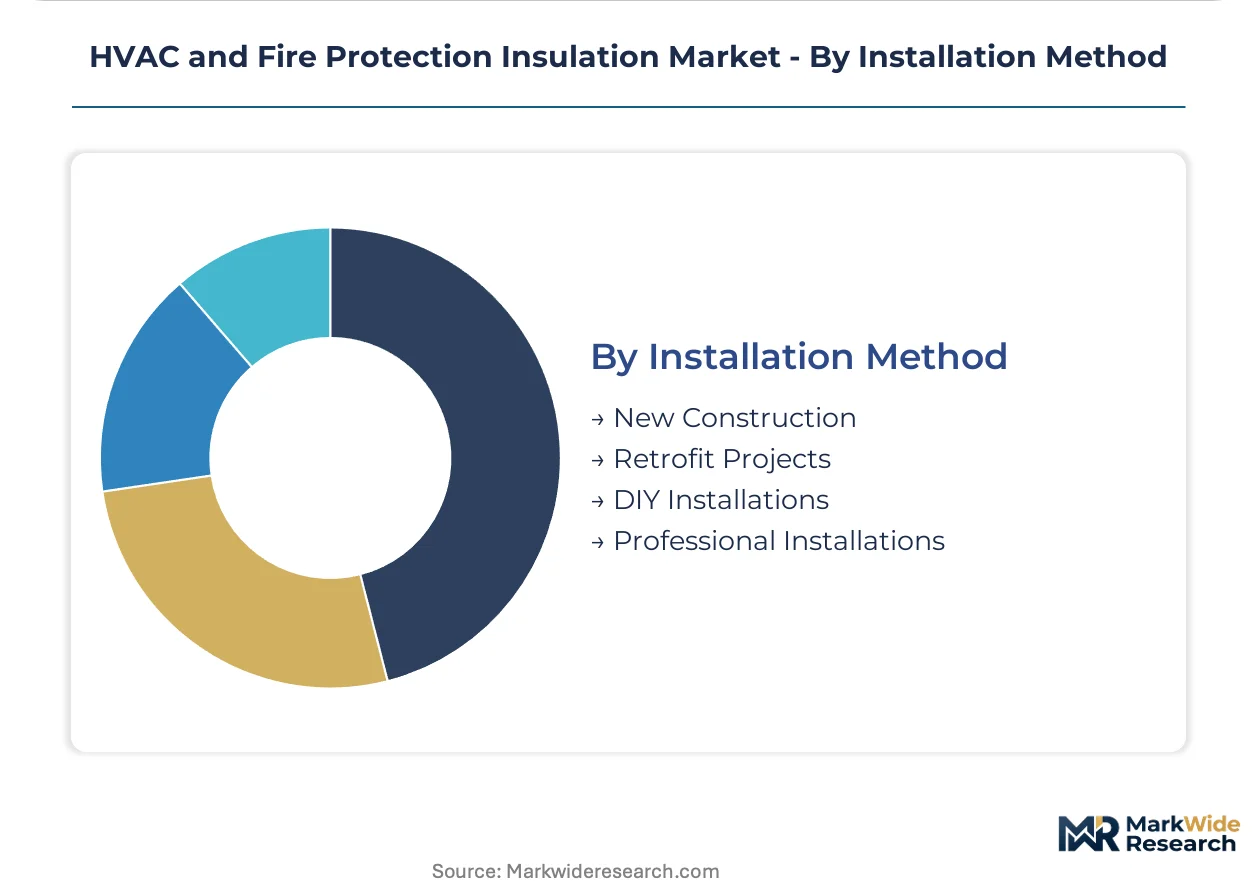
Installation Method:
Maturity differentiation separates established professional installation channels from emerging prefabrication models that relocate insulation work to factory environments.
- New Construction:Integrated project delivery models allow insulation specification during early design phases, enabling material optimization and waste reduction through BIM-coordinated procurement. Off-site panel assembly with integrated MEP routing expands factory-applied insulation demand for ductwork and piping modules.
- Professional Installations:Certified crews handle complex fire-stopping and high-performance envelope assemblies where warranty coverage and code compliance documentation prove essential for occupancy permitting.
- Retrofit Projects:Existing building upgrades face access constraints and contamination risks that favor spray foam and aerogel blankets where space limitations preclude conventional thickness requirements. OSHA exposure limits for synthetic mineral fibers raise compliance costs for US retrofit contractors.
- DIY Installations:Consumer-grade fiberglass batts and rigid foam boards serve residential attic and basement projects where code enforcement remains limited and performance verification is absent.
New construction absorbs the bulk of installed capacity; retrofit projects are gaining share fastest as building performance certificates accelerate existing building upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction and district heating retrofits concentrate procurement volumes in Germany, the United States, and Singapore, while regulatory tightening across the EU and Asia-Pacific redirects specification decisions toward low-carbon alternatives.
Germany
District heating network expansions in Berlin and Hamburg drive mineral wool procurement for high-temperature distribution systems. The EU F-Gas Regulation's hydrofluorocarbon phase-down accelerates foam board specification toward certified Environmental Product Declarations. Passive house construction clusters in Bavaria and Baden-Württemberg compress supplier qualification cycles for multi-material systems.
United States
Hyperscale data center campuses in Virginia and Texas expand mechanical insulation procurement for chilled water distribution and fire-rated containment. OSHA workplace exposure limits for synthetic mineral fibers raise compliance costs for installation crews across retrofit markets. The Southeast's cooling degree-day expansion creates specification windows for elastomeric foam systems in commercial HVAC.
Singapore
Tropical data center construction demands condensation control materials for high-humidity mechanical environments. The city-state's Green Mark certification program ties building performance ratings to financing access, accelerating premium insulation upgrades. Semiconductor fabrication facilities anchor specification demand for space-constrained thermal solutions.
India
Bureau of Indian Standards fire safety upgrades in Maharashtra and Gujarat create procurement windows for mineral wool and elastomeric systems. Cooling degree-day expansion across Delhi-NCR and Bangalore drives commercial HVAC insulation specification. Large-format infrastructure projects compress contractor supplier qualification timelines.
Netherlands
Building performance certificates linked to occupancy permits accelerate envelope insulation upgrades in Randstad commercial developments. The EU Green Deal's embodied carbon thresholds redirect specification toward verified lifecycle data. Rotterdam and Amsterdam district heating retrofits concentrate demand for stone wool fire-stopping and thermal continuity systems.
HVAC and Fire Protection Insulation Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers scale mineral wool and foam board production to serve data center and district heating procurement waves. The vendor base separates into three tiers: integrated multinational suppliers with multi-product portfolios, regional specialists anchored in single material categories, and emerging fabricators targeting prefabrication convergence. Strategic archetypes include scale-driven fiberglass manufacturers, fire-rated stone wool formulators, and elastomeric foam specialists. M&A activity and geographic expansion represent the primary competitive vectors as contractors consolidate procurement around turnkey insulation packages.
Among the integrated multinational tier, Owens Corning, Rockwool International, and Armacell International exemplify distinct positioning archetypes. Owens Corning represents scale-driven fiberglass manufacturing serving large-format HVAC ductwork contracts through high-volume supply agreements. Rockwool International anchors the fire-rated specification segment with stone wool formulations addressing combined thermal and non-combustible requirements. Armacell International occupies the elastomeric specialization position for chilled water and refrigeration applications where condensation control determines material selection. These three entities collectively illustrate how procurement consolidation favors suppliers offering multi-product accountability across duct liner, pipe wrap, and fire-stopping categories.
| Leading Market Players |
|---|
| Johns Manville |
| Kingspan Group |
| Owens Corning |
| PPG Industries |
| Armacell International |
| Rockwool International |
| Saint-Gobain |
| Glassrock Insulation |
| Knauf Insulation |
| Others |
Value Chain & Pricing Dynamics
Basalt and slag price indices cascade through stone wool manufacturing into three-tier pricing structures across premium, standard, and economy levels, compressing margins for mid-tier producers while integrated multinationals absorb volatility through captive mineral sourcing. Contractors in Germany and Texas face compressed bid windows as raw material swings transmit into project-based quotations within 30-day cycles.
Pricing Analysis
High-volume supply agreements dominate large-format HVAC contracts, while spot purchasing governs retrofit mineral wool procurement. Price differentiation rests on EN 13501 certification grade and geographic delivery radius from manufacturing clusters. Cost compression in standard-grade fiberglass intensifies as Owens Corning and Knauf Insulation expand Virginia and Bavaria capacity. Residential retrofit contractors exhibit acute price sensitivity; data center developers prioritize thermal performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese basalt processing and German slag recovery networks, exposing stone wool producers to steel production cycle volatility. Raw material flows draw from Norwegian olivine mines, Belgian glass cullet recyclers, and Saudi petrochemical complexes for foam blowing agents. Tariff exposure on Chinese mineral fiber imports threatens US distributor margins. Distribution runs through multi-product HVAC wholesalers consolidating around turnkey insulation packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's hydrofluorocarbon phase-down creates a cost-of-compliance moat favoring manufacturers with certified Environmental Product Declarations and low-GWP formulation capabilities, raising barriers for uncertified competitors.
For Market Incumbents: To counter mineral fiber input volatility, secure backward integration into slag recovery networks through steel mill partnerships or long-term offtake agreements with Norwegian basalt quarries. Expand factory-applied insulation capacity in Texas and Bavaria to capture prefabrication convergence demand from data center contractors consolidating procurement. For New Entrants and Emerging Players: Enter via India's Bureau of Indian Standards fire safety upgrade cycle, targeting Maharashtra and Gujarat commercial build-outs where elastomeric and mineral wool specification windows remain underpenetrated. Pursue aerogel composite distribution partnerships with Swiss pharmaceutical cleanroom contractors seeking space-constrained thermal solutions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap stone wool formulators with EN 13501 testing backlogs in the Netherlands and Germany, where building performance certificate mandates accelerate consolidation. Watch for EU Green Deal embodied carbon threshold tightening as the inflection signal triggering premium insulation asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Recovery | Captive basalt and slag sourcing insulates Owens Corning and Rockwool International from steel cycle volatility. |
| Low-GWP Blowing Agent Transition | Armacell International's reformulation investments align foam production with EU F-Gas Regulation phase-down schedules. |
| Factory-Applied Insulation Capacity Expansion | Off-site panel assembly with integrated MEP routing captures data center contractor consolidation in Virginia and Frankfurt. |
| Environmental Product Declaration Certification | Verified cradle-to-grave lifecycle data satisfies Netherlands and Germany building code updates every 24-36 months. |
| Aerogel Composite Distribution Partnerships | Swiss pharmaceutical cleanroom and South Korean semiconductor facility specifications reward thermal bridging control premiums. |
Study Parameters
Document review covered regulatory filings from EPA and EU ECHA, trade data from Eurostat and USITC, and manufacturer sustainability disclosures, complemented by interviews with HVAC contractor procurement directors, mechanical engineer specification leads, distributor inventory managers, and building code compliance officers. Secondary validation drew from EN 13501 test laboratory records, ASTM E84 certification databases, and district heating utility capital expenditure plans. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Historical capacity utilization rates cross-referenced against panel input from insulation specification consultants and data center EPC contractors informed the analytical framework across the analysis window. Segmentation dimensions modeled include material type, application thermal requirements, end-user procurement scale, and installation method complexity. CAGRs derived from slope-intercept fitting of verified installation volumes against construction permit data, with mineral wool fire-stopping and elastomeric foam chilled water specifications as industry-specific demand anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Green Deal acceleration or OSHA synthetic mineral fiber threshold tightening. Projections reflect assumptions on district heating retrofit pace, data center construction cadence, and low-GWP blowing agent cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
North America Scrubber System Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Cold Insulation Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
US Commercial HVAC Rooftop Units Market