
 Europe District Cooling Pipeline Network Market | 2026-2036
Europe District Cooling Pipeline Network Market Size, Share, and Industry Trends Forecast 2026-2036
Europe District Cooling Pipeline Network Market Analysis
Commercial real estate portfolios are collapsing into district cooling contracts as landlords face mounting pressure to decarbonize base building systems. Veolia anchors its position through captive operation contracts across French business districts. ENGIE competes with integrated design-build offerings that bundle substation engineering with long-term energy supply agreements. Vattenfall dominates Nordic urban networks by leveraging its legacy district heating tunnel infrastructure for seasonal cooling expansion.
Europe District Cooling Pipeline Network denotes the buried and aboveground conduit systems—typically pre-insulated steel, cross-linked polyethylene, or composite pipes rated for 5–15 bar operating pressure—that transport chilled water or ice slurry from central plants to multiple end users. These networks eliminate distributed refrigeration machinery at individual buildings, cutting peak electrical demand and refrigerant leakage risk. Underground infrastructure commands the largest installed base given municipal aesthetic requirements and right-of-way constraints in historic European city centers. Chilled water technology leads by volume, though thermal energy storage is gaining traction where utilities seek to arbitrage day-night electricity spreads. Mixed-use developments represent the fastest-growing end user category as planners consolidate residential towers, retail podiums, and office blocks under single thermal master plans.
The EU Green Deal and F-Gas Regulation tighten refrigerant phase-down schedules, pushing building operators toward water-based district solutions that eliminate on-site synthetic coolant stocks. ECHA oversees material compliance for pipe insulation chemistries under REACH, while CE marking mandates pressure equipment safety validation across member states. Stakeholders must track how national transpositions of the Energy Performance of Buildings Directive rewrite connection obligations for large commercial refurbishments.
Market Dynamics
The EU F-Gas Regulation is compressing synthetic refrigerant availability across member states, forcing building operators toward water-based distribution architectures that eliminate on-site coolant stocks entirely. This regulatory compression is restructuring capital allocation across the district cooling value chain.
Growth Catalysts
- EU Green Deal decarbonization mandates:National transpositions of the Energy Performance of Buildings Directive now require large commercial refurbishments to connect to district thermal networks where available.
- Data center thermal load concentration:Hyperscale facilities in Northern Europe are anchoring new pipeline extensions as server density exceeds 50 kW per rack.
- Pre-insulated composite pipe advances:Cross-linked polyethylene and glass-reinforced epoxy systems are cutting installation labor hours by half versus legacy steel.
Market Restraints
- Copper and steel input volatility:Pre-insulated pipe manufacturers face margin compression when base metal prices spike, with limited pass-through in municipal tender structures.
- Right-of-way scarcity in historic cores:UNESCO-protected city centers across Italy and Belgium block trenching permits, fragmenting network continuity.
- Air-source heat pump substitution:Distributed electric cooling is capturing smaller commercial loads where pipeline connection fees exceed standalone system payback.
Strategic Opportunities
- Eastern European district heating conversion:Poland and Czech Republic legacy steam networks present retrofit potential for seasonal cooling injection.
- Thermal energy storage arbitrage:Ice and chilled water tanks enable utilities to flatten peak demand and capture day-night electricity spreads.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are pressuring real estate investment trusts to outsource thermal infrastructure to district operators.
Industry Challenges
- Specialized welding certification scarcity:District cooling pipeline installation demands EN 287-qualified pressure welders, with training pipelines failing to match project velocity.
- Legacy building system integration:Connecting 1970s-era HVAC plants to modern low-temperature district loops requires costly heat exchanger retrofits and controls upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe District Cooling Pipeline Network Market |
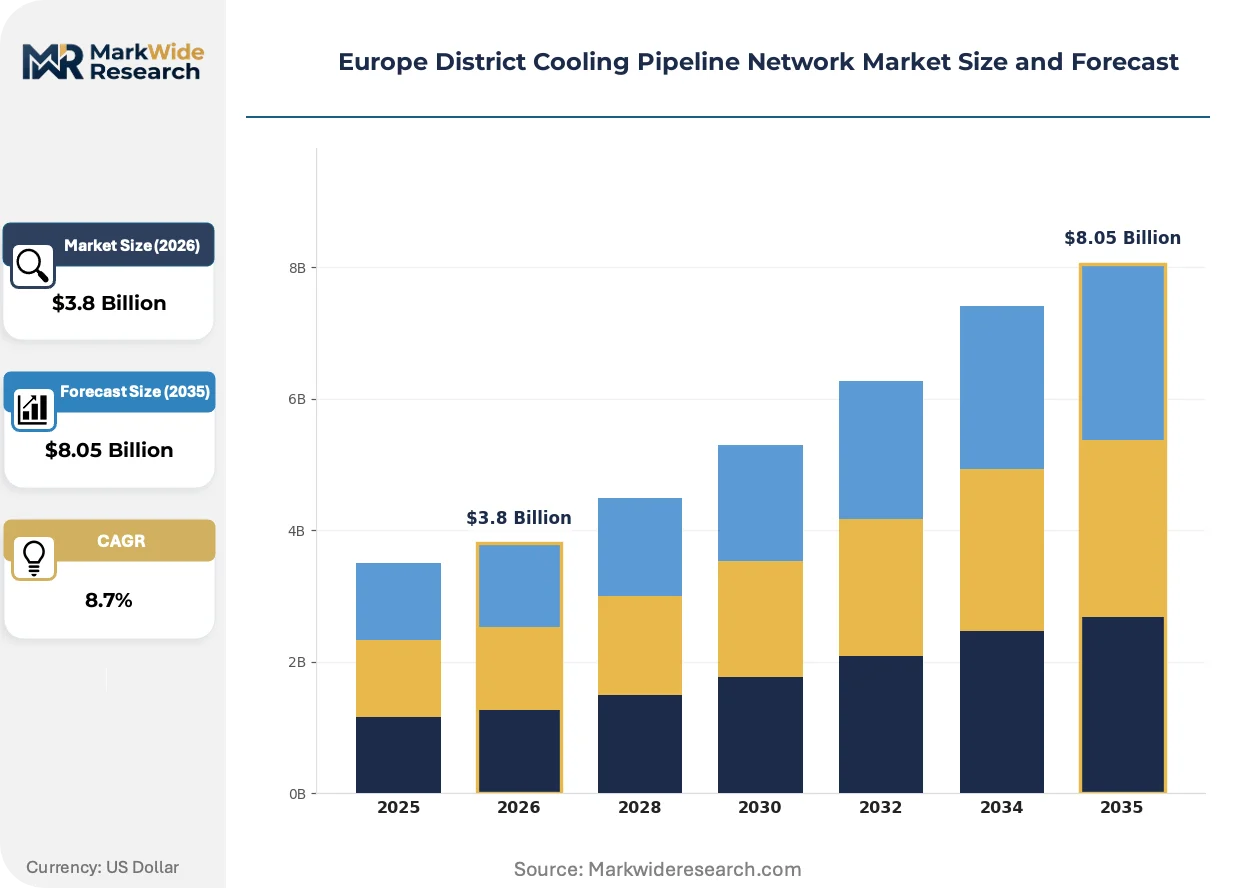
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Underground, Aboveground, Hybrid, Substation End User: Residential, Commercial, Industrial, Mixed-use Technology: Chilled Water, Ice Storage, Thermal Energy Storage, Direct Expansion Service Type: Design, Installation, Maintenance, Operation |
| Companies Covered | Aquatherm, Brugg Pipes, CPV Limited, Eval Europe, Future Pipe Industries, Veolia, ENGIE, Vattenfall, Fortum, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe District Cooling Pipeline Network Market Emerging Trajectories
Material substitution and regulatory chemistry constraints are rewriting procurement specifications across European district cooling infrastructure. Operators now prioritize corrosion-resistant, low-thermal-conductivity systems that minimize energy loss across extended distribution runs.
Cross-linked polyethylene (PEX-AL-PEX) composite piping is supplanting traditional carbon steel in secondary distribution loops. Swedish and Danish network operators are specifying PEX for campus-scale extensions where operating pressures stay below 10 bar. The shift is compressing maintenance budgets by eliminating cathodic protection systems and reducing leak repair frequency by two-thirds.
The EU F-Gas Regulation's phasedown schedule is tightening refrigerant quotas for building-scale chillers. Industrial operators in Germany and the Netherlands are responding by accelerating connection to district networks that centralize cooling production. The regulation is most acute for supermarket chains and pharmaceutical cold storage facilities with distributed refrigeration footprints.
Energy-as-a-service contracting is displacing traditional capex-heavy ownership models for cooling infrastructure. French and Spanish commercial landlords are signing 15-20 year thermal supply agreements that bundle pipeline connection, substation maintenance, and metered cooling delivery. The model is concentrating procurement authority with district utility procurement teams and compressing vendor sales cycles.
Europe District Cooling Pipeline Network Market Segmentation
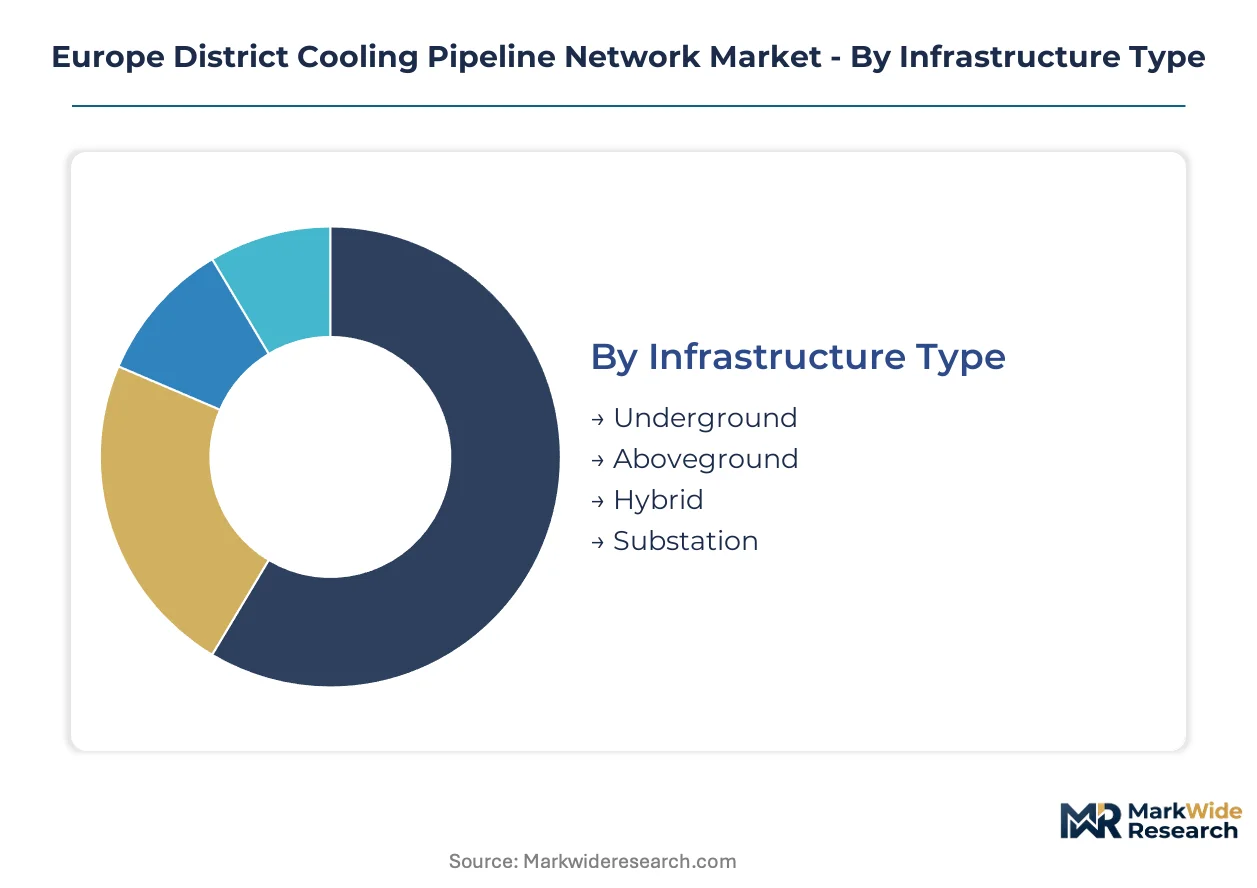
Segmentation across Europe's district cooling pipeline networks reveals how infrastructure investment, regulatory pressure, and end-use thermal loads concentrate capital deployment. Each dimension exposes distinct procurement patterns and margin structures across the value chain.
Infrastructure Type:
Geographic distribution of infrastructure types tracks municipal planning regimes and historic core protection status. Underground systems dominate Nordic and French urban networks where tunneling heritage supports deep burial. Aboveground installations concentrate in Eastern European industrial zones with fewer heritage constraints.
- Underground:Pre-insulated steel and composite pipes buried 1.5–3 meters below surface, rated for 50-year service life. Swedish and Danish utilities deploy these across Stockholm and Copenhagen historic districts where surface aesthetics are regulated. EU Green Deal connection mandates accelerate trenching permits in commercial zones.
- Aboveground:Elevated steel conduit on structural supports, common in industrial parks and data center campuses. Polish and Czech operators favor these for seasonal cooling extensions to legacy district heating networks. Installation avoids archaeological survey delays that stall underground projects.
- Hybrid:Mixed burial strategies combining deep urban tunnels with surface distribution laterals. German utilities deploy these across Rhine-Ruhr metropolitan corridors.
- Substation:Building-level heat exchanger and metering enclosures that interface district loops with internal HVAC systems. French commercial landlords specify these under long-term energy-as-a-service contracts.
Underground commands the established base. The steepest expansion runs through Substations as real estate investment trusts outsource thermal infrastructure.
End User:
Customer type segmentation maps directly to connection fee structures and contract duration. Industrial users anchor base load with 20-year thermal supply agreements. Commercial portfolios drive volume through portfolio-wide master service contracts.
- Residential:Multi-family towers and social housing estates connecting to municipal networks. Danish and Finnish cities lead deployment through housing association aggregation. Connection rates lag where air-source heat pumps offer lower first cost.
- Commercial:Office towers, retail podiums, and hospitality assets. French business districts around La Défense and Lyon Part-Dieu concentrate contract volume. CSRD disclosure requirements pressure landlords to decarbonize base building systems through district connection.
- Industrial:Manufacturing facilities, pharmaceutical cold storage, and food processing plants. Netherlands and Belgium chemical corridors anchor large-diameter pipeline extensions. F-Gas Regulation phase-out of synthetic refrigerants accelerates conversion from distributed cooling.
- Mixed-use:Integrated developments combining residential, commercial, and retail under single thermal master plans. Stockholm's Hammarby Sjöstad and Amsterdam's Zuidas represent template deployments. Planners consolidate thermal demand to improve network load factors.
Commercial commands the established base. The steepest expansion runs through Mixed-use as urban densification concentrates diverse thermal demand.
Technology:
Technology selection tracks electricity pricing volatility and thermal storage economics. Chilled water dominates where networks serve steady cooling loads. Ice and thermal storage gain share where utilities arbitrage day-night spreads.
- Chilled Water:Conventional 5–7°C distribution loops using central electric or absorption chillers. German and Austrian networks standardize on this architecture for commercial base load. Operating simplicity minimizes specialized maintenance requirements.
- Ice Storage:Latent heat systems storing cooling capacity as phase-change material. Spanish and Italian operators deploy these where summer peak pricing exceeds 200 EUR/MWh. Tank footprint requirements limit urban deployment.
- Thermal Energy Storage:Sensible heat systems using stratified chilled water tanks. Swedish utilities integrate these with legacy district heating infrastructure for seasonal cooling injection. Storage duration extends to 24–48 hours versus ice systems.
- Direct Expansion:Refrigerant-based distribution to building-level evaporators, bypassing water loops. Rare in new European deployment due to F-Gas Regulation constraints. Legacy systems in Southern Europe face retrofit pressure.
Chilled Water commands the established base. The steepest expansion runs through Thermal Energy Storage as utilities seek demand flexibility.
Service Type:
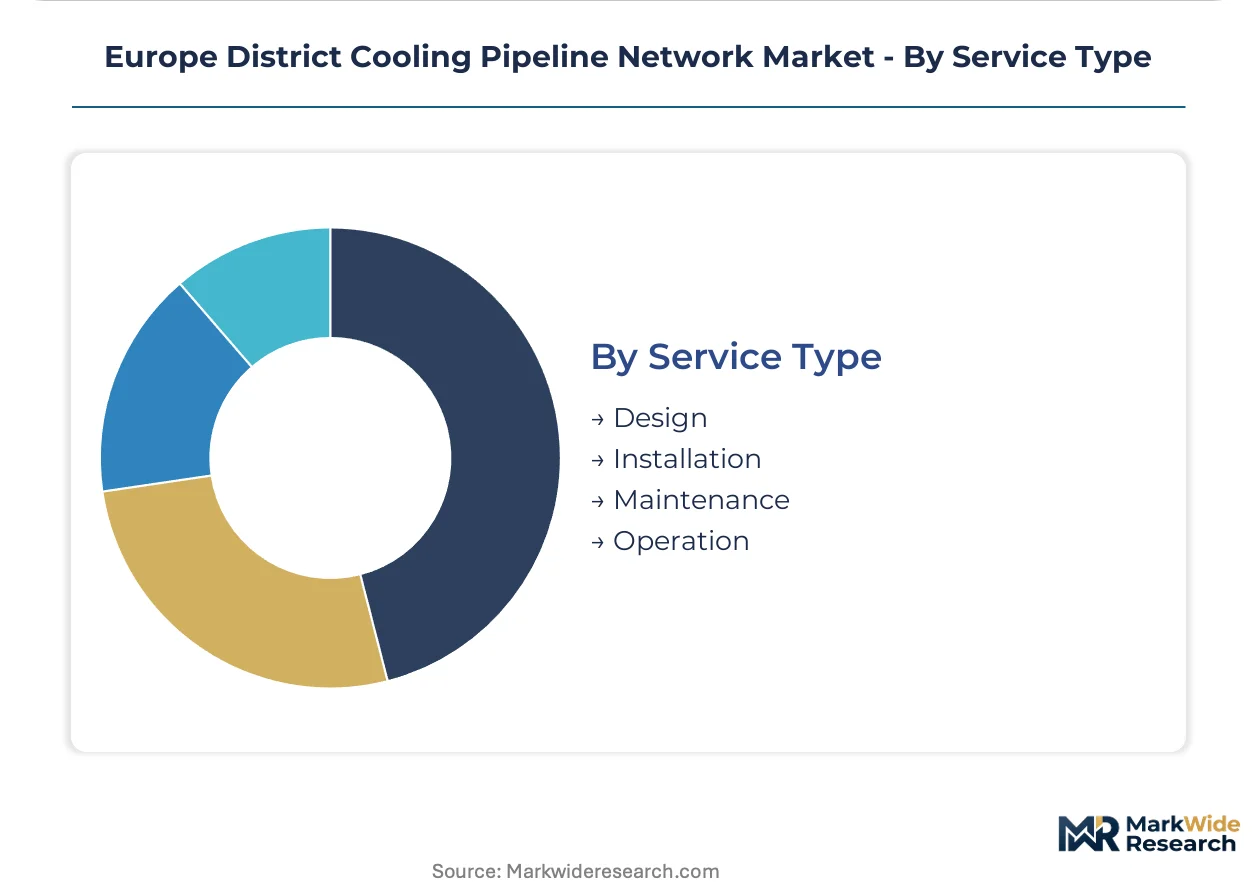
Service segmentation reflects shifting risk allocation between utilities and building operators. Design-build contracts concentrate with integrated energy companies. Operation and maintenance contracts extend to 15–20 year terms.
- Design:Network routing, hydraulic modeling, and substation specification. Engineering consultancies in Germany and Netherlands capture these contracts. Municipal tender structures favor firms with EN 287-certified welding supervision.
- Installation:Trenching, pipe laying, pressure testing, and commissioning. Labor productivity varies 3x across European markets due to certification requirements. Cross-linked polyethylene systems cut installation hours versus legacy steel.
- Maintenance:Leak detection, insulation repair, and cathodic protection monitoring. French and Spanish operators bundle these under energy-as-a-service agreements. Predictive maintenance using fiber-optic sensing is gaining traction.
- Operation:Central plant dispatch, substation optimization, and customer billing. District utilities retain these functions to capture margin from thermal arbitrage. Real-time optimization platforms reduce pumping energy by 15–25 percent.
Installation commands the established base. The steepest expansion runs through Operation as utilities consolidate long-term customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Øresund tunnel network anchors Northern Europe's district cooling density, enabling Swedish and Danish utilities to leverage legacy district heating infrastructure for seasonal cooling expansion across metropolitan corridors.
Sweden
Stockholm's Hammarby Sjöstad thermal master plan concentrates mixed-use development under centralized cooling distribution. The EU Green Deal's Energy Performance of Buildings Directive transposition mandates connection for commercial refurbishments exceeding 1,000 square meters. Vattenfall operates tunnel-based networks extending from Ropsten to Norra Djurgårdsstaden, injecting chilled water into repurposed heating pipes during summer months.
Denmark
Copenhagen's district cooling grid serves pharmaceutical manufacturing and data center clusters with 6°C distribution loops. F-Gas Regulation phase-out schedules accelerate conversions from distributed refrigeration at Novo Nordisk facilities and Maersk logistics hubs. HOFOR operates seawater-cooled plants feeding Ørestad and Nordhavn developments through pre-insulated polyethylene laterals.
Germany
Rhine-Ruhr metropolitan corridor utilities deploy hybrid burial strategies combining deep urban tunnels with surface distribution. REACH compliance requirements under ECHA oversight constrain pipe insulation chemistry specifications. RWE and E.ON operate cooling networks across Düsseldorf's MedienHafen and Essen's commercial core, integrating thermal storage for electricity arbitrage.
France
La Défense and Lyon Part-Dieu business districts anchor captive operation contracts for commercial real estate decarbonization. CSRD disclosure mandates pressure real estate investment trusts to outsource thermal infrastructure. ENGIE and Veolia compete through 15-20 year energy-as-a-service agreements bundling substation engineering with metered cooling delivery.
Netherlands
Amsterdam's Zuidas financial district and Rotterdam harbor industrial zones drive pipeline extensions for data center thermal loads. ECHA material compliance enforcement shapes procurement specifications for cross-linked polyethylene systems. Eneco operates networks connecting Schiphol Trade Park hyperscale facilities to centralized absorption chilling plants.
Europe District Cooling Pipeline Network Market Vendor Landscape
Concentration sits with integrated energy utilities that combine legacy district heating infrastructure with cooling service expansion. The competitive structure tiers between multinational operators with captive municipal contracts and specialized pipe fabricators serving project-specific procurement. Two strategic archetypes dominate: tunnel-network utilities leveraging existing underground rights-of-way, and design-build integrators bundling engineering with long-term operation agreements. Competitive moves center on energy-as-a-service contract capture and pre-insulated composite pipe technology licensing.
Within the integrated utility tier, Veolia and ENGIE exemplify divergent market approaches—Veolia through captive operation contracts anchoring French business districts, ENGIE through bundled design-build offerings. Vattenfall occupies a position representing Nordic tunnel-network operators that repurpose heating infrastructure for seasonal cooling. Among specialized fabricators, Aquatherm and Brugg Pipes sit within the composite piping segment supplying cross-linked polyethylene systems that cut installation labor versus legacy steel. These named entities anchor archetype positions without constraining the broader competitive field.
| Leading Market Players |
|---|
| Aquatherm |
| Brugg Pipes |
| CPV Limited |
| Eval Europe |
| Future Pipe Industries |
| Veolia |
| ENGIE |
| Vattenfall |
| Fortum |
| Others |
Supply Flow & Price Mechanics
Long-term energy-as-a-service contracts lock in both supply access and price visibility for European district cooling operators, binding substation engineering, pipeline connection, and metered delivery into 15-20 year agreements that shield buyers from copper and steel input volatility while guaranteeing utilities predictable revenue streams.
Pricing Analysis
Volume-discount tiering structures separate large commercial portfolios from individual building connections across French and Nordic networks. Pricing stratifies across premium, standard, and economy tiers based on contract duration and thermal load predictability, with industrial anchors securing lowest rates through 20-year offtake commitments. Cost compression in municipal tender structures intensifies as pre-insulated pipe manufacturers face limited pass-through mechanisms during base metal price spikes. Small commercial loads exhibit highest price sensitivity where air-source heat pump payback periods undercut connection fee amortization.
Supply Chain Analysis
EN 287-certified welding certification scarcity chokes project velocity across German and French installation markets, constraining pipeline commissioning schedules regardless of material availability. Pre-insulated steel and cross-linked polyethylene systems draw from mills in Germany, Sweden, and Poland, with composite pipe fabrication concentrated among Nordic specialists. Single-source vulnerability runs through cathodic protection equipment and specialized fusion welding machinery. Distribution runs through district utility procurement teams that consolidate vendor relationships under master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified pressure welder shortages and legacy building integration complexity create persistent capability gaps that reward operators with captive training pipelines and retrofit engineering expertise.
For Market Incumbents: Secure EN 287-certified welding capacity through captive training academies before project backlogs accumulate. Anchor thermal energy storage arbitrage capabilities to capture electricity spread volatility as utilities flatten peak demand. Defend against air-source heat pump substitution by compressing connection fees for mid-size commercial loads through standardized substation designs. For New Entrants and Emerging Players: Anchor in Eastern European district heating conversion opportunities across Poland and Czech Republic legacy steam networks. Target seasonal cooling injection projects where existing tunnel infrastructure eliminates right-of-way barriers. Pursue composite pipe technology licensing partnerships with established Nordic fabricators to bypass steel welding certification requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tunnel-network utilities with legacy district heating infrastructure repurposable for seasonal cooling expansion. Long-term viability favors operators with municipal captive contracts and energy-as-a-service billing platforms. Monitor F-Gas Regulation phase-out enforcement intensity as inflection indicator for distributed refrigeration conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Energy Storage Integration | Swedish utilities arbitrage day-night electricity spreads through stratified chilled water tanks. |
| Composite Pipe Technology Licensing | Cross-linked polyethylene systems cut German installation labor by half versus legacy steel. |
| Energy-as-a-Service Contract Capture | French REITs outsource thermal infrastructure under CSRD disclosure pressure. |
| Legacy Heating Network Conversion | Polish operators inject seasonal cooling into existing district heating tunnels. |
| Welding Certification Pipeline Development | EN 287-qualified pressure welder scarcity constrains French project velocity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across district utility planning officers, commercial real estate portfolio managers, EN 287-certified welding supervisors, pre-insulated pipe procurement leads, and ECHA compliance specialists. Secondary validation drew from EU F-Gas Regulation filings, ECHA REACH substance registrations, national Energy Performance of Buildings Directive transposition texts, and district energy association technical specifications. Bottom-up project pipeline tracking triangulated against top-down utility capex disclosures.
Across the analysis window, forecasts model infrastructure type, end user category, technology architecture, and service type segmentation alongside municipal regulatory framework variations. CAGRs derive from network extension velocity correlated with commercial refurbishment mandates and data center thermal load concentration. Industry-specific inputs include copper and steel price volatility indices, right-of-way permit approval rates, and F-Gas quota auction clearing prices.
Underlying assumptions cover stable EU Green Deal enforcement continuity and copper price mean-reversion, with deviation risk concentrated in UNESCO heritage protection expansions and air-source heat pump cost curves. Practitioners should keep alternative scenarios live as national building code transpositions and refrigerant phase-out schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Aeration System Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Roof Vents Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Industrial Hood Ventilation Market