
 Ductless HVAC System Market | 2026-2036
Ductless HVAC System Market Size, Share, and Industry Trends Forecast 2026-2036
Ductless HVAC System Market Intelligence
A multi-brand sourcing model for large-scale construction projects is shifting procurement away from single-vendor relationships. Developers now blend systems from different manufacturers to optimize for specific building requirements and budgets. Daikin Industries Ltd. leverages its deep expertise in inverter technology to secure high-performance specifications. Midea Group competes aggressively on production volume and cost structure, while Panasonic Corporation sustains its position through a focus on air quality features and smart controls.
Ductless HVAC systems deliver zoned heating and cooling through an outdoor compressor connected to indoor air-handling units via refrigerant lines. These systems operate without the need for centralized ductwork, offering significant installation flexibility and improved energy efficiency. Mini-split configurations command the residential segment, valued for their cost-effectiveness in single-zone applications. The commercial sector shows a clear preference for multi-split systems, which allow for independent climate control across multiple rooms or floors.
Regulatory frameworks globally mandate higher energy efficiency and the use of environmentally benign refrigerants. In the United States, the EPA enforces the phase-down of HFCs, while the EU's F-Gas Regulation and Ecodesign directives set stringent performance benchmarks. These rules push manufacturers toward innovation in compressor technology and heat pump designs. System compatibility with smart home ecosystems and advanced energy management software will define the next generation of competitive products.
Market Dynamics
Regulatory mandates for higher energy efficiency and the phase-down of high global warming potential refrigerants are the central force shaping the ductless HVAC market. This pressure compels innovation in compressor technology and heat pump design across all segments.
Growth Catalysts
- F-Gas Regulation Compliance:Europe's stringent F-Gas Regulation accelerates the transition to low-GWP refrigerants like R-32 and R-290, creating replacement demand for compliant ductless systems in the residential and light commercial sectors.
- Residential Retrofitting Demand:Retrofitting older residential buildings, particularly those lacking pre-existing ductwork, provides a substantial growth avenue for mini-split systems due to their installation flexibility and improved energy performance.
- Inverter Technology Adoption:The widespread adoption of inverter-driven compressors enhances energy efficiency and provides precise temperature control, appealing to both residential and commercial users seeking lower operational costs.
Market Restraints
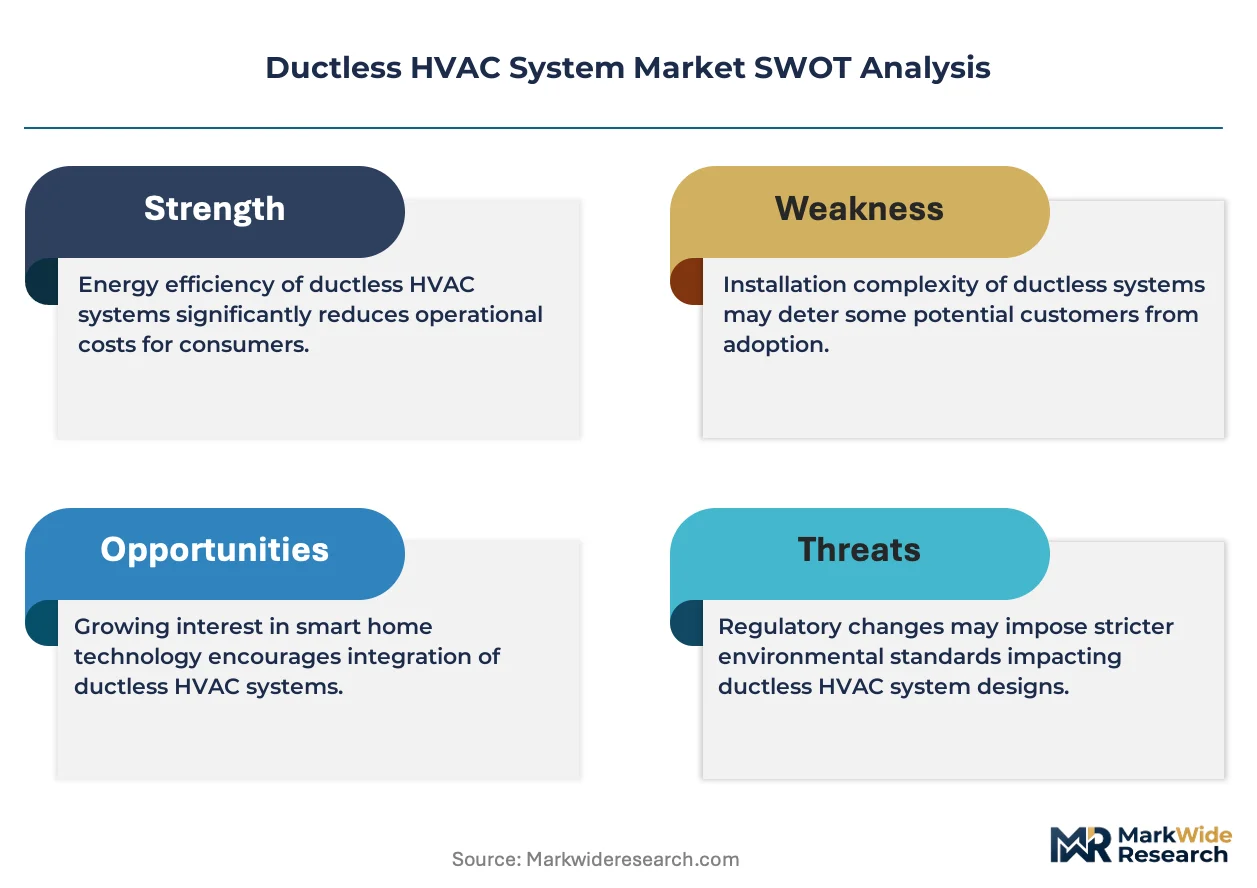
- High Initial Installation Cost:The upfront capital expenditure for multi-zone ductless systems can be significantly higher than traditional centralized HVAC units, deterring budget-conscious buyers in some residential segments.
- Aesthetic and Space Constraints:The visibility of indoor air-handling units on walls or ceilings poses an aesthetic challenge in high-end residential and hospitality applications, limiting adoption where interior design is paramount.
- Competition from Centralized VRF:In large commercial projects, centralized Variable Refrigerant Flow (VRF) systems present a strong substitution threat, offering similar zoned control benefits but with greater scalability and management features.
Strategic Opportunities
- Urbanization in Southeast Asia:Rapid urbanization and new construction in high-density cities like Jakarta and Bangkok create significant opportunities for multi-split systems in both new residential and commercial buildings.
- Smart Home Ecosystem Integration:Developing systems with native compatibility for leading smart home platforms and energy management software opens new value streams and appeals to tech-savvy consumers seeking automated climate control.
- Building Electrification Incentives:Government incentives promoting building electrification, such as those within the U.S. Inflation Reduction Act (IRA), create a strong tailwind for high-efficiency ductless heat pumps as replacements for fossil fuel furnaces.
Industry Challenges
- Installer Skill Gap:A shortage of technicians trained in the proper installation, sizing, and servicing of advanced multi-split systems can lead to suboptimal performance, increased service calls, and potential brand reputation damage.
- Integration with Building Automation:Ensuring seamless interoperability between proprietary ductless HVAC controls and existing building automation systems (BAS) in commercial retrofits presents a significant technical and software integration challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ductless HVAC System Market |
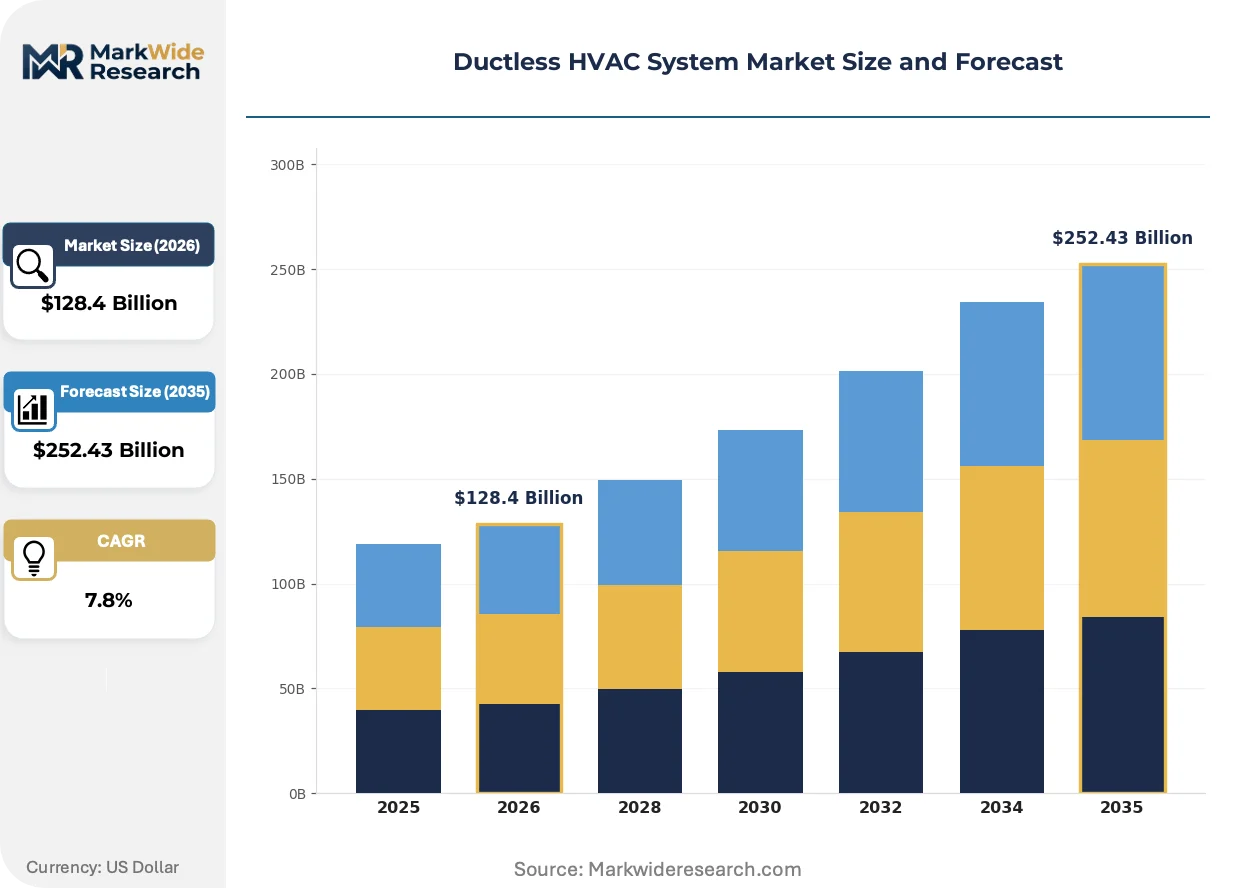
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $252.43 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini-Split, Multi-Split, Portable System, Cassette Unit End User: Residential, Commercial, Industrial, Institutional Technology: Inverter Technology, Non-Inverter Technology, Smart Control, Remote Control Installation Type: Wall-Mounted, Ceiling-Mounted, Floor-Mounted, Free-Standing |
| Companies Covered | Carrier, Panasonic Corporation, Daikin Industries Ltd., Gree Electric Appliances Inc., Samsung Electronics, Mitsubishi Electric Corporation, Fujitsu General Limited, Midea Group, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ductless HVAC System Market Strategic Shifts & Innovations
The evolution of ductless HVAC systems centers on the integration of smart technologies and sustainable performance. Manufacturers are responding to regulatory pressures and consumer expectations by developing more intelligent, efficient, and environmentally conscious climate control solutions.
Advanced cold-climate heat pump technology enables ductless systems to provide efficient heating in sub-freezing temperatures. Commercial facilities and residential homeowners in colder regions are adopting these units to displace fossil fuel heating. This performance enhancement is converging with on-board diagnostics and predictive maintenance software, creating a more resilient and self-monitoring system.
Europe’s Ecodesign directive sets progressively stricter minimum energy performance standards (MEPS) for heating and cooling products. This regulation forces manufacturers to invest heavily in R&D for more efficient compressors, fans, and heat exchangers to remain compliant. The residential mini-split segment is most affected, with non-compliant models being phased out of the market.
A multi-brand sourcing model is gaining traction among large-scale construction developers, moving away from single-vendor contracts. This approach allows developers to blend high-performance units from one manufacturer with cost-effective systems from another to optimize project budgets. This purchasing behavior is most prominent in the competitive commercial real estate sectors of the United States and Indonesia.
Ductless HVAC System Market Segmentation
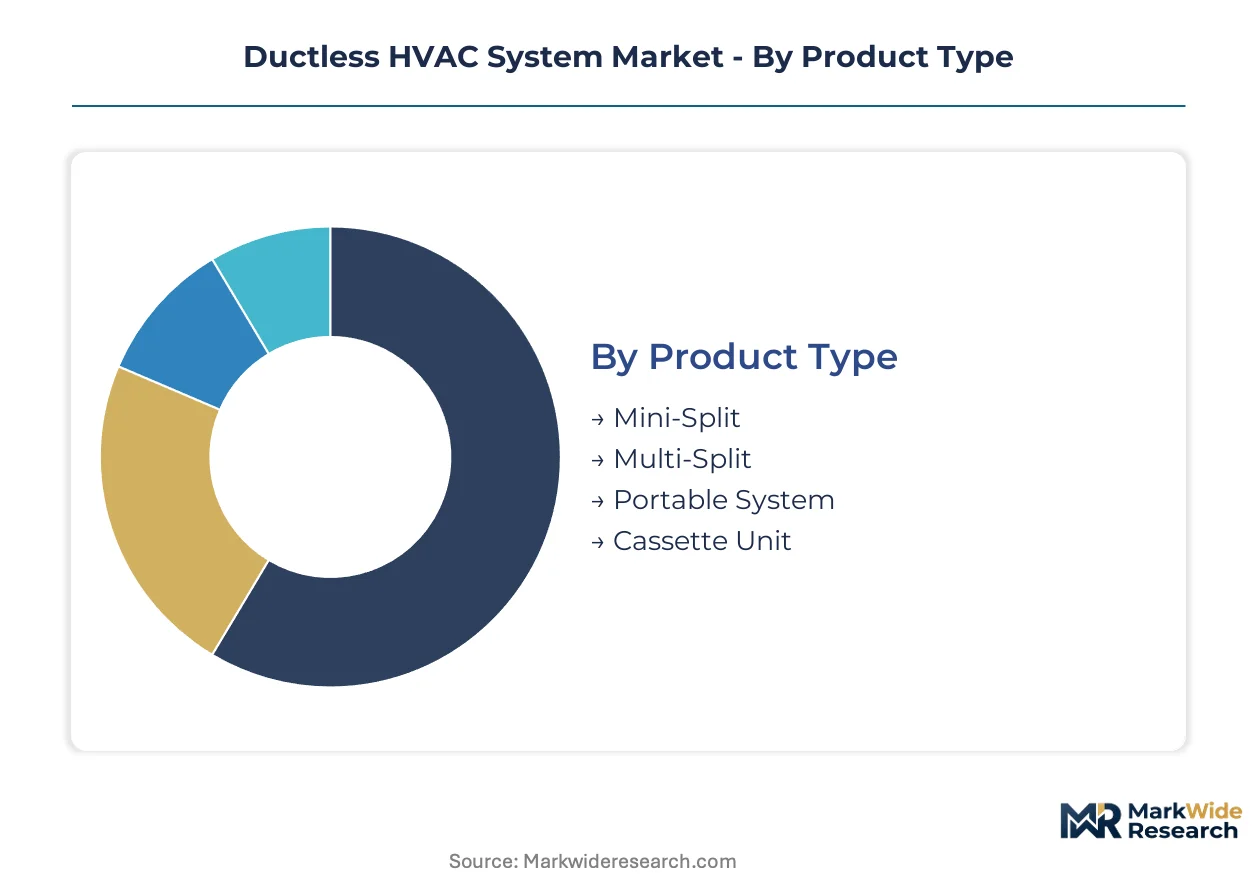
Ductless HVAC system market segmentation reveals diverse demand patterns influenced by application scale, technological advancements, and specific user requirements. Understanding these segments helps manufacturers tailor product offerings and allows stakeholders to identify key growth pockets within the expanding market.
Product Type:
Product type differentiation in ductless HVAC systems primarily centers on capacity, application scale, and installation complexity.
- Mini-Split:These systems feature an outdoor compressor connected to a single indoor air-handling unit, offering localized heating and cooling. Residential retrofitting in older buildings lacking ductwork drives significant demand for mini-split units due to their ease of installation and energy efficiency benefits.
- Multi-Split:Multi-split configurations link one outdoor unit to multiple indoor units, enabling independent temperature control across several zones or rooms. The commercial sector, particularly in new construction and modernization projects within high-density urban areas like Jakarta, favors multi-split systems for their scalability and zoned climate management.
- Portable System:These self-contained units offer temporary cooling solutions without permanent installation, often used in rental properties or supplementary cooling scenarios.
- Cassette Unit:Designed for ceiling integration, cassette units provide discreet air distribution and are frequently chosen for aesthetic reasons in commercial and high-end residential spaces.
Volume sits with Mini-Split systems; growth tilts toward Multi-Split configurations.
End User:
End-user segments are distinguished by their specific climate control requirements, operational hours, and budget constraints.
- Residential:This segment encompasses single-family homes and multi-unit dwellings, where demand is strong for retrofitting older structures without existing ductwork. Homeowners prioritize energy efficiency, quiet operation, and smart home compatibility for comfort.
- Commercial:Commercial applications include offices, retail spaces, and hospitality venues, where multi-split systems provide independent climate control for various zones. Businesses seek systems offering operational cost savings and consistent comfort for employees and customers.
- Industrial:Industrial settings, such as manufacturing plants or warehouses, require robust systems capable of maintaining specific temperatures and air quality in challenging environments.
- Institutional:Educational facilities, healthcare centers, and government buildings constitute the institutional segment, focusing on reliable performance and compliance with stringent indoor air quality standards.
The residential sector currently dominates demand, while commercial applications are experiencing strong expansion.
Technology:
Technology segmentation reflects the maturity and sophistication of control mechanisms and compressor designs within ductless HVAC units.
- Inverter Technology:Inverter-driven compressors modulate their speed to match heating or cooling demand, significantly enhancing energy efficiency and providing precise temperature regulation. This technology is becoming standard across residential and commercial high-performance systems.
- Smart Control:Systems with smart control capabilities integrate with home automation platforms and energy management software, offering users remote access and automated climate scheduling. Consumers in technologically advanced markets like the United States increasingly seek these integrated solutions.
- Non-Inverter Technology:These systems operate at a fixed compressor speed, cycling on and off to maintain temperature, and typically represent a more budget-friendly option.
- Remote Control:Standard remote controls enable basic temperature adjustments and mode selection, providing convenient localized operation for individual units.
Inverter technology drives energy performance, and smart control features are gaining share fastest.
Installation Type:
Installation type differentiates ductless HVAC systems based on aesthetic considerations, space utilization, and specific architectural requirements of the customer.
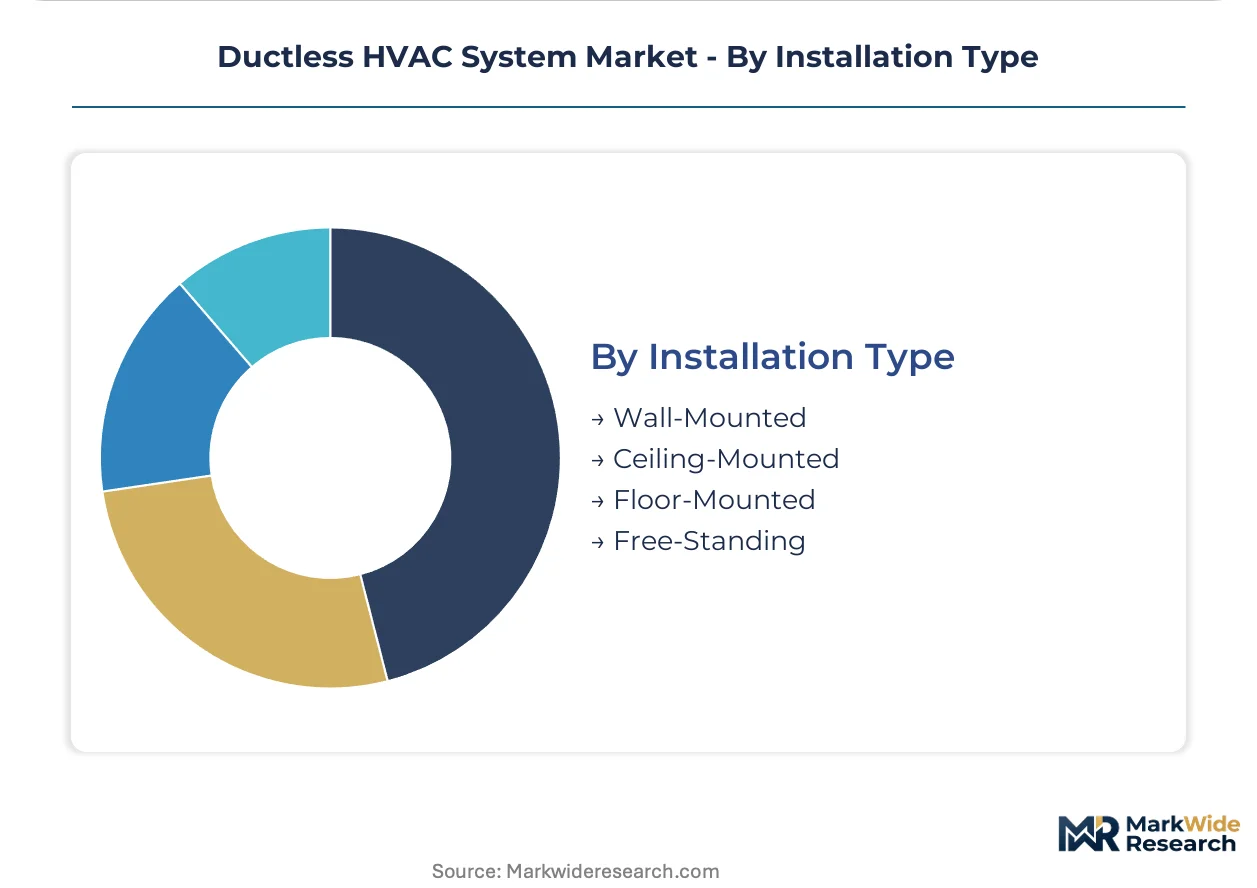
- Wall-Mounted:These are the most common indoor units, installed high on a wall, offering a cost-effective and straightforward solution for residential and light commercial applications. Their widespread use contributes to their market dominance.
- Ceiling-Mounted:Ceiling-mounted units, including cassette types, offer discreet integration into the interior design, favored in high-end residential and commercial spaces where aesthetics are paramount. They distribute air evenly from above.
- Floor-Mounted:Positioned near the floor, these units are suitable for spaces with limited wall space or specific heating distribution needs, often found in older homes or conservatories.
- Free-Standing:Free-standing units offer flexibility in placement without permanent installation, often utilized as supplementary heating or cooling in various settings.
Wall-mounted units hold the largest market share, with ceiling-mounted options showing steady uptake in design-conscious projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's deep expertise in inverter technology and advanced climate control systems anchors innovation across the global ductless HVAC market. This technological leadership influences product development worldwide. Manufacturers in Japan consistently push the boundaries of energy efficiency and smart integration.
United States
United States demand for ductless HVAC systems is driven by residential retrofitting and building electrification initiatives. The U.S. Inflation Reduction Act (IRA) provides significant incentives for high-efficiency heat pumps, accelerating market adoption. Tech-savvy consumers in California's urban centers increasingly integrate smart home ecosystems with advanced climate control solutions.
Germany
Germany focuses on high-efficiency ductless systems due to stringent energy performance standards and F-Gas Regulation compliance. Europe's F-Gas Regulation mandates a transition to low-GWP refrigerants, creating replacement demand. Commercial projects in Munich's growing urban landscape prioritize multi-split systems for zoned climate control and operational savings.
Indonesia
Indonesia experiences strong demand for ductless HVAC systems fueled by rapid urbanization and new construction projects. Local building codes increasingly emphasize energy efficiency in commercial and residential developments. High-density urban areas like Jakarta see significant uptake of multi-split systems for scalable and independent climate management.
Thailand
Thailand's ductless HVAC market expands with modernization projects and ongoing urban development. National energy conservation policies encourage the adoption of more efficient cooling solutions across various sectors. Bangkok's booming hospitality sector frequently deploys discreet cassette units for aesthetic appeal and precise room-level climate control.
Japan
Japanese consumers prioritize ductless systems featuring advanced inverter technology and smart control integration. METI's stringent energy efficiency targets drive continuous innovation in compressor and heat pump designs. Tokyo's smart city initiatives showcase seamless integration of advanced HVAC with sophisticated building automation systems.
Ductless HVAC System Market Key Industry Players
Global majors compete with regional champions across technological innovation and production scale within the ductless HVAC market. The market exhibits a tiered structure, with premium brands focusing on performance and budget players on volume. Strategic archetypes include technology innovators, mass-market producers, and specialized solution providers. Companies pursue portfolio diversification and strategic partnerships to strengthen their market positions.
Among the established global players, Daikin Industries Ltd. exemplifies a technology-driven archetype, leveraging its deep expertise in inverter technology for high-performance specifications. Midea Group, a Chinese manufacturer, occupies a position as a mass-market producer, competing aggressively on production volume and cost structure across various segments. Panasonic Corporation, a Japanese conglomerate, represents a specialist in integrated solutions, sustaining its market standing through a focus on air quality features and smart controls within its product offerings. These companies anchor different competitive vectors, from high-end innovation to broad market accessibility.
| Leading Market Players |
|---|
| Carrier |
| Panasonic Corporation |
| Daikin Industries Ltd. |
| Gree Electric Appliances Inc. |
| Samsung Electronics |
| Mitsubishi Electric Corporation |
| Fujitsu General Limited |
| Midea Group |
| LG Electronics |
| Others |
Cost & Logistics Intelligence
Europe's F-Gas Regulation and the EPA's HFC phase-down significantly gate qualified supply for ductless HVAC systems. These environmental mandates drive premium-tier pricing for compliant, high-efficiency units.
Pricing Analysis
Warranty and service bundling often differentiate pricing within the ductless HVAC market. The dominant pricing model for residential mini-splits is per-unit transactional, while commercial projects typically involve project-based contracts. Inverter technology integration and brand premium from manufacturers like Daikin drive price differentiation. Pricing softness reflects intense competition from mass-market producers, with residential retrofitting buyers being highly price-sensitive.
Supply Chain Analysis
Logistics and freight costs significantly influence the landed price of ductless HVAC systems. Geographic supply concentration centers primarily in China, Japan, and South Korea for finished units and key components. The industry relies on specialized compressors, R-32 refrigerants, and copper tubing, making it vulnerable to commodity price volatility. Distribution runs through specialized HVAC distributors and direct-to-installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing a significant technology-transition phase, moving away from legacy fixed-speed compressors. Inverter technology is rapidly replacing older designs, driving efficiency and precise climate control capabilities.
For Market Incumbents:Lock in long-term supply agreements for critical low-GWP refrigerants to mitigate future regulatory risks. Incumbents should also acquire specialized smart control software firms to integrate advanced energy management features. This strategy defends against emerging modular heat pump designs and strengthens market position through certification investment for new efficiency standards.
For New Entrants and Emerging Players:Specialized installation contractors represent a key channel for new entrants. Target residential retrofitting in underserved urban areas and light commercial applications with cost-effective mini-split solutions. Southeast Asian high-density urban centers offer a highly penetrable geography. A go-to-market angle focused on bundled installation and maintenance services will appeal to budget-conscious buyers.
For Investors and Strategic Acquirers:Mass market adoption of R-290 based systems is the leading indicator that the market is ready for a full-scale refrigerant transition. The ductless HVAC market shows sustained growth viability over the next decade, driven by electrification trends. Vertically integrated manufacturers with strong intellectual property in inverter technology represent attractive acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cold-Climate Heat Pump R&D | Captures market share in regions displacing fossil fuel heating. |
| Develop Smart Home Ecosystem Integrations | Attracts tech-savvy consumers seeking automated climate control solutions. |
| Invest in Technician Training Programs | Addresses installer skill gaps, ensuring optimal system performance for customers. |
| Secure Low-GWP Refrigerant Supply | Ensures compliance with F-Gas Regulation, reducing future operational risks. |
| Diversify Manufacturing Footprint | Mitigates geopolitical supply chain risks from concentrated production in Asia. |
Research Approach
Independent corroboration across HVAC engineers, construction project managers, and building automation specialists underwrites the qualitative findings. Primary interviews with industry stakeholders provided nuanced perspectives, validated by secondary research from EPA reports, EU Ecodesign directives, and national energy conservation policies. This approach ensured bottom-up and top-down triangulation of market dynamics.
Comparable historical reference periods anchored the forecast framework for the ductless HVAC market. The analytical framework modeled segmentation dimensions including product type, end user, technology, and installation type. Compound annual growth rates were derived from historical trends and projected regulatory impacts. Key industry-specific forecast inputs included refrigerant phase-down schedules and building electrification incentives across the analysis window.
Caveats apply where unforeseen geopolitical events or rapid shifts in energy policy could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and technological progression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Global Chilled Beam System Market