
 Specialty Adhesives Market | 2026-2036
Specialty Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Adhesives Market Intelligence
Buyer concentration among automotive OEMs is recalibrating procurement volumes for structural bonding systems as electric vehicle platforms multiply. Henkel AG & Co. KGaA leverages its reactive adhesive portfolio to anchor European OEM supply chains. H.B. Fuller Company competes through geographic dominance in Asia-Pacific packaging applications. 3M sustains technology leadership in electronics-grade acrylic formulations.
Specialty adhesives are engineered bonding systems formulated from synthetic polymers, curing agents, and functional additives, typically achieving lap shear strengths above 1000 psi and operating across temperature ranges from minus 40°C to 150°C depending on chemistry. Their primary industrial purpose is to replace mechanical fasteners in weight-sensitive or thermally stressed assemblies. Epoxy formulations dominate structural aerospace applications where outgassing specifications and thermal cycling resistance command premium positioning. Water-based technology occupies the fastest-expanding share as VOC regulations tighten across manufacturing jurisdictions. Reactive systems concentrate margin pools in medical device and semiconductor packaging segments where cure precision and biocompatibility certification create qualification barriers.
EPA regulates VOC emissions from adhesive manufacturing facilities under Clean Air Act Title V permitting, while REACH restricts hazardous substance content in European imports. ECHA substance evaluation pressures reformulation of solvent-based portfolios toward compliant chemistries. FDA biocompatibility standards govern medical-grade adhesive approvals for device manufacturers. Stakeholders must monitor evolving substance restriction lists and qualification timelines to secure market access before competitor formulations achieve regulatory lock-in.
Market Dynamics
Lightweighting mandates across automotive platforms are compressing mechanical fastener volumes and reallocating specification authority from Tier-1 suppliers to OEM material engineering teams. This concentration of buyer power is restructuring formulation priorities and qualification timelines across adhesive portfolios.
Growth Catalysts
- EV Platform Expansion:Electric vehicle battery pack assembly demands thermally conductive bonding systems that maintain structural integrity across charge-cycle temperature swings. OEMs specify these chemistries for module-to-pack integration.
- REACH Annex XVII Restrictions:Solvent-phase adhesive categories face substance sunset dates in European manufacturing. Reformulation urgency is accelerating water-based and hot-melt technology substitution in industrial coating applications.
- Semiconductor Advanced Packaging:Die-attach adhesives with ultra-low alpha particle emission specifications are qualifying for chiplet architectures. Foundries in Taiwan and South Korea are expanding specification libraries for heterogeneous integration.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and acrylic monomer prices track benzene and propylene derivative markets. Asian petrochemical complex outages transmit rapid cost spikes to formulated adhesive producers.
- Specialty Silane Concentration:Coupling agent supply for moisture-cure silicones concentrates among German and Japanese chemical producers. Qualification of alternative adhesion promoters requires 18-24 month validation cycles.
- Cure Kinetics Limitation:Two-component structural epoxies demand precise mix-ratio control and elevated temperature post-cure. These constraints exclude ambient-process applications where one-part moisture-cure systems dominate.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for mobile phone and component assembly are expanding domestic adhesive consumption. Local formulation facilities can bypass import duty structures on finished goods.
- EU Green Deal Public Procurement:Bio-based content thresholds in construction and infrastructure tenders create preferential positioning for adhesives with certified renewable carbon content. ISCC PLUS chain-of-custody documentation unlocks specification access.
- Digital-Physical Convergence:Pressure-sensitive adhesives integrating printed electronics for structural health monitoring are qualifying for wind turbine blade and civil infrastructure applications. Sensor-embedded bonding layers enable predictive maintenance data streams.
Industry Challenges
- Polymer Rheology Expertise Scarcity:Formulation chemistry for high-shear-rate dispensing in automated assembly requires specialized knowledge at the intersection of polymer physics and process engineering. Universities produce fewer graduates in adhesive science than industry retirement rates.
- Biocompatibility Certification Timeline:FDA 510(k) and ISO 10993 testing protocols for medical device adhesives extend 24-36 months. Device OEMs freeze specifications early in product development, locking out late-qualifying alternatives.
- Legacy Equipment Retrofit Complexity:Hot-melt dispensing systems in packaging operations require heated hose and tank modifications to handle next-generation metallocene polyolefin adhesives. Capital allocation decisions delay technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Adhesives Market |
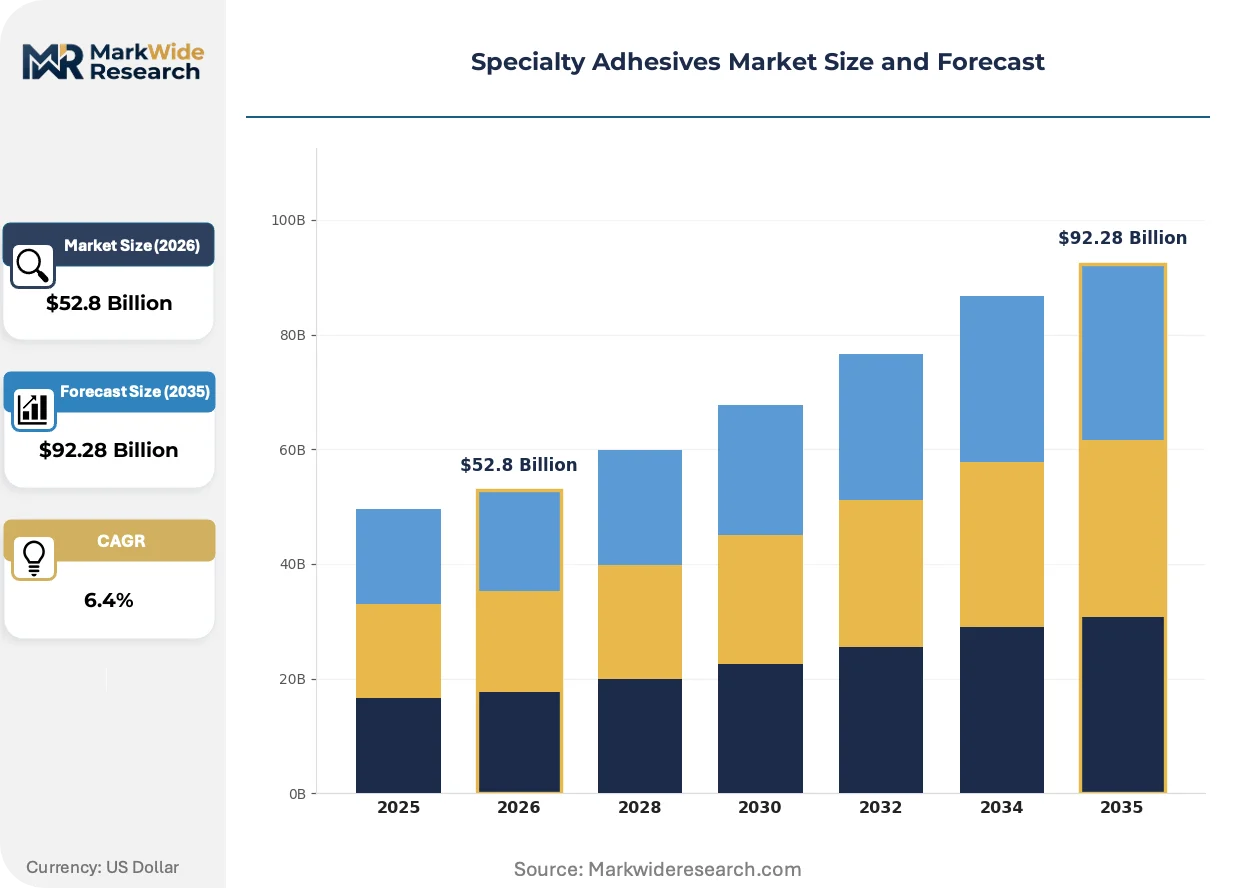
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: Aerospace, Automotive OEMs, Electronics, Construction Application: Packaging, Woodworking, Bonding, Sealing Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Arkema Group (Bostik SA), H.B. Fuller Company, Sika AG, Master Bond Inc., Permatex, Avery Dennison, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Adhesives Market Strategic Shifts & Innovations
Formulation science is converging with process automation and sustainability verification systems to redefine competitive positioning. These developments compress traditional specification cycles while elevating performance thresholds.
UV-LED curable acrylic adhesives are decentralizing production workflows by eliminating thermal ovens from assembly lines. Automotive electronics manufacturers in Germany and Mexico are adopting these systems for dashboard component bonding. The technology enables cellular manufacturing layouts that reduce work-in-process inventory and floor-space requirements.
ECHA substance evaluation under REACH is forcing reformulation of aromatic amine curing agents in epoxy systems used for wind turbine blade construction. Danish and Spanish blade manufacturers are accelerating qualification of aliphatic amine alternatives. The transition compresses margin structures during 12-18 month requalification periods.
Specification authority is migrating from procurement functions to OEM material engineering departments as structural bonding assumes critical load-path functions. Tier-1 suppliers in the US and China report extended technical review cycles and expanded testing protocols. This centralization elevates technical service intensity as a competitive differentiator over price positioning.
Specialty Adhesives Market Segmentation
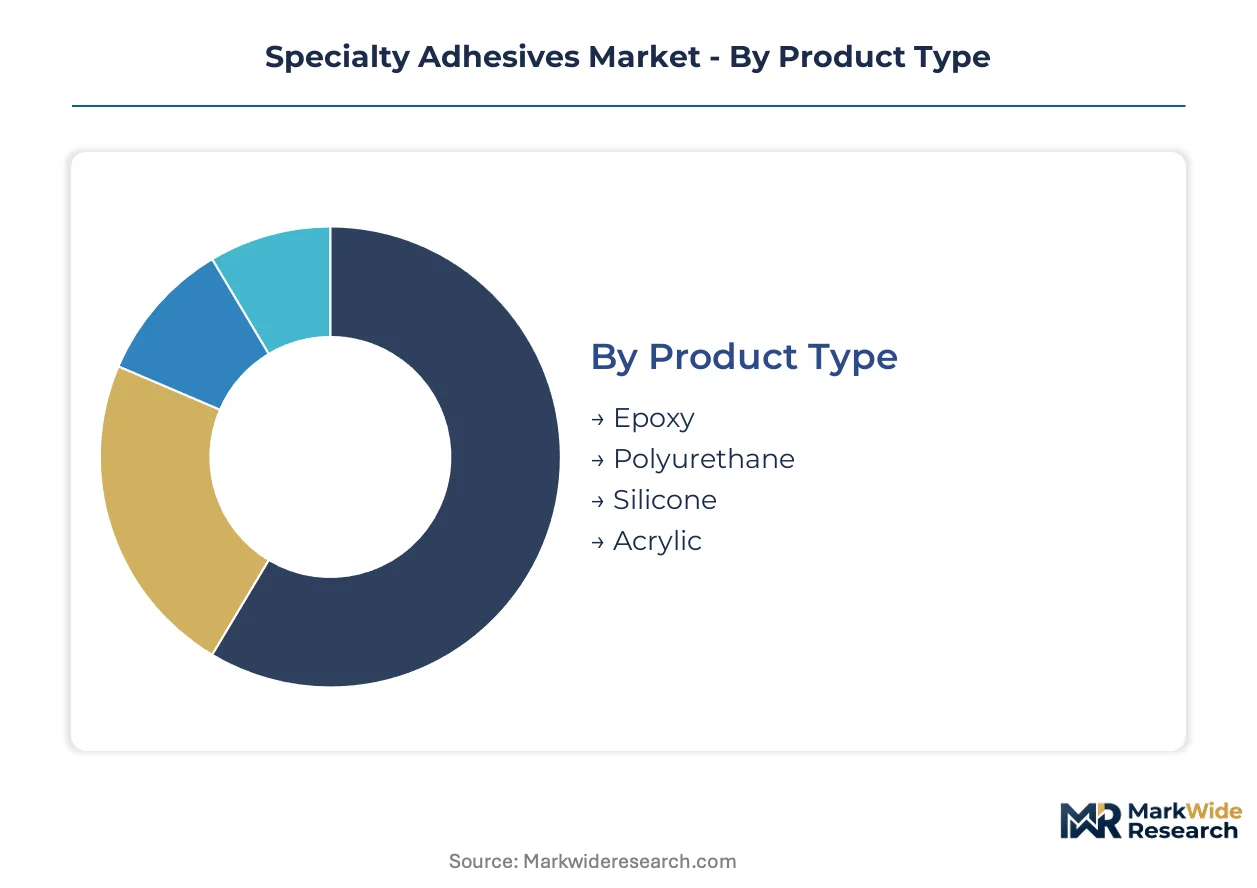
Specialty adhesives fragment across four intersecting dimensions that determine specification authority and margin capture. Product chemistry defines performance ceilings. End-user verticals dictate qualification intensity. Application method shapes equipment compatibility. Technology platform determines regulatory exposure and sustainability positioning.
Product Type:
Customization intensity varies from rigid aerospace specifications to commoditized construction grades, with formulation latitude expanding as performance tolerance widens.
- Epoxy:Two-part thermoset systems achieve lap shear strengths exceeding 3000 psi and service temperatures to 180°C. Aerospace manufacturers in France and Germany specify these for primary structural bonding in composite wing assemblies. Outgassing compliance per ASTM E595 commands premium positioning.
- Polyurethane:Moisture-cure and two-component variants balance flexibility with adhesion to polar substrates. Automotive OEMs in Michigan and Bavaria deploy these for windshield bonding and lightweight panel attachment. NVH damping requirements drive specification.
- Silicone:Room-temperature vulcanizing formulations deliver thermal stability across minus 60°C to 230°C ranges. Electronics packaging in Taiwan and South Korea consumes high-purity grades for LED encapsulation.
- Acrylic:UV-curable and cyanoacrylate instant adhesives target high-speed assembly. Medical device manufacturers in Massachusetts and Minnesota specify USP Class VI certified grades.
Most installed capacity flows through Epoxy. Expansion is steepest in Acrylic as UV-LED curing displaces thermal ovens.
End User:
Customer scale determines technical service intensity, with fragmented construction buyers at one pole and concentrated aerospace primes at the other.
- Aerospace:OEMs and Tier-1 suppliers impose qualification cycles exceeding 24 months. Boeing and Airbus specification libraries lock in approved formulations. Flame-retardant and outgassing certifications create entry barriers.
- Automotive OEMs:Platform engineering teams now control structural bonding specifications directly. Battery pack assembly in Nevada and Shanghai consumes thermally conductive grades for module-to-pack integration. Lightweighting mandates accelerate adhesive substitution for spot welds.
- Electronics:Semiconductor foundries in Hsinchu and Pyeongtaek demand ultra-low alpha particle die-attach materials. Miniaturization trends favor thin-film adhesives with precise viscosity control.
- Construction:Project-based procurement with distributed decision-making favors cost-optimized formulations. Green building certifications in California and British Columbia drive low-VOC specification.
Volume concentrates in Automotive OEMs. Margin capture peaks in Aerospace.
Application:
Process speed requirements separate high-throughput packaging from precision sealing applications with extended cure windows.
- Packaging:High-speed carton sealing and flexible film lamination dominate consumption. Food and beverage producers in São Paulo and Jakarta specify FDA-compliant hot-melt formulations for direct contact applications.
- Woodworking:Furniture manufacturers in Vietnam and Poland deploy PVAc and polyurethane reactive hot-melts for edgebanding and panel assembly. Formaldehyde emission regulations tighten formulation options.
- Bonding:Structural load-bearing applications command highest performance thresholds. Wind turbine blade manufacturers in Denmark and Spain specify epoxy systems for shear web and spar cap integration.
- Sealing:Gasketing and encapsulation applications prioritize environmental resistance. EV battery enclosures specify flame-retardant silicone foams for thermal runaway protection.
Throughput volume peaks in Packaging. Technical complexity concentrates in Bonding.
Technology:
Regulatory pressure on volatile organic compounds creates divergence between declining solvent platforms and expanding water-based and reactive systems.
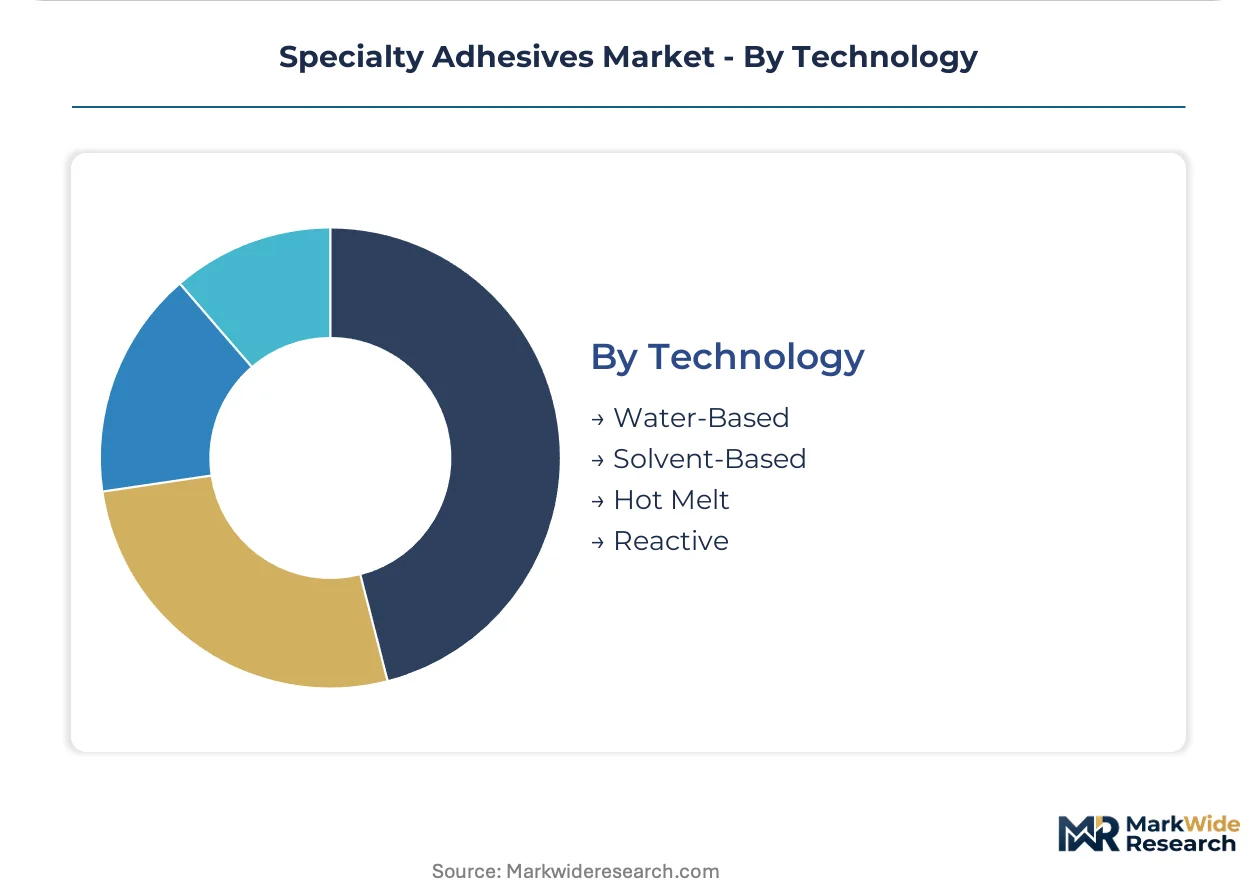
- Water-Based:Emulsion polymers serve paper and packaging markets with minimal VOC exposure. European REACH compliance accelerates substitution for solvent alternatives in industrial coating.
- Solvent-Based:Remaining applications concentrate in pressure-sensitive tape and specialty film lamination where water systems fail. ECHA substance evaluation threatens aromatic solvent categories.
- Hot Melt:Metallocene polyolefin and polyurethane reactive systems enable high-speed bonding without cure ovens. E-commerce fulfillment centers in Ohio and Hesse deploy these for case and carton sealing.
- Reactive:Two-component epoxies and moisture-cure silicones deliver highest structural performance. Medical device manufacturers in Minnesota and Massachusetts specify these for permanent implantable applications.
Equipment base concentrates in Hot Melt. Regulatory tailwinds favor Water-Based expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer formulation expertise concentrates in German industrial clusters, while Asian manufacturing scale dominates consumption volumes. Regional regulatory divergence is fragmenting product portfolios as REACH, EPA, and China's MEE impose incompatible substance restrictions.
United States
Automotive OEMs in Michigan and California specify thermally conductive adhesives for battery pack assembly as EV platforms multiply. EPA Clean Air Act Title V permitting tightens VOC emission controls on manufacturing facilities. Adhesive formulators in the Midwest industrial corridor are expanding water-based capacity to preempt regulatory displacement.
Germany
Wind turbine blade manufacturers in Denmark and northern Germany consume structural epoxy systems for spar cap integration as offshore capacity expands. ECHA substance evaluation under REACH threatens aromatic amine curing agents, forcing 18-month reformulation cycles. The Bavarian chemical corridor anchors European R&D for low-outgassing aerospace grades.
China
Semiconductor foundries in Hsinchu and Shanghai demand ultra-low alpha particle die-attach materials for advanced packaging architectures. MIIT dual carbon goals and MEE enforcement accelerate solvent-based adhesive phase-out in manufacturing zones. The Yangtze River Delta concentrates domestic formulation capacity serving electronics and EV battery assembly.
Japan
Electronics packaging specialists in Osaka and Nagoya specify high-purity silicone encapsulants for LED and power module applications. METI industrial standards govern moisture-cure kinetics in automated assembly lines. The Chubu region maintains captive silane coupling agent production to circumvent German and Japanese supplier concentration.
India
Mobile phone assembly under PLI scheme incentives drives hot-melt and pressure-sensitive adhesive consumption in Noida and Chennai. BIS certification requirements for imported formulations create localization pressure on multinational suppliers. Domestic formulation facilities in Maharashtra and Gujarat bypass finished goods import duties.
Specialty Adhesives Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The vendor base stratifies into three layers: integrated materials science conglomerates with cross-industry adhesive portfolios, regional formulation specialists serving single verticals, and captive producers supplying internal manufacturing demand. Consolidation pressure concentrates among mid-scale European and North American players facing feedstock volatility. Dominant competitive moves include backward integration into specialty monomer production and geographic expansion through qualified toll manufacturing partnerships.
Within the diversified conglomerate tier, 3M and Henkel AG & Co. KGaA exemplify scale-driven positioning across multiple end-use verticals. H.B. Fuller Company occupies a focused specialist position emphasizing geographic density in packaging applications. These three anchors demonstrate how portfolio breadth versus vertical depth creates distinct competitive moats in qualification-intensive segments.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Arkema Group (Bostik SA) |
| H.B. Fuller Company |
| Sika AG |
| Master Bond Inc. |
| Permatex |
| Avery Dennison |
| Illinois Tool Works Inc. |
| Others |
Cost & Logistics Intelligence
Polymer rheology specialists in the German chemical corridor command wage premiums that compress margin spreads between aerospace-grade epoxy formulations and standard construction adhesives. Labor-cost differentials between Bavarian R&D hubs and Asian manufacturing zones drive three-tier pricing stratification across certification tiers.
Pricing Analysis
Bundled technical service contracts separate premium aerospace specifications from unbundled commodity grades sold through distribution. Three-tier pricing structure across premium, standard, and economy levels reflects qualification intensity, with FDA biocompatibility certification and REACH compliance creating tier boundaries. Pricing pressure stems from petrochemical feedstock volatility transmitted through benzene and propylene derivative markets. Automotive OEMs exhibit lowest price sensitivity due to qualification lock-in, while construction project buyers drive aggressive spot-market negotiation.
Supply Chain Analysis
Workforce availability constraints in German and Japanese silane coupling agent production concentrate supply risk for moisture-cure silicone formulators. Raw material sourcing draws from Chinese epoxy resin capacity, South Korean acrylic monomer output, and German specialty amine production. Single-source vulnerability in high-purity silicone precursors threatens semiconductor packaging supply chains. Distribution runs through qualified toll manufacturing partnerships that bypass finished goods import duties in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty adhesives function as a geographic-arbitrage play where REACH compliance costs in Europe create 15-20% cost advantages for Indian and Southeast Asian formulation facilities serving export markets.
For Market Incumbents: Anchor European supply chains through backward integration into specialty monomer production to offset aromatic amine curing agent restrictions under ECHA evaluation. Defend specification authority by embedding technical service teams within OEM material engineering departments before battery platform designs freeze. Capacity expansion in Maharashtra and Gujarat captures PLI scheme benefits while circumventing BIS certification delays on imported finished goods.
For New Entrants and Emerging Players: Regional formulation specialists in Vietnam and Poland present partnership opportunities for packaging-grade hot-melt penetration. Target woodworking and flexible film lamination segments where qualification cycles compress below 12 months and incumbent technical service intensity remains lowest. Go-to-market execution should prioritize e-commerce fulfillment center relationships in Ohio and Hesse for metallocene polyolefin adhesive trials.
For Investors and Strategic Acquirers: Chemical conglomerates with cross-industrial adhesive portfolios are the most active acquirers in this space, seeking geographic density and qualification libraries. The 5-10 year viability window favors mid-scale European players with captive aerospace specifications facing consolidation pressure from feedstock volatility. Monitor ECHA substance evaluation timelines as inflection indicators for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive supply of epoxy curing agents insulates Henkel and 3M from ECHA aromatic amine restrictions. |
| Green Manufacturing Transition | ISCC PLUS certification unlocks EU Green Deal public procurement for bio-based polyurethane reactive systems. |
| Long-term Supply Agreement | Foundry partnerships in Hsinchu secure allocation for ultra-low alpha particle die-attach materials. |
| Joint Venture | Local formulation facilities in Noida bypass BIS import certification for PLI scheme mobile assembly. |
| Capacity Expansion | Yangtze River Delta plants serve domestic EV battery pack demand as MIIT enforces solvent phase-out. |
Research Approach
Bottom-up automotive and electronics modeling reconciled against top-down chemical production tracking forms the analytical core of this study. Primary interviews with adhesive formulators, OEM material engineers, procurement leads at Tier-1 suppliers, and distribution channel partners combined with secondary validation from ECHA substance evaluation databases, EPA Clean Air Act permitting records, SEC 10-K chemical segment disclosures, and customs trade data for monomer imports. Triangulation between demand-side specification libraries and supply-side capacity announcements ensures volume consistency.
Historical trendline analysis of formulation qualification cycles and petrochemical feedstock pricing established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product chemistry, end-use vertical, application method, and technology platform dimensions with regional regulatory cluster overlays. CAGRs derived from installed capacity expansion announcements and OEM platform launch schedules. Forecast inputs included EV battery pack content-per-vehicle assumptions and semiconductor advanced packaging adoption curves.
Revisions become necessary when REACH Annex XVII substance sunset dates accelerate, major petrochemical complex outages exceed 90-day durations, or FDA biocompatibility testing protocols extend beyond standard timelines. Forecasts reflect documented assumptions regarding qualification cycle stability and regulatory enforcement consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Europe Bone Glue Market