
 Adhesive Primer Market | 2026-2036
Adhesive Primer Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesive Primer Market Analysis
The adhesive primer market is consolidating around a widening gap between high-performance aerospace and electronics-grade formulations and commodity construction-grade products. Henkel leverages its global adhesives platform to sustain premium positioning in automotive OEM specifications. H.B. Fuller anchors its North American presence through specialized water-based primer lines for wood and furniture applications. Momentive Performance Materials differentiates via silicone-based primer chemistry for electronics substrates requiring thermal stability.
Adhesive primer is a surface-active coating applied to substrates prior to adhesive bonding to enhance wetting, chemical affinity, and interfacial adhesion strength, typically formulated with reactive silanes, chlorinated polyolefins, or epoxy resins at solids contents between 5% and 25%. Its primary industrial purpose is to prevent bond failure in critical assemblies where substrate surface energy mismatch would otherwise compromise structural integrity. Water-based formulations are gaining share fastest as manufacturers reformulate to meet tightening VOC regulations, while solvent-based systems retain dominance in aerospace and marine applications where performance specifications remain stringent. Epoxy primers command the highest margins due to their use in metal bonding for automotive and industrial equipment where corrosion resistance and load-bearing adhesion are non-negotiable.
EPA regulations in the United States limit hazardous air pollutant emissions from coating operations, compelling primer producers to certify products under NESHAP standards or risk exclusion from federal and state procurement channels. REACH registration requirements and the EU F-Gas Regulation in Europe impose substance-by-substance compliance burdens that favor established chemical producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving state-level VOC rules in California and New York alongside China's GB standards for construction chemicals, as divergence in regional compliance thresholds will determine which formulation platforms achieve scalable supply positions.
Market Dynamics
Water-based adhesive primer reformulation is compressing profit margins for solvent-dependent producers while opening specification windows for compliant formulators in automotive and electronics assembly chains.
Growth Catalysts
- REACH Phase-Down Mandates:The EU F-Gas Regulation and VOC limits under the EU Green Deal are forcing automotive OEMs to qualify water-based primers for lightweight bonding, expanding addressable specification volume.
- EV Battery Pack Assembly:Thermal management substrate preparation in electric vehicle manufacturing is pulling epoxy and silicone primer consumption as cell-to-pack architectures proliferate.
- China Infrastructure Investment:Domestic construction chemical standards under GB protocols are accelerating substrate preparation requirements for transportation and energy infrastructure projects.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and silane coupling agent prices fluctuate with benzene and methanol spot markets, compressing formulation margin stability for mid-tier producers.
- Specialty Chemical Supply Concentration:Chlorinated polyolefin supply chains cluster in East Asian merchant producers, creating single-source vulnerability for corrosion-resistant metal primers.
- Solvent-Based Performance Floor:Aerospace and marine specifications maintain solvent-borne adhesion requirements that water-based chemistry cannot yet satisfy, fragmenting R&D allocation.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component assembly are creating first-mover specification windows for thermal-stability primer platforms.
- Recyclable Adhesive Systems:Convergence of reversible bonding chemistry with primer surface activation is enabling circular economy service models in automotive disassembly operations.
- Direct-to-Plant Technical Service:On-site formulation tuning and application training is displacing traditional distributor technical support in high-volume automotive OEM contracts.
Industry Challenges
- Formulation Chemist Scarcity:Cross-functional expertise spanning polymer science, surface engineering, and regulatory compliance is concentrating at established chemical conglomerates, constraining specialist firm hiring pipelines.
- Multi-Jurisdiction Certification Lag:Simultaneous EPA NESHAP, REACH registration, and China MEE filing timelines extend product launch cycles by 18-24 months for new molecular platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesive Primer Market |
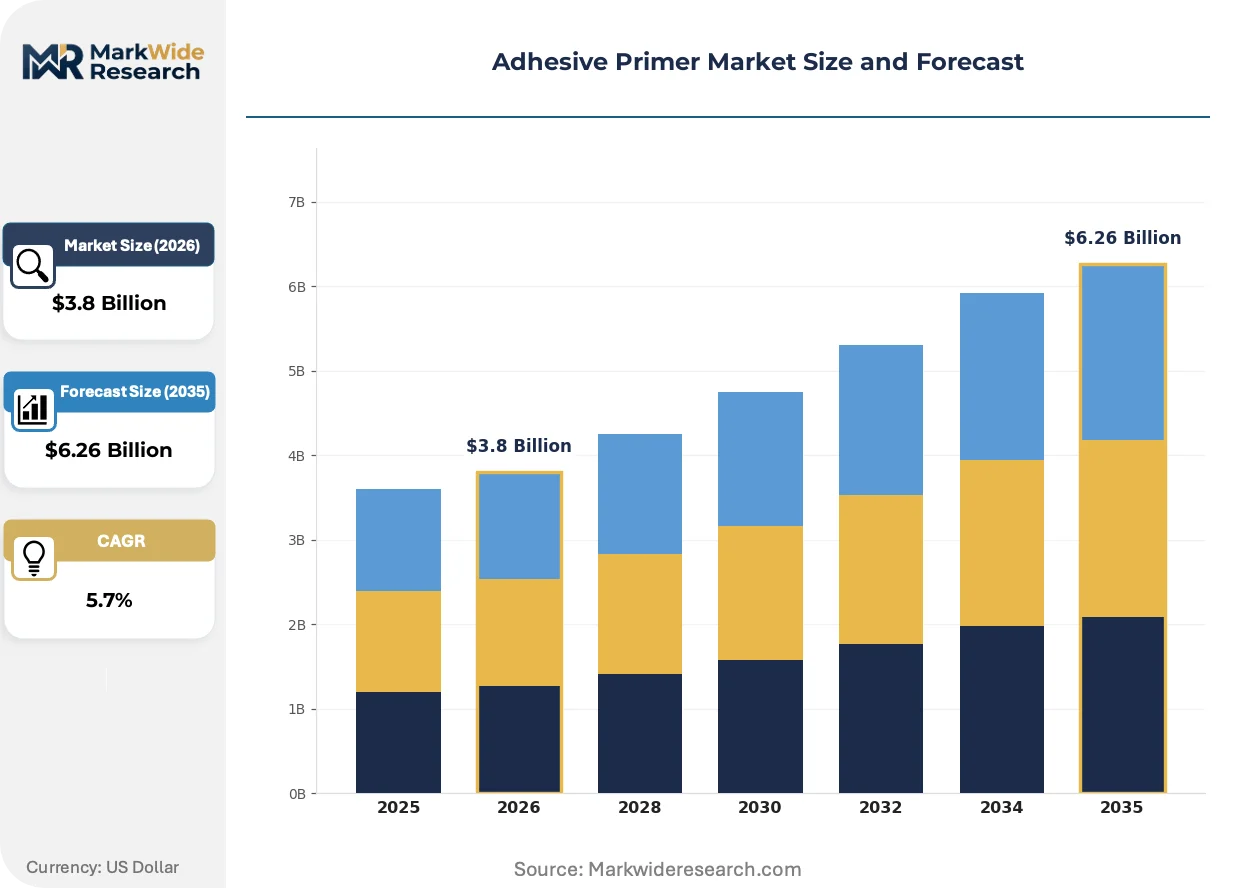
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Oil-Based, Epoxy Application: Construction, Automotive, Electronics, Furniture Material: Metal, Wood, Plastic, Glass End User: Manufacturers, Contractors, DIY Enthusiasts, Retailers |
| Companies Covered | 3M, Henkel, Arkema, Momentive Performance Materials, Eastman, LORD Corp, Sika, H.B. Fuller, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesive Primer Market Emerging Trajectories
Reactive silane chemistry is migrating from electronics into automotive metal bonding applications, while regulatory compliance automation is reshaping how formulation data flows through supply chains.
UV-curable primer technology is electrifying assembly line throughput constraints in consumer electronics manufacturing. Foxconn and Luxshare Precision are adopting cationic epoxy-silane systems for smartphone and wearable substrate preparation. This platform is compressing takt time requirements and displacing thermal cure ovens from compact assembly footprints.
The EPA's expanded NESHAP coating operation standards are compelling primer producers to certify VOC content through third-party audit protocols. Facilities in Michigan and Ohio face emission threshold enforcement that disqualifies uncertified products from federal procurement channels. Automotive Tier-1 suppliers are consolidating qualified vendor lists to pre-certified formulators with documented compliance infrastructure.
Automotive OEMs are unbundling primer specification authority from adhesive system suppliers. Procurement teams at Stellantis and BMW Group now require standalone primer technical data packages with substrate-specific adhesion validation. This pattern is most visible in German and US Midwest assembly operations where bonding failure liability has shifted from adhesive vendors to substrate preparation chemical providers.
Adhesive Primer Market Segmentation
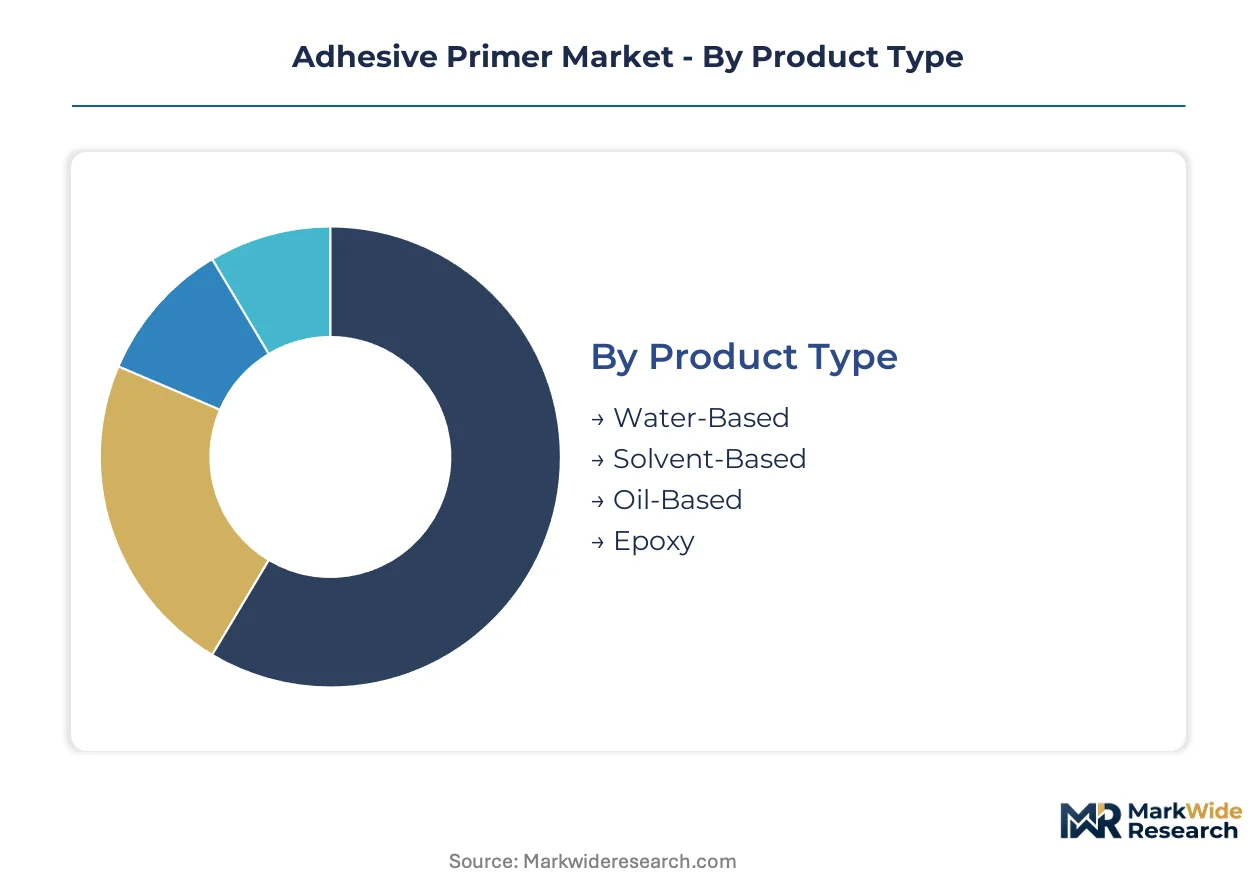
Adhesive primer segmentation reveals divergent compliance burdens across formulation chemistries and end-use specifications. Product type and application categories carry distinct certification requirements that reshape competitive access and margin structures.
Product Type:
Water-based primers face REACH registration and EPA NESHAP certification demands, while solvent-based systems navigate aerospace performance floors and marine specifications.
- Water-Based:Formulated with acrylic and polyurethane dispersions at 5-15% solids, these systems require extensive VOC compliance documentation for automotive OEM qualification. German automakers and Michigan Tier-1 suppliers are consolidating procurement around certified water-based platforms as EU Green Deal timelines compress. Leading the category by volume: Solvent-Based. Growing fastest: Water-Based.
- Solvent-Based:Chlorinated polyolefin and aromatic hydrocarbon carriers deliver superior wetting on low-surface-energy substrates. Aerospace assembly lines in Toulouse and Hamburg maintain solvent-borne specifications that water-based chemistry cannot yet satisfy, preserving premium positioning despite regulatory pressure.
- Oil-Based:Alkyd and natural oil resin systems serve heritage furniture restoration and specialty wood coating applications where penetration depth matters more than cure speed.
- Epoxy:Two-component amine-cured systems command specification authority in EV battery pack assembly and industrial metal bonding where corrosion resistance is non-negotiable.
Margin concentration aligns with performance tier: Epoxy captures premium positioning. Volume scale favors reformulated water-based platforms.
Application:
Construction applications pull commodity-grade formulations through distributor channels, while automotive and electronics segments demand direct technical service relationships.
- Construction:Substrate preparation for infrastructure and commercial building envelopes drives steady consumption of water-based and solvent-based primers through regional distributor networks. Chinese GB standards for construction chemicals are accelerating specification requirements for transportation and energy infrastructure projects in Jiangsu and Guangdong provinces.
- Automotive:Lightweight bonding applications for aluminum and composite body-in-white assemblies require epoxy and silicone primer platforms with documented thermal cycling performance. Stellantis and BMW Group procurement teams now require standalone primer technical data packages with substrate-specific adhesion validation.
- Electronics:Thermal management substrate preparation in cell-to-pack EV architectures and smartphone assembly lines pulls specialized formulations.
- Furniture:Wood and panel bonding applications concentrate demand in North American and European manufacturing clusters.
Construction dominates volume throughput. Electronics expands most quickly on EV and consumer device assembly demand.
Material:
Substrate surface energy and corrosion susceptibility determine primer chemistry selection and application protocol complexity.
- Metal:Aluminum and steel substrates in automotive and industrial equipment require epoxy and chlorinated polyolefin primers with salt spray resistance certification. Corrosion protection specifications in German automotive assembly and Japanese industrial equipment manufacturing sustain premium formulation demand.
- Wood:Porosity and moisture content variability drive specification of oil-based and water-based penetrating primers in furniture and construction applications.
- Plastic:Low-surface-energy polyolefin and engineered thermoplastic substrates demand reactive silane and flame-treatment-compatible primer systems.
- Glass:Optical and display applications require ultra-low residue silane coupling agents with refractive index matching.
Metal substrates anchor volume consumption. Plastic applications gain share fastest on polymer substitution in automotive lightweighting.
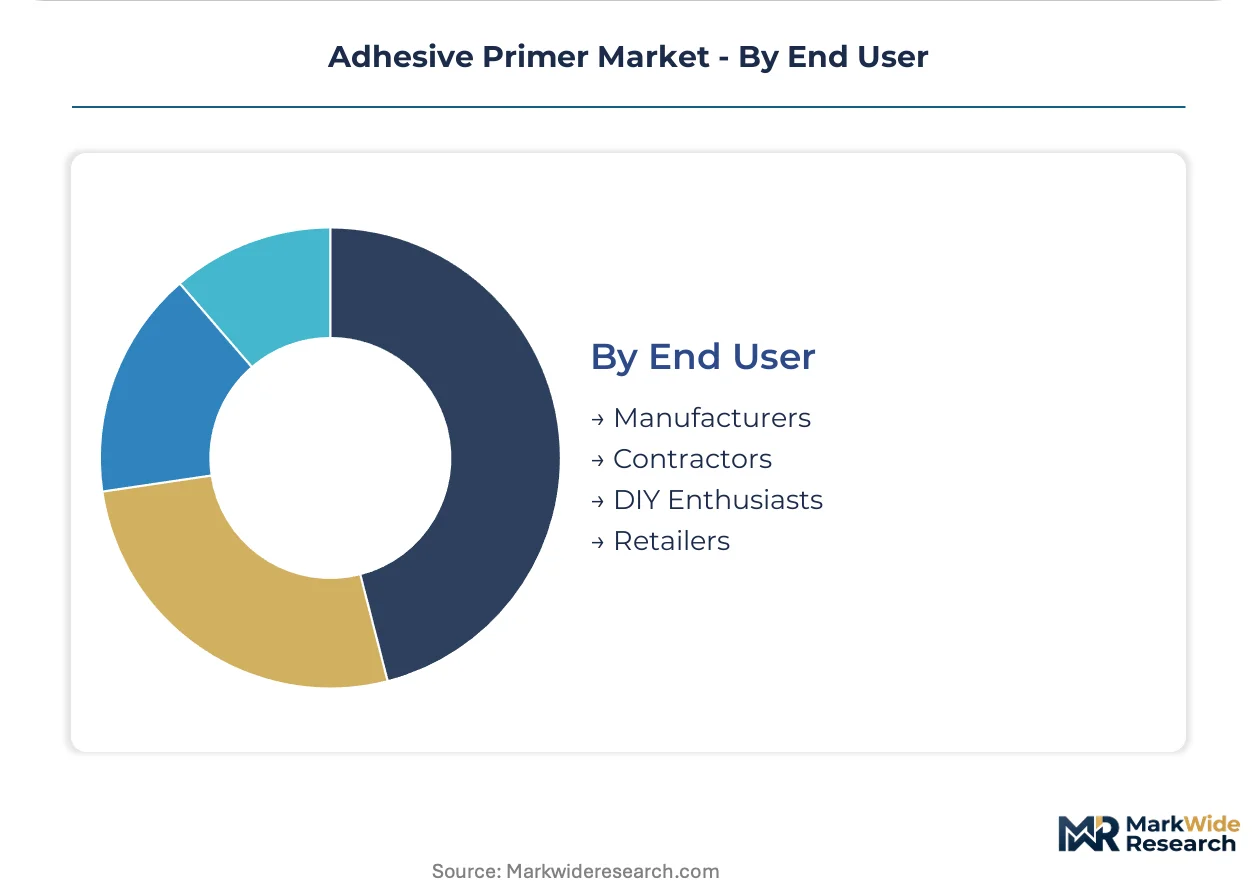
End User:
Procurement authority concentrates with manufacturers holding direct formulation relationships, while contractor and DIY channels flow through distribution.
- Manufacturers:Automotive OEMs, electronics assemblers, and industrial equipment producers specify primers through qualified vendor lists with documented compliance infrastructure. Foxconn and Luxshare Precision adopt UV-curable cationic epoxy-silane systems for smartphone substrate preparation.
- Contractors:Construction and installation service providers source through regional distribution with application training support.
- DIY Enthusiasts:Retail channel consumers purchase small-format water-based primers for home repair and craft applications.
- Retailers:Big-box and specialty hardware stores curate primer assortments based on regional VOC regulations and seasonal demand patterns.
Manufacturers command specification authority and margin capture. Retail channels represent highest volume dispersion with lowest per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta dominates adhesive primer formulation capacity, hosting epoxy and silicone chemistry clusters serving automotive OEMs and electronics assemblers across East Asia.
United States
Automotive lightweighting programs in Michigan and Ohio pull chlorinated polyolefin and epoxy primer consumption for aluminum body-in-white assembly. EPA NESHAP coating operation standards enforce VOC certification through third-party audit protocols. Detroit-Hamtramck assembly corridors consolidate procurement around pre-certified formulators with documented compliance infrastructure.
Germany
Stellantis and BMW Group procurement teams require standalone primer technical data packages with substrate-specific adhesion validation for composite bonding applications. REACH Phase-Down mandates and EU F-Gas Regulation impose substance-by-substance compliance burdens favoring established chemical producers. Stuttgart and Munich assembly operations drive specification authority for thermal cycling performance documentation.
China
Domestic EV production and infrastructure investment accelerate substrate preparation requirements under GB standards for construction chemicals. MEE filing timelines extend product launch cycles for new molecular platforms entering the market. Jiangsu and Guangdong provinces concentrate demand for transportation and energy infrastructure primer applications.
Japan
Industrial equipment manufacturing sustains premium formulation demand for corrosion protection specifications on metal substrates. METI oversees chemical product safety frameworks influencing primer registration requirements. Nagoya and Osaka industrial corridors anchor chlorinated polyolefin supply chain concentration for corrosion-resistant metal primers.
India
PLI scheme incentives for semiconductor and component assembly create first-mover specification windows for thermal-stability primer platforms. BIS certification requirements shape construction chemical quality standards for infrastructure projects. Maharashtra and Gujarat manufacturing clusters attract electronics assembly investment pulling specialized substrate preparation chemicals.
Adhesive Primer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry tiers, with epoxy and silicone-based systems commanding specification authority in automotive and electronics segments while water-based platforms compete on compliance certification. The vendor base concentrates among diversified chemical conglomerates with dedicated regulatory affairs capacity and regional formulation facilities. Three archetypes dominate: global adhesives platforms leveraging cross-product specification relationships, specialized silicone and epoxy chemistry houses, and regional water-based formulators capturing VOC-driven substitution demand. M&A activity targets compliant formulation assets in Europe and North America, while capacity expansion concentrates in Yangtze River Delta and Gujarat chemical corridors.
Among diversified chemical conglomerates, Henkel and H.B. Fuller occupy positions spanning multiple adhesive chemistry tiers, with Henkel exemplifying global platform leverage and H.B. Fuller anchoring North American water-based specialization. Momentive Performance Materials sits within the specialty silicone chemistry tier, representing thermal-stability formulation expertise for electronics substrate applications.
| Leading Market Players |
|---|
| 3M |
| Henkel |
| Arkema |
| Momentive Performance Materials |
| Eastman |
| LORD Corp |
| Sika |
| H.B. Fuller |
| PPG Industries |
| Others |
Supply Flow & Price Mechanics
EU Green Deal VOC mandates gate qualified supply and premium-tier pricing access, compressing solvent-dependent producers while rewarding certified water-based formulators with specification authority in automotive OEM procurement channels. Buyers now face bifurcated sourcing where compliance documentation commands measurable price premiums over uncertified alternatives.
Pricing Analysis
Yield-guaranteed adhesion performance anchors value-based pricing for epoxy and silicone primer tiers in EV battery and electronics applications. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified formulations from construction-grade commodities, with certification level and volume scale driving differentiation. Cost compression in water-based segments is intensifying because reformulation R&D expenses outpace volume scaling. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to liability exposure, while construction contractors remain most sensitive to per-unit differentials.
Supply Chain Analysis
Freight cost volatility from East Asian chlorinated polyolefin producers to European and North American formulators is reshaping regional sourcing strategies. Manufacturing gravity centers on China, Germany, and the United States, with epoxy resin and silane coupling agents drawing from benzene and methanol feedstock markets. Single-source vulnerability concentrates in Japanese chlorinated polyolefin supply for corrosion-resistant metal primers. Distribution runs through qualified vendor lists with documented compliance infrastructure for automotive OEMs, while construction channels flow through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adhesive primer market has become a vertical-integration race, with backward integration into silane coupling agent production emerging as the decisive margin-defense lever for established players.
For Market Incumbents: To counter water-based reformulation margin compression, deepen captive supply of specialty silane intermediates and expand certification infrastructure for simultaneous EPA NESHAP, REACH, and China MEE filing capacity. Anchor procurement relationships through direct-to-plant technical service teams that displace distributor support in high-volume automotive contracts. For New Entrants and Emerging Players: Begin with India's PLI-driven electronics manufacturing corridors, where thermal-stability primer specifications remain underpenetrated by incumbent silicone specialists. Target Maharashtra and Gujarat assembly clusters with localized formulation facilities and BIS certification support. Lead with UV-curable platform demonstrations that compress takt time for smartphone substrate preparation. For Investors and Strategic Acquirers: First-mover water-based qualification by Stellantis or BMW Group procurement teams is the leading indicator that compliant formulation assets will command sustained premium multiples over commodity solvent-dependent competitors. Acquire regional water-based specialists with documented EPA and REACH compliance infrastructure rather than greenfield capacity. Monitor EU F-Gas Regulation phase-down timelines as the inflection signal for accelerated specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Intermediates | Captive supply of Momentive-grade coupling agents defends margin against benzene feedstock volatility. |
| Simultaneous Multi-Jurisdiction Certification | Parallel EPA NESHAP, REACH, and China MEE filing capacity compresses product launch cycles by 12-18 months. |
| Direct-to-Plant Technical Service Deployment | On-site formulation tuning at Detroit-Hamtramck corridors displaces traditional distributor relationships. |
| UV-Curable Platform Scale-Up | Cationic epoxy-silane systems at Foxconn assembly lines electrify throughput for smartphone substrate preparation. |
| Regional Water-Based Formulation Acquisition | Compliant assets in Michigan and Ohio capture VOC-driven substitution demand from solvent-dependent competitors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving formulation chemists, automotive OEM procurement leads, construction chemical distributors, and regulatory affairs directors at diversified chemical conglomerates. Bottom-up volume estimates triangulated against top-down value projections derived from ACC and Cefic industry reports, SEC 10-K disclosures, and China customs trade statistics.
Data-stream reconciliation across product type, application, material substrate, and end-user procurement authority generated segment-level projections over the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating EV battery pack assembly growth, infrastructure investment patterns, and regulatory phase-down timelines. Forecast inputs included OEM qualification pipeline visibility, chlorinated polyolefin supply chain concentration metrics, and formulation chemist labor market tightness indices.
Underlying measurement precision varies by segment; automotive and electronics specifications carry tighter precision than construction commodity grades due to documented qualification pipelines and qualified vendor list transparency. Forecasts reflect assumptions about regulatory enforcement consistency, feedstock price correlation stability, and OEM unbundling of primer specification authority. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Brazil Adhesives Market