
 Thailand Sealants Market | 2026-2036
Thailand Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Sealants Market Analytics
Technical service contracts for application engineering and on-site joint inspection are decoupling sealant procurement from simple product transactions in Thailand. Dow Thailand Group leverages its Rayong petrochemical integration to sustain cost-competitive silicone supply chains for domestic construction. Sika Thailand anchors its position through specialized waterproofing system packages that bundle membranes with polyurethane sealants for infrastructure clients. Momentive Performance Materials (Thailand) Ltd. differentiates via R&D intensity in high-temperature silicone formulations serving the Eastern Seaboard's electronics manufacturing zone.
Thailand sealants comprise viscoelastic compounds—typically silicone, polyurethane, acrylic, or butyl-based—formulated to fill gaps, block moisture ingress, and accommodate thermal movement across substrates ranging from concrete to aluminum glazing systems. Silicone sealants dominate architectural applications due to UV stability and elongation properties exceeding 400%, while polyurethane variants capture industrial adhesion demand where tensile strength and chemical resistance matter. The construction end-user segment leads volume consumption, driven by Bangkok's high-rise residential pipeline and EEC infrastructure projects, whereas automotive applications in butyl and polyurethane formulations represent the fastest-growing margin pool as electric vehicle assembly expands in Chonburi and Rayong provinces.
Thailand's Ministry of Industry enforces TISI standards for construction chemical performance, while the Department of Industrial Works regulates VOC emissions under the Factory Act, compelling reformulation investments from sealant manufacturers. The country's national pharmaceutical regulator and Board of Investment jointly scrutinize imported raw material safety profiles, shaping market access for foreign suppliers. Stakeholders must monitor how Thailand's evolving green building certification criteria and Eastern Economic Corridor zone-specific procurement rules will redefine specification power between local distributors and multinational direct-sales operations.
Market Dynamics
Thailand's Board of Investment green building incentives are redirecting sealant procurement specifications toward low-VOC polyurethane systems, forcing formulation investments that favor domestic producers with Rayong petrochemical integration.
Growth Catalysts
- EEC Infrastructure Pipeline:Thailand's Eastern Economic Corridor zone mandates industrial-grade sealants for petrochemical complexes and automotive assembly plants, creating concentrated demand pull.
- TISI Performance Standards:Thailand's Ministry of Industry enforcement of construction chemical benchmarks elevates specification barriers that qualified domestic suppliers exploit.
- Silicone UV Stability:Bangkok's high-rise glazing contractors specify silicone sealants for elongation properties exceeding 400% in tropical exposure conditions.
Market Restraints
- Petrochemical Feedstock Volatility:Silicone and polyurethane raw material costs fluctuate with Rayong complex output, compressing margin predictability for formulators.
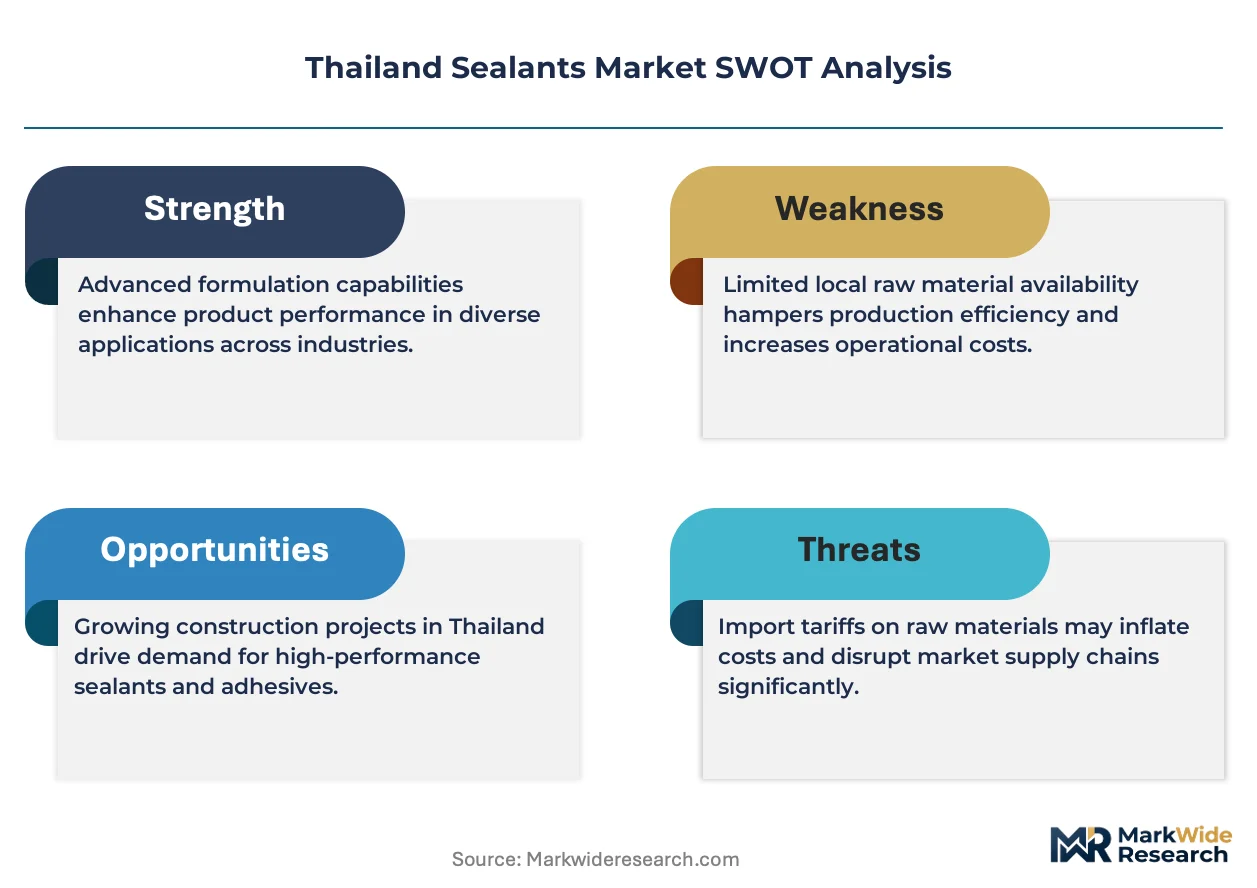
- Import Dependency for Specialty Additives:Thailand's national pharmaceutical regulator and Board of Investment jointly scrutinize imported raw material safety profiles, delaying market access for foreign suppliers.
- Acrylic Substitution in Cost-Sensitive Segments:Budget construction projects in secondary provinces substitute acrylic sealants for silicone in non-structural joints, capping premium penetration.
Strategic Opportunities
- Chonburi-Rayong EV Assembly Expansion:Electric vehicle battery pack sealing and thermal management applications create demand for high-temperature silicone formulations.
- Technical Service Contract Bundling:Application engineering and on-site joint inspection services decouple sealant procurement from commodity transactions, enabling margin capture.
- Green Building Certification Tailwinds:Evolving criteria under Thailand's green building programs redirect specification power toward low-emission system packages.
Industry Challenges
- Specialized Applicator Skill Scarcity:Proper joint preparation and sealant installation for high-rise glazing and infrastructure waterproofing requires certified technicians that contractors struggle to source.
- Factory Act VOC Compliance Timelines:The Department of Industrial Works mandates reformulation investments that strain R&D bandwidth at mid-scale domestic producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Sealants Market |
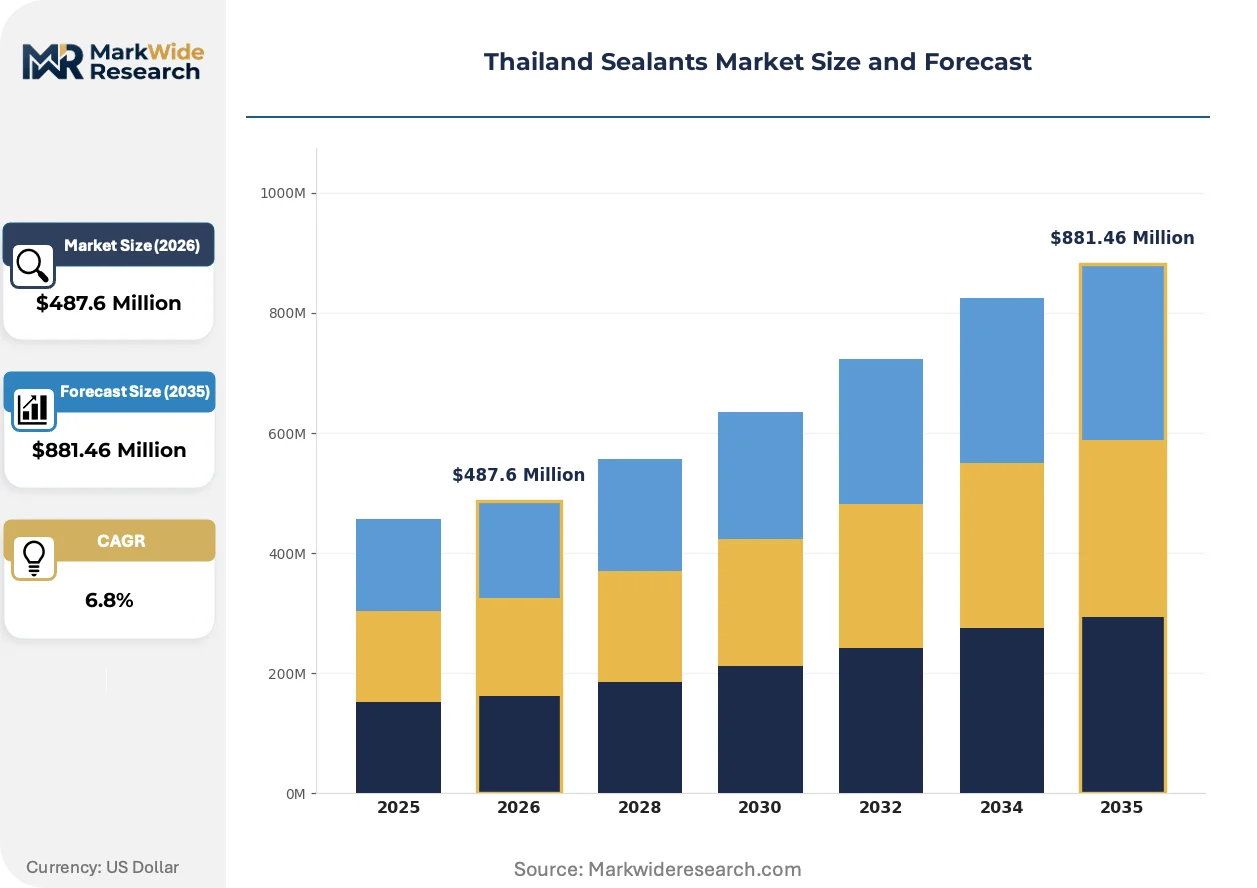
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Butyl End User: Construction, Automotive, Aerospace, Marine Application: Adhesion, Sealing, Insulation, Waterproofing Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | 3M, SCG Chemicals, Sika Thailand, Momentive Performance Materials (Thailand) Ltd., H.B. Fuller (Thailand) Ltd., Dow Thailand Group, BASF (Thailand) Ltd., Thai Industrial Sealants Co., Ltd., Henkel (Thailand) Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Sealants Market Evolving Landscape
Digital specification platforms and on-site quality verification technologies are compressing the traditional sealant procurement cycle, forcing suppliers to embed technical validation earlier in project workflows.
Two-component polyurethane systems with integrated moisture-cure accelerators are decentralizing application control from factory conditions to challenging on-site environments. Bangkok infrastructure contractors adopt these systems for monsoon-season waterproofing where ambient humidity previously delayed cure times. This technology is decentralizing project scheduling risk away from weather-dependent application windows toward year-round installation capability.
Thailand's Department of Industrial Works enforcement of Factory Act VOC emission limits is compelling sealant manufacturers to reformulate solvent-based systems into waterborne or 100%-solid alternatives. The industrial consequence is accelerated R&D spending at domestic producers with captive petrochemical feedstock. Construction chemical segments serving Bangkok's high-rise residential pipeline face the steepest compliance costs and are responding through pre-certified low-emission product bundles.
Specification authority is migrating from general contractors to specialized waterproofing consultants who demand system-level warranties bundling membranes with compatible sealants. This behavior disrupts traditional distributor relationships and replaces them with direct technical partnerships between formulators and engineering firms. The shift is most visible in Phuket and Bangkok infrastructure projects where joint-performance guarantees have become mandatory bid requirements.
Thailand Sealants Market Segmentation
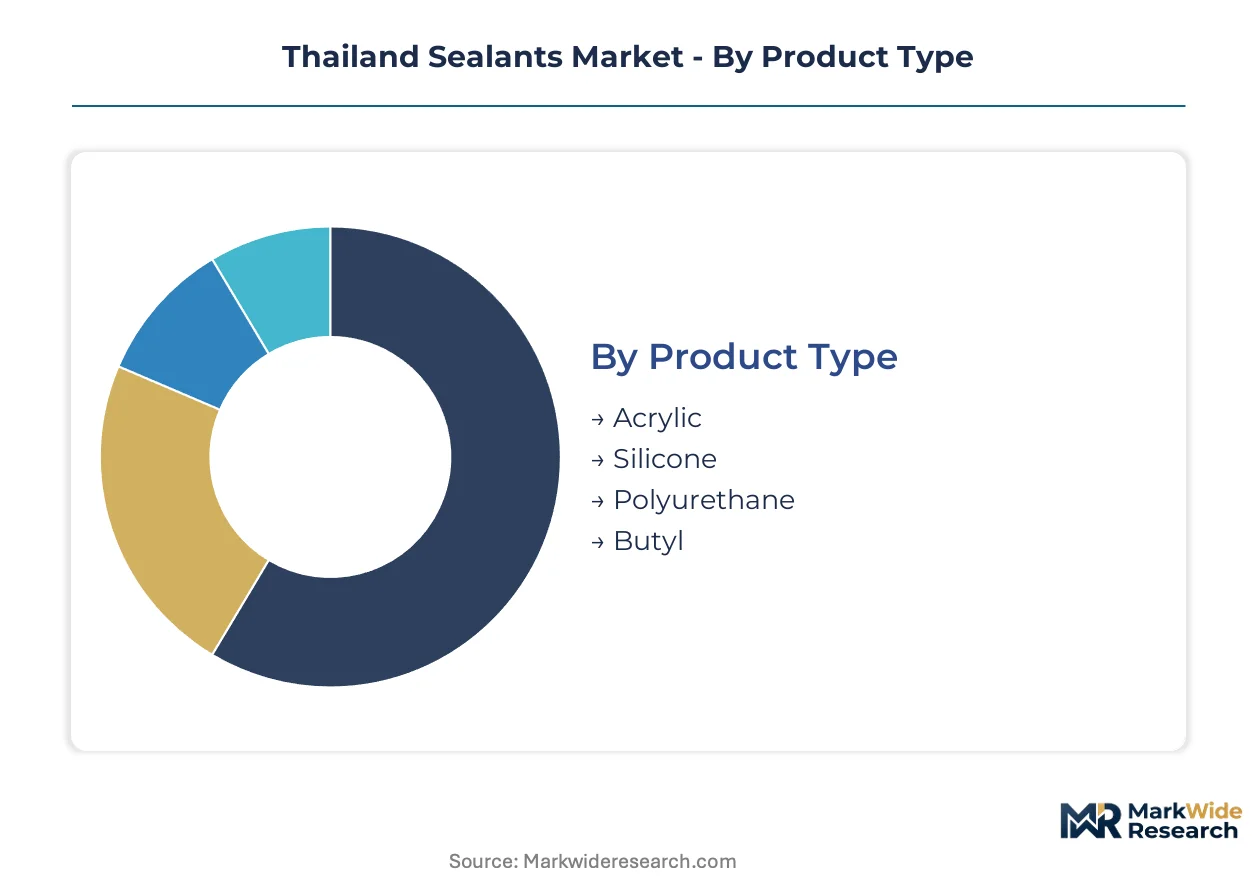
Sealant specification in Thailand fragments across performance tiers, end-use engineering requirements, and procurement channel economics. Understanding how demand concentrates within each axis reveals where formulation investments and distribution partnerships yield sustainable margin capture.
Product Type:
Technology selection hinges on thermal movement accommodation, chemical exposure profiles, and cure chemistry compatibility with tropical humidity cycles.
- Silicone:UV-stable formulations with elongation exceeding 400% dominate Bangkok high-rise glazing and façade engineering. Rayong petrochemical integration sustains cost-competitive supply chains for domestic construction volume.
- Polyurethane:Tensile strength and chemical resistance position these systems for industrial adhesion in Eastern Economic Corridor manufacturing plants. Low-VOC reformulations capture Board of Investment green building incentives.
- Acrylic:Budget-sensitive secondary province projects substitute these for non-structural joint applications where premium performance specifications are waived.
- Butyl:Electric vehicle battery pack sealing in Chonburi and Rayong provinces drives thermal management formulation demand.
Mature deployment sits with silicone in established construction specifications. Newer deployment is concentrated in polyurethane low-VOC systems responding to Factory Act compliance timelines.
End User:
Customer archetypes diverge sharply between project-based construction procurement and continuous manufacturing supply agreements.
- Construction:Bangkok's high-rise residential pipeline and EEC infrastructure projects generate concentrated volume demand for waterproofing and glazing systems. TISI performance standards elevate specification barriers that qualified suppliers exploit.
- Automotive:Electric vehicle assembly expansion across Chonburi and Rayong creates the steepest expansion trajectory for high-temperature silicone and butyl formulations in battery sealing applications.
- Aerospace:Limited domestic MRO activity constrains addressable market scale for specialty aviation-grade sealants.
- Marine:Phuket and Eastern Seaboard shipyard maintenance generates intermittent demand for saltwater-resistant polyurethane systems.
Procurement sophistication clusters with construction engineering firms. Volume growth is accelerating fastest in automotive manufacturing integration.
Application:
Functional use cases determine whether specification authority rests with general contractors, waterproofing consultants, or manufacturing engineers.
- Waterproofing:Monsoon-season infrastructure projects in Bangkok drive two-component polyurethane adoption with moisture-cure accelerators. Specification authority has migrated to specialized consultants demanding system-level warranties bundling membranes with compatible sealants.
- Sealing:High-rise glazing contractors specify silicone for thermal movement accommodation across aluminum-to-glass interfaces in tropical exposure conditions.
- Adhesion:Industrial-grade demand from petrochemical complexes and automotive plants concentrates in the Eastern Economic Corridor.
- Insulation:Thermal barrier applications in electronics manufacturing zones require R&D-intensive high-temperature formulations.
Technical service bundling is most advanced in waterproofing. Direct formulator-to-engineer partnerships are displacing traditional distributor relationships fastest in this application.
Distribution Channel:
Channel economics reflect project scale, specification complexity, and the degree of technical validation required pre-purchase.
- Direct Sales:Large infrastructure and industrial projects engage formulators for application engineering contracts and on-site joint inspection services. Digital specification platforms compress procurement cycles for technically validated buyers.
- Wholesale:Construction material distributors serve Bangkok and Phuket contractors with standardized product lines and volume pricing.
- Retail:Secondary province hardware channels move acrylic sealants for cost-sensitive residential maintenance applications.
- Online:Emerging procurement route for specification-grade products where digital quality verification technologies reduce pre-purchase uncertainty.
Relationship depth is greatest in direct sales. Channel expansion is climbing fastest in online platforms serving technically sophisticated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's sealant production concentrates in Rayong's petrochemical corridor, while consumption spreads across Bangkok's construction belt and the Eastern Economic Corridor's manufacturing zones. This geographic split shapes logistics costs and specification relationships throughout the supply chain.
Bangkok Metropolitan Region
High-rise residential towers and commercial glazing projects drive silicone sealant procurement at scale. TISI performance standards enforce quality benchmarks across construction chemical imports. Sathorn and Sukhumvit corridors host specification consultants who bundle membrane systems with compatible sealants for waterproofing tenders.
Eastern Economic Corridor
Chonburi and Rayong provinces anchor industrial-grade demand from petrochemical complexes and emerging electric vehicle assembly plants. Thailand's Board of Investment incentives redirect formulation investments toward low-VOC polyurethane systems for green building compliance. Amata City and WHA industrial estates consume specialized adhesives for battery pack sealing and thermal management applications.
Phuket and Southern Seaboard
Marine maintenance and resort infrastructure generate intermittent demand for saltwater-resistant polyurethane systems. Monsoon-season waterproofing contracts accelerate two-component system adoption with moisture-cure accelerators. Patong and Kata beachfront developments specify UV-stable silicones for façade longevity in tropical exposure.
Chiang Mai and Northern Region
Budget-sensitive residential construction in secondary cities substitutes acrylic sealants for non-structural joint applications. Provincial hardware distribution channels serve cost-conscious contractors outside premium specification networks. Factory Act VOC enforcement timelines lag Bangkok, delaying low-emission system penetration.
Thailand Sealants Market Competitive Landscape
Top-tier vendors anchor multinational direct-sales operations, while mid-scale domestic producers compete through wholesale distribution and technical service bundling. The market exhibits tiered concentration around petrochemical-integrated formulators and specialized construction chemical suppliers. Three archetypes dominate: Rayong-integrated silicone producers, Bangkok-based waterproofing system packagers, and regional applicator networks with specification influence. Competitive moves center on application engineering contracts and green building certification pre-qualification.
Within the integrated petrochemical tier, Dow Thailand Group and SCG Chemicals occupy positions sustained by captive feedstock access. Sika Thailand exemplifies the system-packaging archetype through bundled membrane-sealant offerings. Momentive Performance Materials (Thailand) Ltd. represents R&D-intensive specialists serving high-temperature industrial applications.
| Leading Market Players |
|---|
| 3M |
| SCG Chemicals |
| Sika Thailand |
| Momentive Performance Materials (Thailand) Ltd. |
| H.B. Fuller (Thailand) Ltd. |
| Dow Thailand Group |
| BASF (Thailand) Ltd. |
| Thai Industrial Sealants Co., Ltd. |
| Henkel (Thailand) Ltd. |
| Others |
Value Network & Pricing Analysis
Thailand's Factory Act VOC emission mandates gate both qualified supply and premium-tier pricing access, compelling reformulation investments that stratify formulators into certified premium suppliers versus non-compliant economy-tier competitors. Board of Investment green building incentives further concentrate specification power with domestic producers holding Rayong petrochemical integration.
Pricing Analysis
Cost-down pressure on standard-grade sealants accelerates because acrylic substitution in secondary province construction erodes silicone penetration. Pricing stratifies across premium, standard, and economy tiers, with certification grade and volume scale as primary differentiation drivers. Bangkok high-rise glazing contractors exhibit lowest price sensitivity due to TISI-mandated performance guarantees, while provincial hardware channels serving residential maintenance face acute margin compression.
Supply Chain Analysis
Thailand's Board of Investment domestic-content incentives are reshaping sourcing toward Rayong-integrated formulators with captive silicone feedstock. Raw material dependencies rest on methanol-based silane precursors, polyether polyols, and specialty moisture-cure accelerators imported from China, South Korea, and Japan. Single-source vulnerability concentrates in high-temperature silicone formulations serving Eastern Seaboard electronics zones. Distribution runs through direct technical partnerships for infrastructure projects and wholesale construction material channels for standardized volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's sealant market reads as supply-constrained by specialized applicator scarcity, a capacity bottleneck that props pricing power for qualified technical service providers. Formulators with certified installation networks capture specification authority ahead of commodity competitors.
For Market Incumbents: Anticipate acrylic substitution threats in secondary provinces by accelerating TISI pre-certification for low-VOC polyurethane bundles. Deepen backward integration into Rayong petrochemical feedstock to defend margin position against import-dependent formulators facing raw material approval delays.
For New Entrants and Emerging Players: Capture white-space in Chonburi-Rayong EV battery sealing applications where high-temperature silicone demand outpaces qualified supply. Target direct technical partnerships with waterproofing consultants in Bangkok infrastructure tenders, bypassing wholesale distribution channels where incumbents hold volume lock-in.
For Investors and Strategic Acquirers: Board of Investment green building incentive expansion is the leading indicator that low-VOC formulation capability will separate viable acquisition targets from stranded assets. Prioritize mid-scale domestic producers with Rayong petrochemical integration and pre-certified emission-compliant product lines over import-dependent distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | Rayong petrochemical integration insulates margin volatility from imported feedstock cost swings. |
| Green Manufacturing Transition | Waterborne polyurethane reformulation satisfies Factory Act VOC timelines for Bangkok construction. |
| Technical Service Contract Expansion | Application engineering partnerships displace distributor relationships in infrastructure waterproofing. |
| Long-term Supply Agreement | Eastern Economic Corridor automotive plants lock in battery sealant volumes through EV assembly ramp. |
| Joint Venture with Applicator Networks | Certified installation capability scarcity creates specification gatekeeper position in high-rise glazing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at Rayong petrochemical complexes, procurement leads at Eastern Economic Corridor automotive plants, waterproofing consultants in Bangkok, and distribution channel partners. TISI construction chemical standards, Department of Industrial Works emission filings, and Board of Investment incentive disclosures provided regulatory validation. Bottom-up demand modeling and top-down supply capacity estimates were triangulated for cross-verification.
Reconciliation of production volume data from petrochemical complexes with consumption patterns across Bangkok construction belts and Eastern Seaboard manufacturing zones shaped the analytical framework across the analysis window. Segmentation dimensions included formulation chemistry, end-use industry, performance certification tier, and regional procurement channel. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements, with monsoon-season waterproofing intensity and EV assembly line commissioning schedules as industry-specific forecast inputs.
The model holds under sustained Board of Investment incentive continuity and TISI enforcement consistency; deviation in Factory Act compliance timelines or raw material import approval delays would shift volume toward non-compliant economy-tier suppliers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market