
 Composite Rollers Market | 2026-2036
Composite Rollers Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Rollers Market Analysis
Buyer concentration is shifting as mining conglomerates consolidate procurement across continental operations, reducing vendor counts while raising technical specifications. Lorbrand Composites leverages its South African manufacturing base to serve African and Australian bulk-handling operators with corrosion-resistant designs. NEPEAN Conveyors anchors its position through backward integration into conveyor system engineering, capturing specification authority early in project development. Pronexos differentiates via specialized hollow roller architectures for high-speed printing and converting applications.
Composite rollers are cylindrical industrial components fabricated from fiber-reinforced polymer matrices, typically carbon fiber or glass fiber bound in thermoset resins, engineered to achieve strength-to-weight ratios exceeding steel alternatives while eliminating corrosion susceptibility. Solid rollers dominate heavy-load mining and aggregate applications where deflection tolerance is critical, while hollow configurations capture aerospace and precision conveyor segments where mass reduction translates directly to energy savings. Glass fiber formulations sustain cost-sensitive industrial equipment demand, whereas carbon fiber grades command premium positioning in marine and aerospace installations where fatigue resistance justifies material expenditure.
ISO 9001 quality management and REACH substance restrictions govern European composite roller supply, with ECHA chemical registrations determining permissible resin formulations and fiber coatings. The US OSHA machinery guarding standards and EPA industrial emissions frameworks shape North American product design requirements, particularly for conveyor system integrations in regulated manufacturing environments. Stakeholders must monitor evolving carbon border adjustment mechanisms and fiber recycling mandates, as circular economy compliance will increasingly determine supplier eligibility across major industrial procurement channels.
Market Dynamics
Mining conglomerates consolidating continental procurement operations are compressing vendor counts while elevating technical specifications for corrosion-resistant, lightweight roller systems. This buyer concentration is reshaping competitive positioning toward specification authority and backward integration capabilities.
Growth Catalysts
- EU F-Gas Regulation:Tightening material specifications for industrial components are pushing manufacturers toward carbon fiber and aramid alternatives, expanding addressable demand for compliant composite formulations.
- Bulk material handling automation:Conveyor systems operators in mining are specifying hollow roller architectures to capture energy savings from rotational mass reduction.
- REACH compliance frameworks:ECHA chemical registrations determining permissible resin formulations are filtering out incumbent metal roller suppliers lacking polymer engineering capabilities.
Market Restraints
- Carbon fiber feedstock volatility:Aerospace and wind energy sectors compete for limited carbon fiber tow capacity, creating input cost instability for premium roller grades.
- Specialized curing equipment concentration:Autoclave and out-of-autoclave manufacturing assets cluster in Germany and Japan, constraining supply scalability for new entrants.
- Thermoset resin recyclability limitations:Cross-linked polymer matrices resist conventional reprocessing, exposing suppliers to emerging circular economy compliance risks.
Strategic Opportunities
- Carbon border adjustment mechanisms:Upcoming EU carbon pricing on imports creates competitive openings for low-carbon-footprint composite rollers against steel alternatives.
- High-speed printing and converting:Precision hollow roller demand from packaging automation OEMs remains underpenetrated by incumbent mining-focused suppliers.
- Marine and offshore installations:Fatigue-resistant carbon fiber grades command premium positioning where corrosion elimination justifies material expenditure.
Industry Challenges
- Polymer-matrix bonding expertise scarcity:Qualified process engineers capable of optimizing fiber-resin interfaces for load-bearing cylindrical geometries remain concentrated in automotive and aerospace supplier networks.
- ISO 9001 certification timelines:Quality management system audits for European supply eligibility extend 12-18 months, delaying market entry for qualified technical products.
- Legacy steel roller inventory inertia:Mining operators with sunk capital in conventional conveyor systems face switching costs from incompatible bearing housing standards and maintenance protocol retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Rollers Market |
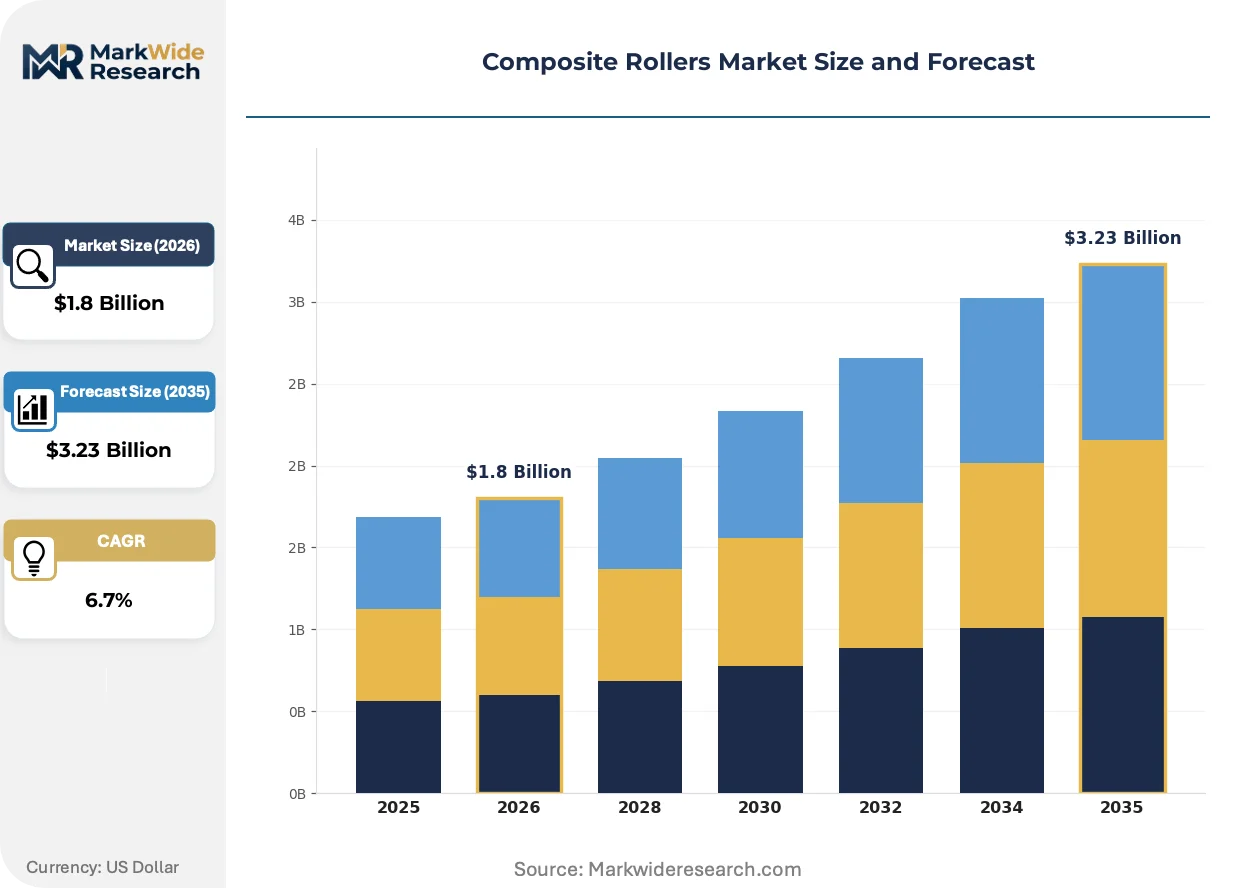
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Rollers, Hollow Rollers, Sleeve Rollers, Frame Rollers Material: Carbon Fiber, Glass Fiber, Polyester, Aramid Application: Industrial Equipment, Conveyor Systems, Aerospace, Marine End User: Manufacturing, Transportation, Construction, Packaging |
| Companies Covered | Lorbrand Composites, NEPEAN Conveyors, Pronexos, Double E Company LLC, Artur Küpper GmbH & Co. KG, Rulmeca Group, PROK, Amalga Composites Inc., Interroll Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Rollers Market Emerging Trajectories
Active substitution of metal alloys with engineered polymer composites is compressing product development cycles and enabling performance specifications previously unattainable with conventional materials. This materials transition is reshaping competitive positioning toward fiber-matrix engineering capabilities.
Carbon fiber pultrusion for cylindrical structural members is electrifying conveyor system design possibilities. Mining operators in Australia and South Africa are specifying solid pultruded rollers for heavy-load applications where deflection tolerance is critical. This manufacturing approach is electrifying specification authority shifts toward suppliers with captive fiber placement and resin infusion capabilities.
REACH substance restrictions governing European composite roller supply are tightening permissible resin formulations and fiber coatings. ECHA chemical registrations now determine which thermoset systems qualify for industrial component applications. German precision engineering clusters and automotive supplier networks are driving specification standards that propagate across EU procurement channels.
Buyer procurement models are compressing vendor qualification timelines while demanding integrated conveyor system engineering support. Mining conglomerates consolidating continental operations are reducing approved supplier lists from dozens to single-digit counts. Australian bulk-handling operators are most visibly demanding specification authority from vendors with backward integration into system design and project development.
Composite Rollers Market Segmentation
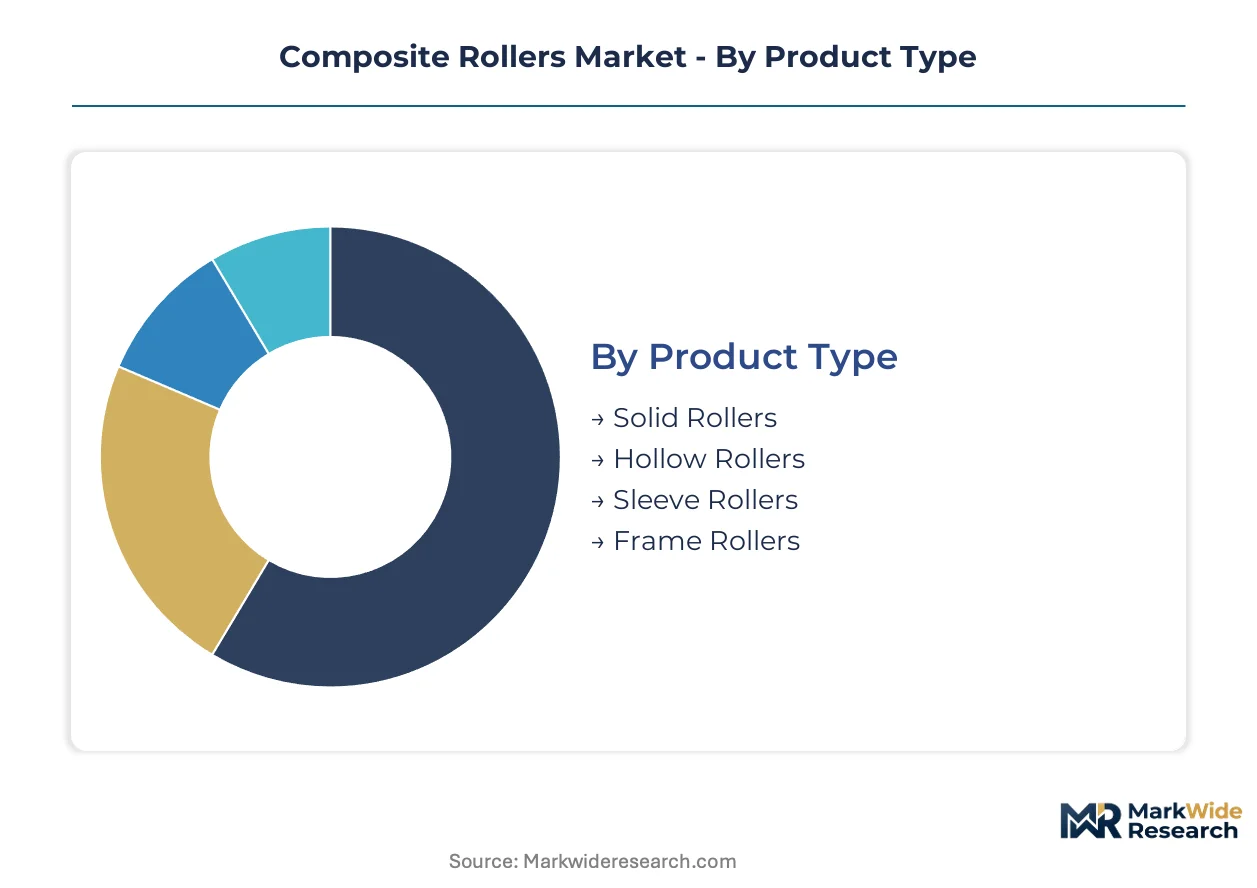
Composite roller segmentation reveals divergent engineering priorities across load-bearing versus mass-critical applications. Material selection and architecture choices directly determine supplier qualification pathways and procurement authority in mining, aerospace, and precision manufacturing channels.
Product Type:
Customization intensity spans from commodity solid designs to application-specific hollow architectures requiring fiber placement automation.
- Solid Rollers:Dense fiber-reinforced polymer cylinders engineered for deflection tolerance under extreme point loads. Mining operators in Australia and South Africa specify solid pultruded configurations for heavy-haul conveyor systems where structural rigidity outweighs mass considerations. Carbon fiber feedstock allocation from wind energy and aerospace sectors constrains supply scalability for premium grades.
- Hollow Rollers:Thin-walled cylindrical shells optimized for rotational inertia reduction in high-speed applications. Aerospace OEMs and precision printing equipment manufacturers in Germany drive specification standards for hollow architectures where energy savings compound across continuous operation cycles. Specialized mandrel winding and resin infusion capabilities concentrate supply among autoclave-equipped fabricators.
- Sleeve Rollers:Replaceable outer composite shells mounted on metallic cores, enabling localized wear component substitution without full roller replacement.
- Frame Rollers:Structural composite members integrating roller function with conveyor frame elements, reducing assembly complexity in modular bulk-handling systems.
Most installed capacity flows through Solid Rollers. Expansion is steepest in Hollow Rollers.
Material:
Cost-to-performance ratios stratify supply tiers from commodity glass formulations to aerospace-grade carbon systems.
- Carbon Fiber:High-modulus tow-reinforced thermoset matrices delivering fatigue resistance and stiffness-to-weight ratios exceeding steel alternatives. Marine installations in Nordic offshore environments and aerospace structural applications command premium positioning where corrosion elimination and mass reduction justify material expenditure. Aerospace and wind energy sector competition for limited tow capacity creates input cost volatility.
- Glass Fiber:E-glass or S-glass reinforced composites dominating cost-sensitive industrial equipment demand. Conveyor system OEMs in bulk material handling specify glass fiber grades where moderate mechanical properties suffice and procurement cost sensitivity prevails. REACH-compliant resin formulations from German chemical suppliers govern European supply eligibility.
- Polyester:Thermoset matrices offering processing economy and adequate environmental resistance for standard industrial duty cycles.
- Aramid:Aromatic polyamide fiber reinforcement capturing niche applications requiring impact absorption and ballistic resistance in specialized handling equipment.
Glass Fiber commands the greatest installed base. Carbon Fiber is climbing the fastest as EU F-Gas Regulation tightens material specifications.
Application:
End-use diversification stretches from standardized mining components to certificated aerospace structural elements.
- Conveyor Systems:Continuous bulk material transport infrastructure spanning mining, aggregate processing, and port logistics. Australian and South African mining conglomerates consolidating continental procurement operations drive specification authority toward backward-integrated suppliers with system engineering capabilities. Energy savings from hollow roller mass reduction are accelerating architecture transitions.
- Aerospace:Flight-critical structural and actuation components subject to FAA and EASA certification protocols. German precision engineering clusters supply tier-one OEMs with autoclave-cured cylindrical elements meeting stringent fatigue and environmental qualification standards.
- Industrial Equipment:General machinery rollers for manufacturing automation and material handling systems.
- Marine:Corrosion-resistant deck machinery and handling systems for offshore platforms and vessel operations.
Conveyor Systems absorb the majority of production volume. Aerospace is gaining share fastest on certification-driven supplier consolidation.
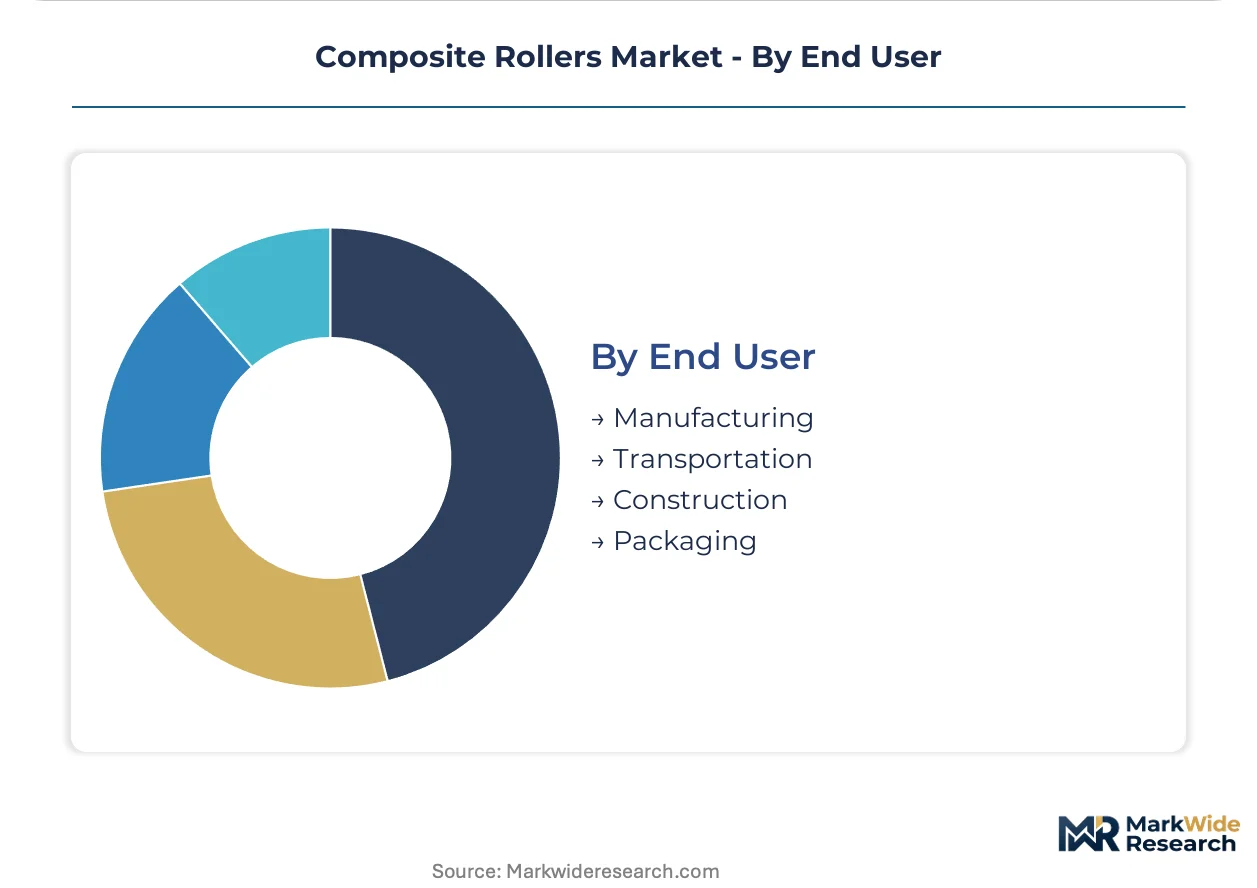
End User:
Procurement sophistication varies from project-based mining capital expenditure to recurring manufacturing equipment replacement cycles.
- Manufacturing:Automated production line and material handling system operators specifying rollers for continuous duty industrial environments. German automotive supplier networks propagate specification standards across EU procurement channels, demanding ISO 9001 quality management and REACH substance compliance documentation.
- Transportation:Logistics infrastructure and vehicle system integrators requiring lightweight, corrosion-resistant cylindrical components.
- Construction:Aggregate processing and mobile equipment OEMs sourcing rollers for harsh-environment material handling applications.
- Packaging:High-speed printing and converting equipment manufacturers demanding precision hollow roller architectures with tight runout tolerances.
Manufacturing represents the largest addressable demand base. Packaging is expanding most quickly as automation OEMs specify precision hollow configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision engineering authority while Australia drives bulk-handling specification standards through mining procurement consolidation. Regulatory divergence between EU chemical frameworks and Anglo-Pacific operational standards creates distinct qualification pathways for composite roller suppliers.
Germany
Automotive supplier networks and precision engineering clusters propagate REACH-compliant specification standards across EU procurement channels. The EU F-Gas Regulation and ECHA chemical registrations filter permissible resin formulations and fiber coatings for industrial component applications. Stuttgart and Munich manufacturing corridors anchor carbon fiber pultrusion capabilities serving aerospace OEMs and conveyor system integrators.
Australia
Mining conglomerates consolidating continental operations compress vendor counts while elevating technical specifications for corrosion-resistant roller systems. National emissions reduction frameworks and state-level mining safety regulations shape procurement documentation requirements. Perth and Brisbane engineering hubs concentrate backward-integrated suppliers with captive conveyor system design capabilities.
United States
OSHA machinery guarding standards and EPA industrial emissions frameworks determine conveyor system integration requirements in regulated manufacturing environments. Regional manufacturing tax incentives and infrastructure investment programs influence capital equipment procurement cycles. Midwest industrial corridors and Southeast automotive supplier networks drive specification authority for precision hollow roller applications.
South Africa
Bulk material handling operators in platinum and coal mining specify solid pultruded rollers for heavy-haul conveyor systems under extreme environmental loading. National mining charter requirements and local content regulations shape supplier qualification criteria. Johannesburg and Pretoria manufacturing bases serve African and Australian export markets with corrosion-resistant composite formulations.
Japan
METI industrial technology roadmaps and JIS standards govern fiber-reinforced polymer component specifications for precision manufacturing equipment. Carbon fiber tow allocation competition from domestic aerospace and wind energy sectors constrains input supply for premium roller grades. Nagoya and Osaka industrial clusters concentrate autoclave-equipped fabricators serving high-speed printing and converting equipment OEMs.
Composite Rollers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base stratifies between mining-focused system integrators with backward integration capabilities and precision engineering specialists serving aerospace and automation OEMs. Three archetypes dominate: continental-scale mining suppliers, regional precision fabricators, and application-specific hollow roller specialists. Competitive moves concentrate on specification authority capture through early project involvement and geographic expansion via licensing partnerships.
Among Germany-based fabricators, Artur Küpper GmbH & Co. KG occupies a position within the precision engineering tier exemplifying REACH-compliant supply chain integration. South African and Australian mining corridor specialists including Lorbrand Composites and NEPEAN Conveyors represent the bulk-handling system integrator archetype with backward integration into conveyor engineering. Netherlands-based Pronexos sits within the application-specific specialist tier serving high-speed printing and converting equipment manufacturers with hollow roller architectures.
| Leading Market Players |
|---|
| Lorbrand Composites |
| NEPEAN Conveyors |
| Pronexos |
| Double E Company LLC |
| Artur Küpper GmbH & Co. KG |
| Rulmeca Group |
| PROK |
| Amalga Composites Inc. |
| Interroll Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Japan anchor composite roller supply, translating captive autoclave assets into pricing discipline that resists commoditization pressure from glass fiber alternatives. Their ownership structure insulates capacity decisions from quarterly earnings pressure, sustaining premium positioning for REACH-compliant carbon fiber grades even as mining procurement consolidates.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity glass fiber rollers, compressing margins for European and North American fabricators lacking downstream integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and fiber modulus, with ISO 9001-autoclave-cured carbon systems commanding substantial premiums over pultruded glass alternatives. Cost compression in standard grades is intensifying because Chinese producers are scaling mandrel winding capacity for bulk conveyor applications. Mining conglomerates exhibit highest price sensitivity, while aerospace OEMs prioritize fatigue resistance over procurement cost.
Supply Chain Analysis
Regional distribution centers in Germany, Australia, and South Africa form hub-and-spoke patterns serving mining corridors with corrosion-resistant solid roller configurations. Manufacturing concentration in Germany, Japan, and China draws from carbon fiber tow, thermoset resin, and precision bearing inputs. Single-source vulnerability around Japanese and German autoclave equipment constrains supply scalability for hollow aerospace-grade production. Distribution runs through conveyor system OEMs and direct mining procurement channels, with specification authority increasingly captured by backward-integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite roller markets offer margin expansion through carbon fiber grade substitution and hollow architecture penetration, as energy savings from rotational mass reduction justify premium positioning in automated bulk handling.
For Market Incumbents: Extend specification authority through early project involvement in Australian and South African mining developments, capturing conveyor system engineering scope before procurement consolidation narrows vendor lists. Deepen captive fiber placement capabilities to defend against emerging Chinese pultrusion specialists. Prioritize REACH-compliant resin formulation investments as ECHA registrations filter out metal roller incumbents lacking polymer engineering competence. For New Entrants and Emerging Players: Hollow roller automation for high-speed printing and converting equipment represents the most penetrable white-space target, as incumbent mining-focused suppliers underinvest in precision runout tolerances. Target packaging OEMs in Germany and Japan with mandrel-winding expertise transferable from adjacent cylindrical composite applications. Pursue licensing partnerships with established autoclave operators to circumvent ISO 9001 certification timelines. For Investors and Strategic Acquirers: Mining conveyor system integrators are the most active acquirer in this space, seeking backward integration into roller manufacturing to capture specification authority and margin from component supply. Five-to-ten year viability hinges on circular economy compliance capabilities as thermoset recyclability mandates emerge. Monitor EU carbon border adjustment implementation as inflection indicator for competitive positioning against steel roller alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conveyor System Engineering | NEPEAN Conveyors demonstrates specification authority capture through captive project development capabilities. |
| Autoclave Capacity Expansion | German precision clusters serve aerospace OEMs with EASA-compliant hollow roller architectures. |
| REACH-Compliant Resin Formulation Investment | ECHA registration status determines European supply eligibility for industrial component applications. |
| Hollow Roller Architecture Development | Pronexos penetrates packaging automation through specialized mandrel winding for printing equipment. |
| Regional Licensing Partnerships | Lorbrand Composites leverages South African manufacturing to serve Australian mining procurement consolidation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with conveyor system procurement directors, composite fabrication plant managers, mining maintenance executives, and aerospace tier-one supplier quality leads with secondary validation from customs trade data, ECHA chemical registration databases, SEC filings of diversified industrial conglomerates, and ISO certification body records. Bottom-up volume builds across product type, material grade, and application segments were triangulated against top-down market sizing from regional production capacity assessments.
Historical reference periods anchored the forecast window to observed substitution rates from steel to composite rollers in Australian and South African mining installations. The analytical framework modeled segmentation across solid versus hollow architecture, carbon versus glass fiber reinforcement, conveyor system versus aerospace application, and regional regulatory compliance clusters. CAGRs were derived from elasticity-adjusted demand projections incorporating carbon fiber feedstock allocation competition and REACH substance restriction implementation timelines.
The model holds under stable EU F-Gas Regulation enforcement and continued mining procurement consolidation; deviation in carbon border adjustment implementation pace or thermoset recycling mandate acceleration would shift competitive positioning between composite and steel alternatives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Lightweight Materials Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Medical Composite Material Market
Composite Materials
Expandable Graphite Market
Composite Materials
United States Marine Composites Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
FRP Reactor Market
Composite Materials
Global Sports Composites Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Carbon Composites Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
LAMEA Composite Process Material Kits Market