
 Southeast Asia Adhesives and Sealants Market | 2026-2036
Southeast Asia Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Adhesives and Sealants Market Analytics
Electric vehicle assembly is restructuring adhesive procurement across Southeast Asia. H.B. Fuller Company leverages its reactive adhesive portfolio to secure thermal management bonding programs with emerging ASEAN EV platforms. Henkel AG & Co. KGaA sustains dominance in structural epoxy applications through localized compounding operations in Thailand. Sika AG anchors construction-grade polyurethane demand via contractor-direct distribution networks spanning Vietnam and the Philippines.
Adhesives and sealants comprise formulated polymer systems—typically ranging from 1,000 to 50,000 centipoise viscosity—engineered to create structural or environmental barriers between substrates through surface wetting, chemical curing, or physical setting mechanisms. Their primary industrial purpose centers on replacing mechanical fasteners with bonded joints that distribute stress uniformly across joined materials. Water-based acrylic formulations lead volume consumption in packaging applications across the region, while reactive polyurethane systems capture premium margin pools in automotive lightweighting programs. Hot melt technology dominates high-speed corrugated board lines, though solvent-based epoxies retain critical share in electronics potting where moisture resistance thresholds exceed 85 degrees Celsius continuous operation.
Thailand's Department of Industrial Works enforces volatile organic compound emission ceilings that compel reformulation away from solvent-based systems in Bangkok metropolitan manufacturing zones. Vietnam's Ministry of Natural Resources and Environment implements hazardous chemical inventory reporting that shapes import licensing for epoxy hardeners and isocyanate precursors. Indonesia's National Standardization Agency mandates SNI certification for construction sealants used in public infrastructure, creating compliance barriers for uncertified imports. Stakeholders must monitor diverging national chemical registries across ASEAN, where mutual recognition gaps between Thai, Vietnamese, and Indonesian conformity assessment procedures continue to fragment product registration strategies.
Market Dynamics
Electric vehicle battery pack assembly is restructuring procurement patterns across ASEAN manufacturing hubs, with thermal management bonding requirements displacing legacy mechanical fastening in module-to-pack architectures.
Growth Catalysts
- Thailand's Board of Investment incentives:Green chemistry tax holidays accelerate water-based adhesive substitution in Bangkok industrial coatings corridors. Formulators gain five-year corporate income tax exemptions for solvent-free production lines.
- Corrugated packaging automation:Indonesia's Java-based box plants anchor regional hot melt consumption as high-speed folder-gluer lines replace starch-based alternatives. Solvent-free EVA systems now dominate 300-meter-per-minute production environments.
- Reactive polyurethane chemistry:Automotive lightweighting programs in Vietnam drive two-component structural bonding for mixed-material body-in-white assemblies. These systems enable aluminum-to-steel joining without galvanic corrosion pathways.
Market Restraints
- Petrochemical feedstock volatility:Polyether polyol and MDI pricing swings compress margin stability for polyurethane formulators serving construction sealant markets. Thai producers face working capital strain from 90-day raw material inventory cycles.
- Import dependency for epoxy hardeners:Vietnam's Ministry of Natural Resources and Environment hazardous chemical inventory reporting creates licensing friction for cycloaliphatic amine precursors. Domestic blending capacity remains underdeveloped.
- Moisture-cure silicone limitations:Tropical humidity accelerates skin-over in construction-grade sealants, restricting open time for Philippine contractors applying facade glazing compounds.
Strategic Opportunities
- Cambodia and Myanmar infrastructure buildout:Greenfield construction in Phnom Penh and Yangon creates first-mover positioning for construction-grade polyurethane distributors. These markets lack established local formulator networks.
- Indonesia's National Standardization Agency SNI mandate:Public infrastructure sealant certification requirements erect compliance barriers for uncertified imports. Accredited domestic production facilities capture captive public sector demand.
- UV-curable acrylic convergence with digital printing:Narrow-web label presses in Malaysia integrate inline adhesive curing for variable-data packaging. This hybrid technology enables short-run flexibility without solvent emissions.
Industry Challenges
- Formulation chemist scarcity:Reactive adhesive compounding expertise concentrates in Thailand's Eastern Economic Corridor, leaving Vietnamese and Indonesian facilities dependent on expatriate technical staffing.
- Dual-registration burden:Divergent Thai, Vietnamese, and Indonesian chemical registries fragment product approval strategies. Mutual recognition gaps force redundant toxicological dossier submissions.
- Legacy starch adhesive displacement:Corrugated plants in rural Indonesia face capital constraints retrofitting hot melt tank and hose systems. Workforce retraining for 180-degree application temperatures extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Adhesives and Sealants Market |
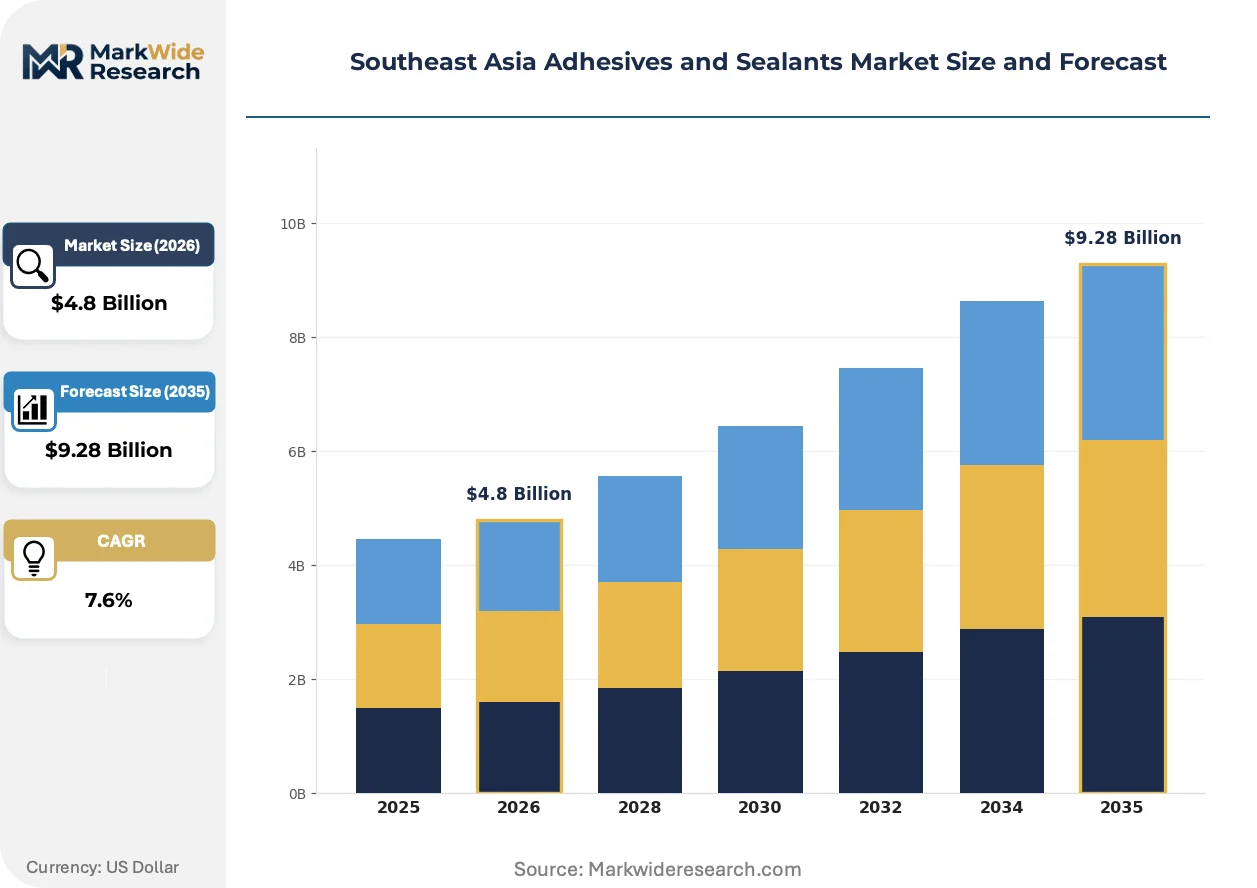
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic Application: Construction, Automotive, Packaging, Electronics End User: Manufacturers, Contractors, Distributors, Retailers Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | H.B. Fuller Company, Dow, Henkel AG & Co. KGaA, Pidilite Industries, BASF SE, Sika AG, 3M, Toagosei Group, Arkema, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Adhesives and Sealants Market Evolving Landscape
Bio-based feedstock integration and curing chemistry advances are compressing performance gaps between sustainable and conventional systems across Southeast Asian manufacturing.
UV-LED curable pressure-sensitive adhesives are rewriting bonding economics for electronics assembly in Malaysian Penang and Johor Bahru clusters. Smartphone and wearable manufacturers adopt these systems for zero-VOC, instant-cure display lamination. The technology is compressing work-in-process inventory from hours to seconds while eliminating thermal damage to OLED substrates.
Thailand's Department of Industrial Works volatile organic compound emission ceilings compel reformulation across Bangkok metropolitan manufacturing zones. Solvent-based epoxy and chloroprene systems face phased capacity restrictions from 2025. Packaging converters respond with water-based acrylic migrations and hot melt line conversions, though high-humidity performance gaps persist in unconditioned warehouse applications.
Direct procurement from adhesive formulators is displacing distributor intermediaries in Vietnam's automotive tier-one supply base. Battery module assemblers in Vinh Phuc and Thai Nguyen provinces negotiate annual volume contracts for thermal interface materials. This channel compression transfers technical service burden to formulator field engineers while capturing 8-12 point margin compression previously absorbed by trading houses.
Southeast Asia Adhesives and Sealants Market Segmentation
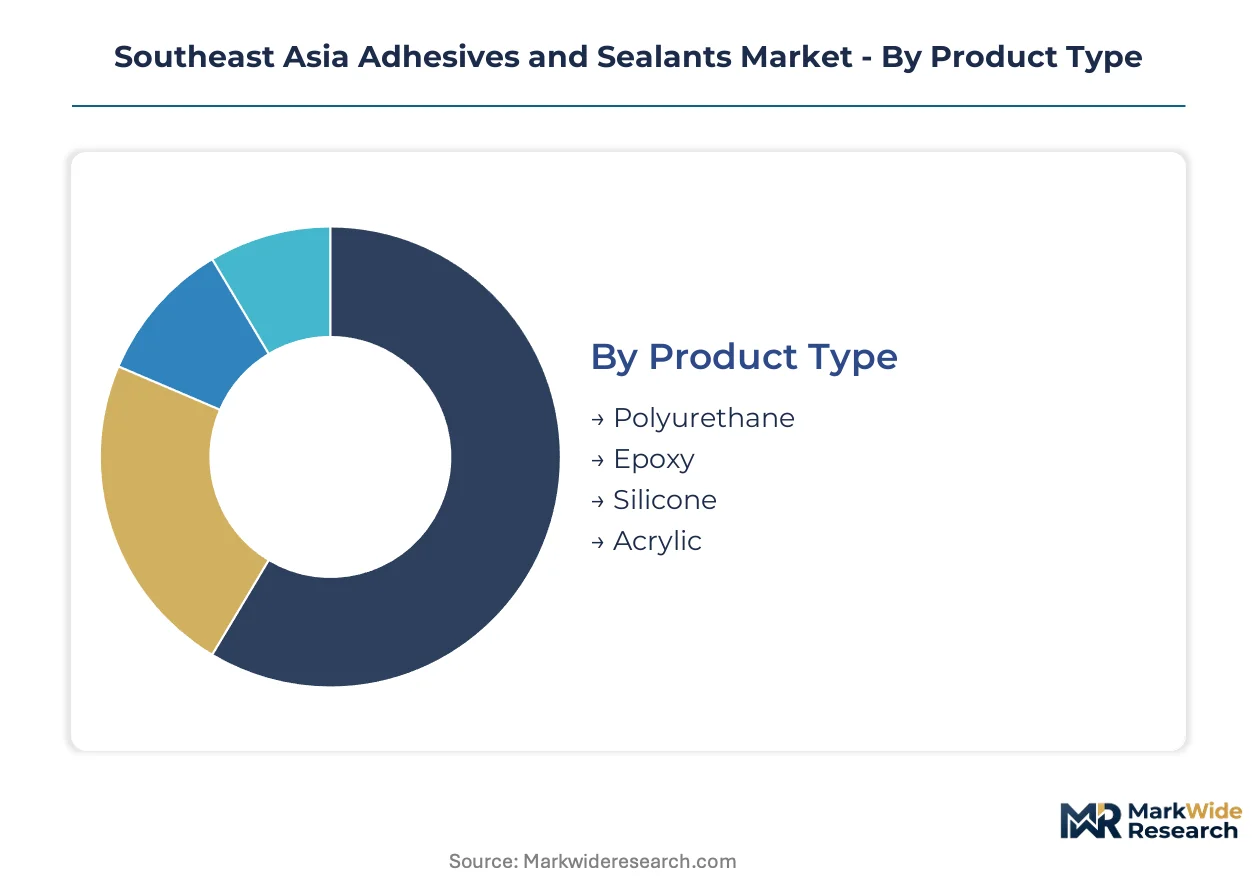
Segmentation in Southeast Asian adhesives and sealants reveals divergent capital requirements and margin profiles across chemistry platforms. Procurement patterns in automotive and construction verticals favor localized compounding capacity, while packaging and electronics segments reward formulation flexibility over fixed asset intensity.
Product Type:
Capital intensity varies sharply across chemistry platforms, with reactive systems demanding specialized reactor infrastructure and continuous process controls.
- Polyurethane:Two-component systems combine polyols with isocyanate hardeners to form thermoset bonds with exceptional toughness and chemical resistance. Thai automotive manufacturers in the Eastern Economic Corridor anchor regional demand for structural polyurethane in mixed-material vehicle assemblies, though MDI feedstock volatility strains working capital cycles.
- Epoxy:These thermosetting polymers cure through amine or anhydride crosslinking to deliver dielectric strength exceeding 15 kV/mm and adhesion to metal substrates. Electronics potting applications in Malaysian Penang clusters drive specification-grade consumption, where moisture resistance thresholds above 85 degrees Celsius continuous operation command premium positioning.
- Silicone:Moisture-cure alkoxy systems dominate construction glazing and weatherseal applications across tropical ASEAN markets. Indonesian high-rise developments in Jakarta and Surabaya absorb volume for facade engineering, though humidity-accelerated skin-over limits open time for field contractors.
- Acrylic:Water-borne emulsion polymers serve high-volume packaging and pressure-sensitive adhesive applications with lower capital barriers to entry. Vietnam's corrugated box sector is migrating from starch-based alternatives, compressing margins for commodity-grade suppliers.
Most installed capacity flows through Polyurethane. Expansion is steepest in Acrylic.
Application:
End-use concentration determines technical service intensity and distributor engagement models across the region.
- Construction:Structural glazing, waterproofing membranes, and tile fixing systems require on-site application support and contractor certification programs. Philippine infrastructure buildout in Metro Manila and Cebu City absorbs construction-grade polyurethane and silicone volumes, with Sika and local distributors maintaining direct contractor relationships.
- Automotive:Battery module assembly, body-in-white structural bonding, and interior trim attachment demand reactive adhesive expertise with thermal management specifications. Thailand's EV platform localization is restructuring procurement toward direct formulator contracts, bypassing traditional trading house intermediaries.
- Packaging:Corrugated board lamination and flexible film converting reward high-speed application systems and rapid set speeds. Indonesia's Java-based packaging corridor anchors regional hot melt consumption, where 300-meter-per-minute folder-gluer lines have displaced starch-based alternatives.
- Electronics:Display lamination, semiconductor encapsulation, and wearable device assembly require ultra-low outgassing and precision dispensing compatibility. Malaysian Penang and Johor Bahru electronics clusters are adopting UV-LED curable pressure-sensitive systems for zero-VOC, instant-cure bonding of OLED substrates.
Construction commands the largest share of technical service resources. Electronics is gaining share fastest.
End User:
Channel structure fragments across customer types, with direct procurement compressing distributor margins in automotive verticals.
- Manufacturers:Tier-one automotive suppliers and electronics OEMs negotiate annual volume contracts with technical service riders, transferring formulation support burden to formulator field engineers. Vietnamese battery module assemblers in Vinh Phuc and Thai Nguyen provinces exemplify this channel compression.
- Contractors:Construction applicators require on-site training, certification, and just-in-time delivery logistics. Philippine facade glazing contractors depend on distributor-managed inventory for moisture-cure silicone compounds.
- Distributors:Trading houses retain relevance in fragmented construction and maintenance markets where SKU breadth outweighs technical depth. Rural Indonesian corrugated plants source hot melt systems through regional distributors with credit extension capabilities.
- Retailers:Consumer-grade DIY adhesives and sealants flow through hardware chains and e-commerce platforms, with limited technical differentiation beyond brand recognition and price positioning.
Manufacturers absorb the highest proportion of direct sales investment. Distributors face margin compression in automotive accounts.
Technology:
Regulatory pressure and application speed requirements are restructuring technology mix across ASEAN manufacturing.
- Water-Based:Acrylic and polyurethane dispersions eliminate volatile organic compound emissions while retaining bond strength for porous substrates. Thailand's Department of Industrial Works emission ceilings are accelerating conversion from solvent systems in Bangkok metropolitan zones, though high-humidity performance gaps persist in unconditioned warehouse applications.
- Solvent-Based:Epoxy and chloroprene systems retain critical share in electronics potting and specialty rubber bonding where moisture resistance and chemical inertness exceed water-borne capabilities. Phased capacity restrictions from Thai regulators are forcing reformulation investments.
- Hot Melt:Ethylene-vinyl acetate and metallocene polyolefin systems dominate high-speed packaging lines with instant green strength and no cure time. Indonesia's corrugated automation wave has made hot melt the default technology for 300-meter-per-minute production environments.
- Reactive:Two-component polyurethane and epoxy systems enable structural bonding of dissimilar materials with load-bearing performance. Automotive lightweighting programs in Vietnam and Thailand are driving specification-grade consumption for aluminum-to-steel joining without galvanic corrosion pathways.
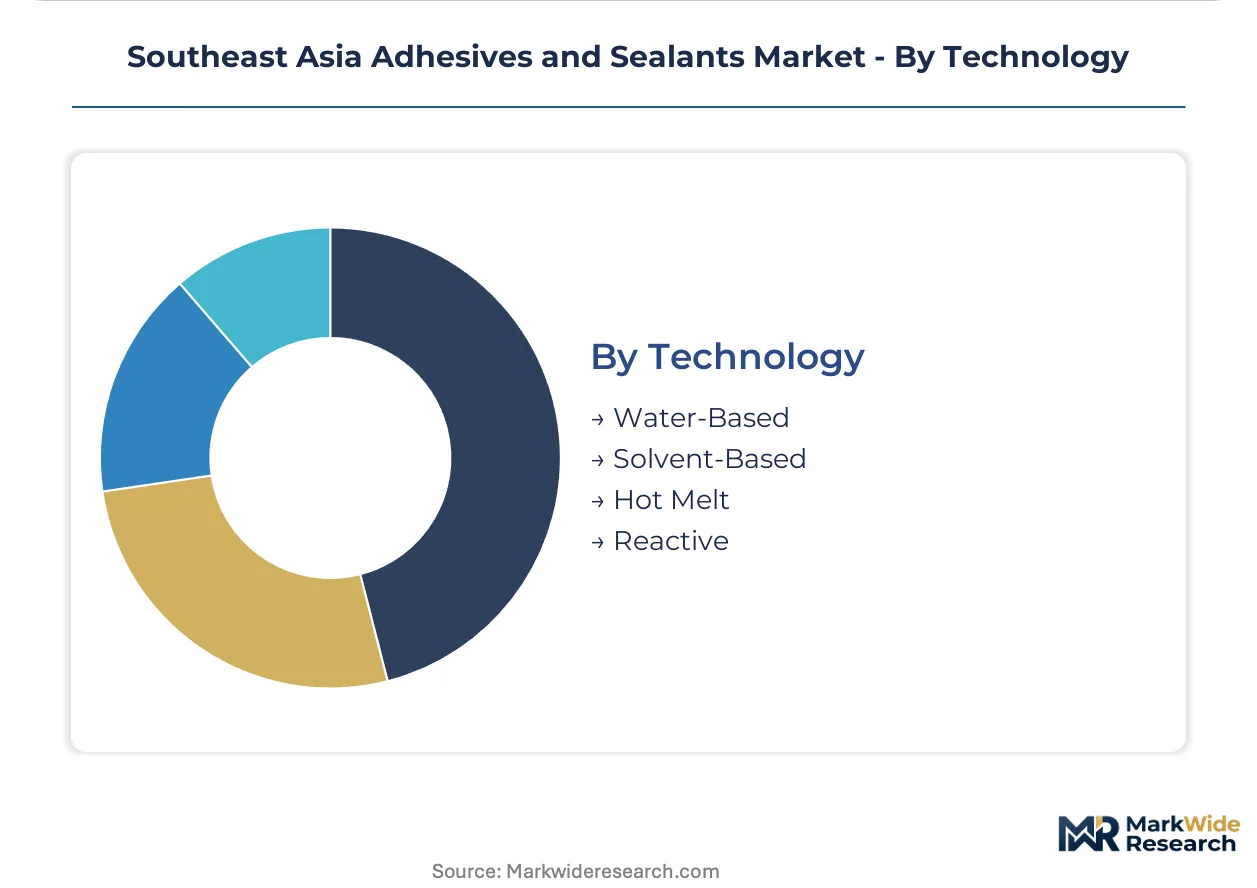
Hot Melt represents the largest installed base. Reactive systems are climbing the fastest on automotive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within ASEAN follows divergent chemical compliance costs. Thailand's green chemistry incentives attract formulators seeking relief from Indonesian SNI certification burdens and Vietnamese import licensing friction. This regulatory arbitrage concentrates water-based adhesive capacity in Bangkok's industrial corridors while leaving construction-grade markets fragmented across national boundaries.
Thailand
Thailand's Eastern Economic Corridor anchors regional polyurethane compounding for automotive structural bonding. The Board of Investment grants five-year corporate income tax exemptions for solvent-free production lines. Bangkok metropolitan manufacturers accelerate water-based acrylic migration to satisfy Department of Industrial Works VOC emission ceilings.
Indonesia
Indonesia's Java-based packaging corridor dominates regional hot melt consumption for corrugated automation. The National Standardization Agency mandates SNI certification for construction sealants in public infrastructure. Surabaya and Jakarta high-rise developments absorb moisture-cure silicone volumes despite humidity-accelerated skin-over limitations for field contractors.
Vietnam
Vietnam's automotive lightweighting programs in Vinh Phuc and Thai Nguyen provinces drive two-component structural polyurethane demand. The Ministry of Natural Resources and Environment enforces hazardous chemical inventory reporting that creates licensing friction for epoxy hardener imports. Battery module assemblers negotiate direct annual volume contracts with formulators, bypassing traditional distributor channels.
Malaysia
Malaysia's Penang and Johor Bahru electronics clusters adopt UV-LED curable pressure-sensitive adhesives for display lamination. Narrow-web label presses integrate inline adhesive curing for variable-data packaging applications. This hybrid technology eliminates thermal damage to OLED substrates while compressing work-in-process inventory cycles.
Philippines
Philippine infrastructure buildout in Metro Manila and Cebu City absorbs construction-grade polyurethane and silicone volumes. Facade glazing contractors depend on distributor-managed inventory for moisture-cure compounds. Sika and local distributors maintain direct contractor relationships with on-site application support and certification programs.
Southeast Asia Adhesives and Sealants Market Competitive Landscape
Capacity expansion dominates the current landscape as multinational formulators localize compounding operations to satisfy automotive direct-procurement requirements. The market exhibits tiered concentration: global chemical conglomerates control specification-grade reactive systems, regional specialists capture construction distribution channels, and commodity packaging suppliers compete on hot melt formulation flexibility. Three archetypes define competitive positioning: technology licensors with patented curing chemistry, integrated resin producers with captive polyol supply, and application-equipment bundlers with dispensing system lock-in. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players adding water-based lines to offset solvent-based capacity restrictions.
Among the global diversified chemical groups, Henkel AG & Co. KGaA, BASF SE, and Dow exemplify the integrated-resin-producer archetype with backward control over key petrochemical feedstocks. H.B. Fuller Company and Sika AG occupy positions as application-technology specialists, with the former representing the reactive adhesive formulator model and the latter anchoring construction-grade distribution networks. 3M exemplifies the technology-licensor tier with materials science IP spanning pressure-sensitive and structural platforms. Regional specialists including Pidilite Industries and Toagosei Group represent the Asia-Pacific formulation-focused competitors with localized product registration expertise.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Dow |
| Henkel AG & Co. KGaA |
| Pidilite Industries |
| BASF SE |
| Sika AG |
| 3M |
| Toagosei Group |
| Arkema |
| Others |
Value Network & Pricing Analysis
Reactive adhesive compounding expertise concentrates in Thailand's Eastern Economic Corridor, creating labor-cost differentials that widen pricing-tier spreads between specification-grade reactive systems and commodity packaging adhesives. Formulators in Bangkok metropolitan zones absorb premium technical staffing costs, while Indonesian hot melt suppliers compete on leaner operational structures.
Pricing Analysis
Distributor margins in construction-grade sealants compress as automotive OEMs negotiate direct annual volume contracts with reactive adhesive formulators. Three-tier pricing structure across specification-grade, industrial-standard, and commodity-economy levels separates SNI-certified infrastructure sealants from uncertified imports and basic hot melt formulations. Cost compression in commodity EVA hot melts intensifies because Indonesian corrugated automation drives volume concentration among price-sensitive packaging converters. Tier-one automotive battery assemblers exhibit lowest price sensitivity due to thermal management performance requirements, while rural Indonesian box plants prioritize per-kilogram procurement economics above technical service.
Supply Chain Analysis
Returns and off-specification adhesive flows from Vietnamese automotive tier-one suppliers feed into lower-grade construction applications through informal secondary channels. Geographic supply concentration centers on Thailand for polyurethane compounding, Indonesia for hot melt formulation, and Malaysia for electronics-grade UV-curable systems. Raw material dependencies draw from Saudi Arabian MDI feedstocks, Singaporean polyether polyol trading hubs, and Korean epoxy resin precursors. Single-source vulnerability in cycloaliphatic amine hardeners creates licensing friction under Vietnam's hazardous chemical inventory reporting. Distribution runs through contractor-direct networks for construction sealants and formulator-direct contracts for automotive reactive systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia's adhesives and sealants market functions as a stable compounder anchored by irreversible automotive lightweighting and EV battery assembly trends that sustain structural demand regardless of cyclical packaging fluctuations.
For Market Incumbents: Cement dominance in Thailand's Eastern Economic Corridor by expanding localized polyurethane compounding capacity ahead of Board of Investment incentive windows closing. Secure backward integration into polyol supply through long-term offtake agreements with Singaporean petrochemical traders to defend against MDI price volatility eroding margin stability in construction sealant portfolios.
For New Entrants and Emerging Players: UV-LED curable pressure-sensitive adhesive technology offers a technology-first wedge into Malaysian electronics clusters where display lamination specifications outpace incumbent formulation capabilities. Target Cambodia and Myanmar infrastructure buildout as white-space geographies lacking established local formulator networks, entering through construction-grade polyurethane distribution partnerships with regional trading houses.
For Investors and Strategic Acquirers: Integrated resin producers with captive polyol supply are the most active acquirer in this space, consolidating regional specialists to secure SNI certification capabilities for Indonesian public infrastructure capture. Acquisition target archetype: Vietnamese reactive adhesive compounders with established Vinh Phuc automotive relationships and underdeveloped domestic hardener blending capacity. Monitor Thailand's Department of Industrial Works VOC enforcement intensity as early signal for water-based formulation capacity valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Captive MDI and polyether polyol sourcing insulates Thai formulators from petrochemical feedstock volatility compressing construction sealant margins. |
| SNI Certification Investment | Accredited domestic production facilities capture captive Indonesian public infrastructure demand blocked from uncertified import competitors. |
| UV-LED Curable Capacity Addition | Zero-VOC instant-cure systems penetrate Malaysian Penang electronics clusters requiring OLED substrate thermal damage avoidance. |
| Direct Procurement Channel Expansion | Annual volume contracts with Vietnamese battery module assemblers capture margin previously absorbed by trading house intermediaries. |
| Green Chemistry Production Line Conversion | Solvent-free water-based acrylic capacity satisfies Bangkok metropolitan Department of Industrial Works emission ceilings ahead of phased restrictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulator technical directors, automotive tier-one procurement leads, corrugated plant operations managers, and construction distributor inventory planners with secondary validation through Thai customs trade data, Indonesian SNI certification registries, ACC regional chemical reports, and ASEAN automotive production databases. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
Segment-weighting across chemistry platforms, application verticals, and national regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions included reactive versus commodity technology tiers, automotive versus packaging end-use concentration, and certified versus uncertified product grades. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery assembly penetration rates and corrugated automation adoption curves.
The model holds under stable ASEAN automotive localization and Indonesian packaging investment trajectories; deviation in Thai VOC enforcement intensity or Vietnamese import licensing friction would shift capacity migration patterns and pricing-tier spreads. Practitioners should monitor Board of Investment incentive renewal schedules and SNI certification backlog queues for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Wood Glue Market