
 North America Reactive Adhesives Market | 2026-2036
North America Reactive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Reactive Adhesives Market Analytics
Market Context
Buyer concentration among automotive OEMs and tier-1 suppliers is recalibrating procurement volumes across the value chain. Henkel AG & Co. KGaA leverages its polyurethane expertise to anchor supply relationships with Detroit-area manufacturers. 3M competes through tape-adhesive hybrid platforms that extend its reach beyond conventional dispensing systems. Dow dominates silane-modified chemistry for structural glazing applications in commercial construction.
Technical Definition and Segment Structure
Reactive adhesives cure through chemical polymerization rather than solvent evaporation, achieving bond strengths exceeding 20 MPa in epoxy systems and enabling load-bearing joints between dissimilar substrates. Epoxy formulations sustain the largest revenue pool due to established aerospace certification protocols, while UV-cured acrylics represent the fastest-expanding technology segment driven by electronics miniaturization in Mexico's contract manufacturing zones. Moisture-cured polyurethanes occupy mature positions in construction sealing where application simplicity outweighs speed requirements.
Regulatory Frame and Outlook
EPA VOC limits under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulations, while OSHA Permissible Exposure Limits shape workplace handling protocols for isocyanate-containing products. Health Canada's PMRA evaluates adhesive imports under the Pest Control Products Act for antimicrobial claims, creating dual-compliance obligations for cross-border suppliers. Stakeholders must monitor evolving state-level green building codes in California and New York that specify low-emitting material thresholds for public projects.
Market Dynamics
Automotive OEMs in the Great Lakes corridor are displacing mechanical fasteners with structural bonding systems to achieve lightweighting targets, compressing procurement cycles and forcing adhesive suppliers to co-locate technical service teams near assembly plants.
Growth Catalysts
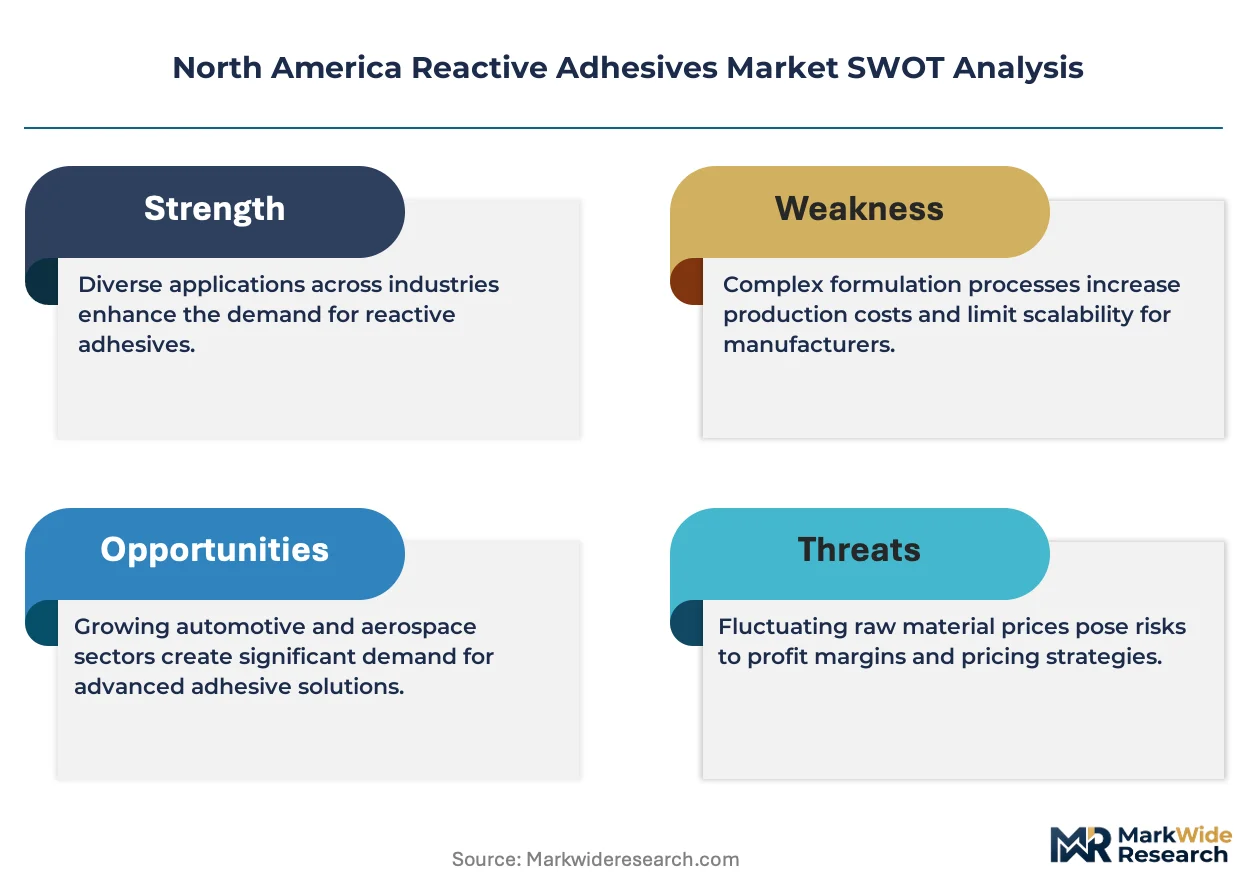
- EPA VOC limits under NESHAP:Solvent-based adhesive formulations face phase-out timelines across U.S. manufacturing facilities, redirecting specification decisions toward reactive chemistries that eliminate emission control equipment requirements.
- Lightweight vehicle assemblies:Multi-material bonding between aluminum body panels and carbon fiber reinforced plastics in electric vehicle platforms creates specification pull for high-strength structural adhesives.
- Mexico's electronics contract manufacturing zones:UV-cured acrylic demand accelerates for miniaturized component assembly, with Guadalajara and Tijuana clusters expanding cleanroom bonding capacity.
Market Restraints
- Isocyanate feedstock volatility:MDI and TDI pricing swings tied to crude oil and benzene markets compress polyurethane adhesive margins and destabilize annual contract negotiations.
- Great Lakes supplier concentration:Technical service capabilities for automotive qualification programs cluster in southeast Michigan, creating geographic dependency risk for tier-1 suppliers.
- Cure time limitations:Epoxy systems requiring elevated temperature cycles constrain high-volume assembly line integration compared to mechanical fastening alternatives.
Strategic Opportunities
- Canadian green building codes:Toronto and Vancouver municipal procurement mandates for low-emitting materials in public infrastructure projects create specification entry points for moisture-cured polyurethane sealants.
- Wind blade manufacturing in Texas and Iowa:Structural bonding of composite laminates for utility-scale turbines represents an underpenetrated end-use vertical with qualification timelines shorter than aerospace certification.
- Hybrid UV-thermal cure systems:Convergence of instant handling strength with post-cure thermal properties enables automation in automotive electronics assembly previously blocked by speed-durability tradeoffs.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silane-modified polymer synthesis concentrates among retiring technical staff at legacy suppliers, constraining new product development timelines.
- Automotive qualification protocols:OEM-specific crashworthiness and durability testing cycles extend 18-36 months, freezing supplier switching decisions regardless of performance advantages.
- Cross-border compliance complexity:Dual obligations under OSHA PELs and Health Canada PMRA antimicrobial claim evaluations fragment formulation strategies for integrated North American supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Reactive Adhesives Market |
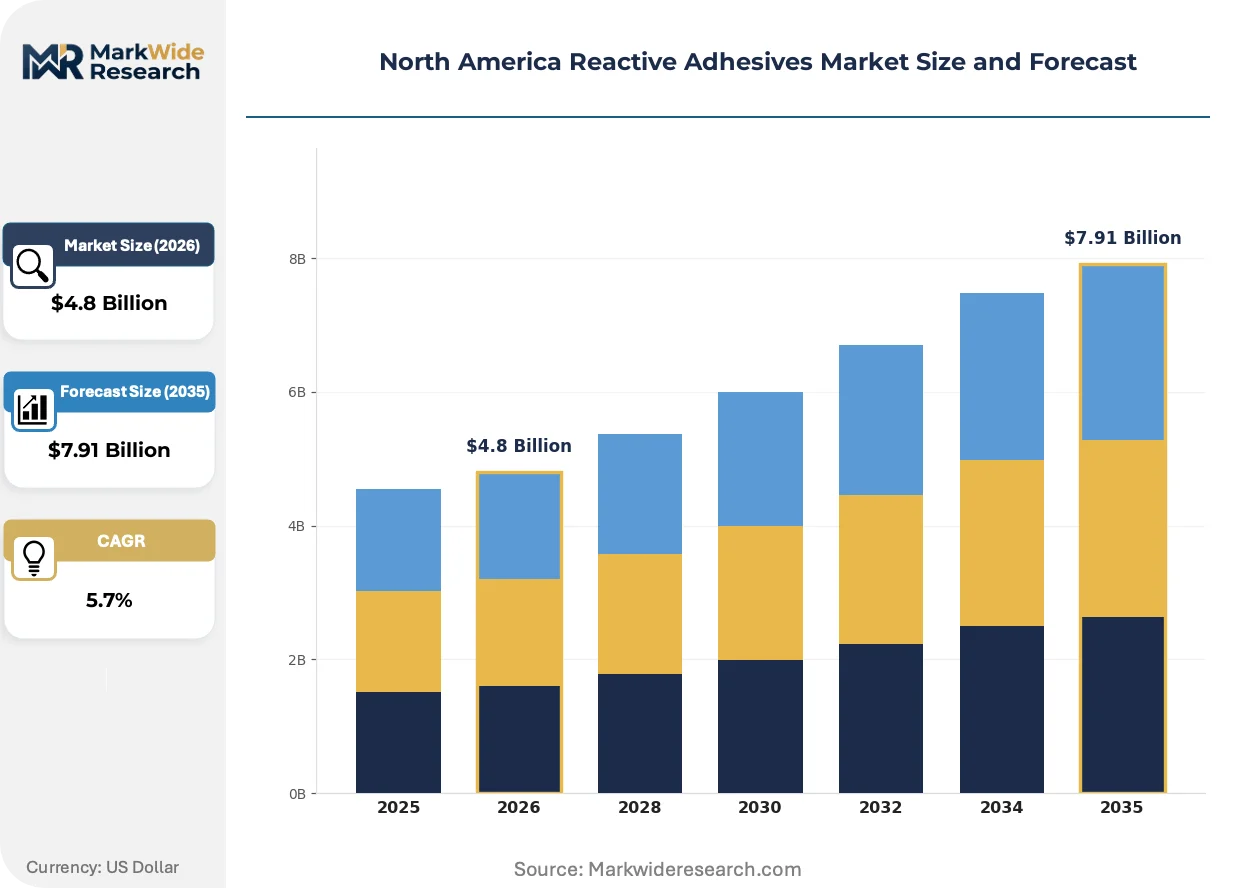
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silane-Modified, Acrylic End User: Automotive, Construction, Electrical, Packaging Technology: Moisture-Cured, Heat-Cured, UV-Cured, Solvent-Based Application: Coating, Bonding, Sealing, Insulation |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, H.B. Fuller Company, Dow, Avery Dennison Corporation, Dymax Corporation, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Reactive Adhesives Market Evolving Landscape
Reactive adhesive development is pivoting from incremental cure-speed improvements toward substrate-agnostic bonding platforms that collapse the distinction between structural and non-structural applications across automotive and electronics assembly.
Silane-terminated polyether technology is converging with conventional polyurethane backbone structures to produce hybrid systems that bond untreated polyolefins without plasma or flame surface preparation. Tier-1 automotive suppliers in Ohio and Ontario are piloting these platforms for interior trim assembly, eliminating capital-intensive pretreatment stations. The convergence is compressing equipment supplier margins while expanding addressable substrate combinations for adhesive formulators.
OSHA's updated Permissible Exposure Limits for isocyanates are forcing workplace engineering controls and respiratory protection upgrades across U.S. adhesive manufacturing and application facilities. The industrial consequence is accelerated investment in closed-loop dispensing systems and low-monomer content formulations. Construction segment buyers in California and New York are responding by specifying isocyanate-free alternatives for public project bids, even at performance tradeoffs.
Specification authority is migrating from plant-level purchasing to centralized automotive OEM material engineering teams, collapsing the number of decision-makers in high-volume procurement. Regional distributors in the Great Lakes corridor are being displaced by direct mill-to-plant logistics contracts with embedded technical service. The shift is most visible in Michigan, where tier-1 seating and interior suppliers have consolidated adhesive sourcing to single-source framework agreements with biannual price reviews.
North America Reactive Adhesives Market Segmentation
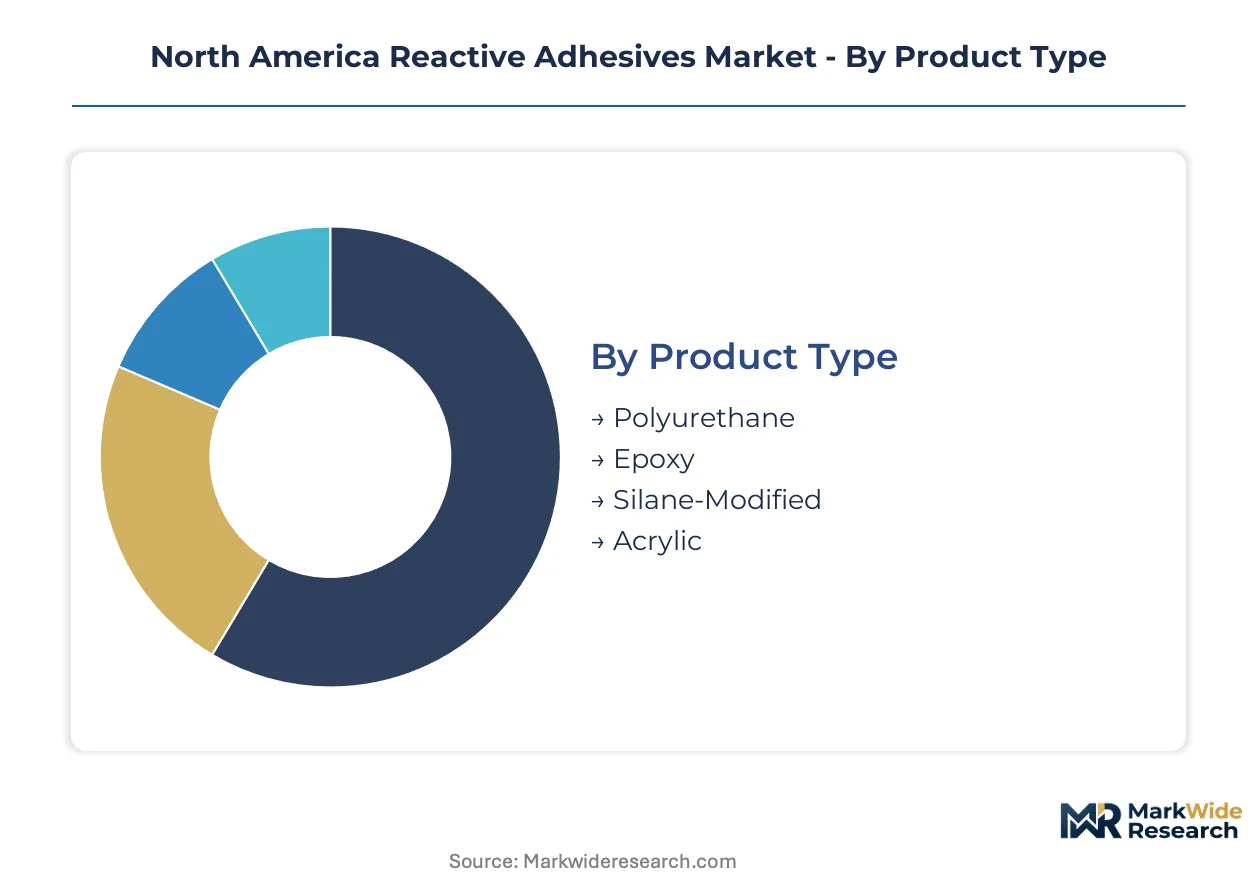
Reactive adhesive procurement in North America follows distinct technical and commercial logics that fragment supplier capabilities across chemistry types, cure mechanisms, and end-use qualification requirements. Understanding these segment boundaries reveals where formulation expertise concentrates and where specification authority migrates.
Product Type:
Epoxy and polyurethane formulations anchor standalone structural applications, while silane-modified and acrylic systems increasingly embed within multi-material assembly platforms.
- Epoxy:Two-part thermosetting systems achieve bond strengths exceeding 20 MPa and dominate aerospace certification protocols. Demand concentrates in Great Lakes automotive structural bonding as OEMs displace mechanical fasteners for aluminum-to-composite joints.
- Polyurethane:Moisture-cured and two-part formulations offer flexibility across temperature cycles and vibration loading. Construction sealing in Toronto and Vancouver municipal infrastructure drives specification pull for low-VOC variants meeting green building procurement mandates.
- Silane-Modified:Hybrid backbone structures bond untreated polyolefins without surface pretreatment. Tier-1 automotive suppliers in Ohio pilot these platforms for interior trim assembly.
- Acrylic:UV-cured and anaerobic variants serve electronics miniaturization in Guadalajara and Tijuana contract manufacturing clusters.
Epoxy leads volumes today; acrylic is gaining share fastest.
End User:
Automotive and construction buyers operate on divergent procurement timelines, with electrical and packaging segments demanding speed-to-cure over structural durability.
- Automotive:OEM qualification protocols extend 18-36 months for crashworthiness validation. Great Lakes corridor manufacturers specify structural adhesives for electric vehicle multi-material platforms.
- Construction:Application simplicity and weathering resistance outweigh cure speed. California and New York public project bids increasingly mandate isocyanate-free alternatives.
- Electrical:Miniaturized component assembly in Mexico's cleanroom facilities demands instant handling strength from UV-cured systems.
- Packaging:High-speed line integration favors reactive hot-melts with rapid green strength development for food and beverage carton sealing.
Construction commands the broadest SKU proliferation; automotive drives the highest per-unit specification value.
Technology:
Cure mechanism selection determines capital equipment requirements and workplace exposure controls across manufacturing environments.
- Moisture-Cured:Single-component systems eliminate metering equipment and suit field application where environmental control is limited. Construction sealants in the Great Lakes corridor rely on this simplicity.
- Heat-Cured:Elevated temperature cycles deliver full structural properties but constrain high-volume assembly line integration. Epoxy systems dominate this tradeoff in aerospace and wind blade manufacturing.
- UV-Cured:Instant polymerization enables automation in electronics assembly previously blocked by speed-durability tradeoffs. Guadalajara contract manufacturers expand cleanroom bonding capacity.
- Solvent-Based:EPA NESHAP phase-out timelines redirect specification decisions toward reactive chemistries that eliminate emission control equipment requirements.
Moisture-cured systems retain the largest installed base; UV-cured platforms show the steepest expansion trajectory.
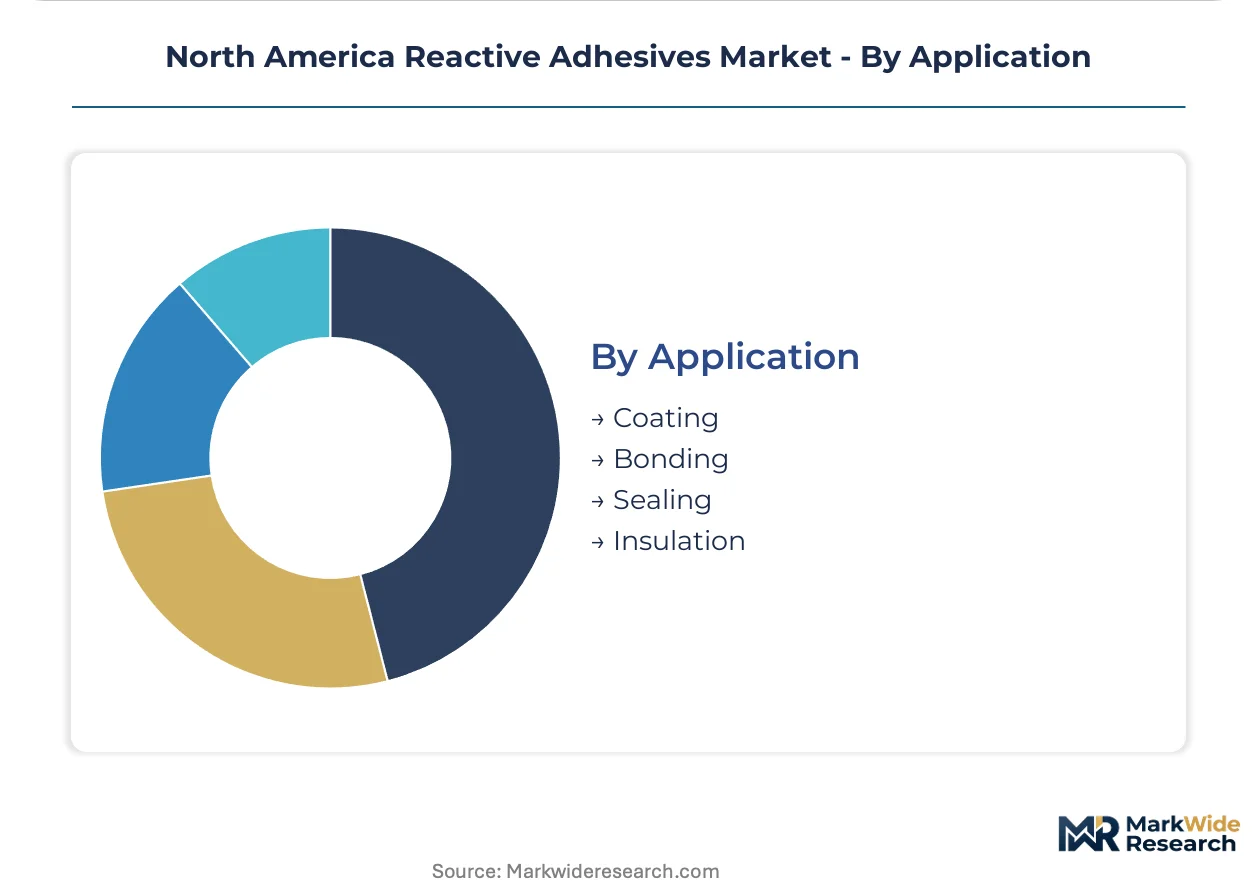
Application:
Functional role in the assembly stack determines performance specifications and pricing tolerance across end-use verticals.
- Bonding:Structural load-bearing applications between dissimilar substrates command premium formulation development. Automotive OEMs in Michigan and Ohio consolidate sourcing to single-source framework agreements.
- Sealing:Environmental barrier functions prioritize elongation and weathering over tensile strength. Canadian municipal procurement mandates for low-emitting materials create specification entry points.
- Coating:Protective and decorative films require controlled viscosity and sag resistance. Industrial equipment manufacturers in Texas specify chemical-resistant epoxy coatings.
- Insulation:Thermal and electrical barrier applications in automotive electronics assembly favor thin-film dispersions with dielectric stability.
Bonding captures the highest value per kilogram; sealing generates the most consistent recurring volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States automotive OEMs command the largest procurement volumes, while Mexican electronics manufacturers drive the fastest technology adoption curves. Canada anchors construction-grade demand through green building procurement mandates. Each national market operates under distinct regulatory frameworks that shape formulation requirements and supplier qualification protocols.
United States
EPA NESHAP VOC limits under Section 112 are phasing out solvent-based formulations across Michigan and Ohio manufacturing facilities. OSHA updated Permissible Exposure Limits for isocyanates in 2024, forcing respiratory protection upgrades at adhesive application plants. Detroit-area tier-1 suppliers consolidate sourcing to single-source framework agreements with biannual price reviews.
Canada
Toronto and Vancouver municipal procurement mandates for low-emitting materials create specification entry points for moisture-cured polyurethane sealants. Health Canada's PMRA evaluates antimicrobial claims under the Pest Control Products Act, creating dual-compliance obligations for cross-border suppliers. Ontario's automotive corridor in Windsor and Oshawa mirrors Detroit's bonding application specifications for lightweight vehicle platforms.
Mexico
Guadalajara and Tijuana electronics contract manufacturing clusters expand cleanroom bonding capacity for miniaturized component assembly. The country's environmental regulator SEMARNAT aligns industrial emissions standards with US EPA frameworks to maintain maquiladora export access. Jalisco state's automotive supplier parks in El Salto are adopting UV-cured acrylic systems for interior electronics modules.
North America Reactive Adhesives Market Competitive Landscape
United States producers anchor the volume tier; European specialists hold premium formulation positions. The market structure consolidates around three to five integrated chemical conglomerates with captive resin synthesis capabilities, while mid-scale regional formulators compete on technical service proximity. Two strategic archetypes dominate: diversified materials conglomerates with adhesive divisions, and pure-play adhesive specialists with vertical control over polymer backbones. Capacity expansion and strategic partnerships represent the primary competitive moves, with suppliers co-locating technical service teams near automotive assembly plants.
Within the diversified conglomerate tier, 3M and Dow exemplify scale-driven positions anchored by tape-adhesive hybrid platforms and silane-modified chemistry expertise respectively. Henkel AG & Co. KGaA represents the European specialist archetype with polyurethane formulation heritage. These three companies occupy positions that span multiple chemistry types and end-use verticals, enabling cross-selling into automotive OEM qualification programs.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H.B. Fuller Company |
| Dow |
| Avery Dennison Corporation |
| Dymax Corporation |
| Huntsman International LLC |
| Others |
Value Network & Pricing Analysis
Captive resin synthesis capabilities among the three largest North American suppliers anchor both supply security and pricing power, locking in preferential access to MDI and TDI feedstocks while forcing smaller formulators into volatile spot markets for isocyanate precursors.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for epoxy resin intermediates, compressing margins for mid-scale formulators lacking backward integration into bisphenol-A supply. Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial grades reflects the cost of OEM validation protocols. Pricing pressure stems from automotive procurement consolidation to single-source frameworks with biannual price reviews. Tier-1 suppliers exhibit lowest price sensitivity due to qualification lock-in, while construction distributors face acute cost compression from green building mandate compliance.
Supply Chain Analysis
USMCA domestic-content rules for automotive components are reshaping sourcing patterns, pushing adhesive suppliers to qualify Mexican resin finishing capacity for Detroit-area OEM contracts. Feedstock dependence draws from Gulf Coast petrochemical corridors for epoxy intermediates, Great Lakes regional production for polyurethane prepolymers, and imported silane coupling agents from Germany and Japan. Single-source vulnerability concentrates in isocyanate supply where three producers control North American MDI capacity. Distribution runs through direct mill-to-plant logistics contracts with embedded technical service teams, displacing traditional regional distributor networks in Michigan and Ohio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American reactive adhesives represent a late-cycle quality story as automotive OEMs shift procurement authority toward material engineering teams willing to pay formulation premiums for crashworthiness-validated structural bonding systems.
For Market Incumbents: Deepen captive control over silane-modified polymer synthesis to defend against emerging hybrid-platform competitors from European specialty chemical houses. Accelerate co-location of technical service teams near expanding electric vehicle assembly plants in Tennessee and Kentucky to preempt qualification cycle lockout. Prioritize low-monomer polyurethane formulation investment ahead of anticipated OSHA isocyanate exposure limit tightening. For New Entrants and Emerging Players: EPA NESHAP VOC phase-out timelines in Michigan and Ohio open a window for solvent-free epoxy specialists to capture displaced solvent-based adhesive volumes in automotive refinishing applications. Target wind blade manufacturing clusters in Texas and Iowa with accelerated qualification protocols that bypass the 18-36 month automotive validation cycles. Lead with hybrid UV-thermal cure platform demonstrations to electronics contract manufacturers in Guadalajara seeking automation compatibility. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale polyurethane formulators because automotive OEM consolidation has collapsed the number of qualified suppliers while preserving premium pricing for validated products. Focus on targets with existing aerospace or automotive OEM approvals that can be leveraged across multi-material bonding applications. Watch for EPA enforcement acceleration on NESHAP compliance deadlines as the inflection signal for distressed acquisition opportunities among non-compliant solvent-based formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive MDI and epoxy intermediate production insulates margins from benzene price volatility. |
| Co-located Technical Service Expansion | Proximity to Detroit-area OEM plants compresses qualification cycle timelines for new adhesive platforms. |
| Low-Monomer Formulation Development | OSHA isocyanate exposure rule anticipation positions suppliers ahead of respiratory protection mandates. |
| Wind Blade Qualification Fast-Track | Shorter certification timelines than aerospace unlock utility-scale composite bonding revenue streams. |
| Hybrid UV-Thermal Cure Platform Launch | Convergent cure technology enables automation in Guadalajara electronics cleanroom assembly operations. |
Research Methodology
Multiple input streams — structured interviews with adhesive formulator R&D directors and automotive OEM material engineers, trade data reconciliation from USITC and Statistics Canada import records, and EPA regulatory filing analysis — were reconciled against Dow, Henkel, and 3M segment disclosures in SEC 10-K filings. Bottom-up volume estimates from end-use consumption patterns were triangulated with top-down chemical industry capacity data from the American Chemistry Council.
Historical volume trajectories were cross-referenced against expert panel assessments of electric vehicle platform adoption rates and green building code implementation timelines across the analysis window. Segmentation modeling incorporated chemistry type, cure mechanism technology, end-use vertical, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections for lightweight vehicle assembly and electronics miniaturization trends.
Revisions become necessary when EPA NESHAP enforcement intensity, OSHA isocyanate rule finalization, or USMCA domestic-content interpretation shifts materialize beyond current administrative guidance assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Global Methyl Acrylate Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Europe Reactive Adhesives Market