
 Amine Curing Agents Market | 2026-2036
Amine Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Amine Curing Agents Market Analytics
Modular additive packages is repositioning procurement patterns across the amine curing agents sector. Huntsman Corporation leverages its integrated epoxy-amine platform to control formulation consistency for wind energy customers. Evonik Industries AG specializes in cycloaliphatic grades that sustain premium positioning in electrical insulation applications. Dow anchors North American supply through backward integration into ethyleneamine feedstocks.
Amine curing agents are nitrogen-containing organic compounds that crosslink epoxy resins through nucleophilic addition to oxirane rings, typically requiring stoichiometric ratios of active hydrogen equivalents to epoxy functionality for complete cure. These agents serve as the chemical backbone for thermoset networks in protective coatings, structural adhesives, and fiber-reinforced composites. Aliphatic amines dominate volume consumption in ambient-cure construction coatings where fast handling properties command utility. Cycloaliphatic amines capture disproportionate margin pools in electrical encapsulation applications where low color and UV stability differentiate performance. Aromatic amines retain entrenched positions in high-temperature aerospace composites despite tighter occupational exposure thresholds.
EPA regulates volatile organic compound emissions from coating operations under National Emission Standards for Hazardous Air Pollutants, pushing formulators toward low-VOC amine adducts. REACH restricts certain aromatic amine classifications under Substances of Very High Concern protocols, redirecting R&D investment toward aliphatic and cycloaliphatic alternatives. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for amine manufacturing facilities in Jiangsu and Zhejiang provinces. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and supply chain requalification timelines.
Market Dynamics
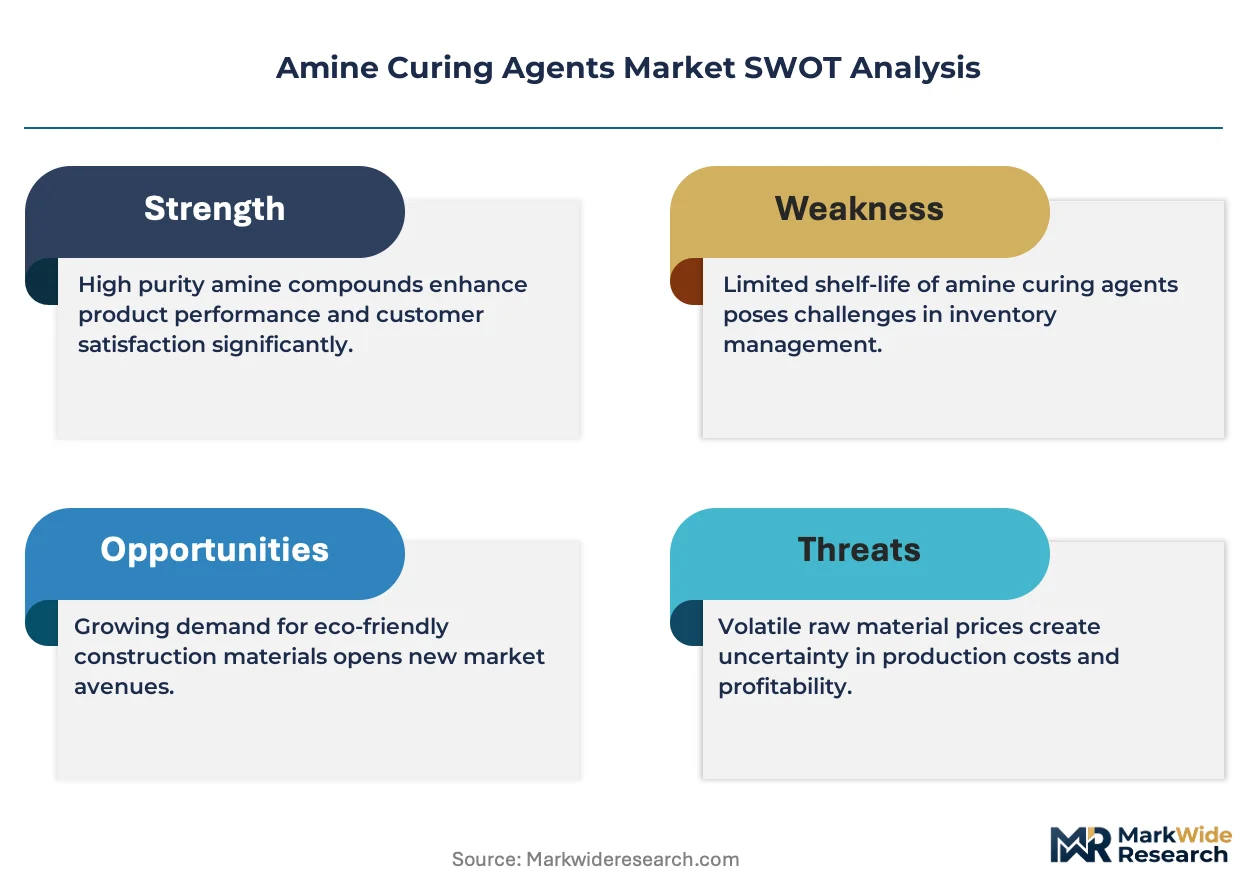
REACH Substances of Very High Concern protocols are forcing systematic reformulation across European epoxy-amine supply chains, redirecting R&D investment toward aliphatic and cycloaliphatic alternatives while compressing margins on legacy aromatic product lines.
Growth Catalysts
- Wind energy expansion:Offshore turbine blade fabrication in Germany and Denmark drives specialized epoxy-amine formulations. Manufacturers require low-viscosity systems enabling vacuum infusion of carbon fiber spar caps.
- China's dual carbon goals:MEE energy intensity benchmarks accelerate facility upgrades in Jiangsu and Zhejiang provinces. Domestic amine producers capture preferential procurement from state-owned aerospace composite programs.
- Electrical encapsulation demand:Cycloaliphatic amines with low color and UV stability capture premium positioning in EV power module packaging. Japanese automotive tier-1s specify these grades for thermal cycling resistance.
Market Restraints
- Feedstock volatility:Ethyleneamine prices track naphtha-cracker economics, squeezing formulator margins during upstream petrochemical cycles. Dow's backward integration into ethyleneamine feedstocks insulates only integrated players.
- Regulatory fragmentation:Divergent occupational exposure thresholds for aromatic amines between EPA NESHAP and REACH SVHC create dual compliance burdens. Reformulation costs compound for multinational coating suppliers.
- Substitution pressure:Anhydride curing agents displace amines in certain high-temperature aerospace prepregs where latency and hot/wet performance outweigh handling convenience.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing create captive demand for battery encapsulation-grade cycloaliphatic amines. Domestic formulation capabilities remain underdeveloped.
- Modular additive packages:Pre-blended accelerator and rheology modifier systems enable just-in-time compounding at wind blade fabrication sites. This disintermediates traditional distributor channels.
- EU Green Deal chemistry:Bio-based amine feedstocks from fatty acid derivatives qualify for sustainable product procurement mandates. Early movers secure qualification with Dutch and Belgian coating formulators.
Industry Challenges
- Specialized formulation chemist scarcity:Expertise in stoichiometric ratio optimization for epoxy-amine networks concentrates at legacy industrial centers. Emerging market facilities struggle to replicate cure kinetics know-how.
- Supply chain reconfiguration friction:Relocating amine manufacturing from Jiangsu to inland provinces to meet MEE carbon intensity targets requires requalification of aerospace customer specifications. Timeline compression strains technical service resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amine Curing Agents Market |
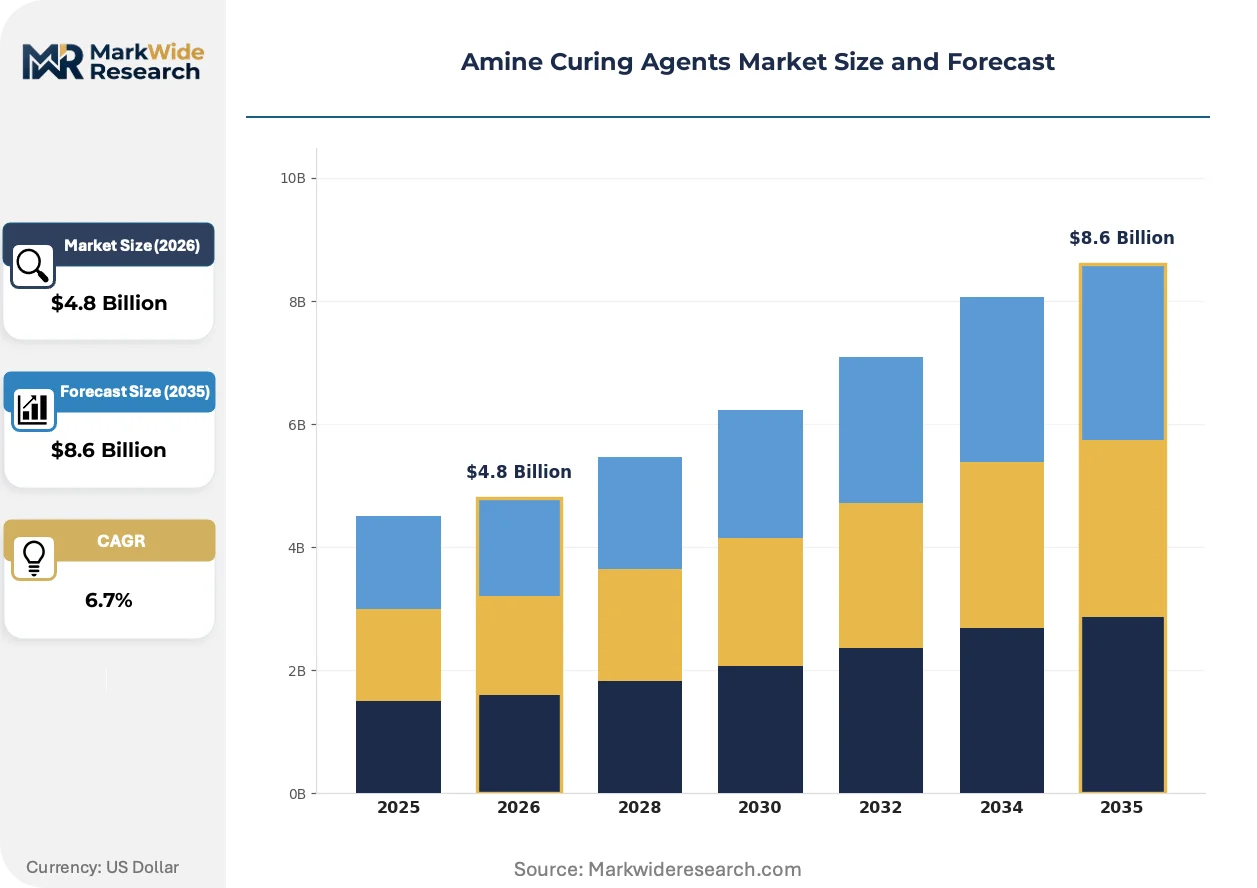
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Amines, Aromatic Amines, Cycloaliphatic Amines, Others End Use Industry: Automotive, Aerospace, Construction, Electrical Application: Coatings, Adhesives, Sealants, Composites Form: Liquid, Solid, Powder, Paste |
| Companies Covered | Huntsman Corporation, BASF SE, Evonik Industries AG, Cardolite Corporation, Aditya Birla Chemicals, Dow, Mitsubishi Chemical Group, Hexion Inc., Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amine Curing Agents Market Evolving Landscape
Formulation chemistry is converging with digital process control systems, enabling real-time viscosity management during automated dispensing operations. This integration is compressing development cycles and reshaping how curing agent suppliers engage with composite fabricators.
Additive manufacturing of epoxy composites is consolidating around photopolymerizable amine-acrylate hybrid systems. Aerospace prototyping shops in France and Germany adopt these materials for rapid tooling applications. The technology is consolidating design-to-part timelines from weeks to days, pressuring conventional batch-scale amine suppliers to develop compatible low-shrinkage grades.
REACH authorization requirements for certain aromatic diamines are tightening occupational exposure documentation obligations. Coating applicators in automotive OEM supply chains face mandatory substitution planning timelines. Italian and Spanish protective coatings specialists accelerate aliphatic amine adduct qualification to preempt enforcement windows.
Specification bundling is concentrating procurement authority at wind turbine OEM engineering centers. Vestas and Siemens Gamesa now dictate approved amine supplier lists to blade fabricators across their global supply bases. This centralization is visible most acutely in Denmark and northern Germany, where blade molding clusters have consolidated from fragmented subcontractor networks to OEM-captive facilities.
Amine Curing Agents Market Segmentation
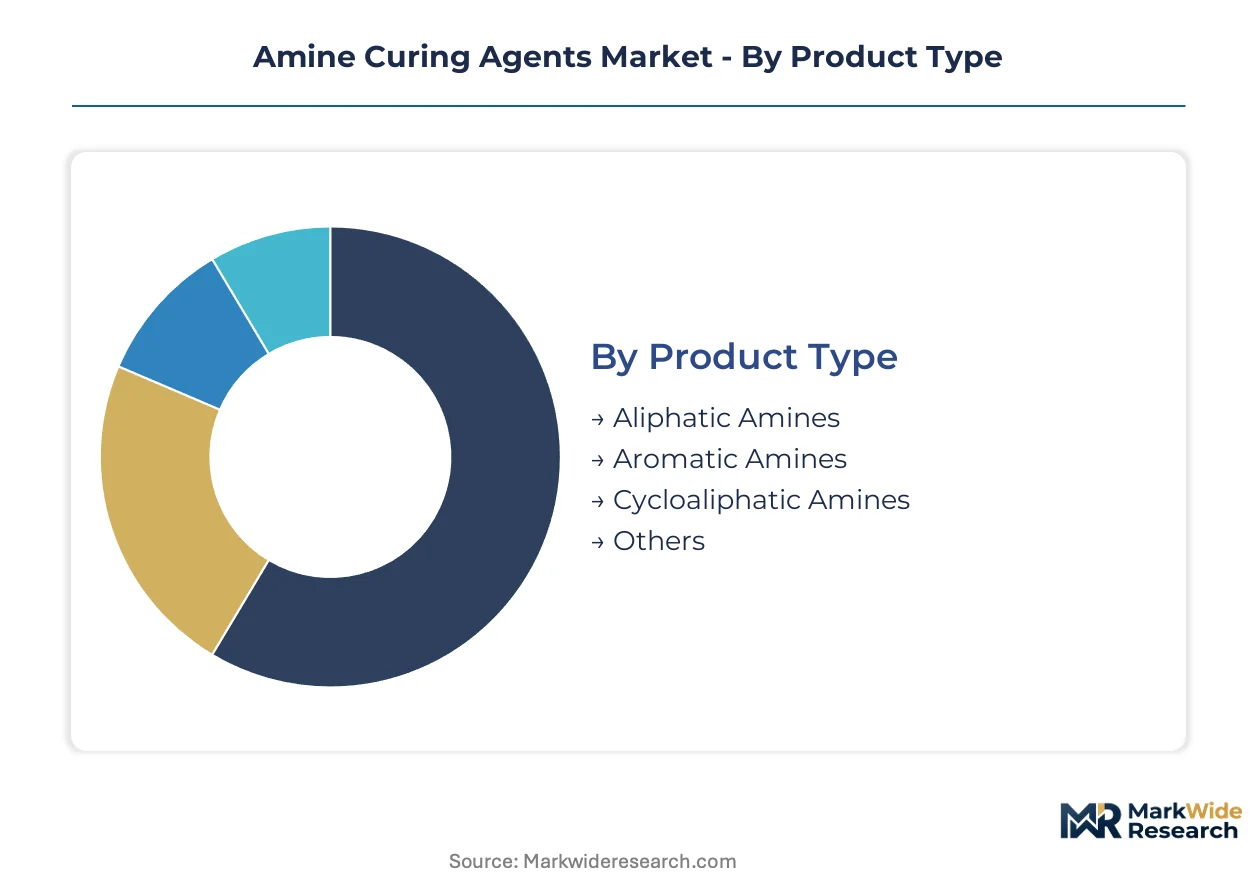
Segmentation in amine curing agents reveals how formulation chemistry aligns with distinct performance requirements across end-use specifications. Product architecture, application method, and cure conditions collectively determine procurement patterns and supplier positioning strategies.
Product Type:
Upgrade cycles in epoxy-amine formulations are accelerating as REACH restrictions and performance benchmarks push customers toward higher-tier chemistries.
- Aliphatic Amines:Primary amines and polyamines derived from ethyleneamines deliver rapid ambient-temperature cure kinetics. Construction coating formulators in Germany specify these grades for fast-handling floor and protective systems where return-to-service speed commands premium pricing.
- Cycloaliphatic Amines:Rigid ring structures with secondary amine functionality provide low-color, UV-stable cured networks. Japanese automotive tier-1s and German EV power module manufacturers specify these for electrical encapsulation where thermal cycling resistance and visual clarity differentiate performance tiers.
- Aromatic Amines:Aniline-derivative structures with elevated glass transition temperatures retain entrenched positions in aerospace prepregs despite tighter occupational exposure documentation obligations under REACH authorization protocols.
- Others:Modified amine adducts, Mannich bases, and phenalkamines serve niche applications including underwater cure and chemically resistant tank linings.
Aliphatic amines sit at the top of the volume ranking, with cycloaliphatic amines climbing the fastest as electrical encapsulation specifications tighten.
End Use Industry:
Cost tier differentiation separates specification-grade aerospace formulations from commodity construction applications, with margin structures varying by an order of magnitude.
- Automotive:Battery encapsulation and structural adhesive applications specify cycloaliphatic and modified aliphatic grades. Indian PLI scheme incentives for advanced chemistry cell manufacturing are creating captive demand that domestic formulation capabilities struggle to fulfill.
- Aerospace:Carbon fiber prepregs and primary structural adhesives require aromatic amine hardeners with hot/wet performance retention. REACH SVHC protocols are forcing systematic reformulation timelines across European supply chains.
- Construction:Ambient-cure protective coatings and flooring systems consume aliphatic amine volumes. Chinese coastal industrial provinces in Jiangsu and Zhejiang concentrate fabrication clusters serving domestic infrastructure programs.
- Electrical:Potting compounds and encapsulants for transformers, switchgear, and EV power electronics demand cycloaliphatic grades with low ionic content and dielectric stability.
Construction commands the largest volume position, while electrical applications are expanding most quickly as electrification accelerates across automotive and grid infrastructure.
Application:
Application method determines viscosity, pot life, and cure schedule requirements, with automated dispensing systems reshaping formulation specifications.
- Coatings:Solvent-borne and high-solids epoxy-amine systems dominate protective and marine applications. EPA NESHAP regulations on volatile organic compound emissions are pushing formulators toward low-VOC amine adducts in US manufacturing.
- Adhesives:Structural bonding applications in wind turbine blade fabrication require low-viscosity systems enabling vacuum infusion of carbon fiber spar caps. Vestas and Siemens Gamesa centralize approved supplier lists across their global supply bases.
- Sealants:Flexible epoxy-amine formulations serve expansion joint and secondary containment applications where elongation and chemical resistance balance.
- Composites:Fiber-reinforced epoxy systems in aerospace and wind energy specify precise stoichiometric ratios for optimized mechanical properties and thermal performance.
Coatings maintain the broadest installed base, with composites gaining share fastest as wind blade dimensions scale and aerospace production rates recover.
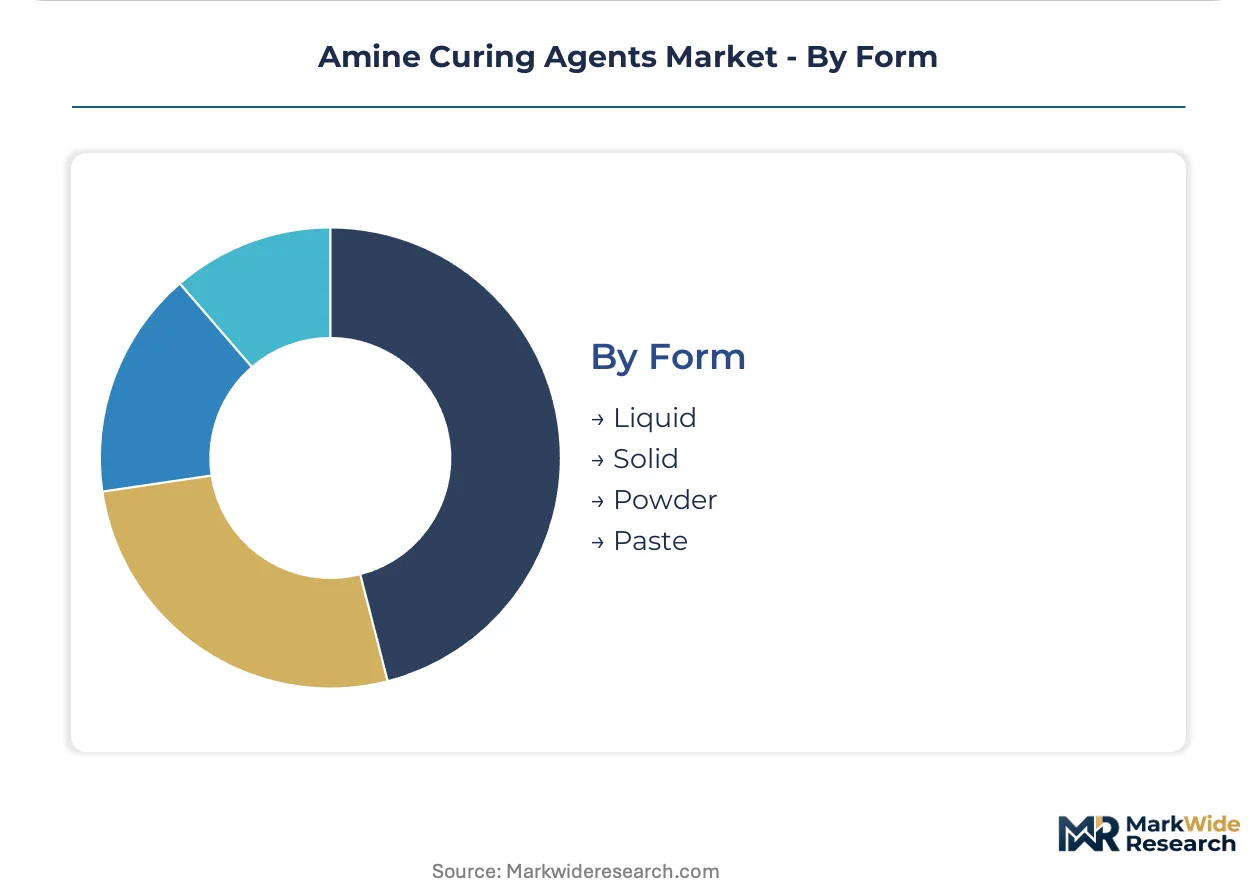
Form:
Physical form selection reflects handling logistics, shelf stability requirements, and compatibility with automated metering equipment.
- Liquid:Low-viscosity amines and reactive diluent-modified systems enable spray application and automated dispensing. Wind blade fabrication sites in Denmark and northern Germany specify pumpable grades for vacuum infusion processes.
- Solid:Powdered diamines and latent curing agents provide extended shelf life and controlled cure latency. Hot-melt adhesive formulations and powder coatings utilize these grades.
- Powder:Micronized amine hardeners for epoxy powder coating systems where electrostatic application and controlled film build are required.
- Paste:Thixotropic formulations with fumed silica or clay additives for trowel-applied patching compounds and vertical surface coatings.
Liquid forms dominate current consumption patterns, with solid grades showing steepest expansion trajectory in powder coating and hot-melt adhesive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial epoxy-amine chemistry during the post-war chemicals expansion, establishing formulation expertise that now serves wind energy and aerospace clusters across Northern Europe. Production legacy in the Rhine-Ruhr corridor created technical know-how that diffused into adjacent specialty chemical sectors.
Germany
Offshore wind turbine blade fabrication in Lower Saxony and Schleswig-Holstein drives specialized low-viscosity epoxy-amine systems for carbon fiber spar cap infusion. ECHA REACH Substances of Very High Concern protocols mandate systematic reformulation away from certain aromatic diamines. The Hamburg blade molding cluster has consolidated from fragmented subcontractors to OEM-captive facilities under Vestas and Siemens Gamesa supply base control.
China
State-owned aerospace composite programs in Jiangsu and Zhejiang provinces generate concentrated procurement of specification-grade cycloaliphatic amines. MEE dual carbon goals tighten energy intensity benchmarks for amine manufacturing, forcing facility relocations inland. The Yangtze River Delta fabrication corridor serves domestic infrastructure and aviation supply chains with growing technical sophistication.
United States
EPA National Emission Standards for Hazardous Air Pollutants push coating formulators toward low-VOC amine adducts in automotive OEM supply chains. Dow's backward integration into ethyleneamine feedstocks anchors North American supply security. The Gulf Coast petrochemical corridor concentrates upstream amine precursor production with downstream distribution into construction and marine coatings markets.
Japan
Automotive tier-1 suppliers specify cycloaliphatic grades with low color and UV stability for EV power module thermal cycling resistance. METI industrial standards govern electrical encapsulation material qualification timelines. The Nagoya manufacturing belt concentrates formulation expertise for high-reliability electronics packaging applications.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing create captive demand for battery encapsulation-grade cycloaliphatic amines that domestic formulation capabilities struggle to fulfill. BIS quality certification requirements slow import substitution timelines. Gujarat and Maharashtra coastal industrial zones concentrate composite fabrication for domestic infrastructure and emerging aerospace programs.
Amine Curing Agents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance documentation. The vendor base stratifies into three tiers: integrated petrochemical majors with captive feedstock positions, European and Japanese specialty chemical houses with cycloaliphatic expertise, and regional construction coating suppliers competing on handling speed and local service. Consolidation pressure concentrates procurement authority at wind turbine OEM engineering centers, while REACH-driven reformulation compresses margins on legacy aromatic product lines.
Within the integrated petrochemical tier, Huntsman Corporation and Dow exemplify backward-integrated positioning with controlled formulation consistency for wind energy customers. Evonik Industries AG occupies a specialist position in cycloaliphatic grades that sustain premium positioning in electrical insulation applications. These three companies represent distinct competitive archetypes: feedstock-integrated volume players, performance-grade specialists, and formulation-integrated solution providers.
| Leading Market Players |
|---|
| Huntsman Corporation |
| BASF SE |
| Evonik Industries AG |
| Cardolite Corporation |
| Aditya Birla Chemicals |
| Dow |
| Mitsubishi Chemical Group |
| Hexion Inc. |
| Olin Corporation |
| Others |
Value Network & Pricing Analysis
Feedstock-integrated petrochemical majors with captive ethyleneamine production anchor supply-side discipline across the amine curing agents sector. Their backward control over naphtha-cracker economics insulates formulation consistency for wind energy OEMs while compressing margins on non-integrated aromatic amine specialists facing REACH-driven reformulation costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cycloaliphatic electrical encapsulation grades from commodity aliphatic construction coatings and legacy aromatic aerospace formulations. Price differentiation rests on REACH SVHC compliance documentation and aerospace customer requalification timelines. Pricing pressure stems from ethyleneamine feedstock volatility tracking Gulf Coast petrochemical cycles. Construction coating formulators in China exhibit highest price sensitivity, while Japanese automotive tier-1s accept premiums for thermal cycling resistance.
Supply Chain Analysis
Aerospace customer qualification protocols and REACH authorization documentation create multi-year gating timelines for new amine suppliers seeking entry into European wind blade and EV power module supply chains. Manufacturing concentrates in Germany, China, and the United States, with Jiangsu and Zhejiang provinces serving domestic aerospace programs. Raw material flows draw from naphtha crackers, ethyleneamine derivatives, and aniline feedstocks. Single-source vulnerability runs through concentrated carbon fiber spar cap infusion chemical supply for Vestas and Siemens Gamesa. Distribution runs through OEM-captive blade molding clusters and construction coating distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as REACH restrictions and EV thermal cycling specifications concentrate procurement authority at formulation-integrated suppliers with compliance documentation capabilities.
For Market Incumbents: Deepen backward integration into ethyleneamine feedstocks to match Dow's Gulf Coast positioning and insulate margins from naphtha-cracker volatility. Expand cycloaliphatic capacity in Zhejiang province to capture preferential procurement from state-owned aerospace composite programs before MEE carbon intensity relocations strain technical service resources. For New Entrants and Emerging Players: Photopolymerizable amine-acrylate hybrid systems for aerospace rapid tooling offer technology-first wedge into French and German prototyping shops where design-to-part compression pressures conventional batch-scale suppliers. Target India's PLI scheme for advanced chemistry cell manufacturing where domestic formulation capabilities remain underdeveloped and BIS certification creates import substitution friction. For Investors and Strategic Acquirers: Valuations sit cheapest among regional construction coating suppliers lacking REACH compliance documentation capabilities and cycloaliphatic grade portfolios. Long-term viability favors specialists with aerospace customer requalification relationships and bio-based amine feedstock positions qualifying for EU Green Deal procurement mandates. Watch for MEE enforcement windows accelerating facility relocations from Jiangsu to inland provinces as inflection indicator for supply chain reconfiguration plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethyleneamine Feedstocks | Dow's captive supply secures formulation consistency for Vestas and Siemens Gamesa blade programs. |
| Cycloaliphatic Capacity Expansion in Zhejiang | MEE dual carbon compliance positions suppliers for state-owned aerospace composite procurement preference. |
| Bio-Based Amine Feedstock Qualification | EU Green Deal chemistry mandates reward early movers with Dutch and Belgian coating formulators. |
| Modular Additive Package Development | Pre-blended systems disintermediate distributor channels at Denmark and northern Germany blade sites. |
| REACH SVHC Reformulation Acceleration | Italian and Spanish protective coatings specialists preempt enforcement with aliphatic amine adduct qualification. |
Research Methodology
Bottom-up epoxy-amine formulation modeling reconciled against top-down ethyleneamine feedstock tracking forms the analytical core of this study. Primary interviews with wind blade plant managers, automotive tier-1 procurement leads, aerospace composite R&D directors, and construction coating distribution channel partners combined with secondary validation against ECHA REACH authorization databases, EPA NESHAP compliance filings, customs and trade data, and SEC 10-K disclosures from integrated petrochemical majors. Triangulation across these sources ensures segment-level volume and value estimates reflect actual procurement patterns rather than modeled extrapolation.
Historical trendline analysis of formulation grade transitions and end-use industry consumption patterns established baseline growth trajectories across the projection horizon. The analytical framework models segmentation dimensions including amine chemistry tier, end-use industry application, physical form factor, and regional regulatory cluster. CAGRs derive from slope analysis of grade-specific demand curves adjusted for REACH-driven substitution timelines and MEE carbon intensity enforcement phases. Industry-specific forecast inputs incorporate wind turbine blade dimension scaling and EV power module thermal cycling specification tightening.
The model holds under stable REACH authorization timelines and MEE enforcement phasing; deviation in ECHA Substances of Very High Concern reclassification or naphtha-cracker outage frequency would shift volume trajectories. Forecasts reflect documented assumptions regarding formulation requalification timelines and feedstock cost pass-through mechanisms. A model refresh is warranted upon material change in ECHA authorization protocols or MEE dual carbon goal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market