
 Photo Emulsion Market | 2026-2036
Photo Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Emulsion Market Outlook
EU REACH regulation is hardening restrictions on volatile organic compound emissions from screen printing chemicals. MacDermid sustains its position through captive supply of photopolymer raw materials. FUJIFILM Holdings America Corporation specializes in precision emulsion coatings for electronics lithography. Saati S.p.A. competes on textile-specific formulations that reduce water consumption during stencil development.
Photo emulsion comprises a light-sensitive colloid suspension, typically combining polyvinyl alcohol or gelatin with ammonium dichromate or diazo photoinitiators, that crosslinks upon UV exposure to form durable stencils for ink transfer. Its primary industrial purpose is creating reproducible image carriers for screen printing across textiles, ceramics, and printed circuit boards. Water-soluble emulsions dominate volume in educational and artisan settings where cleanup simplicity outweighs durability demands. UV-sensitive formulations represent the fastest-growing product category as textile printers in Bangladesh and Turkey adopt LED exposure systems to cut energy costs. Electronics applications anchor premium pricing due to sub-micron resolution requirements and cleanroom-grade purity standards.
The EPA enforces National Emission Standards for Hazardous Air Pollutants on coating operations, pushing US manufacturers toward low-VOC water-based alternatives. BIS certification in India mandates heavy metal testing for emulsions used in food-contact packaging applications, creating compliance barriers for unqualified imports. China's MEE implements dual carbon goals that tighten energy intensity benchmarks at emulsion production facilities. Stakeholders must monitor how divergent regional chemical regimes reshape formulation portfolios and determine which technical specifications justify localized manufacturing versus cross-border supply.
Market Dynamics
LED exposure systems are compressing stencil development times across Southeast Asian textile clusters, forcing emulsion suppliers to reformulate for narrower UV wavelength sensitivity while maintaining mesh adhesion under accelerated curing cycles.
Growth Catalysts
- REACH Phase-Out of Chromium Compounds:ECHA restrictions on ammonium dichromate are accelerating diazo photoinitiator adoption in European screen printing operations, creating formulation upgrade cycles among established printers.
- Bangladesh Garment Export Surge:Duty-free access to EU markets under EBA preferences is expanding screen printing capacity in Dhaka and Chittagong, driving emulsion consumption for fast-fashion labeling and embellishment.
- Water-Based Ink Compatibility:Formulators are engineering hybrid emulsion chemistries that withstand both solvent and aqueous ink systems, reducing stencil changeover downtime in multi-substrate print shops.
Market Restraints
- Polyvinyl Alcohol Supply Concentration:Three Chinese manufacturers control over seventy percent of photographic-grade PVA feedstock, exposing formulators to input cost volatility and allocation risk during peak textile seasons.
- Cleanroom Purity Thresholds:Electronics lithography applications require sub-100ppm ionic contamination levels that only two specialized coating facilities outside Japan can consistently achieve, limiting qualified supply expansion.
- Digital Textile Printing Substitution:Direct-to-garment inkjet systems from Italian and Israeli equipment makers are capturing short-run fashion orders previously reserved for screen printing, compressing emulsion volume in sample and capsule production.
Strategic Opportunities
- Turkey Nearshoring Acceleration:European brands are relocating textile finishing from Bangladesh to Turkish Aegean ports to compress lead times, expanding emulsion demand in Izmir and Denizli industrial zones.
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor and PCB manufacturing are attracting cleanroom-grade emulsion investments to Gujarat and Tamil Nadu special economic zones.
- UV-LED Curing Convergence:The pairing of 395nm LED arrays with single-component photopolymer emulsions is eliminating mercury vapor lamp warm-up delays, enabling just-in-time stencil production in Vietnam's export garment sector.
Industry Challenges
- Formulation Chemist Shortage:The retirement of diazo chemistry specialists in Germany and Italy is outstripping university polymer science pipelines, delaying new product qualification cycles.
- Multi-Site BIS Certification:India's mandatory heavy metal testing for food-contact packaging emulsions requires separate facility audits for each production location, extending market entry timelines for multinational suppliers.
- Legacy Equipment Retrofit Complexity:Screen printers in Indonesia and Pakistan operate thirty-year-old exposure frames with inconsistent vacuum drawdown, forcing emulsion suppliers to engineer wider exposure latitude into formulations at premium cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Emulsion Market |
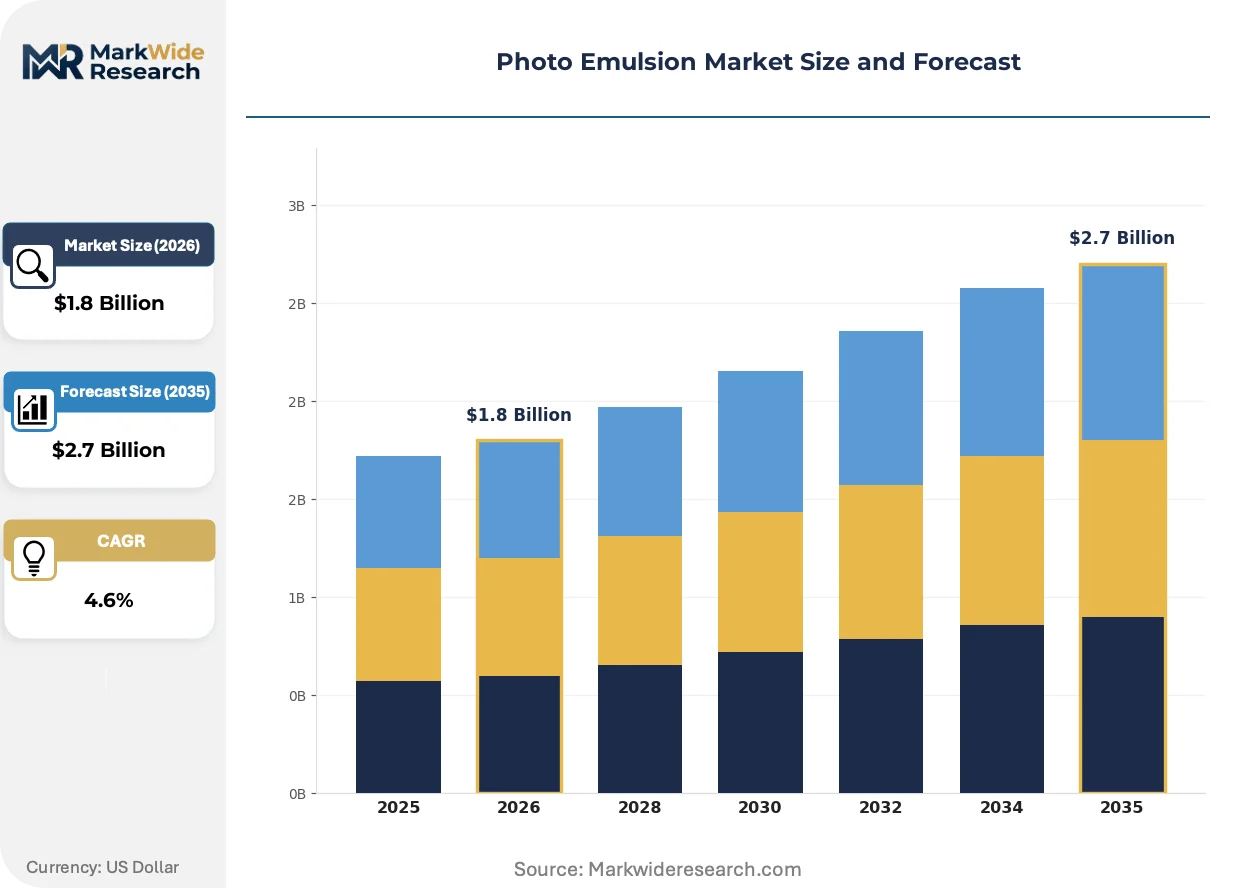
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-soluble, Oil-based, UV-sensitive, Solvent-based Application: Screen Printing, Art Printing, Textile Printing, Electronics End User: Manufacturers, Artists, Designers, Educational Institutions Technology: Digital Print Technology, Analog Print Technology, Hybrid Technology, Traditional Methods |
| Companies Covered | ULANO CORPORATION, MacDermid, PRODECRAN, Kopimask S.A., KIWO, AMEX s.r.l., Saati S.p.A., FUJIFILM Holdings America Corporation, Chromaline Screen Print Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Emulsion Market Strategic Shifts
Formulation science is pivoting from general-purpose durability toward application-specific performance envelopes, with chemistry decisions increasingly downstream of exposure hardware and substrate specifications rather than upstream of them.
Hybrid diazo-photopolymer emulsions are converging with LED exposure hardware to enable single-step stencil development without post-exposure drying stages. Bangladeshi and Turkish textile printers are retrofitting mercury vapor lines with 385-405nm LED arrays to cut energy consumption. This convergence is compressing stencil turnaround from four hours to forty-five minutes in high-volume garment operations.
EPA National Emission Standards for Hazardous Air Pollutants are tightening volatile organic compound thresholds in coating operations across Ohio, North Carolina, and California printing clusters. US formulators are eliminating glycol ether carriers from sensitizer solutions to maintain compliance. Water-based diazo systems are capturing share in educational and sign-making segments previously dominated by solvent-borne chemistries.
Buyer concentration among vertically integrated garment exporters in Vietnam is forcing emulsion suppliers to absorb technical service costs previously borne by distributors. Ho Chi Minh City and Binh Duong print shops now demand on-site mesh preparation training and stencil failure analysis as standard contract terms. This service bundling is squeezing margin for suppliers without regional technical presence.
Photo Emulsion Market Segmentation
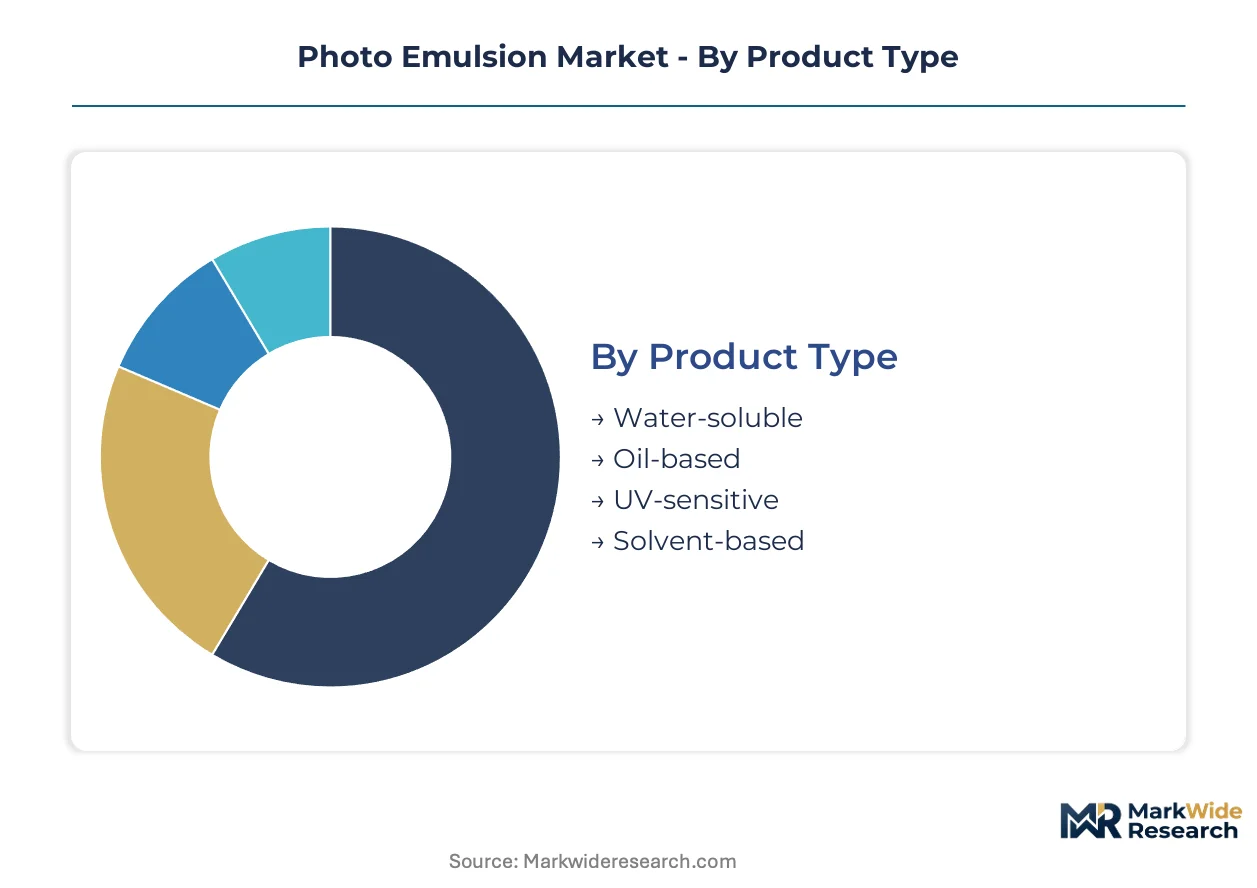
Photo emulsion chemistry varies sharply by exposure hardware and cleanup requirements, driving distinct procurement patterns across textile clusters, electronics cleanrooms, and artisan workshops. Formulators must match viscosity, solids content, and photoinitiator systems to specific mesh counts and substrate porosity rather than selling universal grades.
Product Type:
Printers face recurring reformulation decisions as exposure technology upgrades displace legacy chemistries and regional VOC rules harden.
- Water-soluble:Polyvinyl alcohol colloids with diazo sensitizers dissolve in ambient tap water without solvent recovery systems. Educational institutions and small-batch textile shops in Vietnam and Bangladesh specify these grades for stencil reclamation simplicity despite shorter press life.
- UV-sensitive:Single-component photopolymers with acrylate oligomers crosslink under 395nm LED arrays without post-exposure drying. Turkish Aegean textile finishers are retrofitting mercury vapor lines with LED hardware, compressing stencil turnaround from hours to minutes.
- Oil-based:Hydrocarbon carriers suspend diazo compounds for aggressive solvent ink compatibility in ceramic decal and automotive glass printing.
- Solvent-based:Glycol ether formulations persist in high-durability industrial stencils where reclaim chemistry costs outweigh environmental compliance burdens.
Volume placements concentrate in water-soluble grades; the faster expansion belongs to UV-sensitive formulations.
Application:
End-use specifications diverge across resolution requirements, from sub-micron electronics lithography to coarse mesh textile embellishment.
- Textile Printing:Garment exporters in Dhaka, Chittagong, and Ho Chi Minh City consume emulsion by the ton for fast-fashion labeling, requiring mesh adhesion under high-tension rotary presses and alkaline reclaim cycles.
- Electronics:PCB fabricators and semiconductor mask shops demand ionic contamination below 100ppm and particle-free coatings, with only two qualified coating facilities outside Japan meeting cleanroom-grade purity thresholds consistently.
- Screen Printing:General-purpose signage and container decoration spans solvent, UV, and water-based ink systems, forcing hybrid emulsion formulations.
- Art Printing:Limited-edition serigraphy and fine art reproduction favor water-soluble diazo systems for studio safety and archival pigment compatibility.
Electronics commands premium pricing per liter; textile printing generates the largest absolute volume flows.
End User:
Procurement sophistication spans captive formulation labs, distributor relationships, and direct technical service contracts.
- Manufacturers:Vertically integrated garment exporters in Vietnam's Binh Duong province now bundle on-site mesh preparation training and stencil failure analysis into standard supply contracts, squeezing margin for suppliers without regional technical presence.
- Educational Institutions:University printmaking departments and vocational training centers specify water-soluble, low-toxicity formulations to satisfy campus environmental health protocols.
- Artists:Independent printmakers purchase small-batch diazo kits through specialty distributors, prioritizing shelf stability and mixing simplicity over press durability.
- Designers:Fashion houses and graphic studios operating sample and capsule production face displacement from direct-to-garment inkjet systems, compressing emulsion volume in short-run segments.
Manufacturers dominate procurement scale; educational channels provide steady baseline demand with lower price sensitivity.
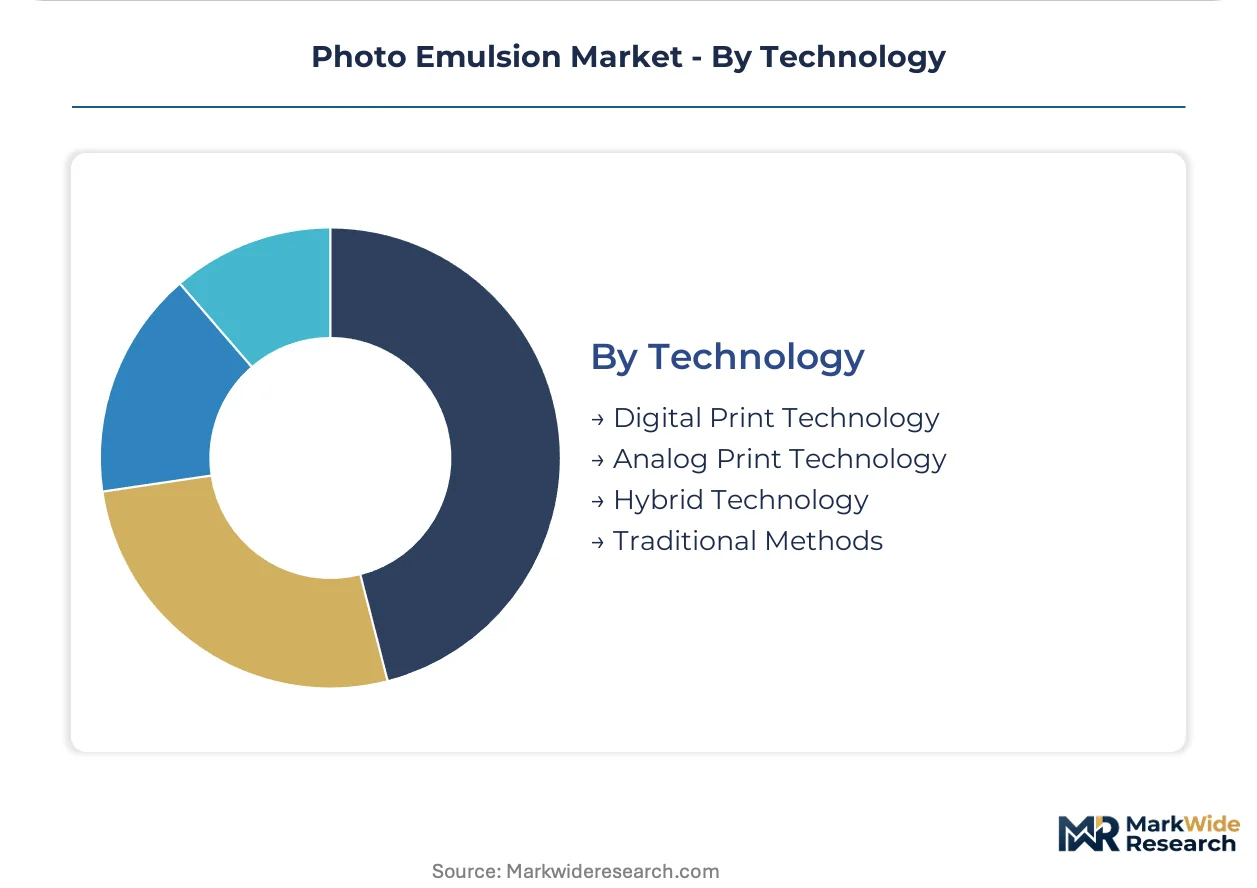
Technology:
Exposure and imaging hardware choices determine emulsion spectral sensitivity, viscosity, and solids loading requirements.
- Digital Print Technology:Computer-to-screen systems using inkjet-deposited wax or toner masks eliminate photographic film, requiring emulsions with precise wet thickness control and minimal surface tack.
- Analog Print Technology:Mercury vapor exposure frames with vacuum drawdown remain prevalent in Indonesia and Pakistan, forcing suppliers to engineer wider exposure latitude into formulations at premium cost.
- Hybrid Technology:LED exposure with digital film positives combines in Bangladeshi and Turkish retrofit installations, demanding reformulation for narrower UV wavelength sensitivity.
- Traditional Methods:Sunlight exposure and hand-cut stencils persist in rural artisan clusters and development programs, specifying coarse-mesh, forgiving emulsion grades.
Analog systems retain installed base dominance; hybrid configurations are climbing the fastest as LED retrofit accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City and Binh Duong province anchor the most concentrated textile emulsion demand cluster outside China, with vertically integrated garment exporters consuming tonnage quantities for fast-fashion labeling and embellishment operations.
Vietnam
Binh Duong's export-oriented garment sector drives bulk emulsion procurement for rotary screen presses, with EPA-aligned environmental standards influencing supplier qualification. The country's MEE implements dual carbon goals tightening energy intensity at production facilities. Ho Chi Minh City print shops now mandate on-site mesh preparation training as standard contract terms.
United States
Ohio, North Carolina, and California printing clusters face EPA National Emission Standards for Hazardous Air Pollutants enforcement, pushing reformulation toward low-VOC water-based alternatives. The EPA regulates coating operations with tightening volatile organic compound thresholds. Educational institutions and sign-making segments in these states specify water-based diazo systems for campus environmental health compliance.
Germany
ECHA restrictions on ammonium dichromate accelerate diazo photoinitiator adoption in European screen printing operations, creating formulation upgrade cycles among established printers. REACH compliance hardens formulation standards for solvent-based chemistries. Stuttgart and Munich industrial zones host specialized coating facilities serving electronics lithography applications.
Turkey
European brands relocating textile finishing from Bangladesh to Turkish Aegean ports compress lead times, expanding emulsion demand in Izmir and Denizli industrial zones. LED exposure hardware retrofitting accelerates across Turkish textile finishers. The Izmir corridor now hosts the fastest-growing cluster of 395nm LED array installations paired with single-component photopolymer systems.
India
BIS certification mandates heavy metal testing for emulsions used in food-contact packaging applications, creating compliance barriers for unqualified imports. The country's production-linked incentive scheme for semiconductor and PCB manufacturing attracts cleanroom-grade emulsion investments. Gujarat and Tamil Nadu special economic zones concentrate new technical service operations for electronics-grade supply.
Photo Emulsion Market Competitive Environment
The competitive structure tilts toward specialty chemical conglomerates with captive photopolymer raw material supply. Three strategic archetypes dominate: diversified imaging technology holding companies with precision coating capabilities, textile-focused formulators with regional technical service networks, and industrial chemical suppliers with backward integration into sensitizer chemistry. Competitive moves concentrate on geographic expansion through distributor acquisition and technology licensing for LED-compatible formulations.
Among diversified imaging technology holding companies, FUJIFILM Holdings America Corporation and MacDermid occupy positions defined by upstream control over coating science and photopolymer feedstocks. Within the textile-specialist tier, Saati S.p.A. exemplifies regional technical service bundling, while ULANO CORPORATION represents the established North American formulator archetype with educational and industrial segment coverage. These three anchors illustrate how competitive positioning separates premium electronics-grade purity from high-volume textile supply.
| Leading Market Players |
|---|
| ULANO CORPORATION |
| MacDermid |
| PRODECRAN |
| Kopimask S.A. |
| KIWO |
| AMEX s.r.l. |
| Saati S.p.A. |
| FUJIFILM Holdings America Corporation |
| Chromaline Screen Print Products |
| Others |
Value Chain & Pricing Dynamics
LED exposure hardware retrofitting across Turkish and Bangladeshi textile clusters simultaneously compresses stencil turnaround times and concentrates procurement leverage among vertically integrated garment exporters, forcing emulsion suppliers to absorb technical service costs previously distributed through channel margins while reformulating for narrower wavelength sensitivity at elevated R&D expense.
Pricing Analysis
Yield-based pricing anchors electronics-grade emulsions, where sub-100ppm ionic contamination thresholds command substantial premiums over textile grades. Three-tier pricing structure across premium, standard, and economy levels separates cleanroom-certified coatings from general-purpose durability grades and educational water-soluble formulations. Cost compression in textile segments intensifies because Vietnamese buyers now mandate bundled on-site training and failure analysis as standard contract terms. Educational institutions exhibit lowest price sensitivity due to campus safety protocols, while export garment manufacturers negotiate aggressively on volume commitments.
Supply Chain Analysis
Ocean freight volatility from Chinese PVA feedstock ports to Southeast Asian formulators amplifies working capital requirements during peak textile seasons. Photographic-grade polyvinyl alcohol production concentrates in China, with diazo photoinitiator synthesis anchored in Germany and Italy. Supply chain risk centers on single-source vulnerability for ionic-purity coating facilities serving semiconductor mask shops. Distribution runs through regional technical service operations in Vietnam, Turkey, and India that bundle formulation supply with mesh preparation training and stencil troubleshooting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photo emulsion market sits in a technology-transition phase, with UV-LED curing systems displacing mercury vapor exposure hardware and single-component photopolymers replacing two-part diazo formulations across high-volume textile operations.
For Market Incumbents: Lock in captive photopolymer supply through backward integration into acrylate oligomer production, insulating margin from Chinese PVA feedstock volatility. Secure BIS certification for Indian food-contact packaging applications ahead of multinational competitors, converting compliance barriers into channel control. Direct-to-garment inkjet substitution threatens short-run segments; defend core volume through LED retrofit partnerships with Turkish and Vietnamese textile finishers. For New Entrants and Emerging Players: REACH Phase-Out of Chromium Compounds in Europe opens a window for diazo photoinitiator specialists to capture formulation upgrade cycles among established printers. Target India's production-linked incentive zones for semiconductor and PCB manufacturing, where cleanroom-grade emulsion demand outpaces qualified supply. Enter through technical service contracts rather than distributor relationships, matching Vietnamese buyer expectations for on-site support. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical conglomerates seeking precision coating capabilities and regional technical service networks. Long-term viability hinges on LED-compatible formulation portfolios and captive raw material positions. Watch the pace of direct-to-garment inkjet adoption in sample and capsule production as the critical inflection signal for textile emulsion volume erosion.| Strategic Initiative | Industry Significance |
|---|---|
| LED-Compatible Formulation Development | Enables 395nm wavelength sensitivity for Turkish and Vietnamese retrofit installations. |
| Backward Integration into Photopolymer Feedstocks | Secures acrylate oligomer supply against Chinese PVA concentration risk. |
| BIS Certification Investment for India | Unlocks food-contact packaging applications under mandatory heavy metal testing rules. |
| Regional Technical Service Expansion | Matches Vietnamese buyer demands for on-site mesh preparation and failure analysis. |
| Cleanroom Coating Facility Qualification | Addresses sub-100ppm ionic contamination requirements for semiconductor lithography. |
Study Parameters
Independent corroboration across primary interviews with emulsion formulation chemists, textile print shop operations managers, and electronics cleanroom procurement leads, combined with secondary validation through ECHA regulatory filings, EPA National Emission Standards enforcement records, and customs trade data, underwrites the qualitative findings. Bottom-up demand modeling from individual textile cluster consumption and top-down supply verification from coating facility capacity assessments generate convergent volume estimates.
Comparable-period anchoring to historical LED adoption curves in adjacent curing chemistries shapes the projection methodology across the analysis window. Segmentation dimensions span product chemistry, exposure technology compatibility, application resolution requirements, and regional regulatory clusters. CAGRs derive from fitted growth curves calibrated to equipment retrofit timelines and formulation upgrade cycles. Electronics content per PCB layer and textile print runs per stencil replacement frequency constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for UV-LED curing convergence would alter the outlook if mercury vapor equipment lifespans extend beyond replacement thresholds. Forecasts reflect assumptions regarding REACH enforcement consistency, BIS audit timelines, and Vietnamese garment export growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
North America Chromatography Resins Market