
 Solvent-Borne Adhesives Market | 2026-2036
Solvent-Borne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent-Borne Adhesives Market Analytics
Water-based adhesive chemistry is hardening its position in packaging and consumer goods, yet solvent-borne systems retain irreplaceable performance in high-stress industrial bonding where moisture resistance and rapid green strength prove critical. Henkel AG & Co. KGaA leverages its global manufacturing footprint to sustain supply security for automotive OEMs across multiple continents. H.B. Fuller anchors its competitive stance through specialized formulations for woodworking and furniture assembly. Sika AG dominates construction-sector applications with engineered solvent systems designed for extreme climate exposure.
Solvent-borne adhesives are formulated solutions in which an organic solvent carries the active polymeric resin, typically comprising polyurethane, epoxy, acrylic, or rubber bases dissolved in hydrocarbon or oxygenated solvents that evaporate to form a bonded joint; these systems achieve handling strengths within minutes and final cure through solvent release or chemical crosslinking, serving industries where water-based alternatives fail on substrate compatibility or environmental durability. Polyurethane formulations command the largest value share due to their versatility across automotive and construction bonding, while acrylic segments capture premium margins in electronics assembly where optical clarity and thermal stability carry specification weight. Rubber-based solvent adhesives occupy a mature volume position in footwear and general packaging applications where cost thresholds dominate procurement decisions.
EPA VOC regulations under the Clean Air Act constrain permissible solvent content in consumer-facing and industrial products, while REACH governs chemical substance authorization across European manufacturing and import channels, and China's MEE enforces emission standards that directly shape formulation practices in the world's largest production base. Regulatory divergence between jurisdictions forces multinational suppliers to maintain parallel product portfolios rather than unified global formulations. Stakeholders must monitor evolving substance restriction lists and carbon-border adjustment mechanisms to anticipate which solvent chemistries will retain market access versus face phasedown mandates.
Market Dynamics
REACH substance restrictions and EPA VOC emission limits are forcing parallel formulation tracks across manufacturing footprints, fragmenting product portfolios and raising compliance costs for multinational adhesive suppliers serving automotive and construction end-uses.
Growth Catalysts
- Automotive lightweighting mandates:Structural bonding of dissimilar materials in electric vehicle platforms relies on solvent-borne polyurethane systems for crash-resistant joints. OEM assembly lines in Germany and China specify these formulations for aluminum-to-composite bonding.
- MEE emission standard enforcement:China's Ministry of Ecology and Environment is tightening VOC discharge permits for industrial coating and adhesive operations, creating certified demand for compliant solvent systems in electronics manufacturing clusters around Shenzhen and Suzhou.
- Construction durability specifications:Infrastructure projects in extreme climate zones specify solvent-borne epoxy and polyurethane adhesives for structural glazing and facade bonding where thermal cycling resistance exceeds water-based alternatives.
Market Restraints
- Petrochemical feedstock volatility:Aromatic hydrocarbon and oxygenated solvent prices fluctuate with crude oil and natural gas derivatives, compressing margin predictability for formulated adhesive producers.
- Water-based substitution in packaging:Flexible packaging converters in food and consumer goods are migrating to water-based acrylic and hot-melt systems where moisture resistance requirements permit, eroding rubber-based solvent adhesive volumes.
- Substance authorization bottlenecks:ECHA's REACH authorization process delays market access for novel solvent chemistries, forcing reliance on legacy formulations with established safety dossiers.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for electronics manufacturing and automotive assembly in Tamil Nadu and Gujarat are creating greenfield demand for industrial-grade bonding systems.
- Repair and maintenance services:Aftermarket automotive collision repair and building facade refurbishment channels represent underdeveloped revenue streams for fast-curing solvent adhesive kits.
- Low-VOC solvent innovation:Exempt compounds under EPA's Method 24 testing protocol, including certain acetate esters and siloxanes, offer regulatory-compliant pathways for next-generation formulations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in solvent-polymer compatibility and rheology control is concentrating at established suppliers, constraining new market entry.
- Dual-registration burden:Maintaining separate REACH-compliant and EPA-registered product lines doubles toxicology testing and regulatory filing costs for global portfolios.
- Legacy equipment retrofit costs:Converting water-based adhesive application lines to handle solvent-borne systems requires explosion-proofing and ventilation upgrades that delay contract wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent-Borne Adhesives Market |
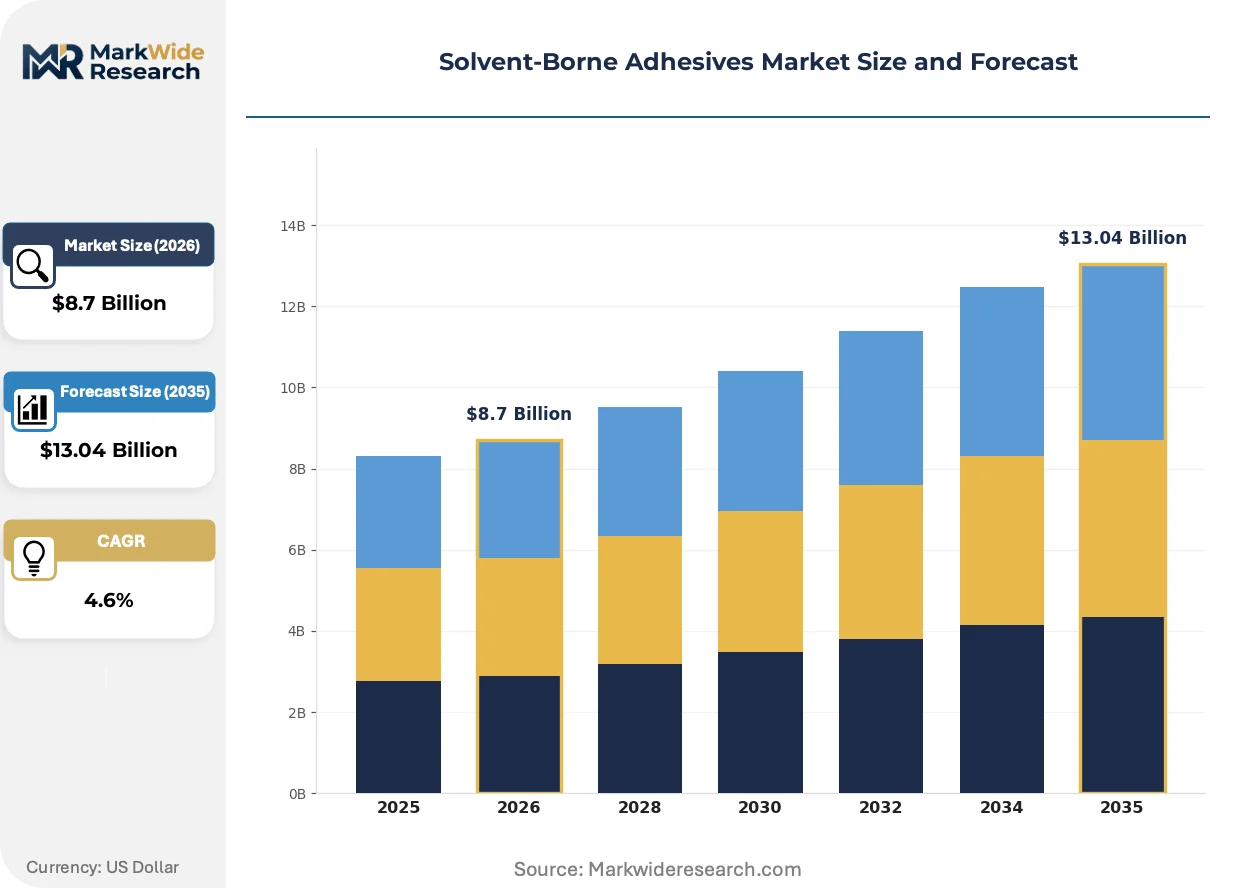
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Rubber End User: Automotive, Construction, Electronics, Furniture Application: Packaging, Woodworking, Automotive Assembly, Footwear Technology: Hot Melt, Reactive, Pressure Sensitive, Solvent Based |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller, Sika AG, Arkema Group, Avery Dennison Corporation, Huntsman Corporation, Illinois Tool Works Inc., Jowat AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent-Borne Adhesives Market Evolving Landscape
Reactive hot-melt hybrids and UV-curable solvent systems are compressing the performance gap between traditional solvent-borne chemistry and emerging cure technologies, reshaping specification dynamics across industrial bonding applications.
Hybrid reactive polyurethane hot-melt systems combine initial solvent-carried tack with moisture-cured structural strength, delivering handling properties competitive with solvent-borne grades while reducing VOC emissions. Automotive Tier-1 suppliers in Stuttgart and Detroit are qualifying these materials for interior trim and seating applications. This convergence is modularizing equipment investments, allowing single production lines to switch between formulation classes without dedicated solvent recovery infrastructure.
EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) for miscellaneous organic chemical manufacturing is tightening residual solvent limits in adhesive production facilities. The rule forces capital expenditure on thermal oxidizers and carbon capture systems at US manufacturing sites. Small and mid-sized formulators in Ohio and Texas are responding by consolidating production at compliant toll manufacturing partners rather than upgrading captive facilities.
Specification-driven procurement is compressing supplier qualification cycles as automotive and aerospace OEMs consolidate approved vendor lists. Tier-2 adhesive converters face direct pressure from Boeing, Airbus, and Volkswagen procurement teams to demonstrate ISO 9001 and IATF 16949 certification prior to trial orders. This concentration is most visible in Germany's Baden-Württemberg automotive supply basin, where adhesive distributors report 40% reduction in active supplier rosters since 2022.
Solvent-Borne Adhesives Market Segmentation
Solvent-borne adhesive procurement splits sharply between specification-driven industrial buyers and cost-sensitive commodity purchasers. Understanding where formulation chemistry, end-use durability requirements, and regulatory compliance intersect determines supplier positioning across each segment boundary.
Product Type:
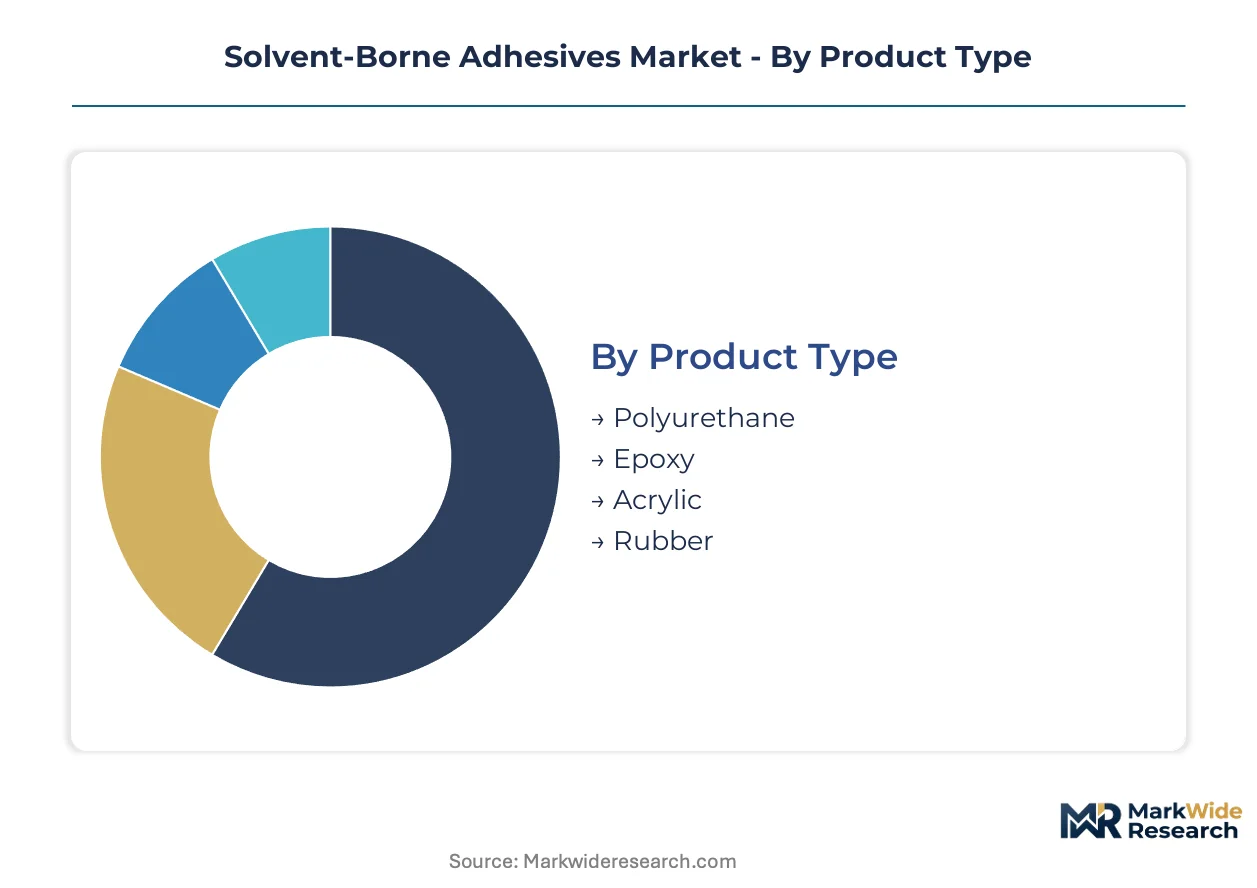
Polyurethane formulations command the largest revenue base, while epoxy and acrylic segments capture premium positioning through specialized performance attributes.
- Polyurethane:These systems dissolve isocyanate-terminated prepolymers in aromatic hydrocarbon carriers, achieving rapid green strength through moisture-triggered crosslinking. Automotive assembly plants in Germany and China specify polyurethane grades for aluminum-to-composite structural bonding where crash resistance and thermal cycling durability prove non-negotiable.
- Epoxy:Bisphenol-A and novolac resins in ketone or glycol ether solvents deliver exceptional chemical resistance and load-bearing strength. Construction projects in the Middle East and Southeast Asia specify epoxy adhesives for structural glazing and facade bonding exposed to extreme temperature fluctuations and UV degradation.
- Acrylic:Methyl methacrylate and cyanoacrylate solutions in ester solvents provide optical clarity and rapid fixture times for electronics assembly.
- Rubber:Natural and synthetic rubber elastomers in hydrocarbon solvents serve footwear manufacturing and general packaging applications where cost thresholds dominate procurement decisions.
Mature deployment sits with rubber-based formulations in legacy packaging and footwear operations. Newer deployment is concentrated in polyurethane systems for electric vehicle platform assembly.
End User:
Automotive and construction sectors drive specification-grade demand, while electronics and furniture segments operate on divergent margin and volume logic.
- Automotive:OEMs and Tier-1 suppliers specify solvent-borne polyurethane and epoxy systems for body-in-white assembly, interior trim bonding, and battery pack encapsulation. Lightweighting mandates for electric vehicle architectures are expanding adhesive bonding surface area per vehicle platform.
- Construction:Infrastructure contractors and facade engineers procure high-solids epoxy and polyurethane grades for structural glazing, panel bonding, and waterproofing membranes. Projects in climate-extreme zones specify these formulations where thermal expansion coefficients and moisture resistance exceed water-based alternatives.
- Electronics:Contract manufacturers in Shenzhen and Suzhou use acrylic solvent adhesives for display lamination, component potting, and thermal interface materials where optical clarity and dielectric properties carry specification weight.
- Furniture:Woodworking shops and furniture assemblers purchase rubber-based and polyurethane solvent systems for edge banding, veneer application, and frame assembly where open time and tack development speed determine line productivity.
Specification intensity clusters in automotive and construction procurement. Volume scale concentrates in furniture and electronics manufacturing.
Application:
Packaging and woodworking represent high-volume, price-competitive segments, whereas automotive assembly and footwear demand tailored formulation performance.
- Packaging:Flexible packaging converters employ rubber-based solvent adhesives for film-to-film lamination in snack and consumer goods wrapping. Migration to water-based and hot-melt alternatives is eroding this segment where moisture resistance requirements permit substitution.
- Woodworking:Furniture manufacturers and millwork operations use polyurethane and neoprene solvent systems for veneer pressing, edge banding, and assembly bonding. Formulation selection balances open time against green strength development for automated edge processing lines.
- Automotive Assembly:Structural bonding of dissimilar materials relies on solvent-borne polyurethane grades qualified by Volkswagen, BMW, and Chinese OEMs for crash-resistant joints. Application specifications include corrosion inhibition, vibration damping, and thermal stability across operating temperature ranges.
- Footwear:Athletic and fashion shoe manufacturers apply rubber-based solvent cements for upper-to-sole attachment and insole bonding. Cost pressures and VOC regulatory scrutiny in manufacturing clusters are accelerating migration to water-based and hot-melt alternatives.
Volume concentration persists in packaging and woodworking. Value capture and formulation innovation are expanding most quickly in automotive assembly applications.
Technology:
Solvent-based chemistry retains irreplaceable performance in high-stress bonding, while reactive and hot-melt systems capture regulatory-compliant niches.
- Hot Melt:Reactive polyurethane hot-melt hybrids combine initial solvent-carried tack with moisture-cured structural strength, reducing VOC emissions while maintaining handling properties competitive with traditional solvent-borne grades.
- Reactive:Two-component epoxy and polyurethane systems cure through chemical crosslinking rather than solvent evaporation, delivering structural integrity in applications where joint permanence and environmental resistance prove critical.
- Pressure Sensitive:Acrylic and rubber-based solvent formulations coated onto tapes and labels provide immediate tack and peel adhesion for temporary holding, masking, and protective film applications in electronics and automotive finishing operations.
- Solvent Based:Traditional solvent-borne systems achieve handling strength within minutes through solvent evaporation, serving industries where water-based alternatives fail on substrate compatibility, environmental durability, or rapid processing requirements.
Established manufacturing infrastructure favors solvent-based application equipment. Capital investment is redirecting toward reactive and hot-melt systems to satisfy tightening EPA and MEE emission thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China and India's industrial corridors are concentrating solvent-borne adhesive demand through tax-incentivized manufacturing clusters. Automotive lightweighting mandates and electronics assembly expansion are reshaping procurement patterns across four critical national markets.
China
Electric vehicle platform assembly and consumer electronics manufacturing dominate solvent-borne polyurethane consumption. MEE enforcement of VOC discharge permits is accelerating formulation compliance investments. Manufacturing clusters around Shenzhen and Suzhou specialize in display lamination adhesives for export-oriented contract manufacturers.
Germany
Automotive OEMs in Stuttgart and Munich specify solvent-borne systems for aluminum-to-composite structural bonding in EV architectures. REACH substance restrictions force parallel formulation tracks for domestic and export production. The Baden-Württemberg supply basin concentrates Tier-1 adhesive qualification activity.
United States
EPA NESHAP rules for hazardous air pollutants are forcing thermal oxidizer investments at Ohio and Texas manufacturing sites. Flexible packaging converters in the Midwest are migrating to water-based alternatives where specifications permit. Automotive collision repair channels represent underdeveloped aftermarket potential.
India
PLI scheme incentives for electronics manufacturing in Tamil Nadu and Gujarat are creating greenfield demand for industrial-grade bonding systems. BIS certification requirements shape import substitution strategies. Gujarat's Special Investment Regions attract adhesive formulators serving automotive assembly corridors.
Solvent-Borne Adhesives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-driven automotive and construction procurement favoring established multinational portfolios while commodity packaging applications tolerate regional formulators. The market structure concentrates around three strategic archetypes: integrated chemical conglomerates with captive resin supply, specialized adhesive pure-plays with formulation expertise, and diversified industrial manufacturers leveraging cross-selling infrastructure. Competitive moves center on geographic expansion through toll manufacturing partnerships and portfolio diversification into reactive hot-melt hybrids.
Within the integrated chemical tier, Henkel AG & Co. KGaA and Arkema Group exemplify multinational scale advantages, while H.B. Fuller occupies a position representing specialized formulation depth in industrial assembly applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller |
| Sika AG |
| Arkema Group |
| Avery Dennison Corporation |
| Huntsman Corporation |
| Illinois Tool Works Inc. |
| Jowat AG |
| Others |
Value Network & Pricing Analysis
Aromatic hydrocarbon index movements cascade through solvent-borne adhesive supply chains, compressing margins at formulators while concentrating pricing power with integrated resin producers in Germany and China. Contract structures stratify across automotive OEM annual agreements, construction project spot procurement, and electronics converter volume tiers.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to certified REACH-compliant formulations held in regional distribution centers, while spot inventory of standard rubber-based grades trades at discounts in oversupplied packaging corridors. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with ISO 9001 and IATF 16949 qualified products commanding sustained premiums. Cost compression in commodity rubber formulations is intensifying because water-based substitution erodes volume scale. Electronics contract manufacturers in Shenzhen exhibit least price sensitivity due to specification lock-in, while flexible packaging converters in the Midwest show highest elasticity where moisture resistance permits alternative chemistries.
Supply Chain Analysis
Reverse-logistics flows for solvent-borne adhesives remain underdeveloped, though automotive collision repair channels and building facade refurbishment operations create emerging collection nodes for expired or off-spec material. Manufacturing concentrates in China, Germany, and the United States, with China hosting 60 percent of global polyurethane prepolymer capacity. Feedstock chains draw from crude oil derivatives, natural gas liquids, and bio-based acetate esters. Single-source vulnerability sits with aromatic hydrocarbon suppliers in the US Gulf Coast. Distribution runs through regional chemical distributors, direct OEM supply agreements, and toll manufacturing partnerships serving mid-sized formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvent-borne adhesive supply is tightening around qualified formulation chemists and certified manufacturing assets, with capacity scarcity propping pricing power for incumbents holding dual REACH-EPA registrations.
For Market Incumbents: Anticipate water-based and reactive hot-melt substitution threats by deepening captive resin production in China and Germany, while accelerating certification investments for MEE-compliant low-VOC formulations to defend automotive OEM contract renewals against emerging Asian competitors. For New Entrants and Emerging Players: EPA NESHAP enforcement in the United States opens a window for toll manufacturing partnerships with distressed Ohio and Texas facilities lacking capital for thermal oxidizer upgrades. Target India's PLI-backed electronics manufacturing clusters in Tamil Nadu and Gujarat, where BIS certification requirements create qualification barriers favoring agile local formulators. Lead with fast-curing solvent adhesive kits for aftermarket automotive collision repair, an underdeveloped channel with fragmented incumbent presence. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized German formulators in Baden-Württemberg facing REACH authorization bottlenecks for legacy solvent chemistries. Long-term viability hinges on portfolio migration toward exempt compounds under EPA Method 24 and reactive hot-melt hybrids. Monitor ECHA substance restriction list updates for early signals of which solvent chemistries face phasedown versus retained market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Prepolymer Production | Henkel and Arkema's captive resin supply secures margin control against aromatic hydrocarbon volatility. |
| Low-VOC Solvent Innovation Program | Acetate ester and siloxane formulations exempt under EPA Method 24 preserve automotive OEM qualification pathways. |
| Toll Manufacturing Partnership Expansion | Ohio and Texas consolidations allow small formulators to bypass NESHAP capital requirements through compliant third-party production. |
| Reactive Hot-Melt Hybrid Platform Launch | Moisture-cured polyurethane systems reduce VOC emissions while matching solvent-borne handling speeds for interior trim applications. |
| India Industrial Corridor Market Entry | PLI scheme incentives in Tamil Nadu and Gujarat create certified demand for electronics and automotive bonding systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with adhesive plant managers, automotive Tier 1 procurement leads, construction project engineers, and distribution channel partners. Bottom-up modeling triangulated formulation-grade production volumes against top-down end-use consumption patterns derived from ACC, Cefic, and VCI chemical industry reports, SEC 10-K disclosures from listed suppliers, and MEE VOC discharge permit databases.
Granularity-level modeling segmented the market by polyurethane, epoxy, acrylic, and rubber chemistries; automotive, construction, electronics, and furniture end-uses; and China, Germany, United States, and India demand clusters. CAGRs were derived from elasticity-adjusted volume projections and value-per-kilogram trends across the analysis window. Forecast inputs incorporated electric vehicle platform expansion rates, REACH substance authorization timelines, and MEE enforcement intensity indices.
The model assumes a particular technology adoption path; alternative pathways for water-based and UV-curable substitution would alter the outlook for solvent-borne volume retention. Forecasts reflect assumptions about regulatory enforcement continuity, feedstock price correlation patterns, and OEM qualification cycle durations. Practitioners should monitor ECHA authorization list revisions, EPA NESHAP implementation guidance, and MEE permit denial rates for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Firestop Sealants Market