
 Europe Polyurethane (PU) Hot-Melt Adhesives Market | 2026-2036
Europe Polyurethane (PU) Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyurethane (PU) Hot-Melt Adhesives Market Foresight
Technical support and formulation customization is repositioning how adhesive suppliers capture value in European industrial channels. Henkel AG & Co KGaA leverages its application laboratories across Düsseldorf and Vienna to embed chemists directly at customer production lines. Sika AG anchors its position through deep specialization in automotive bonding protocols for lightweight multi-material assemblies. Arkema Group competes by controlling upstream polyol supply chains that feed its reactive hot-melt grades.
Europe polyurethane hot-melt adhesives are thermoplastic or reactive systems formulated from isocyanate-terminated prepolymers that cure through atmospheric moisture to form durable elastomeric bonds, typically applied at temperatures between 120°C and 140°C for industrial assembly, lamination, and structural joining. Waterproof grades command premium positioning in outdoor textile and marine applications where moisture resistance determines product lifespan. Fast bonding variants are gaining share in automated packaging lines across the Netherlands and Belgium where cycle-time compression drives equipment specification. Reactive systems carry higher formulation complexity but deliver superior heat resistance for automotive underhood and woodworking edgebanding segments.
EMA chemical substance evaluations, REACH authorization requirements, and the EU F-Gas Regulation collectively constrain solvent-based adhesive formulations while accelerating demand for thermoplastic and hot-melt extrusion alternatives with lower emission profiles. ECHA substance-of-very-high-concern listings for certain isocyanate precursors are forcing reformulation investments that favor suppliers with captive R&D infrastructure. Stakeholders must monitor evolving CLP hazard classifications and prepare technical dossiers ahead of anticipated restriction proposals that could reshape raw material sourcing across the value chain.
Market Dynamics
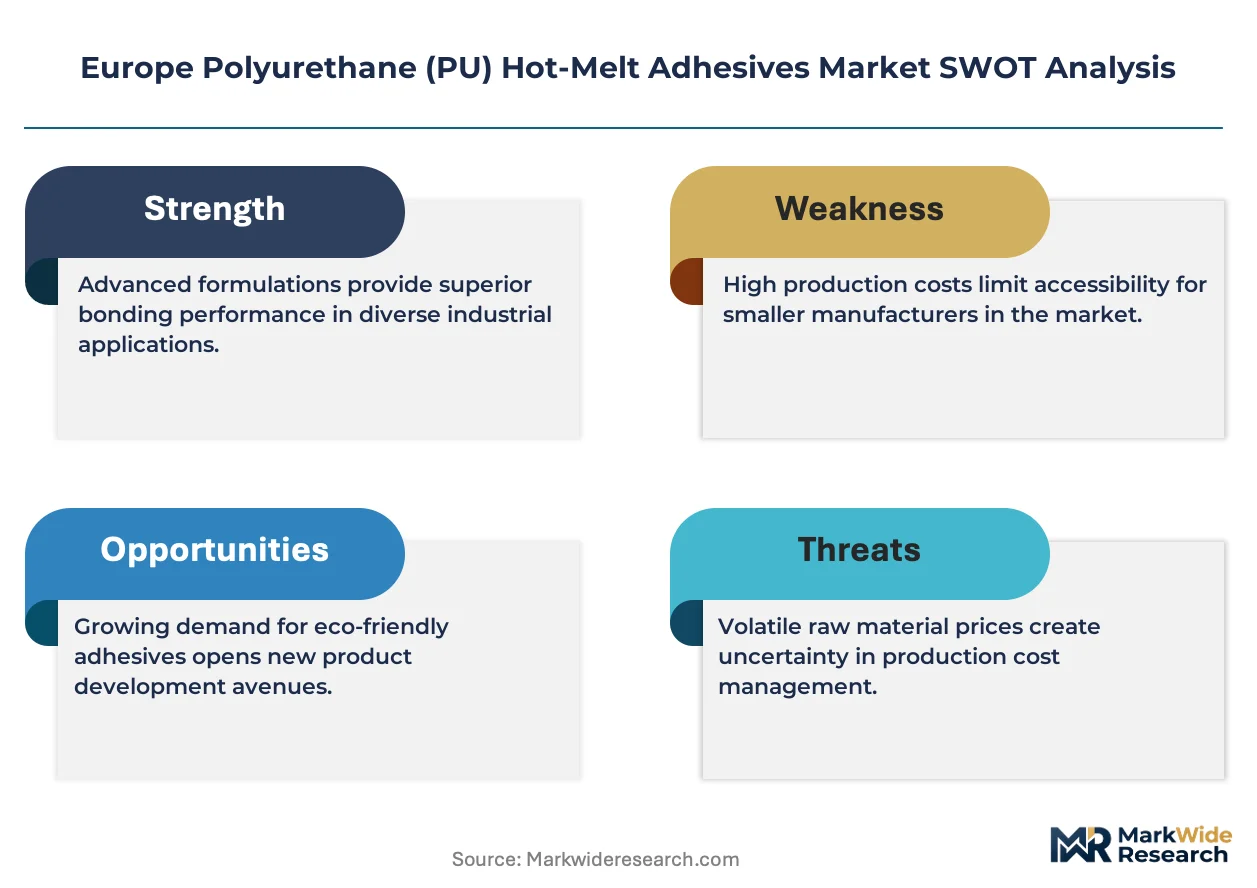
REACH chemical safety standards and the EU Green Deal are forcing adhesive formulators to eliminate volatile-organic-compound emissions while maintaining bond performance, compressing development cycles and rewarding suppliers with captive R&D infrastructure.
Growth Catalysts
- Automotive lightweighting mandates:German and French assembly lines are expanding bonded-component designs to replace mechanical fasteners, directly consuming moisture-curing reactive systems.
- ECHA substance-of-very-high-concern listings:Restrictions on legacy isocyanate precursors are accelerating reformulation investments that favor thermoplastic and hot-melt extrusion alternatives.
- Waterproof grade demand:Outdoor textile and marine applications across Nordic coastal economies command premium positioning where moisture resistance determines product lifespan.
Market Restraints
- Raw material concentration:Polyol and isocyanate feedstock supply clusters in the Rhine-Ruhr industrial corridor create geographic vulnerability to logistics disruptions.
- Technical heat resistance ceiling:Standard thermoplastic formulations fail above 80°C, limiting penetration in automotive underhood segments without reactive system upgrades.
- CLP hazard classification friction:Evolving hazard classifications for isocyanate-containing products extend technical dossier preparation timelines and delay market entry.
Strategic Opportunities
- Polish industrial corridor expansion:Woodworking machinery OEMs in Lower Silesia are sourcing specialized reactive systems as domestic furniture production scales.
- EU F-Gas Regulation tailwind:Solvent-based adhesive phase-outs are creating substitution demand for thermoplastic hot-melt extrusion in packaging lamination.
- Smart factory integration:Automated dispensing systems with real-time viscosity monitoring are converging with Industry 4.0 protocols in Dutch packaging lines.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in moisture-cure kinetics and polyol-isocyanate stoichiometry is concentrated among aging technical workforces in Germany and Austria.
- REACH authorization timelines:Technical dossier preparation for novel prepolymer chemistries extends 18-24 months, compressing product development windows.
- Legacy equipment retrofit costs:Existing hot-melt applicators in Italian woodworking clusters require heated-hose upgrades to handle higher-viscosity reactive grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyurethane (PU) Hot-Melt Adhesives Market |
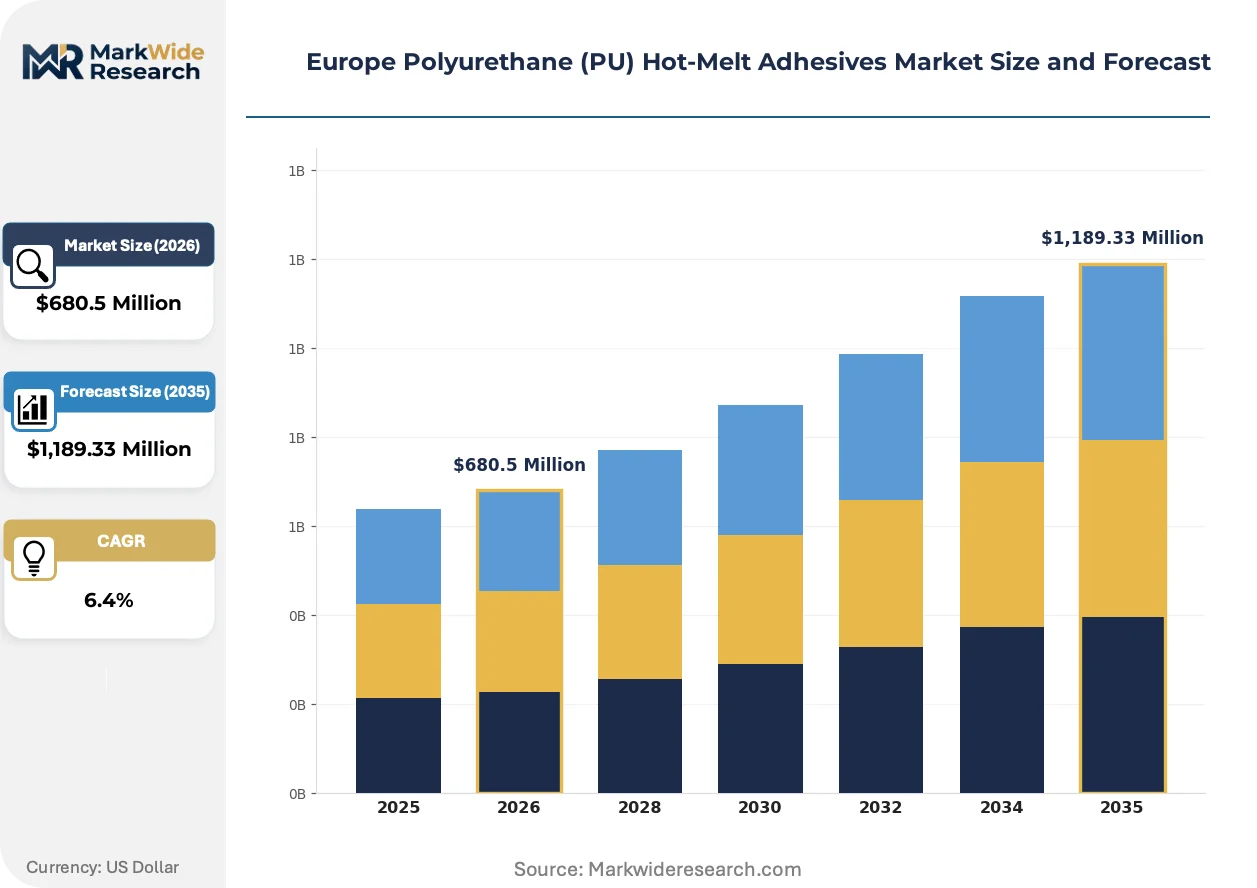
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,189.33 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterproof, Low Temperature, High Viscosity, Fast Bonding Application: Packaging, Automotive, Textile, Woodworking End User: Manufacturers, Contractors, Retailers, Distributors Technology: Hot Melt Extrusion, Thermoplastic, Reactive Systems, Solvent Based |
| Companies Covered | Bostik, Sika AG, Henkel AG & Co KGaA, Huntsman Corporation LLC, Arkema Group, H B Fuller Company, Jowat SE, Paramelt BV, 3M, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyurethane (PU) Hot-Melt Adhesives Market Shifts & Advancements
Moisture-curing reactive systems are compressing the performance gap between thermoplastic convenience and structural durability, reshaping equipment specifications and supplier technical service models across European industrial channels.
Bio-based polyol feedstocks derived from rapeseed and castor oil are unifying sustainability credentials with performance parity in woodworking edgebanding applications. Austrian furniture manufacturers are specifying these grades for export markets requiring renewable content documentation. This unifying trend is collapsing the traditional premium gap between petrochemical and bio-based formulations.
REACH authorization requirements and the EU F-Gas Regulation are systematically constraining solvent-based adhesive formulations across industrial lamination segments. EMA chemical substance evaluations are accelerating demand for thermoplastic and hot-melt extrusion alternatives with verified emission profiles. Automotive interior lamination in Stuttgart and Wolfsburg production clusters is most affected, with Tier 1 suppliers restructuring formulation portfolios ahead of anticipated restriction proposals.
Buyer concentration among German packaging machinery OEMs is compressing supplier qualification cycles and unbundling technical support from material supply contracts. Equipment specification decisions in the Netherlands and Belgium now precede adhesive selection, reversing traditional procurement sequences. This pattern is most visible in automated food packaging lines where cycle-time performance guarantees determine vendor selection.
Europe Polyurethane (PU) Hot-Melt Adhesives Market Segmentation
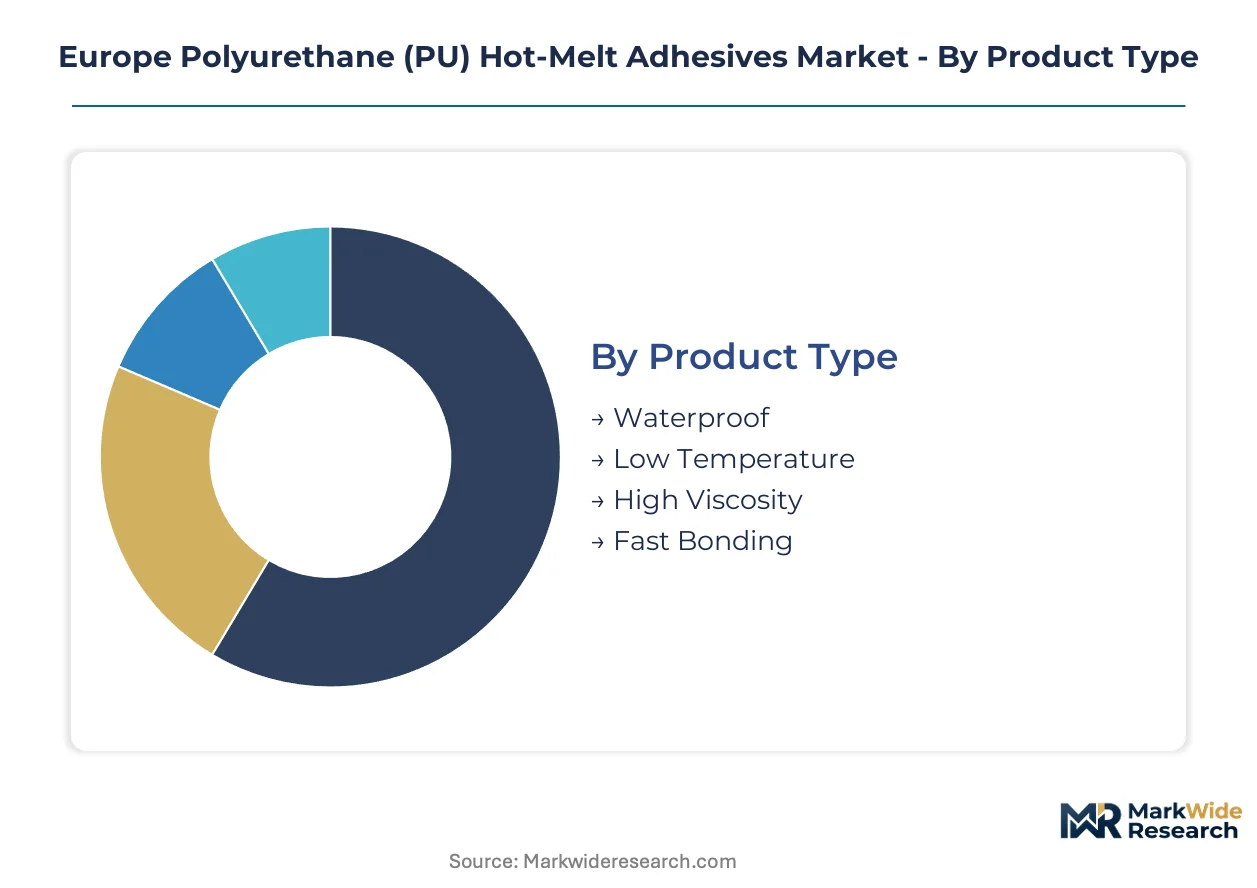
European polyurethane hot-melt adhesive procurement patterns diverge sharply between standalone material supply and integrated system contracts, with equipment specification increasingly preceding chemical selection. Formulators now compete on application engineering depth rather than commodity chemistry alone.
Product Type:
Waterproof grades operate as standalone specialty products commanding specification premiums, while fast-bonding variants embed directly into automated packaging line integrations where cycle-time guarantees dominate vendor selection.
- Waterproof:Formulated with hydrophobic polyol backbones and enhanced crosslink density for marine textile and outdoor furniture applications. Nordic coastal manufacturers in Denmark and Norway specify these grades for export contracts requiring moisture-resistance certification.
- Fast Bonding:Engineered with accelerated moisture-cure kinetics for high-speed automated lines. Dutch food packaging OEMs in Eindhoven and Venlo embed these systems into equipment performance guarantees, reversing traditional procurement sequences.
- Low Temperature:Modified prepolymer formulations enabling application at 90-110°C for heat-sensitive substrates.
- High Viscosity:Thixotropic grades for vertical surface bonding and gap-filling in structural assembly.
Waterproof leads volumes today; fast bonding is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive automotive bonding protocols from volume-driven packaging lamination, with margin structures diverging by technical service intensity.
- Automotive:Reactive systems for multi-material lightweighting in German assembly plants. Stuttgart and Wolfsburg production clusters specify moisture-curing grades for aluminum-to-composite joints, with bond-line failure modes determining Tier 1 supplier qualification.
- Packaging:Thermoplastic extrusion for high-speed lamination across Belgian and Dutch converting lines. Cycle-time compression drives equipment specification decisions that precede adhesive selection.
- Textile:Waterproof grades for outdoor apparel and marine upholstery in Scandinavian markets.
- Woodworking:Edgebanding and panel lamination for Austrian and Polish furniture manufacturing corridors.
Packaging commands the widest volume base; automotive delivers the steepest expansion trajectory.
End User:
Customer type determines contract structure, with manufacturers integrating technical support into long-term supply agreements while distributors compete on formulation availability and logistics reach.
- Manufacturers:Direct procurement with embedded application engineering for automotive and woodworking sectors. German industrial corridors demand on-site chemist placement and real-time viscosity monitoring integration.
- Contractors:Project-based purchasing for construction and marine assembly with specification-driven grade selection.
- Distributors:Stocking intermediaries serving fragmented Italian and Spanish woodworking clusters with standard thermoplastic grades.
- Retailers:Small-format packaging for maintenance and repair segments across hardware channels.
Manufacturers anchor revenue concentration today; distributors are expanding share most quickly through technical service bundling.
Technology:
Maturity gradients separate established thermoplastic extrusion from emerging reactive system adoption, with regulatory pressure accelerating displacement timelines for legacy solvent formulations.
- Reactive Systems:Moisture-curing prepolymers forming permanent elastomeric bonds with superior heat resistance. REACH authorization constraints on isocyanate precursors favor suppliers with captive R&D infrastructure for reformulation investment.
- Thermoplastic:Reversible physical curing enabling reprocessing and equipment cleaning. Standard formulations dominate packaging lamination where 80°C service temperature limits are acceptable.
- Hot Melt Extrusion:Continuous application systems with real-time viscosity control converging with Industry 4.0 protocols in Dutch automated lines.
- Solvent Based:Legacy formulations facing systematic phase-out under EU F-Gas Regulation and EMA chemical substance evaluations.
Thermoplastic leads installed base today; reactive systems are climbing the fastest as automotive lightweighting mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands formulation expertise density unmatched elsewhere, while Poland absorbs capacity spillover from western supply chains. French automotive clusters drive reactive system qualification protocols. Regulatory divergence between REACH enforcement zones and candidate member states reshapes cross-border procurement patterns.
Germany
Stuttgart and Wolfsburg automotive clusters specify moisture-curing reactive systems for aluminum-to-composite bonding in electric vehicle platforms. REACH authorization timelines from ECHA compress 18-24 month reformulation windows for isocyanate precursors. The Rhine-Ruhr industrial corridor concentrates polyol and isocyanate feedstock supply, creating geographic vulnerability to logistics disruptions.
France
Paris Basin packaging converters demand fast-bonding grades for high-speed lamination lines serving export markets. The EU Green Deal's volatile-organic-compound limits tighten faster than neighboring jurisdictions, forcing accelerated solvent-based phase-outs. Lyon textile manufacturers specify waterproof grades for marine upholstery bound for Nordic coastal economies.
Poland
Lower Silesia woodworking machinery OEMs source specialized reactive systems as domestic furniture production scales for German retail channels. Candidate country status delays full REACH enforcement, creating temporary formulation flexibility. Katowice industrial corridors attract adhesive distributors serving fragmented Italian and Spanish woodworking clusters.
Netherlands
Eindhoven and Venlo automated food packaging lines embed adhesive performance into equipment specification contracts, reversing traditional procurement sequences. EU F-Gas Regulation enforcement accelerates solvent-based adhesive substitution in lamination segments. Rotterdam chemical handling infrastructure supports bulk thermoplastic hot-melt extrusion imports for Benelux converting operations.
Austria
Vienna application laboratories embed chemists directly at customer production lines for woodworking edgebanding technical support. Alpine furniture manufacturers specify bio-based polyol grades from rapeseed and castor oil for renewable content documentation. Upper Austrian industrial zones concentrate moisture-cure kinetics expertise among aging technical workforces.
Europe Polyurethane (PU) Hot-Melt Adhesives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive bonding protocols favoring integrated technical service providers while packaging lamination rewards scale-driven extrusion suppliers. Three strategic archetypes dominate: formulation specialists with captive R&D infrastructure, regional distributors bundling logistics reach with application support, and chemical conglomerates controlling upstream polyol supply chains. Consolidation pressure concentrates among mid-tier players lacking REACH authorization capabilities. Competitive moves center on backward integration into prepolymer production and geographic expansion into Polish industrial corridors.
Among German-anchored diversified chemical groups, Henkel AG & Co KGaA and Sika AG occupy positions exemplifying the technical-embedding archetype, with application laboratory networks representing substantial competitive moats. Arkema Group sits within the upstream-control tier, with polyol supply chain positioning supporting reactive grade formulation flexibility. These three structures illustrate how European polyurethane hot-melt adhesive competition stratifies by R&D infrastructure depth rather than commodity chemistry scale alone.
| Leading Market Players |
|---|
| Bostik |
| Sika AG |
| Henkel AG & Co KGaA |
| Huntsman Corporation LLC |
| Arkema Group |
| H B Fuller Company |
| Jowat SE |
| Paramelt BV |
| 3M |
| Others |
Supply & Pricing Matrix
Reactive-grade certification tiers bifurcate procurement economics between automotive bonding protocols and commodity packaging lamination, compressing margin structures in standard thermoplastic segments while concentrating pricing power among suppliers with captive R&D infrastructure for REACH-compliant reformulation. This tier divergence maps directly onto supply chain geography: premium reactive systems draw from Rhine-Ruhr polyol clusters with integrated isocyanate supply, whereas commodity grades source through Rotterdam bulk handling terminals serving Benelux converting lines.
Pricing Analysis
Capacity additions in Poland are reshaping price floors for standard thermoplastic grades, forcing incumbent German suppliers to bundle technical service into material contracts to defend positioning. Three-tier pricing structure across premium reactive, standard thermoplastic, and economy solvent-transition grades reflects certification burden and formulation complexity. Cost compression in commodity packaging segments intensifies because Dutch OEMs now specify adhesive performance within equipment procurement cycles, reversing traditional supplier selection sequences. Automotive Tier 1s show least price sensitivity due to bond-line failure liability exposure, while Italian woodworking distributors compete primarily on per-kilogram unit economics.
Supply Chain Analysis
Refurbishment flows for hot-melt applicator equipment create secondary material demand channels across German and Austrian woodworking clusters, extending effective supply chain reach beyond primary chemical distribution. Polyol and isocyanate feedstock supply concentrates in Germany, Belgium, and the Netherlands, with Rotterdam chemical terminals anchoring bulk thermoplastic imports for Benelux converting operations. Formulation rests on rapeseed-derived bio-polyol availability from Upper Austrian agricultural processing and castor oil feedstock from Spanish cultivation regions. Single-source vulnerability to ECHA substance-of-very-high-concern listings for legacy isocyanate precursors threatens reformulation timelines. Distribution runs through regional distributors serving fragmented Southern European woodworking markets and direct technical service contracts for German automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe polyurethane hot-melt adhesives constitute a late-cycle quality story as REACH enforcement and automotive lightweighting mandates shift procurement criteria toward certified reactive systems with embedded technical support. Premium specification demand from Stuttgart and Wolfsburg electric vehicle platforms now precedes commodity volume considerations in supplier qualification protocols.
For Market Incumbents: Lock in automotive bonding protocol certification through on-site chemist placement at Wolfsburg and Stuttgart production clusters, insulating positioning from emerging Polish capacity additions in standard thermoplastic grades. Deepen backward integration into prepolymer production to compress reformulation cycles for anticipated ECHA restriction proposals on isocyanate precursors. Channel control through equipment specification partnerships with Dutch packaging machinery OEMs represents the critical defensive lever against price erosion in commodity segments.
For New Entrants and Emerging Players: Begin with bio-based polyol formulation for Austrian furniture manufacturing corridors, where renewable content documentation commands specification premiums and incumbent technical service density remains lowest. Polish Lower Silesia woodworking machinery OEMs present the most penetrable geography given candidate-country REACH flexibility and scaling domestic production for German retail channels. A technical service bundling go-to-market angle—embedding application engineering into material supply contracts—sidesteps direct commodity price competition with established Rhine-Ruhr suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier players lack captive R&D infrastructure for REACH authorization timelines, creating acquisition targets among regional distributors with technical service relationships but insufficient reformulation capabilities. Five-to-ten year viability favors suppliers controlling upstream polyol supply chains or owning application laboratory networks. The signal to watch is ECHA substance-of-very-high-concern listing velocity for isocyanate precursors, which would accelerate displacement of legacy formulators unable to fund 18-24 month technical dossier preparation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prepolymer Production | Captive supply of isocyanate-terminated feedstocks compresses reformulation cycles for REACH compliance. |
| Application Laboratory Network Expansion | On-site chemist placement at German automotive clusters embeds technical service into long-term supply agreements. |
| Bio-Based Polyol Formulation Investment | Rapeseed and castor oil feedstocks satisfy Austrian furniture export requirements for renewable content documentation. |
| Equipment Specification Partnerships | Dutch packaging machinery OEMs now precede adhesive selection in procurement sequences, reversing traditional vendor qualification. |
| Polish Industrial Corridor Capacity Buildout | Lower Silesia woodworking machinery growth absorbs spillover demand from German retail channel expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with formulation chemists, automotive Tier 1 procurement leads, woodworking machinery OEM technical directors, and distribution channel partners with secondary validation against ECHA substance registration databases, EU customs trade flows for polyol and isocyanate feedstocks, and SEC filings from listed chemical conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for European industrial production and automotive assembly output.
Segment-weighting approaches distributed value and volume projections across reactive system, thermoplastic, and solvent-transition technology tiers, further disaggregated by automotive, packaging, textile, and woodworking end-use applications. CAGRs derived from elasticity-adjusted demand modeling incorporating regulatory phase-out timelines for solvent-based formulations and automotive lightweighting content-per-vehicle trajectories. Industry-specific forecast inputs included EMA chemical substance evaluation schedules and EU F-Gas Regulation enforcement intensity assumptions.
Several conditions sit outside the modeled scope, including unannounced ECHA restriction proposals, abrupt logistics disruptions in Rhine-Ruhr chemical corridors, and faster-than-anticipated bio-polyol feedstock cost parity achievements. Forecasts reflect documented assumptions regarding REACH authorization timeline stability and automotive platform electrification cadence. Practitioners should monitor ECHA substance-of-very-high-concern listing announcements and German automotive production cluster bond-line specification changes for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Russia Adhesives Market