
 Fabric Glue Market | 2026-2036
Fabric Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Glue Market Analysis
Buyer concentration in the fabric glue supply chain is rebalancing as mass-market retailers and e-commerce platforms consolidate procurement volumes while independent craft stores fragment into specialized niches. Henkel AG & Co. KGaA leverages its European manufacturing footprint to serve industrial textile clients with consistent quality. H.B. Fuller Company anchors its position through deep relationships with apparel manufacturers seeking durable bonding solutions. Pidilite Industries Ltd dominates the South Asian consumer segment with localized branding and distribution density.
Fabric glue comprises synthetic or natural polymer formulations designed to create flexible, wash-resistant bonds between textile substrates without stitching, typically curing through evaporation, thermal activation, or pressure-sensitive contact. Water-based acrylic and polyurethane dispersions dominate industrial applications due to low volatile organic compound profiles and compatibility with automated coating equipment. Solvent-based formulations retain share in high-performance textile lamination where rapid tack development and moisture resistance justify stricter handling protocols. Hot melt adhesives gain ground in fashion design workflows for temporary positioning and embellishment attachment where repositionability before final cure adds operational value.
EPA regulations in the United States restrict formaldehyde emissions from adhesive formulations used in consumer textile goods, compelling suppliers to certify reformulated products through third-party testing. REACH registration requirements in Europe mandate full substance disclosure for imported adhesive chemistries, creating compliance barriers for non-EU manufacturers without in-house toxicology resources. ISO 10993 biocompatibility standards influence medical textile applications where skin-contact adhesives require cytotoxicity validation. Stakeholders must monitor evolving chemical restriction lists across multiple jurisdictions to anticipate reformulation costs and secure continued market access.
Market Dynamics
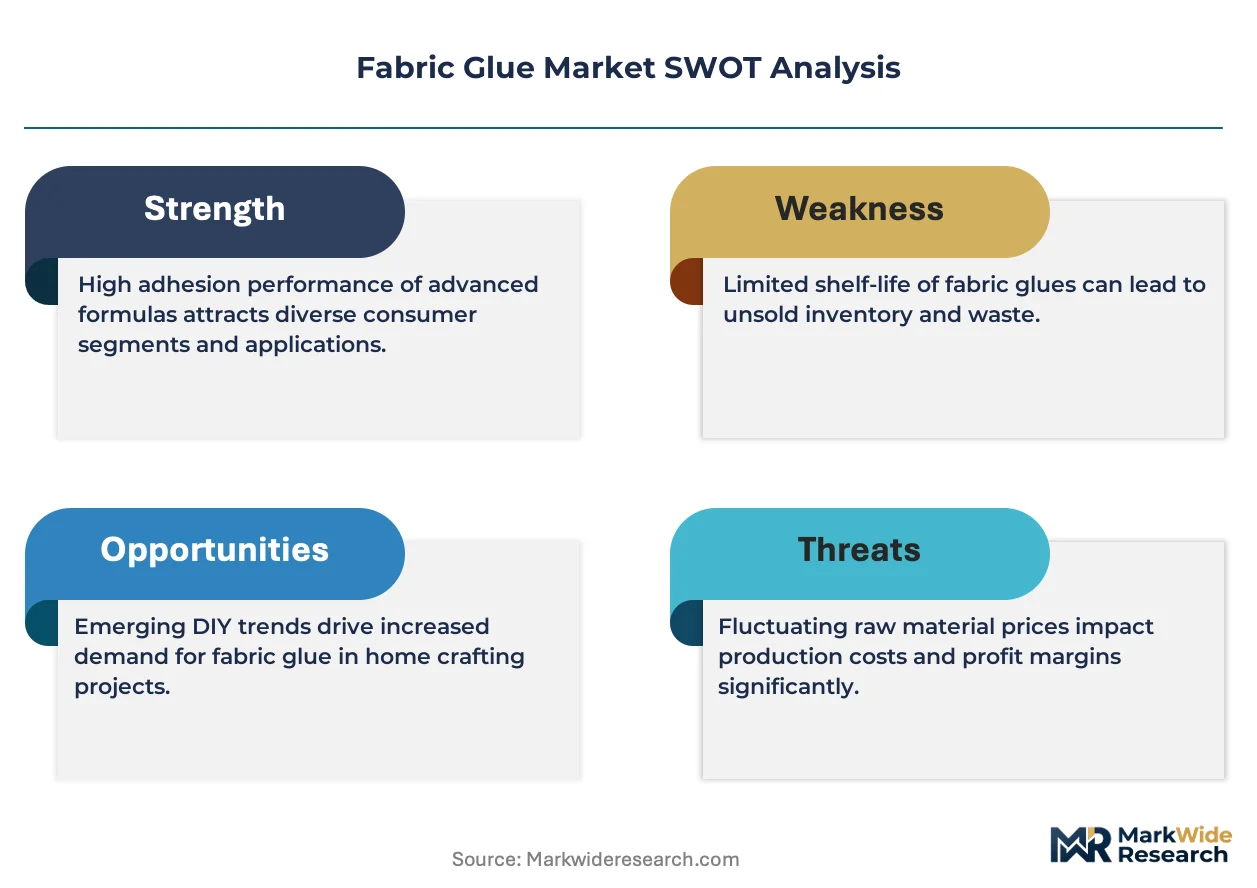
REACH compliance in Europe is forcing wholesale reformulation of solvent-based fabric adhesives toward water-based and bio-derived chemistries, compressing margins for suppliers lacking in-house toxicology capabilities while creating first-mover advantages for compliant manufacturers.
Growth Catalysts
- Textile Manufacturing Scale-Up:Domestic apparel production in China consumes industrial-grade fabric adhesives for automated bonding lines. Local brands prioritize cost-competitive bonding solutions over imported alternatives.
- EPA Formaldehyde Restrictions:Emission limits on consumer textile goods in the United States accelerate certification demand for third-party-tested reformulations. Suppliers with pre-validated portfolios capture shelf space at mass-market retailers.
- Hot Melt Workflow Integration:Fashion designers adopt repositionable hot melt systems for temporary embellishment placement. Operational flexibility before final cure reduces material waste in sample production.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane dispersion costs fluctuate with crude oil derivatives. Formulators lack pricing power to pass input swings to consolidated retail buyers.
- Specialized Equipment Capex:Automated coating lines for water-based systems require thermal drying infrastructure. Small-batch craft suppliers face barrier-to-entry against industrial-scale competitors.
- Skin-Contact Substitution:Medical textile applications increasingly specify silicone pressure-sensitive adhesives. ISO 10993 cytotoxicity validation costs disadvantage generalist fabric glue suppliers.
Strategic Opportunities
- DIY Channel Digitization:E-commerce platforms aggregate fragmented home crafter demand. Direct-to-consumer subscription models for adhesive replenishment bypass wholesale markups.
- EU Green Deal Alignment:Bio-based raw material mandates create procurement preference for renewable-content formulations. Early certifiers access public tender pools for institutional textile contracts.
- Wearable Electronics Integration:Conductive fabric adhesives bond sensor arrays to smart garments. Electronics manufacturers seek bonding partners with stretch-cycle durability expertise.
Industry Challenges
- Reformulation Talent Scarcity:Polymer chemists with REACH dossier experience command premium compensation. Smaller suppliers lose personnel to multinationals with dedicated regulatory affairs divisions.
- Legacy System Interoperability:Water-based adhesive viscosity profiles conflict with existing solvent-optimized coating equipment. Capital-intensive line retrofits delay conversion timelines for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Glue Market |
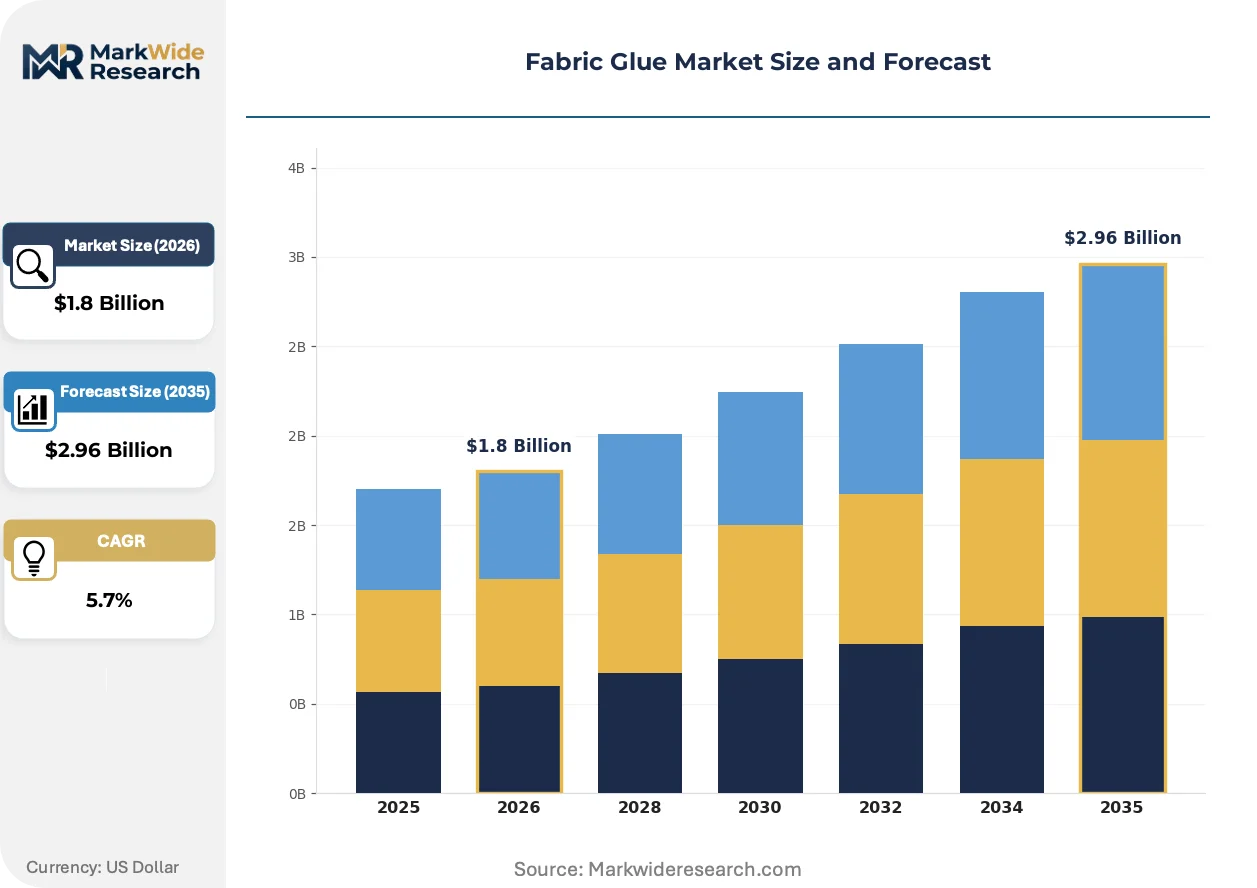
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Pressure Sensitive Application: Textile Industry, Crafting, Home Improvement, Fashion Design End User: Consumers, Manufacturers, DIY Enthusiasts, Retailers Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema, 3M, Pidilite Industries Ltd, Beacon Adhesives, Inc, Gutermann GmbH, Permatex, Inc., Nan Pao Resins Chemical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Glue Market Emerging Trajectories
Active chemistry platforms and application methods are diverging across industrial and consumer segments, with automation compatibility and sustainability credentials becoming primary selection criteria rather than secondary specifications.
UV-curable polyurethane dispersions are consolidating position in high-speed textile lamination lines. Automotive interior suppliers adopt these systems for zero-VOC bonding of seat fabrics to foam substrates. The technology is compressing cure-cycle times from minutes to seconds, enabling continuous-roll processing previously incompatible with adhesive-based assembly.
REACH substance disclosure requirements are tightening import barriers for non-EU adhesive manufacturers. Full toxicology dossier preparation demands six-figure euro investments per substance. Asian exporters without European legal entity structures are ceding share to regional formulators with in-house registration capabilities.
Home crafters increasingly source adhesives through platform-aggregated marketplaces rather than specialty retail. Amazon and Alibaba consolidate discovery and comparison shopping for water-based fabric glues. This channel rotation is most visible in Germany and the United Kingdom, where DIY project content creators drive purchase intent through tutorial-linked affiliate commerce.
Fabric Glue Market Segmentation
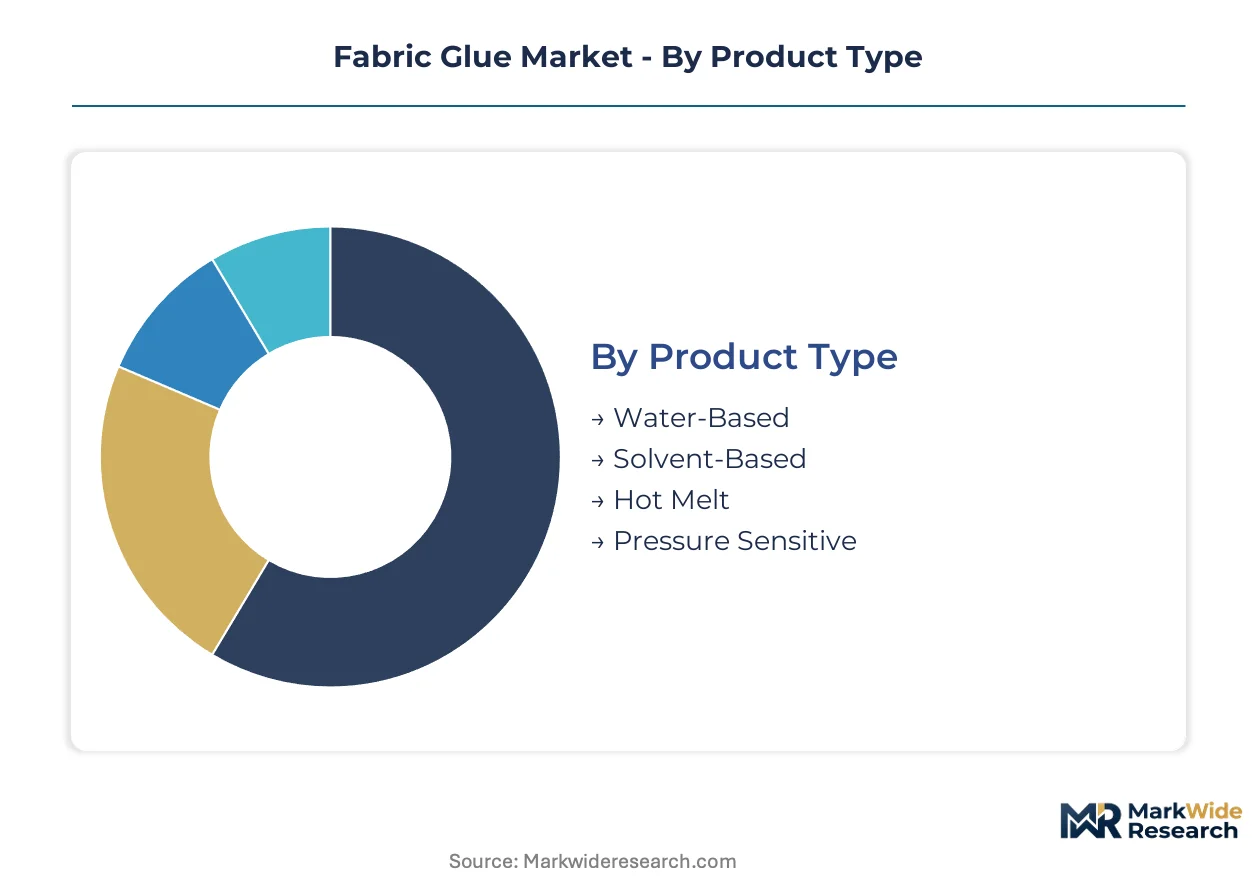
Segmentation in fabric adhesives separates industrial procurement from consumer purchasing behaviors, with formulation chemistry and distribution channel creating distinct margin profiles. Understanding these divides reveals where capital deployment yields differential returns.
Product Type:
Supply concentration in acrylic and polyurethane dispersions determines which chemistries achieve cost-competitive scale across automated coating lines.
- Water-Based:Acrylic and polyurethane dispersions cure through thermal evaporation, delivering low-VOC profiles compatible with continuous-roll textile processing. Demand concentrates in Chinese apparel manufacturing where automated bonding lines prioritize emission-compliant formulations. REACH dossier preparation costs disadvantage smaller formulators lacking European legal entities.
- Solvent-Based:Rapid tack development and moisture resistance justify continued use in high-performance textile lamination despite stricter handling protocols. Automotive interior suppliers in Germany specify these systems for seat fabric-to-foam bonding where cure speed outweighs regulatory burden.
- Hot Melt:Thermoplastic formulations enable repositionability before final cure, reducing material waste in fashion design sample production. Operational flexibility drives adoption among Milan and Paris atelier workflows.
- Pressure Sensitive:Silicone and acrylic variants bond sensor arrays to smart garments for wearable electronics integration. ISO 10993 cytotoxicity validation requirements limit supplier participation in medical textile applications.
Today's leader: Water-Based. Tomorrow's challenger: Pressure Sensitive.
Application:
Cost tier separation between industrial-scale bonding and small-batch craft consumption creates divergent pricing power across application segments.
- Textile Industry:Automated coating lines in Chinese and Vietnamese apparel manufacturing consume industrial-grade adhesives by the ton. Volume concentration with consolidated manufacturers compresses margins for non-integrated suppliers.
- Crafting:DIY enthusiasts and home crafters purchase water-based formulations through platform-aggregated marketplaces. Amazon and Alibaba consolidate discovery, bypassing traditional specialty retail markups in Germany and the United Kingdom.
- Home Improvement:Upholstery repair and decorative fabric bonding demand convenient, low-odor formulations. Shelf space competition at mass-market retailers favors suppliers with pre-validated EPA-compliant portfolios.
- Fashion Design:Temporary embellishment placement and sample prototyping require repositionable systems. Hot melt workflow integration reduces material waste in pre-production stages across European design houses.
Volume concentrates in Textile Industry. Margin expansion potential sits with Fashion Design.
End User:
Customer type fragmentation separates specification-driven industrial procurement from impulse-driven consumer purchasing, with distinct channel and marketing requirements.
- Consumers:Individual purchasers prioritize convenience, low odor, and wash resistance for household textile repairs. E-commerce subscription models for adhesive replenishment capture recurring revenue without wholesale intermediaries.
- Manufacturers:Apparel and automotive textile producers specify adhesives for automated bonding lines. Technical service relationships and formulation customization secure multi-year supply agreements.
- DIY Enthusiasts:Project-oriented crafters respond to tutorial-linked affiliate commerce from content creators. Platform algorithms drive discovery more than brand loyalty in this segment.
- Retailers:Mass-market chains and specialty stores consolidate procurement volumes, extracting favorable terms through private-label sourcing. Compliance certification requirements filter supplier eligibility.
Manufacturers anchor revenue stability. DIY Enthusiasts offer the steepest expansion trajectory through digital channel migration.
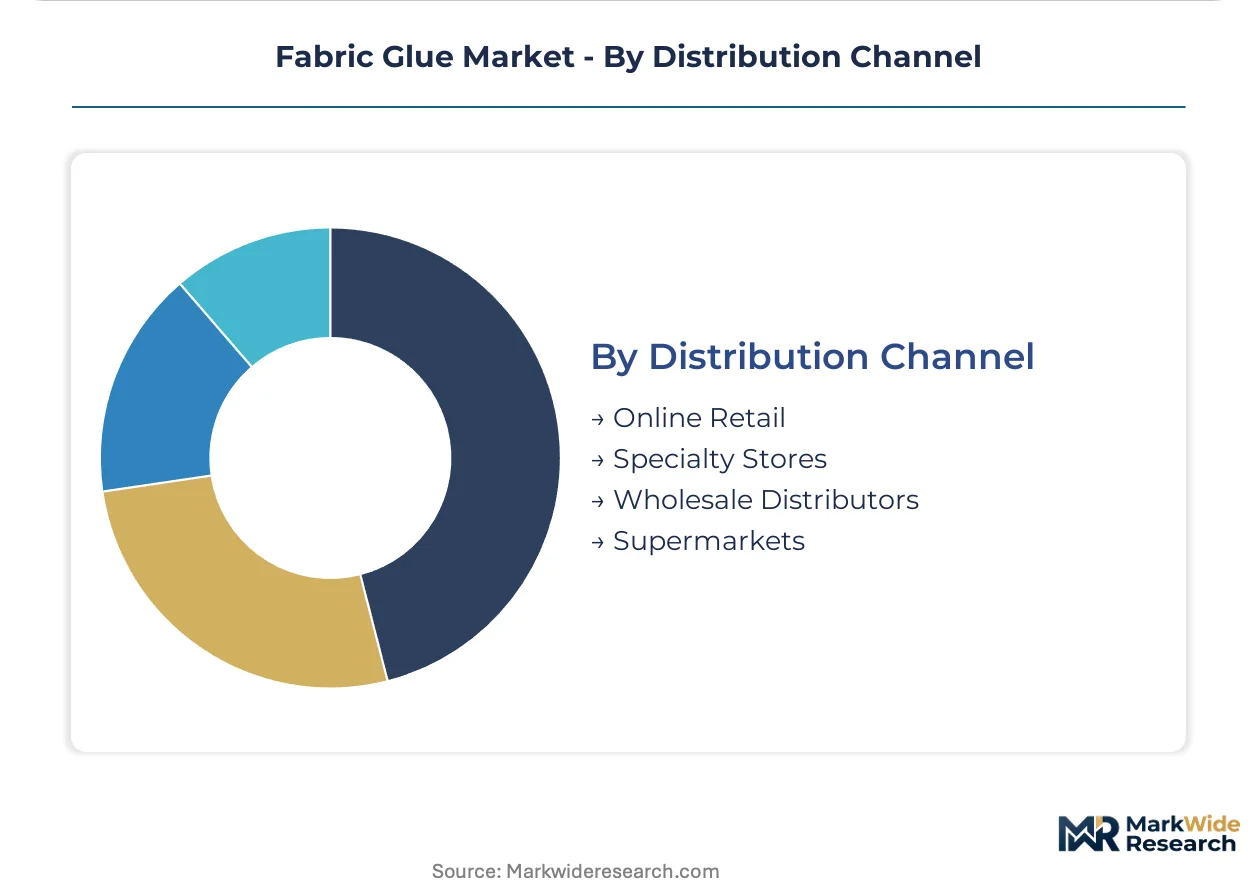
Distribution Channel:
Channel geography determines regulatory exposure and margin capture, with cross-border e-commerce creating compliance complexity for non-EU suppliers.
- Online Retail:Amazon, Alibaba, and specialty adhesive platforms aggregate fragmented demand across geographies. REACH substance disclosure requirements tighten import barriers for Asian exporters lacking European legal structures.
- Specialty Stores:Independent craft retailers fragment into niche segments serving professional designers and serious hobbyists. Personalized technical advice justifies price premiums over mass-market alternatives.
- Wholesale Distributors:Industrial textile manufacturers source through regional distributors with inventory and technical service capabilities. Consolidation among distributors reduces supplier negotiating leverage.
- Supermarkets:Mass-market placement requires EPA-compliant formulations with third-party certification. Shelf space scarcity favors suppliers with established retail relationships and marketing investment capacity.
Online Retail captures volume growth. Specialty Stores defend margin through service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's textile manufacturing scale dwarfs Germany's precision lamination sector, yet both drive divergent adhesive demand profiles. Brazil's emerging craft economy and India's domestic apparel boom round out the geographic spread.
China
Domestic apparel brands in Guangdong and Zhejiang provinces operate automated bonding lines consuming water-based acrylic dispersions by the ton. The Ministry of Ecology and Environment enforces GB standards limiting VOC emissions from textile finishing operations. Dongguan industrial clusters retrofit solvent-optimized equipment to accommodate lower-viscosity water-based systems.
Germany
Automotive interior suppliers in Bavaria specify rapid-cure solvent formulations for seat fabric-to-foam lamination despite REACH compliance costs. ECHA substance disclosure requirements disadvantage Asian exporters lacking European legal entities. Stuttgart-area manufacturing plants integrate UV-curable polyurethane systems for zero-VOC continuous-roll processing.
United States
Mass-market retailers consolidate procurement volumes for EPA-compliant home improvement adhesives with third-party formaldehyde certification. The EPA restricts emissions from consumer textile goods, filtering shelf space eligibility. California's DIY content creator economy drives tutorial-linked affiliate commerce for water-based craft formulations.
India
Domestic textile manufacturers in Maharashtra and Gujarat seek cost-competitive bonding solutions for automated garment production lines. BIS standards govern adhesive quality parameters for industrial applications. Tiruppur's knitwear cluster sources localized supply chains to bypass import duty exposure on European formulations.
Brazil
Emerging home crafters in São Paulo and Rio de Janeiro purchase adhesives through Mercado Livre and Amazon marketplace aggregators. ANVISA regulates skin-contact adhesive safety for consumer textile applications. Southeastern manufacturing zones develop regional distribution hubs to serve fragmented specialty retail demand.
Fabric Glue Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and distribution channel vectors. The vendor base separates into three tiers: multinational chemical groups with adhesive divisions, regional formulators with regulatory dossier capabilities, and craft-specialized niche suppliers. Strategic archetypes include REACH-compliant European manufacturers, cost-optimized Asian producers, and digitally native direct-to-consumer brands. Capacity expansion and portfolio diversification toward bio-derived raw materials represent the dominant competitive moves.
Among the multinational tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify divergent geographic anchoring strategies. Henkel leverages its European manufacturing footprint to serve industrial textile clients with consistent quality and regulatory pre-certification. H.B. Fuller anchors its position through deep relationships with apparel manufacturers seeking durable bonding solutions. Pidilite Industries Ltd occupies a distinct position as a South Asian consumer segment specialist with localized branding density and distribution reach into fragmented craft retail channels.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema |
| 3M |
| Pidilite Industries Ltd |
| Beacon Adhesives, Inc |
| Gutermann GmbH |
| Permatex, Inc. |
| Nan Pao Resins Chemical Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Polymer chemists with REACH dossier experience cluster in Germany and the Netherlands, commanding compensation premiums that widen pricing spreads between compliant premium tiers and cost-optimized Asian supply.
Pricing Analysis
Capacity additions in China are reshaping price floors for water-based acrylic dispersions as domestic manufacturers achieve scale economies in automated coating line supply. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European formulations from BIS-compliant Indian production and unbranded Chinese commodity supply. Price differentiation hinges on certification grade and volume scale, with consolidated apparel manufacturers extracting favorable terms while small-batch craft buyers absorb retail markups. Pricing pressure stems from petrochemical feedstock volatility that formulators cannot fully pass through to platform-aggregated e-commerce buyers.
Supply Chain Analysis
Acrylic resin supply rests on petrochemical producers in China, South Korea, and Germany with integrated upstream control over propylene derivatives. Key inputs include polyurethane prepolymers, tackifying rosins, and specialty additives for UV-curable systems. Single-source vulnerability concentrates in European specialty chemical houses holding REACH registration exclusives. Distribution runs through regional industrial distributors serving textile manufacturers, with direct-to-consumer channels bypassing wholesale layers for craft segment fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory compliance layering, with ECHA substance disclosure milestones creating durable competitive moats for dossier-capable suppliers.
For Market Incumbents: Anticipate silicone pressure-sensitive adhesive substitution in medical textile applications by accelerating ISO 10993 cytotoxicity pre-certification across premium portfolios. Defend position through backward integration into bio-based raw material supply chains aligned with EU Green Deal procurement preferences. Channel control via technical service relationships with automated coating line operators secures multi-year offtake stability against emerging Asian competitors. For New Entrants and Emerging Players: E-commerce platform aggregation offers the most penetrable route for craft segment entry, particularly in tutorial-linked affiliate commerce channels where algorithmic discovery displaces brand loyalty. Target fashion design ateliers in Milan and Paris with repositionable hot melt systems that reduce sample production waste. White-space exists in conductive fabric adhesives for wearable electronics integration where stretch-cycle durability expertise remains scarce. For Investors and Strategic Acquirers: Specialty chemical conglomerates with adhesive divisions are the most active acquirer in this space, seeking regional formulators with existing REACH dossiers to shortcut European market access. Long-term viability favors targets with demonstrated bio-based formulation pipelines and digital channel infrastructure. Watch for ECHA substance restriction list expansions as inflection indicators that would trigger accelerated consolidation among non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captures EU Green Deal procurement preference for renewable-content institutional textile contracts. |
| REACH Dossier Acquisition | Shortcuts six-figure euro toxicology investments and eliminates import barriers for Asian exporters. |
| Direct-to-Consumer Channel Launch | Bypasses wholesale markups through subscription models for adhesive replenishment in craft segments. |
| UV-Curable System Scale-Up | Enables zero-VOC continuous-roll processing for automotive interior lamination in Stuttgart-area plants. |
| Conductive Adhesive R&D Partnership | Positions for wearable electronics integration where electronics manufacturers seek stretch-cycle durability partners. |
Methodological Framework
Direct dialogue with polymer chemists, procurement leads at apparel manufacturers, distribution channel partners, and regulatory affairs directors combined with secondary validation from ECHA registration databases, customs trade records, SEC 10-K filings, and textile industry association reports. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with macroeconomic demand modeling.
Bottom-up volume builds aggregated individual segment trajectories across formulation chemistry, application type, and end-user category throughout the forecast period. Top-down cross-checks applied GDP-elasticity models and textile production indices to bracket aggregate demand. CAGRs derived from segment-level growth rate distributions weighted by current revenue contribution. Industry-specific inputs included automated coating line installation rates and REACH compliance cost curves.
The model assumes a particular technology adoption path; alternative pathways for UV-curable polyurethane dispersions would alter the outlook if cure-speed economics shift. Forecasts reflect assumptions about regulatory enforcement intensity and petrochemical price normalization. A small set of triggers warrants ongoing watch: ECHA substance restriction expansions, Chinese environmental enforcement campaigns, and silicone adhesive cost curves in medical applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Tile and Stone Adhesive Market