
 Global Cyanoacrylate Adhesives Market | 2026-2036
Global Cyanoacrylate Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyanoacrylate Adhesives Market Foresight
The gap between premium medical-grade formulations and commodity industrial adhesives is broadening. Henkel AG & Co. KGaA leverages its Loctite heritage to dominate high-purity segments for electronics bonding and surgical applications. 3M sustains technology leadership through proprietary primer systems that expand substrate compatibility. Toagosei Co. Ltd. anchors Asian supply chains with concentrated production of ethyl and methyl monomers for regional OEMs.
Cyanoacrylate adhesives are single-component, fast-curing thermoplastic resins that polymerize upon contact with trace moisture, typically achieving handling strength within seconds and full cure through anionic chain growth at room temperature. Industrial formulations prioritize ethyl cyanoacrylate for its versatile bonding across metals, plastics, and elastomers, while octyl cyanoacrylate commands premium positioning in medical device assembly due to reduced tissue irritation and flexible polymer characteristics. Gel and paste forms are gaining structural share in vertical-gap applications such as footwear manufacturing and woodworking where liquid runoff compromises assembly precision.
FDA device regulations, EPA TSCA Section 5 requirements for new chemical substances, and REACH Annex XVII restrictions on hazardous substances collectively shape formulation chemistry and market access pathways for cyanoacrylate producers. ISO 10993 biocompatibility testing frameworks determine qualification thresholds for adhesives contacting patient tissue or blood pathways. Stakeholders must monitor evolving chemical hazard classifications across the European Chemicals Agency and the EPA Office of Pollution Prevention and Toxics, as reclassification events can trigger reformulation cycles and regional supply reallocations.
Market Dynamics
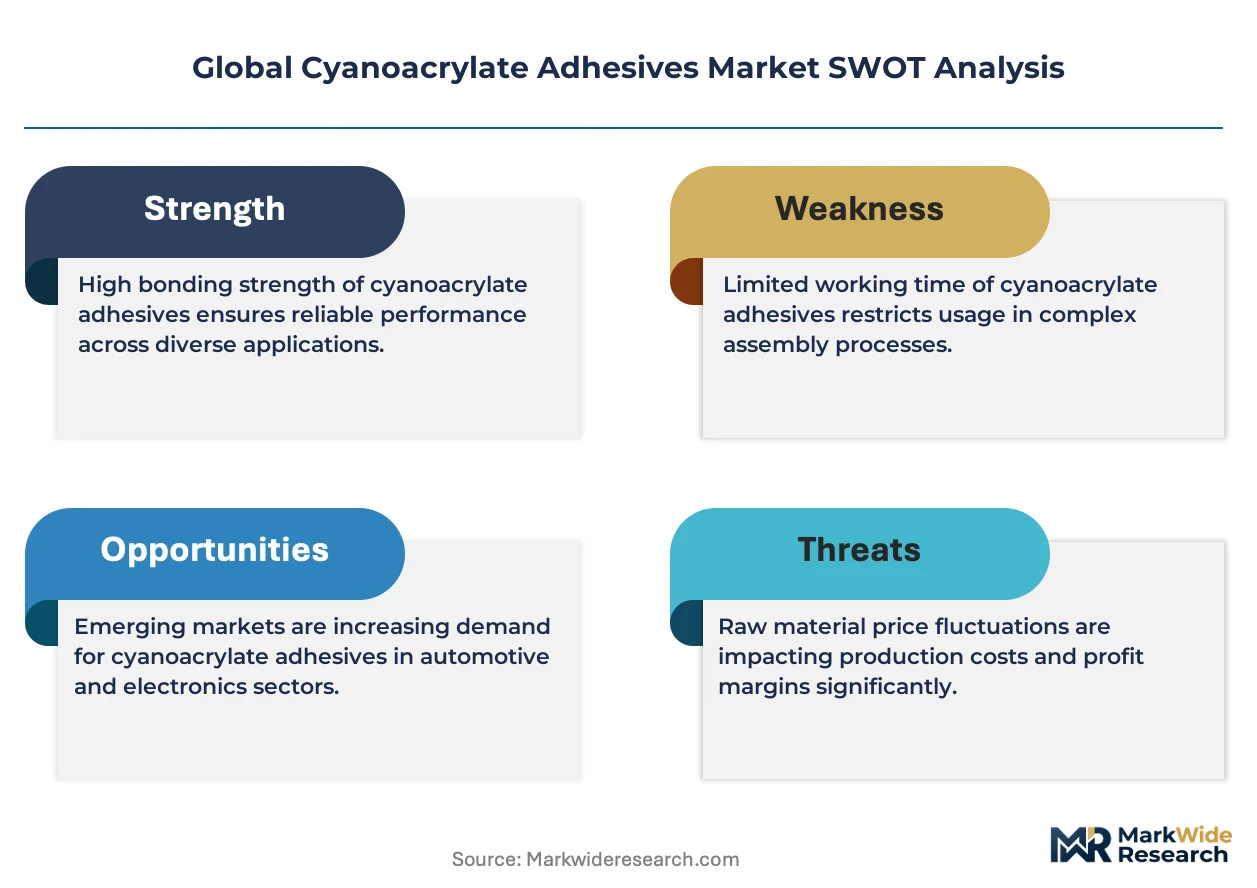
Medical-grade purity thresholds are bifurcating the cyanoacrylate adhesives landscape, as FDA device regulations and REACH Annex XVII restrictions force dual-track formulation strategies that commodity producers cannot easily replicate.
Growth Catalysts
- Minimally invasive surgical instrument assembly:Medical device manufacturers in Germany and Japan are expanding adhesive bonding in laparoscopic and robotic surgery tools, replacing mechanical fasteners with biocompatible cyanoacrylate formulations certified under ISO 10993.
- REACH Annex XVII hazardous substance restrictions:Tightening purity mandates across the European Union are accelerating replacement of legacy industrial formulations, creating qualification advantages for producers with advanced monomer distillation capabilities.
- Ethyl cyanoacrylate versatility:The monomer's balanced cure speed and substrate compatibility is displacing mechanical fastening in Chinese electronics assembly clusters, particularly for smartphone and wearable device component bonding.
Market Restraints
- Crude oil derivative volatility:Ethyl cyanoacrylate synthesis depends on acetic acid and formaldehyde feedstocks, exposing margin structures to petrochemical price swings that formulation specialists cannot fully hedge.
- Japanese monomer concentration:Regional supply chains concentrate high-purity ethyl and methyl monomer production with Toagosei and select Japanese chemical houses, creating single-source vulnerability for Asian OEM qualification programs.
- UV-curable acrylic substitution:Electronics manufacturers in South Korea and Taiwan are piloting light-curing alternatives that eliminate moisture-sensitivity handling constraints in cleanroom environments.
Strategic Opportunities
- Indian medical device manufacturing:The country's PLI scheme for domestic device production is attracting contract manufacturers seeking localized adhesive supply chains, bypassing import dependency on European and Japanese formulations.
- Octyl cyanoacrylate tissue adhesive expansion:Reduced irritation profiles and flexible polymer characteristics are opening veterinary and consumer wound-care applications beyond regulated surgical markets.
- Gel and paste viscosity grades:Vertical-gap applications in Brazilian footwear and Indonesian woodworking are creating demand for non-liquid formulations that resist assembly-line runoff.
Industry Challenges
- ISO 10993 biocompatibility testing timelines:Medical-grade qualification cycles extend months beyond industrial certification, straining working capital for mid-scale producers entering surgical device supply chains.
- Anionic polymerization control:Moisture-triggered cure chemistry demands precision environmental controls in tropical manufacturing environments, complicating quality consistency across multi-site production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyanoacrylate Adhesives Market |
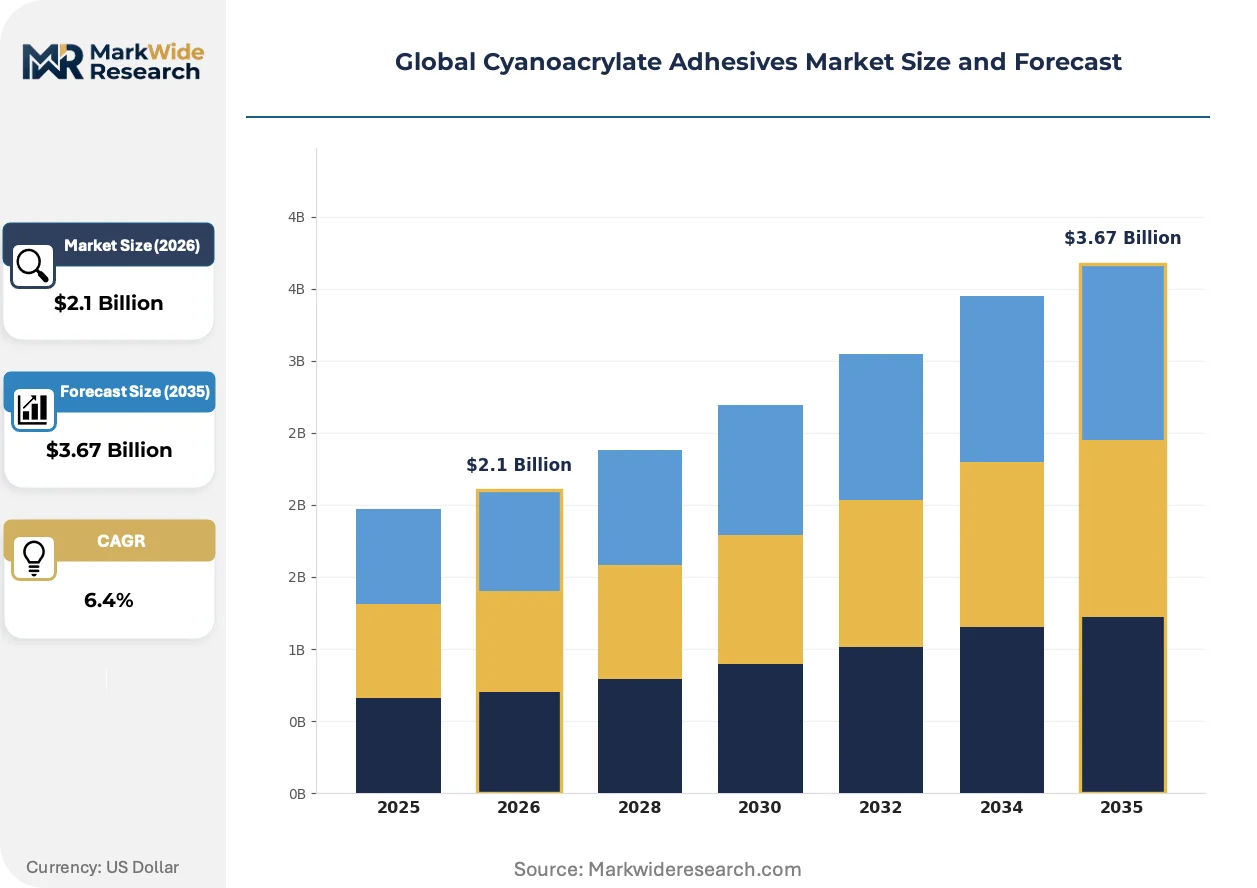
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Cyanoacrylate, Methyl Cyanoacrylate, Butyl Cyanoacrylate, Octyl Cyanoacrylate, Others Form: Liquid, Gel, Paste, Granular Application: Electronics Bonding, Packaging Sealing, Footwear Manufacturing, Woodworking, Medical Device Assembly End User Industry: Consumer Electronics, Footwear Makers, Furniture Producers, Medical Equipment Manufacturers, Packaging Firms |
| Companies Covered | Henkel AG & Co. KGaA, 3M, H.B. Fuller Company, Sika AG, Arkema Group, Huntsman International LLC, Toagosei Co. Ltd., Pidilite Industries Ltd., Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyanoacrylate Adhesives Market Shifts & Advancements
Formulation chemistry is diverging along medical-industrial lines, with regulatory compliance becoming the primary axis of competitive differentiation rather than cure speed or bond strength alone.
Light-activated cyanoacrylate systems is converging with precision electronics assembly requirements. Semiconductor packaging specialists in Taiwan and South Korea are adopting photoinitiator-modified formulations that combine instant handling strength with controlled final cure under UV exposure. This hybrid chemistry is compressing process windows in microelectromechanical system bonding, where moisture-cure variability previously demanded excessive work-in-progress buffers.
ECHA's evolving classification of respiratory sensitizers is forcing reformulation of industrial-grade methyl cyanoacrylate products across German automotive supplier networks. The agency's 2023-2024 substance evaluations have triggered downstream communication obligations that smaller metal-bonding shops struggle to document. Formulators with dedicated toxicology dossiers are capturing share in Ruhr Valley precision manufacturing clusters where compliance documentation now precedes price negotiation.
Certificate-of-analysis purchasing is displacing spot-buying in Chinese medical device export channels. Shenzhen and Suzhou contract manufacturers now require batch-specific biocompatibility test results before releasing payment, replacing traditional specification-sheet acceptance. This verification burden favors adhesive suppliers with captive analytical laboratories, compressing margins for traders without in-house ISO 17025 testing capabilities.
Global Cyanoacrylate Adhesives Market Segmentation
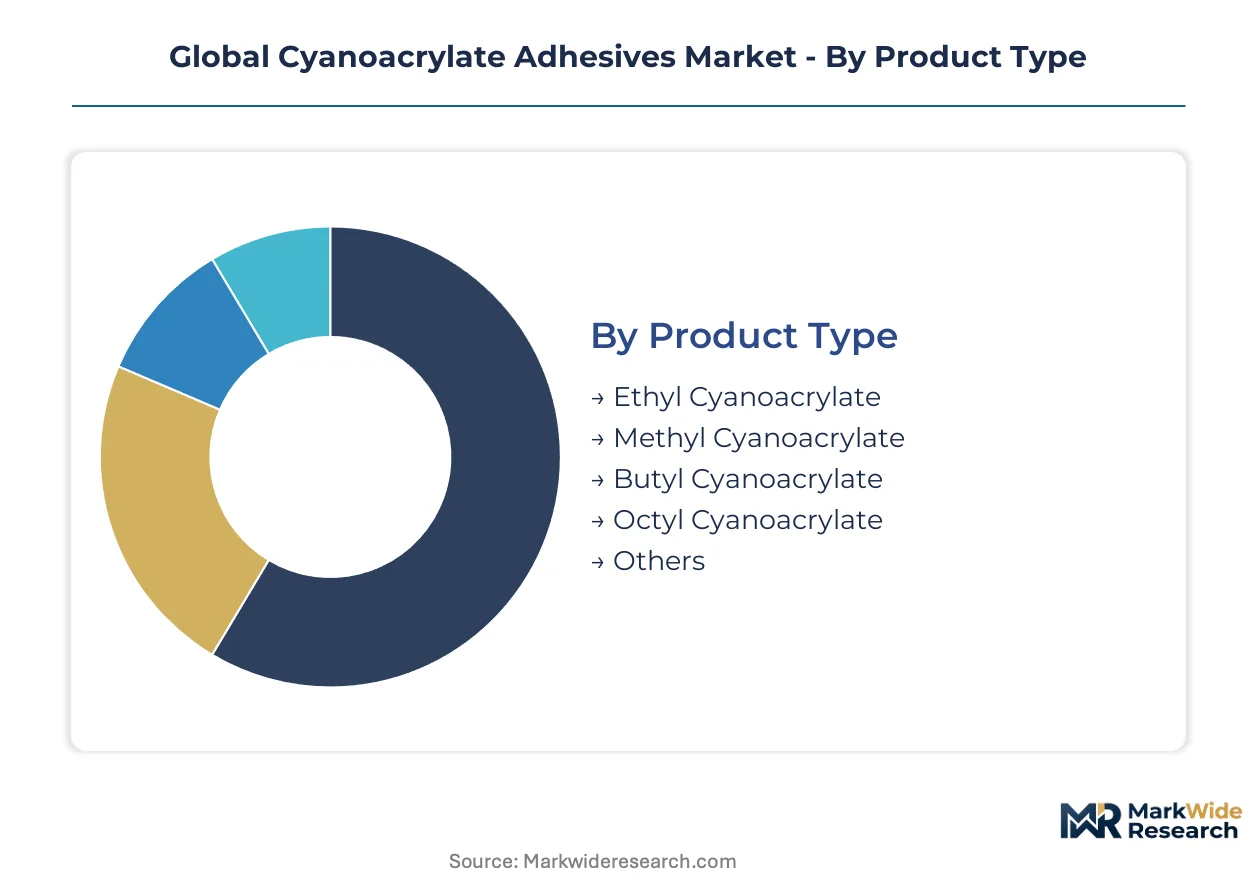
Cyanoacrylate adhesives segment along purity and certification lines that determine market access rather than chemistry alone. Medical-grade formulations command qualification premiums that industrial grades cannot replicate, while viscosity adaptations unlock application-specific growth corridors.
Product Type:
Each monomer variant carries distinct regulatory burdens, with FDA device approvals and REACH Annex XVII compliance thresholds stratifying producer capabilities across industrial and medical channels.
- Ethyl Cyanoacrylate:The dominant industrial monomer balances cure speed against substrate versatility across metals, plastics, and elastomers. Chinese electronics clusters in Shenzhen and Suzhou concentrate procurement for smartphone and wearable device bonding, displacing mechanical fasteners in high-volume assembly.
- Octyl Cyanoacrylate:Longer alkyl chains yield flexible polymer structures with reduced tissue irritation profiles. German and Japanese surgical device manufacturers specify this grade for ISO 10993-certified wound closure and internal tissue bonding applications.
- Methyl Cyanoacrylate:Rapid-cure industrial formulations face ECHA respiratory sensitizer reclassification pressures across German automotive supplier networks.
- Butyl Cyanoacrylate:Intermediate viscosity grades serve Brazilian footwear and Indonesian woodworking vertical-gap applications.
- Others:Specialty monomer variants including propyl and isobutyl esters address niche substrate compatibility requirements.
Ethyl cyanoacrylate sits at the top of the volume ranking, with octyl cyanoacrylate climbing the fastest.
Form:
Physical state determines handling characteristics and process integration complexity, with non-liquid formats commanding manufacturing premiums in tropical and vertical-application environments.
- Liquid:Standard industrial workhorse enabling capillary action bonding in tight-tolerance assemblies. Electronics manufacturers in South Korea and Taiwan are piloting UV-curable acrylic substitutes that eliminate moisture-sensitivity constraints in cleanroom settings.
- Gel:Thixotropic formulations resist runoff on inclined or vertical surfaces. Brazilian footwear assembly lines specify gel grades for sole attachment operations where liquid adhesives compromise precision.
- Paste:High-viscosity grades fill gap tolerances in Indonesian woodworking and furniture production where substrate irregularities demand gap-filling capability.
- Granular:Solid monomer forms support captive polymerization systems in specialized industrial applications.
Liquid formulations retain volume leadership, though gel and paste grades are expanding share fastest in tropical manufacturing corridors.
Application:
End-use certification requirements fragment the competitive landscape, with medical and electronics applications imposing qualification barriers that packaging and woodworking segments do not replicate.
- Electronics Bonding:Miniaturization trends in semiconductor packaging and MEMS assembly drive demand for precision dispensing compatibility. Taiwanese and South Korean manufacturers are adopting photoinitiator-modified systems that combine instant handling with UV-controlled final cure.
- Medical Device Assembly:Laparoscopic and robotic surgical instrument manufacturers in Germany and Japan specify ISO 10993-certified formulations for biocompatible bonding. FDA device regulations and batch-specific certificate-of-analysis requirements favor suppliers with captive analytical laboratories.
- Packaging Sealing:High-speed carton and flexible film sealing operations prioritize ethyl cyanoacrylate for rapid line integration.
- Footwear Manufacturing:Gel and paste viscosity grades address vertical assembly challenges in Brazilian and Vietnamese production facilities.
- Woodworking:Gap-filling paste formulations serve Indonesian furniture export clusters targeting European and North American markets.
Electronics bonding leads by volume, while medical device assembly demonstrates the steepest expansion trajectory on regulatory-driven specification upgrades.
End User Industry:
Customer concentration patterns align with regional manufacturing specialization, with procurement power concentrating in contract manufacturing hubs that dictate supplier qualification protocols.
- Consumer Electronics:OEMs and contract manufacturers in China, Taiwan, and South Korea drive specification-setting for adhesive performance in smartphone, tablet, and wearable device assembly.
- Medical Equipment Manufacturers:German precision instrument makers and Japanese surgical device specialists enforce ISO 10993 and FDA compliance documentation as purchasing prerequisites.
- Footwear Makers:Brazilian and Vietnamese production clusters specify viscosity-modified grades for assembly-line efficiency in tropical climates.
- Furniture Producers:Indonesian and Malaysian export-oriented manufacturers prioritize cost-optimized formulations for wood-to-wood and wood-to-veneer bonding.
- Packaging Firms:High-volume carton sealing operations in North America and Europe favor rapid-cure ethyl cyanoacrylate for line speed optimization.
Consumer electronics commands the largest procurement volumes, with medical equipment manufacturers gaining purchasing influence fastest through certification-driven supplier consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates high-purity medical-grade procurement, while China dominates industrial electronics bonding volumes through Shenzhen and Suzhou manufacturing clusters.
Germany
Precision surgical instrument manufacturers in Baden-Württemberg and Bavaria drive ISO 10993-certified adhesive demand for laparoscopic and robotic surgery tools. ECHA's evolving respiratory sensitizer classifications under REACH Annex XVII force automotive suppliers in the Ruhr Valley to document downstream communication obligations. Stuttgart and Munich medical device clusters enforce certificate-of-analysis purchasing protocols that favor suppliers with captive analytical laboratories.
China
Shenzhen and Suzhou electronics contract manufacturers displace mechanical fasteners with ethyl cyanoacrylate in smartphone and wearable device assembly. The country's national chemical safety regulator aligns domestic standards with evolving international purity benchmarks. Pearl River Delta OEMs now require batch-specific biocompatibility documentation before releasing payment to adhesive suppliers.
Japan
Toagosei and select chemical houses concentrate high-purity ethyl and methyl monomer production, creating single-source vulnerability for Asian OEM qualification programs. METI oversees industrial chemical safety frameworks that influence regional formulation standards. Nagoya and Osaka precision manufacturing clusters specify medical-grade octyl cyanoacrylate for surgical device bonding applications.
United States
FDA device regulations and EPA TSCA Section 5 requirements shape formulation chemistry for medical and industrial adhesive producers. The country's environmental protection agency evaluates new chemical substances through evolving safety assessment protocols. Minnesota and California electronics packaging specialists pilot photoinitiator-modified systems for semiconductor bonding applications.
Brazil
Footwear manufacturers in São Paulo and Rio Grande do Sul specify gel and paste viscosity grades for vertical assembly operations where liquid adhesives compromise precision. ANVISA oversees medical device regulations that influence imported adhesive qualification pathways. Domestic woodworking clusters in Paraná increasingly demand gap-filling formulations for furniture export production.
Global Cyanoacrylate Adhesives Market Competitive Landscape
Top-tier vendors anchor premium medical-grade and electronics bonding segments, while mid-scale regional specialists concentrate on industrial formulations and price-sensitive emerging markets. The competitive structure stratifies across three capability tiers: global chemical conglomerates with captive monomer distillation, regional formulation houses with ISO 17025 testing infrastructure, and commodity traders dependent on specification-sheet acceptance. Dominant competitive moves include backward integration into monomer production and geographic expansion through localized qualification programs.
Within the diversified chemical conglomerate tier, Henkel AG & Co. KGaA and 3M exemplify positioning anchored in regulatory compliance infrastructure and proprietary formulation heritage. Toagosei Co. Ltd. occupies a distinct position as a regional monomer specialist with concentrated production capabilities serving Asian OEM networks. These three entities represent the archetype spectrum spanning global multi-segment coverage, technology-driven substrate compatibility expansion, and supply-chain concentrated regional dominance.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| H.B. Fuller Company |
| Sika AG |
| Arkema Group |
| Huntsman International LLC |
| Toagosei Co. Ltd. |
| Pidilite Industries Ltd. |
| Illinois Tool Works Inc. |
| Others |
Supply & Pricing Matrix
Acetic acid and formaldehyde feedstock indices cascade through cyanoacrylate adhesive pricing tiers, compressing margins at commodity grades while medical-grade monomer distillation capabilities sustain premium capture across German and Japanese surgical device supply chains.
Pricing Analysis
Capacity additions in Chinese ethyl cyanoacrylate synthesis are reshaping price floors for industrial electronics bonding grades. Three-tier pricing structure across medical-grade ISO 10993-certified, industrial high-purity, and commodity formulations stratifies buyer access. Cost compression in standard industrial grades intensifies because Shenzhen contract manufacturers consolidate procurement volumes. Electronics OEMs in South Korea and Taiwan exhibit highest price sensitivity, while German surgical instrument makers prioritize certification documentation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Chinese electronics contract manufacturers, while specialty distributors serve mid-scale Brazilian footwear and Indonesian woodworking accounts. Monomer production concentrates in Japan, China, and Germany, with high-purity ethyl and methyl output anchored in Toagosei's Nagoya facilities. Synthesis draws from acetic acid, formaldehyde, and cyanide derivative inputs. Single-source vulnerability pervades Asian OEM qualification programs dependent on Japanese monomer supply. Distribution runs through authorized chemical distributors with REACH and EPA handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Indian PLI scheme subsidies for domestic medical device manufacturing create cost-advantaged production against European import dependency, while REACH compliance investments in Germany sustain premium pricing power.
For Market Incumbents: Anchor backward integration into monomer distillation to defend against Japanese supply concentration risk. Secure captive ISO 17025 analytical laboratories to meet certificate-of-analysis purchasing protocols from Shenzhen and Suzhou contract manufacturers. Deepen regulatory dossier capabilities ahead of ECHA respiratory sensitizer reclassifications affecting methyl cyanoacrylate industrial formulations.
For New Entrants and Emerging Players: Enter via Indian medical device manufacturing corridors where PLI scheme incentives attract contract manufacturers seeking localized adhesive supply chains. Target veterinary and consumer wound-care octyl cyanoacrylate applications beyond regulated surgical markets, leveraging reduced tissue irritation profiles. Pursue gel and paste viscosity specialization for Brazilian footwear and Indonesian woodworking vertical-gap applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulation houses possessing ISO 17025 testing infrastructure and established OEM qualification relationships. Long-term viability hinges on regulatory compliance capabilities rather than scale alone across the projection horizon. Monitor ECHA substance evaluation timelines and EPA TSCA Section 5 rulings as inflection indicators for reformulation-driven supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Distillation | Captive high-purity ethyl and methyl production insulates margins from Japanese supply concentration. |
| ISO 17025 Laboratory Accreditation | Batch-specific certificate-of-analysis capabilities unlock Shenzhen medical device export channels. |
| Photoinitiator-Modified Formulation Development | UV-controlled final cure addresses moisture-sensitivity constraints in Taiwanese semiconductor packaging. |
| Indian Manufacturing Joint Venture | PLI scheme alignment captures domestic medical device adhesive demand bypassing European import dependency. |
| REACH Annex XVII Compliance Investment | Advanced toxicology dossiers secure share in German automotive supplier networks facing ECHA reclassification. |
Research Methodology
Multiple input streams — primary interviews with adhesive R&D directors, medical device procurement managers, and chemical distribution specialists, alongside secondary validation through ECHA substance evaluation databases, EPA TSCA filings, and customs trade flow records — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against expert panel assessments to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include monomer type, viscosity grade, end-use certification tier, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating electronics miniaturization trends and surgical device bonding specification upgrades.
Inputs from regulatory agency publication schedules and OEM qualification program timelines were available through the study window; gaps in real-time feedstock price volatility data introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding REACH enforcement consistency and EPA evaluation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
UV Glue Market