
 Textile Binders Market | 2026-2036
Textile Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Binders Market Outlook
Modular binder formulations that combine base polymers with crosslinking additives in single-package systems is consolidating buyer preferences toward simplified procurement. BASF SE leverages its integrated acrylic acid chain to control raw material access for textile finishing grades. Huntsman International LLC anchors its position through specialized polyurethane dispersions for coated fabrics. Dow Inc. competes in nonwoven applications with emulsion polymers engineered for thermal bonding efficiency.
Textile binders are film-forming polymers, typically acrylic, polyvinyl acetate, or polyurethane-based emulsions, that adhere fibers or coatings to substrate surfaces at solids contents ranging from 40% to 60% and glass transition temperatures tailored to end-use flexibility requirements. Their primary commercial purpose is to impart structural integrity, hand feel, and durability to fabrics without adding significant weight. Acrylic binder formulations command the deepest margin pools in textile finishing due to their versatility across natural and synthetic substrates. Synthetic adhesive segments in adhesive bonding applications represent the fastest-expanding demand category as technical textiles penetrate automotive and construction end uses. Polyvinyl acetate remains mature in home textiles where cost sensitivity dominates buyer decisions.
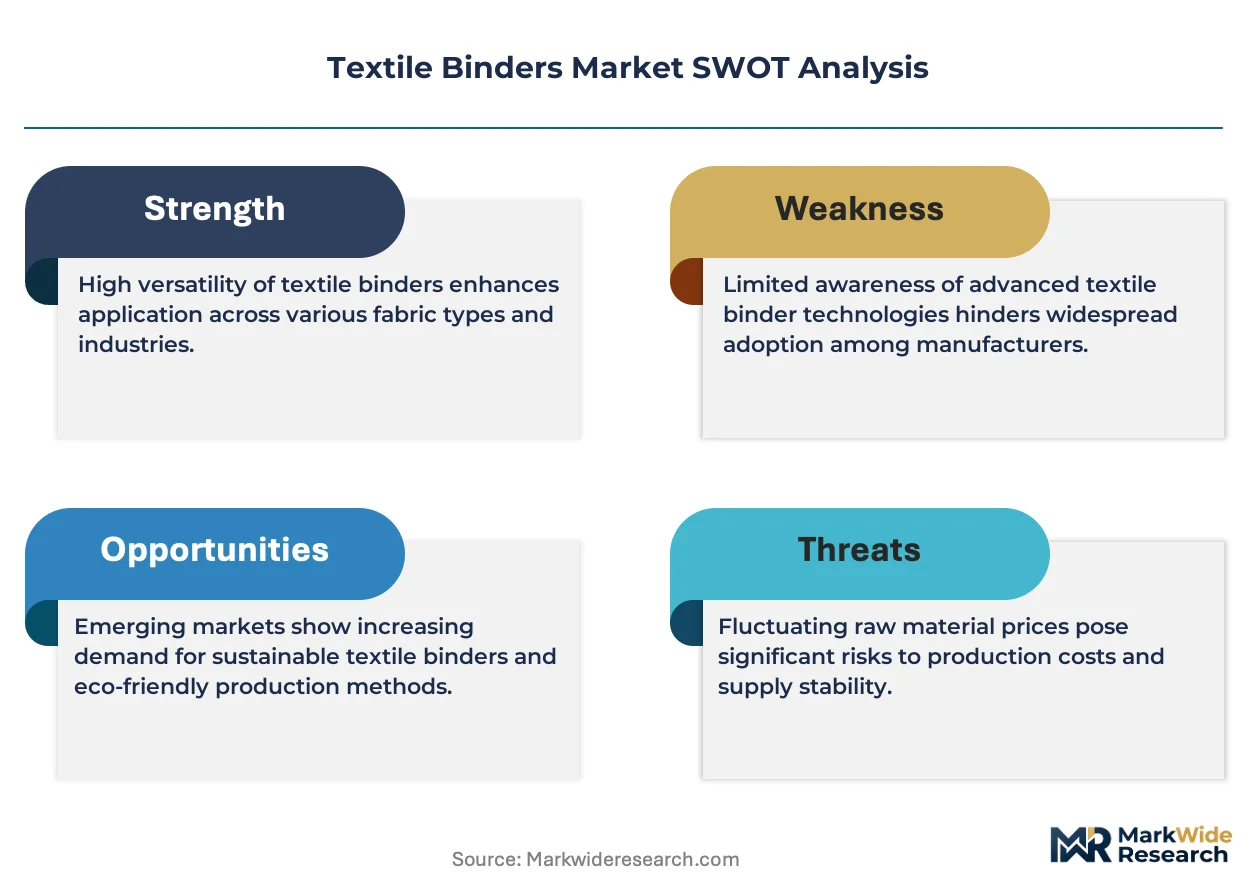
EPA restrictions on formaldehyde emissions in textile finishing and REACH substance authorization requirements in Europe are accelerating water-based reformulation investments among binders suppliers. China's MEE enforcement of volatile organic compound discharge standards in the Yangtze River Delta manufacturing cluster is reshaping local production compliance costs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border textile chemical trade.
Market Dynamics
Water-based acrylic reformulation is compressing formulation complexity as REACH substance authorization and EPA volatile organic compound limits force binder suppliers to eliminate solvent-based systems across hygiene and medical nonwoven applications.
Growth Catalysts
- REACH authorization timelines:European chemical substance restrictions are accelerating supplier investment in compliant water-based acrylic platforms ahead of sunset dates for legacy solvent chemistries.
- Medical nonwoven expansion:Surgical gown and drape producers are scaling thermal-bonded fabric capacity, pulling demand for high-solids acrylic emulsions with tailored glass transition temperatures.
- Yangtze River Delta concentration:China's MEE enforcement of volatile organic compound discharge standards is consolidating domestic binder production around certified water-based systems.
Market Restraints
- Acrylic acid supply concentration:Crude derivative availability tightens when upstream propylene oxide units experience unplanned outages, transmitting volatility into binder raw material costs.
- Polyurethane dispersion technical ceilings:Film flexibility requirements below minus twenty degrees Celsius exceed current aqueous polyurethane performance without solvent coalescing aids.
- Cross-border regulatory divergence:Divergent EPA formaldehyde emission limits and REACH authorization lists strand inventory when formulations approved in one jurisdiction fail compliance in another.
Strategic Opportunities
- Technical textile automotive penetration:Interior trim and seating fabric producers are specifying polyurethane binders for abrasion resistance in electric vehicle cabin designs.
- Construction geotextile specification:Infrastructure stabilization fabrics are adopting synthetic adhesive bonding for soil retention and drainage layer integrity.
- Single-package modular systems:Formulations combining base polymers with integrated crosslinking additives are simplifying buyer procurement workflows and reducing formulation errors.
Industry Challenges
- Formulation chemist scarcity:Expertise in glass transition temperature tuning and solids content optimization for nonwoven thermal bonding is concentrating among senior technical staff at established suppliers.
- Water-based line conversion capex:Shifting solvent-based production to aqueous systems requires reactor vessel replacement and emissions control infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Binders Market |
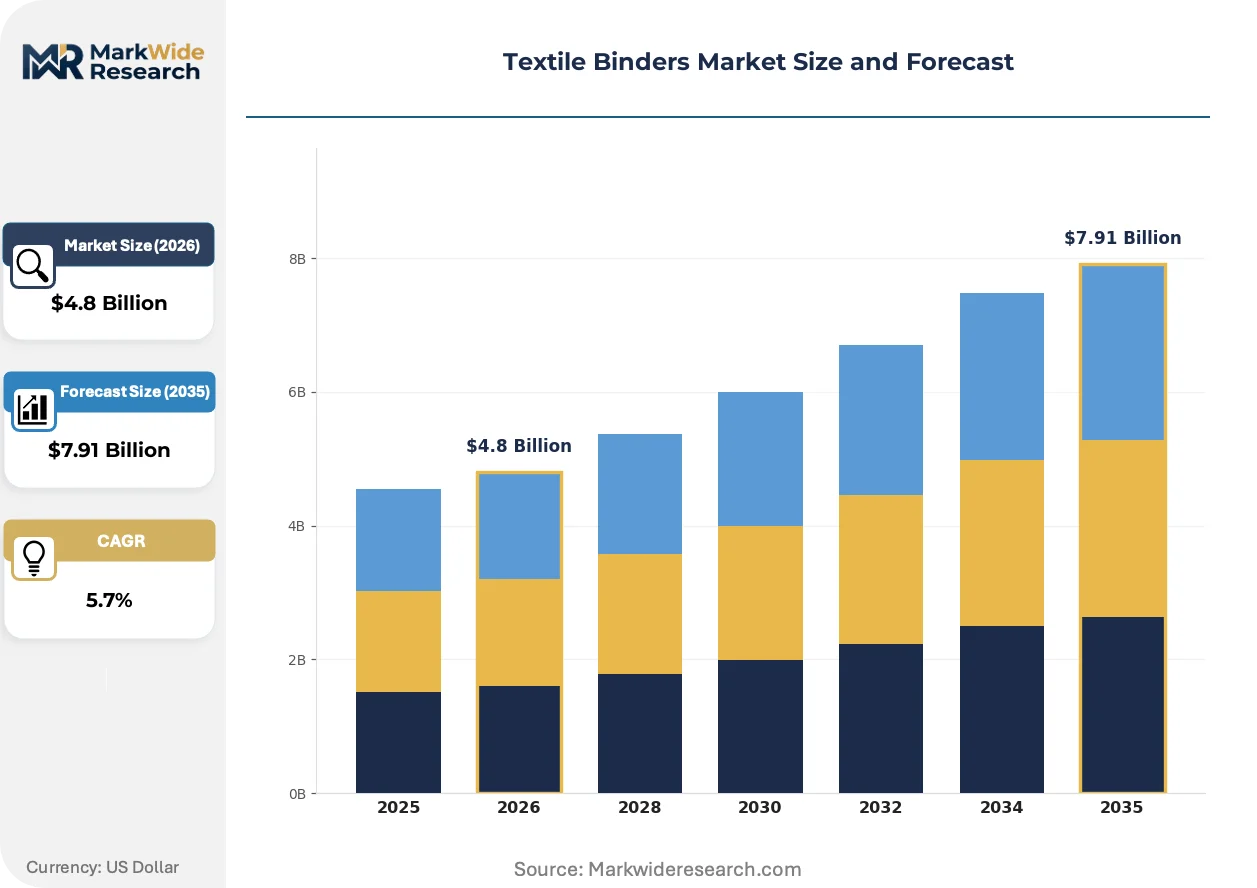
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Acetate, Synthetic Adhesive, Acrylic Binder, Natural Binder Application: Nonwoven Fabrics, Coated Fabrics, Textile Finishing, Adhesive Bonding End User: Apparel Manufacturers, Upholstery Producers, Home Textiles, Industrial Textiles Form: Liquid, Powder, Granule, Sheet |
| Companies Covered | Evonik Industries AG, Eastman Chemical Company, BASF SE, Huntsman International LLC, Solvay SA, Dow Inc., Covestro AG, Wacker Chemie AG, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Binders Market Strategic Shifts
Reactive chemistry integration is collapsing the traditional separation between base polymer supply and downstream crosslinking activation, compressing formulation steps and reducing batch variability in textile finishing operations.
Hybrid acrylic-polyurethane copolymer technology is unifying the hand-feel versatility of acrylics with the abrasion resistance of polyurethanes in single-binder platforms. Automotive seating and interior trim producers are qualifying these systems for electric vehicle applications where durability and aesthetic flexibility converge. This unification is compressing the number of approved supplier lists that original equipment manufacturers must maintain.
EPA formaldehyde emission restrictions under the Toxic Substances Control Act are eliminating urea-formaldehyde crosslinkers from textile finishing formulations. Binder suppliers are reformulating toward glyoxal and polycarbodiimide alternatives, though these carry higher raw material costs. Home textile producers serving the United States market are absorbing compliance costs or exiting formaldehyde-reliant product lines entirely.
Buyer consolidation among multinational nonwoven producers is compressing supplier negotiation cycles and demanding volume-tiered pricing structures. Tier-one hygiene product manufacturers are centralizing global binder procurement through single-source or dual-source contracts. China-based nonwoven capacity expansion is capturing the most visible concentration of this procurement pattern consolidation.
Textile Binders Market Segmentation
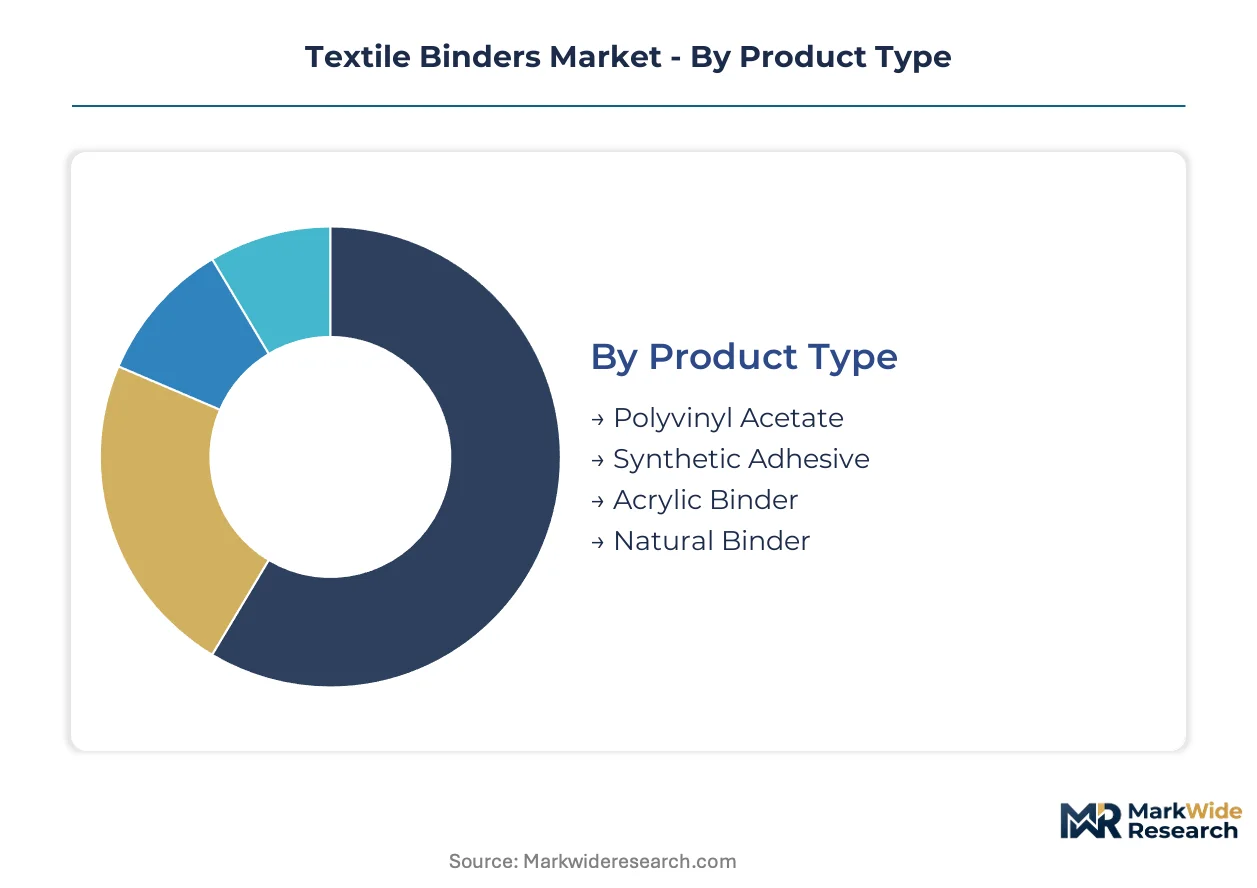
Textile binder procurement decisions hinge on performance specifications that vary sharply across substrate types and end-use durability requirements. Buyers segment demand by polymer chemistry, application method, and regulatory compliance tier rather than treating binders as commodity inputs.
Product Type:
Cost sensitivity and performance requirements split buyer preferences across polymer families with distinct margin structures and reformulation trajectories.
- Acrylic Binder:Versatile emulsion polymers with glass transition temperatures tunable from -20°C to +60°C serve both natural and synthetic fiber substrates. Demand concentrates in hygiene nonwovens produced in China's Yangtze River Delta, where MEE enforcement of volatile organic compound standards favors water-based acrylic platforms over solvent alternatives.
- Synthetic Adhesive:Engineered polymer systems including polyurethane dispersions and modified acrylics deliver abrasion resistance and low-temperature flexibility for technical textiles. Automotive seating producers in Germany and electric vehicle cabin designers in the United States are specifying these grades for durability under mechanical stress and thermal cycling.
- Polyvinyl Acetate:Mature homopolymer and copolymer emulsions dominate cost-driven home textile applications where hand feel requirements are less stringent than industrial specifications.
- Natural Binder:Starch, protein, and bio-based polymer systems serve niche markets seeking renewable content, though thermal stability and moisture resistance constrain application breadth.
Volume sits with acrylic formulations; growth tilts toward synthetic adhesive systems as technical textile penetration deepens in automotive and construction end uses.
Application:
Processing method determines solids content requirements, thermal bonding parameters, and crosslinking chemistry selection across fabric finishing operations.
- Nonwoven Fabrics:High-solids acrylic emulsions at 45-55% solids content enable thermal bonding of synthetic fibers in hygiene and medical applications. Surgical gown producers in the United States and diaper manufacturers in China are scaling capacity for thermal-bonded structures, pulling demand for binders with precise glass transition temperature control.
- Textile Finishing:Surface coating and impregnation processes apply binders to woven and knitted substrates for hand feel modification and dimensional stability. REACH authorization requirements in Europe and EPA formaldehyde emission limits in the United States are forcing reformulation away from urea-formaldehyde crosslinkers toward glyoxal and polycarbodiimide alternatives.
- Coated Fabrics:Polyurethane dispersions and hybrid acrylic-polyurethane systems form protective layers on technical textiles for automotive interiors and protective apparel.
- Adhesive Bonding:Lamination and assembly operations bond fabric layers or attach components in footwear and industrial applications.
Nonwoven applications command the largest volume position; textile finishing represents the steepest expansion trajectory as regulatory compliance accelerates water-based system adoption.
End User:
Customer scale and specification intensity create distinct service requirements from formulation customization to just-in-time delivery.
- Industrial Textiles:Geotextiles, filtration media, and protective fabrics require binders with chemical resistance and mechanical durability under load. Infrastructure stabilization projects in China and road construction in Germany are specifying synthetic adhesive bonding for soil retention fabrics.
- Apparel Manufacturers:Garment producers apply binders for interfacing, embroidery backing, and fabric stabilization where wash durability and hand feel must balance cost.
- Upholstery Producers:Furniture and automotive seating manufacturers prioritize abrasion resistance and flame retardancy in binder selection.
- Home Textiles:Bedding, curtain, and towel producers drive polyvinyl acetate consumption where cost sensitivity dominates over performance differentiation.
Industrial textile buyers generate the highest specification intensity; apparel manufacturers contribute the broadest geographic dispersion of demand.
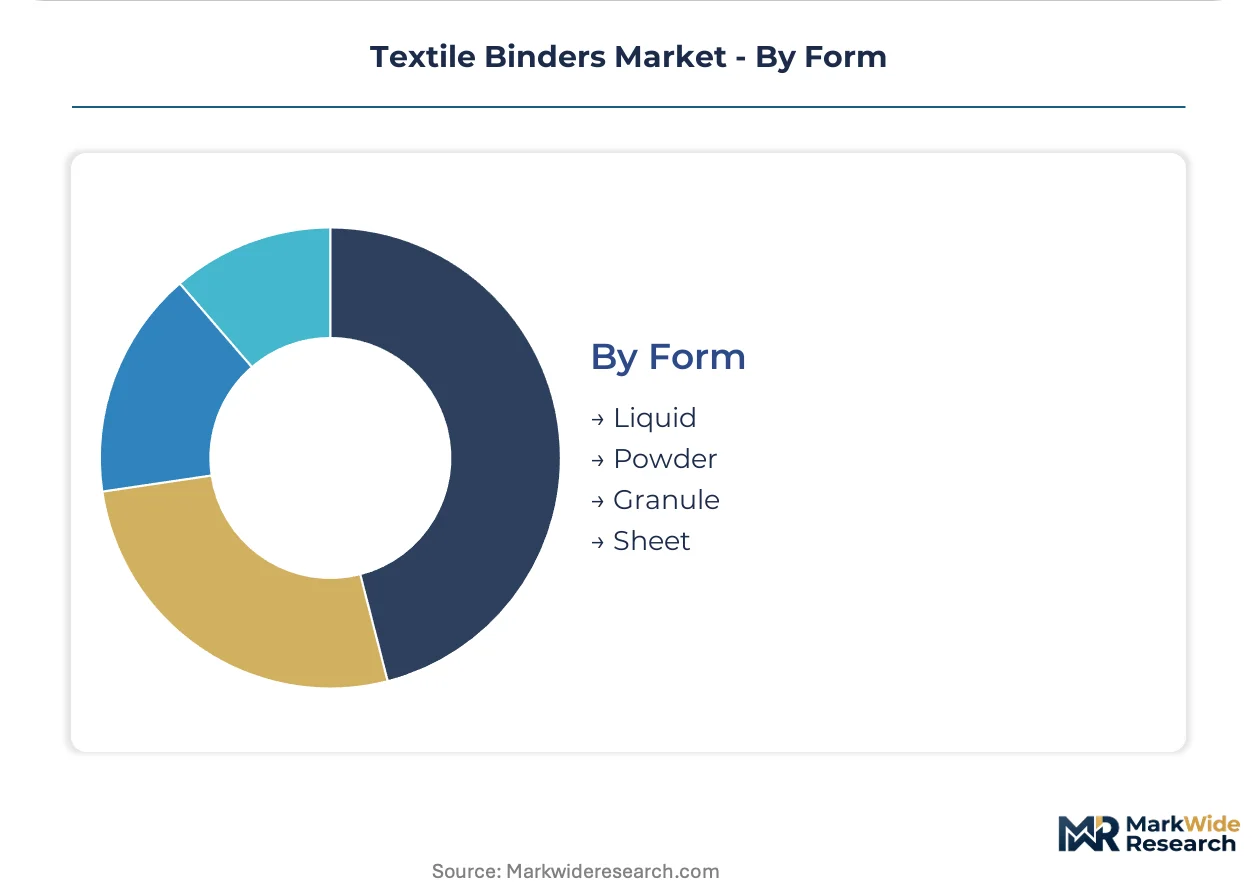
Form:
Physical state determines shipping economics, storage requirements, and processing equipment compatibility at customer sites.
- Liquid:Aqueous emulsions at 40-60% solids content dominate textile finishing due to pumpability and spray application compatibility. Water-based acrylic and polyurethane dispersions in liquid form are capturing procurement preference as EPA and REACH restrictions eliminate solvent-based alternatives.
- Powder:Redispersible polymer powders enable dry blending in construction textile applications and regions with limited liquid handling infrastructure.
- Granule:Solid binder forms serve hot-melt coating operations and specific nonwoven thermal bonding configurations.
- Sheet:Pre-formed binder films and webs facilitate lamination processes in specialized composite applications.
Liquid forms hold the volume concentration; powder formats are gaining share fastest in construction geotextile and emerging market applications where logistics constraints favor dry shipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in China while consumption spreads across Germany, the United States, and Japan. This geographic split shapes cross-border trade flows and regulatory compliance strategies for binder suppliers.
China
Nonwoven fabric manufacturers in the Yangtze River Delta are scaling thermal-bonded capacity for hygiene applications. MEE enforcement of volatile organic compound discharge standards is eliminating solvent-based production lines. Zhejiang and Jiangsu provinces are capturing the bulk of domestic acrylic binder output as multinational chemical firms localize supply chains.
Germany
Automotive seating producers specify polyurethane binders for electric vehicle interior durability. REACH substance authorization timelines are accelerating water-based reformulation investments. The North Rhine-Westphalia chemical corridor hosts specialized dispersion production for technical textile exports.
United States
Surgical gown and medical drape manufacturers pull high-solids acrylic emulsions for thermal-bonded fabric capacity. EPA formaldehyde emission limits under the Toxic Substances Control Act are phasing out urea-formaldehyde crosslinkers. Southeast nonwoven clusters in Georgia and the Carolinas are expanding compliant water-based finishing operations.
Japan
Automotive and electronics textile producers demand low-temperature flexibility specifications. METI industrial standards guide emission control in chemical finishing operations. The Kansai region around Osaka maintains specialized polyurethane dispersion capacity for coated fabric applications.
India
Technical textile penetration in geotextiles and protective fabrics is expanding synthetic adhesive bonding specifications. BIS quality standards and state-level pollution control mandates are tightening formulation compliance. Gujarat chemical manufacturing zones are attracting acrylic emulsion investments serving domestic nonwoven growth.
Textile Binders Market Competitive Environment
The competitive structure tilts toward integrated chemical conglomerates with captive acrylic acid supply. BASF SE and Dow Inc. exemplify this archetype through backward integration into propylene derivatives. Three strategic archetypes dominate: integrated petrochemical players controlling raw material access, specialized dispersion formulators serving technical textile niches, and regional emulsion suppliers competing on logistics proximity. Competitive moves concentrate on water-based line conversions and modular formulation packaging to simplify buyer procurement.
Among European-based chemical conglomerates, BASF SE, Evonik Industries AG, and Covestro AG occupy positions defined by polymer chemistry breadth and regulatory compliance infrastructure. BASF SE exemplifies the integrated archetype through its acrylic acid chain control. Evonik Industries AG represents specialty dispersion expertise. Covestro AG anchors the polyurethane-focused tier. These three sit within a structure where scale advantages in water-based reformulation are compressing mid-tier solvent-dependent competitors.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Eastman Chemical Company |
| BASF SE |
| Huntsman International LLC |
| Solvay SA |
| Dow Inc. |
| Covestro AG |
| Wacker Chemie AG |
| Arkema SA |
| Others |
Value Chain & Pricing Dynamics
Water-based acrylic reformulation is simultaneously elevating capital requirements for compliant production lines and compressing supplier margins as MEE enforcement in China's Yangtze River Delta eliminates solvent-based alternatives. This dual pressure concentrates pricing power among integrated producers with captive acrylic acid supply while forcing mid-tier competitors toward contract manufacturing or exit.
Pricing Analysis
Margin tightening in standard-grade acrylic emulsions reflects propylene oxide derivative volatility and REACH authorization-driven reformulation costs. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and volume commitment. Pricing pressure stems from buyer consolidation among multinational nonwoven producers demanding volume-tiered contracts. Home textile manufacturers exhibit highest price sensitivity; automotive seating producers accept premium positioning for polyurethane durability specifications.
Supply Chain Analysis
Formulation chemist scarcity in Germany's North Rhine-Westphalia and China's Zhejiang provinces constrains water-based line conversion velocity. Supply concentrates in China, Germany, and the United States, with acrylic acid derivatives drawing from propylene oxide units, glyoxal crosslinkers, and polycarbodiimide alternatives. Single-source vulnerability sits with upstream petrochemical feedstock concentration. Distribution runs through direct mill supply contracts with hygiene and medical nonwoven producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic acid supply concentration props pricing across compliant water-based grades, with unplanned propylene oxide outages transmitting volatility into binder raw material costs that integrated producers capture as margin.
For Market Incumbents: Anticipate REACH sunset dates for legacy solvent chemistries by accelerating water-based platform certification ahead of authorization deadlines. Secure captive acrylic acid supply through backward integration or long-term offtake agreements with propylene oxide producers. BASF SE's integrated chain exemplifies the margin protection this lever provides against feedstock volatility. For New Entrants and Emerging Players: Hybrid acrylic-polyurethane copolymer technology offers entry into automotive electric vehicle seating specifications where abrasion resistance and aesthetic flexibility converge. Target construction geotextile applications in India and infrastructure stabilization fabrics in China where synthetic adhesive bonding specifications are expanding fastest. Partner with regional nonwoven producers on single-package modular formulation trials to bypass established supplier qualification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking water-based formulation capabilities. Five-to-ten year viability favors suppliers with certified REACH and EPA compliance infrastructure already deployed. Monitor MEE enforcement intensity in the Yangtze River Delta as the inflection signal for domestic Chinese capacity rationalization and cross-border acquisition windows.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Line Conversion | MEE enforcement in China's Yangtze River Delta eliminates solvent-based production alternatives. |
| Backward Integration into Acrylic Acid | Captive propylene oxide derivative supply insulates margins from upstream petrochemical volatility. |
| Hybrid Copolymer Platform Development | Acrylic-polyurethane unification captures automotive electric vehicle interior trim specifications. |
| Single-Package Modular Formulation | Integrated crosslinking additives simplify procurement workflows for consolidated nonwoven buyers. |
| REACH Pre-Authorization Investment | Early water-based platform certification ahead of sunset dates locks out solvent-dependent competitors. |
Study Parameters
Independent corroboration across plant managers at acrylic emulsion facilities, procurement leads at hygiene nonwoven manufacturers, and distribution channel partners in China and Germany underwrites the qualitative findings. Technical R&D directors at polyurethane dispersion specialists and regulatory affairs leads navigating REACH authorization timelines provided primary perspective. Secondary validation drew from ECHA substance authorization databases, EPA Toxic Substances Control Act filings, ACC and Cefic chemical industry reports, and customs trade flow records. Bottom-up capacity assessments triangulated against top-down consumption estimates across polymer chemistry segments.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include polymer chemistry family, application method, regulatory compliance tier, end-use industry, and regional production hub classification. CAGRs derive from slope analysis of normalized consumption trends against capacity expansion announcements and substitution elasticity estimates. Industry-specific forecast inputs incorporate MEE enforcement intensity projections and REACH authorization timeline probabilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt propylene oxide supply disruption or accelerated REACH sunset date advancement. Forecasts reflect assumptions documented in capacity utilization trajectories and regulatory compliance cost curves. Material deviation in MEE enforcement intensity or REACH authorization pacing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market