
 Global Contact Adhesives Market | 2026-2036
Global Contact Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contact Adhesives Market Analysis
China is rewriting capacity dynamics in contact adhesive supply as domestic producers scale solvent-free and water-based output for regional consumption. Henkel AG & Co. KGaA leverages its European R&D footprint to sustain technology leadership in reactive polyurethane systems. H.B. Fuller Company anchors North American distribution through direct contractor channels and specification-grade product positioning. Sika AG competes aggressively in construction-grade formulations, extending its geographic footprint into Southeast Asian infrastructure projects.
Contact adhesives are one-component or two-component bonding systems formulated with polychloroprene, polyurethane, or natural rubber solids dissolved in solvents or dispersed in aqueous media, achieving structural strength through crystallization or chemical crosslinking upon solvent evaporation or moisture curing. These formulations deliver immediate tack and high green strength, serving primary industrial purposes in bonding decorative laminates, rubber gaskets, footwear components, and automotive interior assemblies where clamping is impractical. Solvent-based systems still dominate volume in emerging markets due to substrate compatibility and open-time flexibility, though water-based technologies are capturing specification-driven demand in European and North American woodworking applications. Hot melt contact adhesives represent the fastest-growing product category, displacing conventional solvent systems in packaging and assembly operations where factory emission controls are tightening.
The EPA enforces volatile organic compound limits under National Emission Standards for Hazardous Air Pollutants that directly restrict solvent-based adhesive formulations in US manufacturing facilities. REACH registration requirements and the EU Green Deal's chemical sustainability targets are accelerating reformulation investments among suppliers serving European automotive and construction end users. China's MEE implements dual carbon goals that tighten emission permits for solvent-intensive adhesive production in coastal provinces. Stakeholders must monitor regulatory divergence between jurisdictions to determine where captive formulation capacity or technology licensing delivers superior returns.
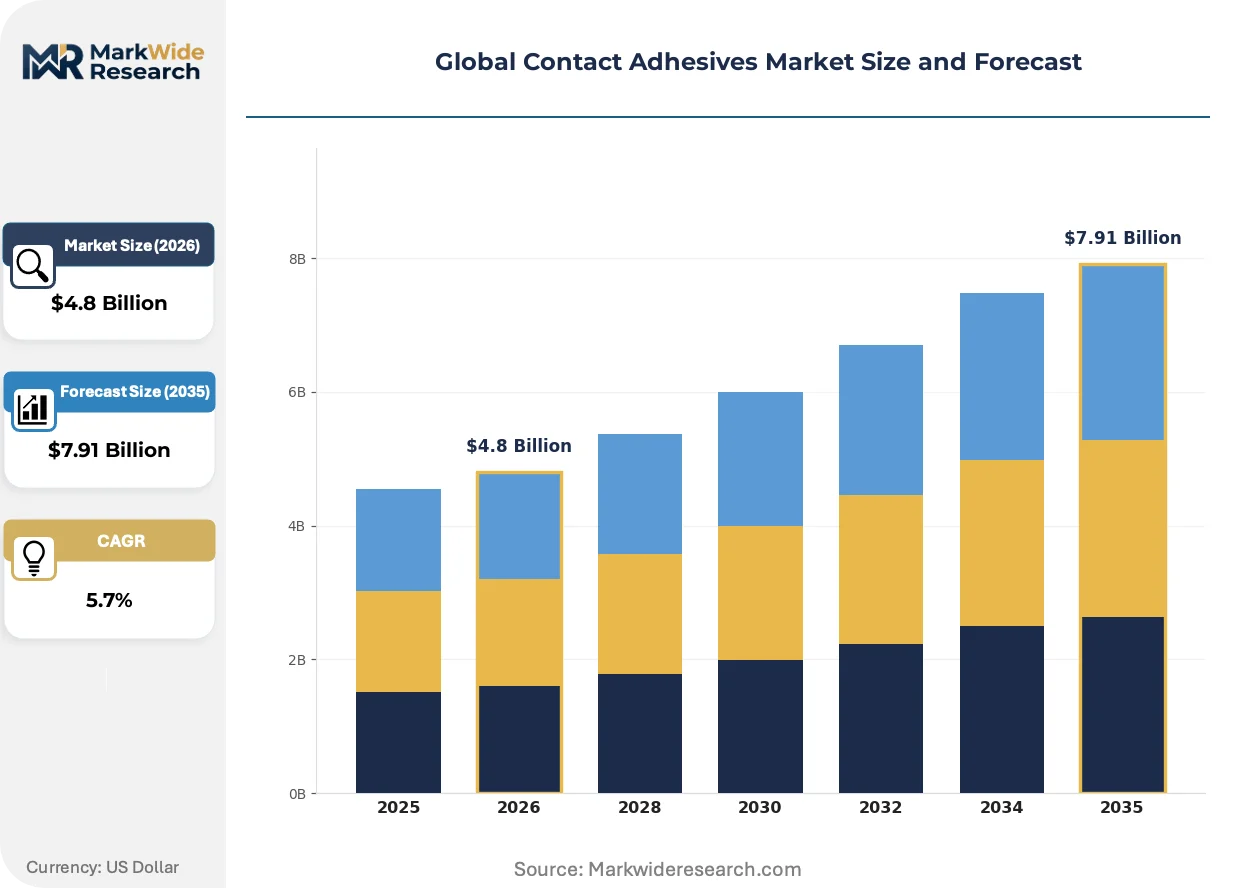
Market Dynamics
Automotive lightweighting mandates and tightening volatile organic compound limits across the US, EU, and China are forcing simultaneous reformulation and application expansion in contact adhesive supply chains. Suppliers must balance immediate green-strength performance with solvent reduction while scaling capacity for electric vehicle assembly lines.
Growth Catalysts
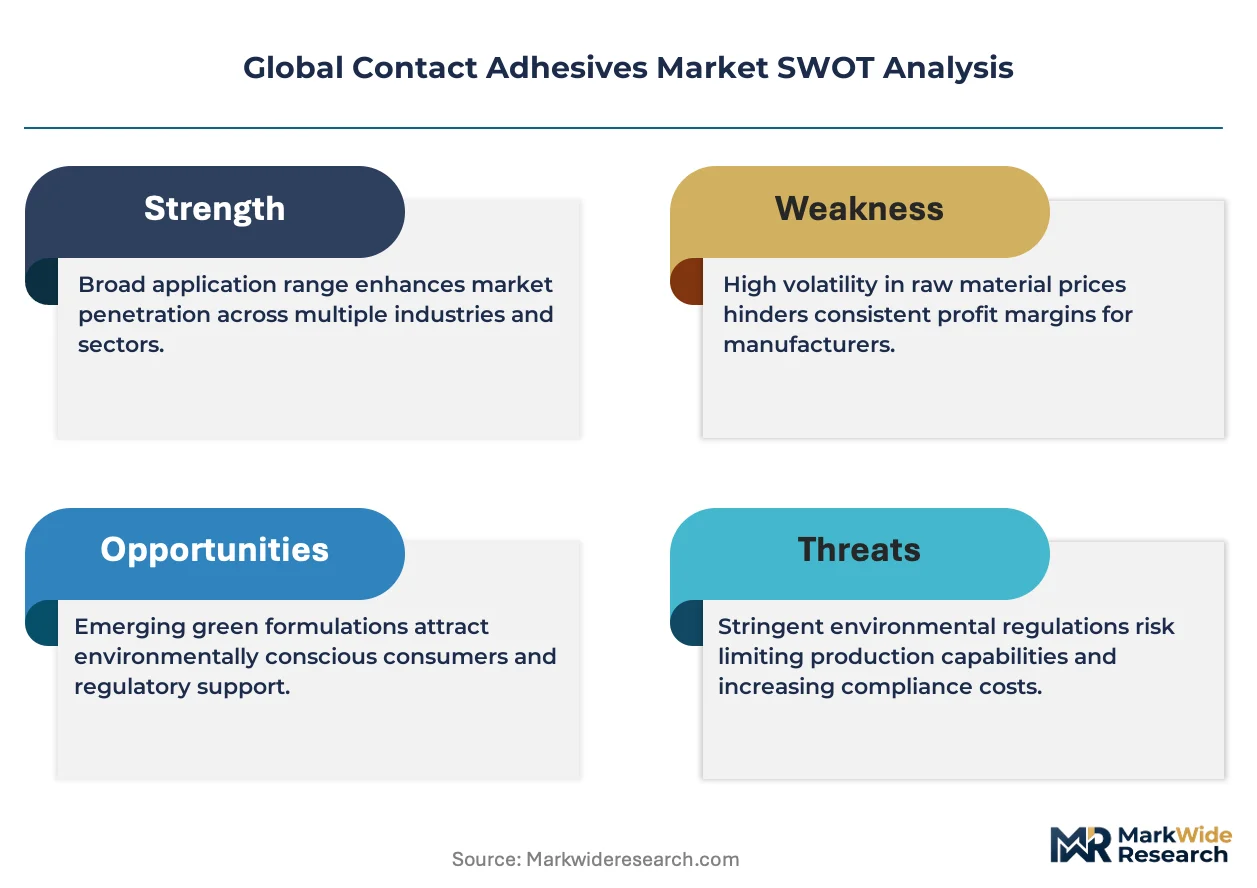
- EPA NESHAP enforcement:US manufacturing facilities face stricter emission controls that accelerate capital deployment into low-VOC application equipment, expanding addressable demand for compliant formulations.
- Electric vehicle interior assembly:Bonding of composite trim panels and acoustic insulation in battery-electric platforms requires contact adhesives that cure without heat exposure near sensitive electronics.
- China's coastal province expansion:Zhejiang and Guangdong manufacturers are scaling water-based polychloroprene output to serve domestic woodworking and footwear export demand.
Market Restraints
- Petrochemical feedstock volatility:Polychloroprene and isocyanate price swings compress formulation margins and complicate long-term contracting with automotive tier suppliers.
- Solvent substitution technical limits:Water-based systems fail to achieve equivalent open time and substrate penetration on oily woods and certain rubber compounds, preserving solvent dependence in key applications.
- MEE permitting bottlenecks:China's Ministry of Ecology and Environment has frozen new solvent-intensive production licenses in the Yangtze River Delta, constraining regional supply elasticity.
Strategic Opportunities
- India construction-grade penetration:Commercial real estate development in Mumbai and Bangalore creates specification demand for laminate bonding systems currently served by informal adhesive channels.
- Hot melt contact technology convergence:Reactive polyurethane hot melts combining immediate tack with moisture-cured durability are capturing automotive seating and headliner assembly from conventional solvent systems.
- EU Green Deal chemical sustainability targets:REACH registration incentives favor bio-based feedstock adoption, rewarding early movers in natural rubber and bio-polyurethane development.
Industry Challenges
- Formulation chemist scarcity:Expertise in balancing crystallization kinetics with emission compliance has concentrated among senior technical staff approaching retirement in European and Japanese suppliers.
- Dual certification timelines:Automotive OEMs require simultaneous IATF 16949 and OEM-specific adhesive approvals that extend qualification cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contact Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, Hot Melt, Cyanoacrylate Application: Construction, Woodworking, Automotive, Electronics End User: Manufacturers, Contractors, DIY Enthusiasts, Aerospace Technology: Thermal, Pressure-sensitive, Reactive, Solvent |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Arkema (Bostik), 3M, Huntsman International LLC, Illinois Tool Works Inc., Pidilite Industries Ltd, Jowat Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contact Adhesives Market Emerging Trajectories
Reactive hot melt systems and bio-based feedstocks are collapsing traditional technology boundaries while regulatory pressure compresses reformulation timelines. Suppliers now compete on application engineering integration rather than standalone product performance.
Moisture-curing reactive polyurethane hot melts are collapsing the performance gap between solvent-based contact adhesives and conventional hot melts in automotive interior assembly. Tier 1 seating suppliers in Germany and the US Midwest are qualifying these systems for headliner and trim panel bonding to eliminate solvent handling infrastructure. The technology is collapsing capital requirements for emission-compliant production lines while maintaining the immediate green strength that assembly operations require.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are accelerating bio-based feedstock validation in European supply chains. Formulators must demonstrate carbon footprint reduction across the full life cycle to retain automotive and construction specification positions. Nordic and Benelux woodworking applications are most affected, with buyers now requiring Environmental Product Declarations as standard tender documentation.
Automotive OEMs are consolidating adhesive procurement through direct specification relationships rather than delegating to tier suppliers, compressing the traditional distribution channel. Tier 2 formulation houses in Michigan and Stuttgart are losing specification influence as Volkswagen, Ford, and BMW centralize materials engineering decisions. This pattern is most visible in North America and Western Europe where platform standardization across multiple assembly plants enables centralized sourcing leverage.
Global Contact Adhesives Market Segmentation
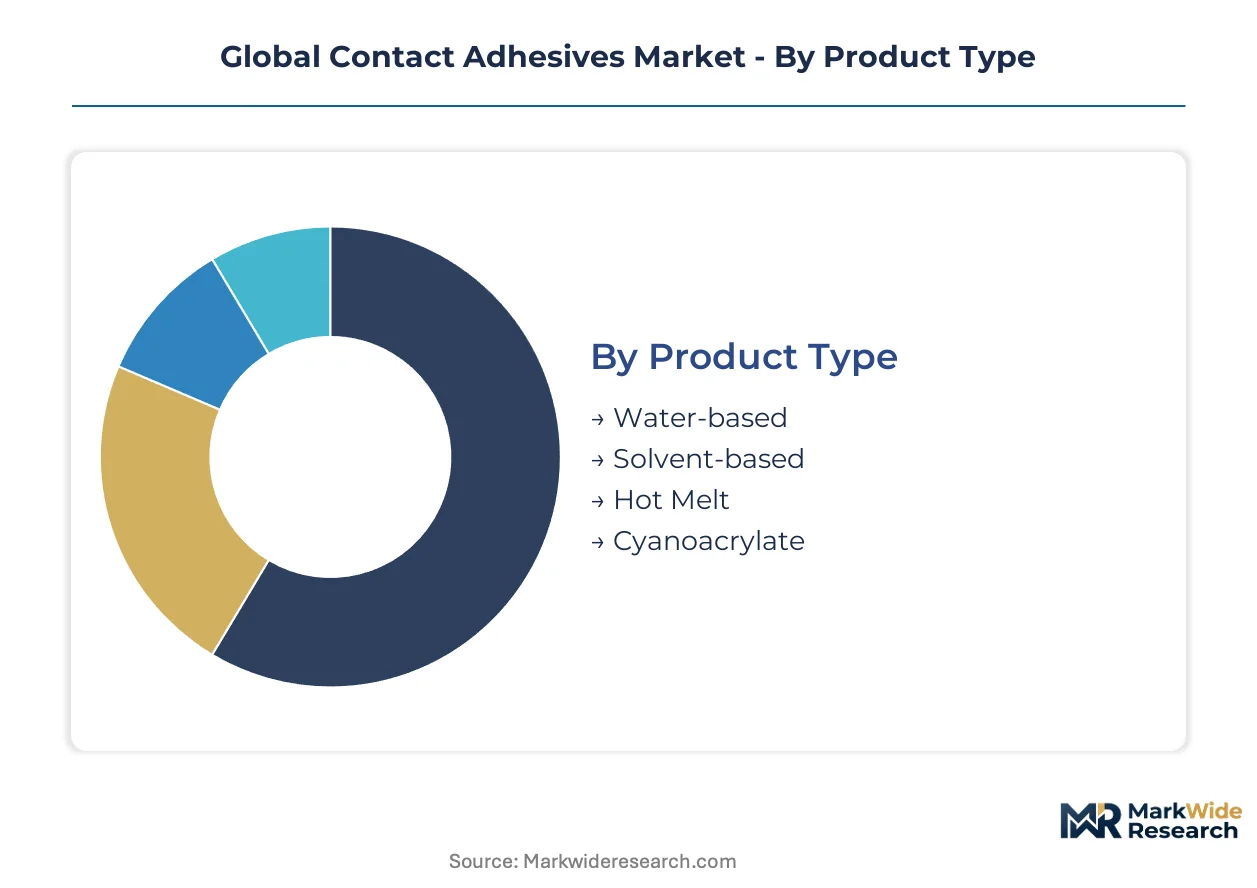
Contact adhesive procurement patterns diverge sharply across formulation chemistry and end-use specifications. Understanding these fault lines reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Mature solvent systems coexist with emerging water-based and hot melt alternatives as regulatory pressure reshapes acceptable trade-offs between performance and compliance.
- Solvent-based:Polychloroprene and polyurethane solids dissolved in aromatic or aliphatic hydrocarbons deliver unmatched open time and substrate penetration on oily woods and rubber compounds. Demand persists in emerging markets and legacy automotive assembly where EPA NESHAP enforcement has not yet forced capital replacement.
- Hot Melt:Reactive polyurethane systems combine immediate green strength with moisture-cured durability, collapsing the traditional performance gap with solvent alternatives. German Tier 1 seating suppliers are qualifying these for headliner bonding to eliminate solvent handling infrastructure entirely.
- Water-based:Aqueous polychloroprene dispersions serve European woodworking specifications where REACH compliance blocks solvent procurement.
- Cyanoacrylate:Instant-bonding formulations capture electronics assembly applications requiring thin-film adhesion without clamping fixtures.
Solvent-based formulations retain volume leadership; hot melt systems hold the steepest expansion curve as factory emission controls tighten.
Application:
Application requirements range from structural load-bearing in construction to precision bonding near sensitive electronics, dictating divergent formulation specifications and approval cycles.
- Automotive:Bonding of composite trim panels and acoustic insulation in battery-electric platforms requires contact adhesives that cure without heat exposure near sensitive electronics. OEMs in Stuttgart and Michigan are consolidating procurement through direct specification relationships.
- Construction:Laminate bonding for commercial interiors and infrastructure projects demands specification-grade products with documented Environmental Product Declarations under EU Green Deal procurement rules.
- Woodworking:Decorative laminate and veneer bonding in Nordic and Benelux markets now mandates bio-based feedstock validation and full life-cycle carbon disclosure.
- Electronics:Miniaturized assembly operations require low-outgassing formulations compatible with precision dispensing equipment and cleanroom protocols.
Construction-grade applications generate the broadest revenue base; automotive bonding is climbing the fastest as electric vehicle platforms multiply.
End User:
Customer types span from specification-driven OEMs with 18-24 month qualification cycles to price-sensitive DIY channels with minimal technical support requirements.
- Manufacturers:Tier 1 automotive and furniture producers demand IATF 16949 certification, batch traceability, and direct technical service support for production line integration.
- Contractors:Commercial construction installers in Mumbai and Bangalore create specification demand for laminate bonding systems currently served by informal adhesive channels.
- DIY Enthusiasts:Retail-packaged formulations for home repair and craft applications prioritize convenience and safety labeling over performance optimization.
- Aerospace:MRO operations and interior retrofit programs require flame-retardant specifications and full material certification documentation.
Manufacturers command the highest specification premiums; contractor channels are expanding most quickly as commercial real estate development accelerates in South Asia.
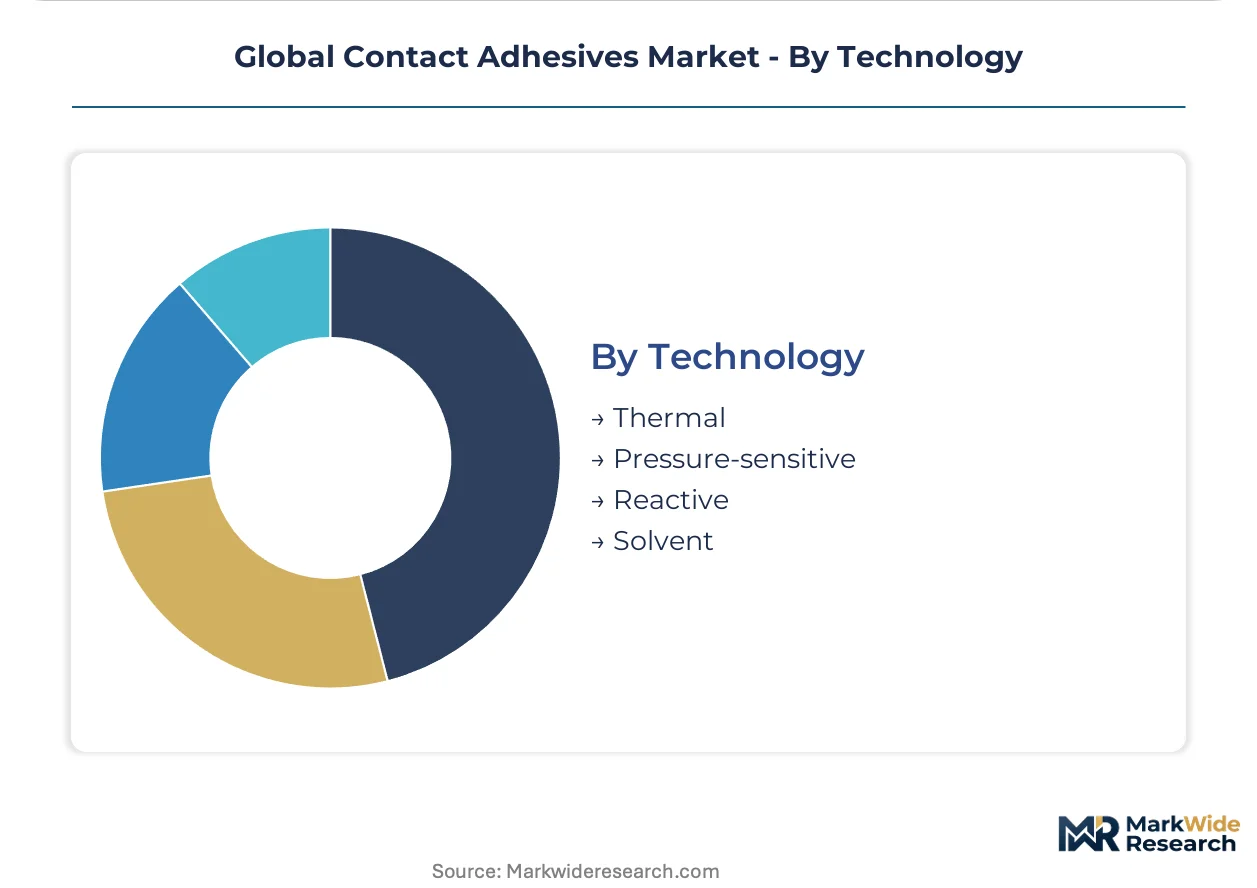
Technology:
Technology selection determines capital intensity, emission profile, and bonding mechanism—crystallization, chemical crosslinking, or physical tack development.
- Reactive:Moisture-curing polyurethane systems achieve structural strength through chemical crosslinking, delivering durability in demanding automotive and construction applications.
- Solvent:Evaporation-driven crystallization of polychloroprene or natural rubber solids produces immediate green strength without equipment investment, though emission controls are constraining new capacity permits.
- Thermal:Heat-activated systems serve niche applications where substrate temperature tolerance permits bonding cycle acceleration.
- Pressure-sensitive:Permanent tack formulations enable repositionable assembly operations in electronics and temporary fixture applications.
Reactive technology captures the highest value per kilogram; solvent systems remain dominant in absolute volume despite regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement under NESHAP anchors the United States as the regulatory benchmark for emission-compliant adhesive procurement, while China's MEE dual carbon goals and the EU Green Deal's chemical sustainability targets reshape capacity investment across three continents.
United States
Automotive OEMs in Michigan and Ohio are consolidating adhesive procurement through direct specification relationships for electric vehicle interior assembly. EPA NESHAP enforcement accelerates capital deployment into low-VOC application equipment across Midwest manufacturing facilities. Detroit-Windsor corridor suppliers are qualifying reactive polyurethane hot melts to eliminate solvent handling infrastructure.
China
Domestic electric vehicle production and commercial construction are concentrating demand for water-based polychloroprene formulations. MEE permitting bottlenecks have frozen new solvent-intensive production licenses in the Yangtze River Delta. Zhejiang and Guangdong manufacturers are scaling solvent-free and water-based output to serve regional woodworking and footwear export demand.
Germany
Tier 1 seating suppliers in Stuttgart are qualifying moisture-curing reactive polyurethane hot melts for headliner and trim panel bonding. REACH registration requirements and EU Green Deal chemical sustainability targets accelerate reformulation investments among suppliers serving automotive end users. Bavarian woodworking applications now mandate Environmental Product Declarations as standard tender documentation.
India
Commercial real estate development in Mumbai and Bangalore creates specification demand for laminate bonding systems. BIS standards and evolving emission norms pressure informal adhesive channels toward compliant formulations. Maharashtra and Karnataka contractors are shifting from unbranded solvent products to specification-grade construction adhesives.
Japan
Precision electronics assembly requires low-outgassing formulations compatible with cleanroom protocols. METI industrial standards and JIS certification requirements maintain high technical barriers to specification-grade supply. Kanto region manufacturers are integrating contact adhesives into automated dispensing systems for miniaturized component bonding.
Global Contact Adhesives Market Vendor Landscape
Capability concentration sits with European and Japanese specialists who command formulation chemistry expertise; scale advantage sits with diversified chemical conglomerates who leverage global distribution infrastructure. The vendor base organizes around three strategic archetypes: integrated adhesive specialists with captive resin production, diversified industrial conglomerates with cross-sector technology platforms, and regional formulation houses serving price-sensitive emerging markets. M&A activity targets water-based technology assets in Europe and North America, while capacity expansion concentrates in coastal Chinese provinces serving domestic electric vehicle supply chains.
Within the integrated specialist tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify divergent geographic anchoring strategies. Henkel occupies a position shaped by European R&D footprint and reactive polyurethane system leadership. H.B. Fuller represents North American distribution strength through direct contractor channels. Sika AG sits within the construction-grade formulation segment, extending geographic presence into Southeast Asian infrastructure markets. These three anchors illustrate how technology specialization and regional channel control determine competitive positioning.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Arkema (Bostik) |
| 3M |
| Huntsman International LLC |
| Illinois Tool Works Inc. |
| Pidilite Industries Ltd |
| Jowat Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European solvent-based adhesive production is driving suppliers toward premium pricing for compliant formulations while forcing buyers to absorb reformulation costs or shift sourcing geography. This utilization squeeze rewards early movers in water-based capacity and compresses margins for legacy producers locked into emission-intensive assets.
Pricing Analysis
Geographic price spreads between Chinese water-based output and European specification-grade formulations now exceed transport-adjusted differentials, reflecting regulatory compliance premiums. Three-tier pricing structure across specification-grade, industrial-standard, and commodity-economy levels separates automotive OEM contracts from construction bulk procurement and informal channel supply. Price differentiation rests on REACH certification tiers and volume scale commitments, with automotive tier suppliers showing least sensitivity due to 18-24 month qualification lock-in. Cost compression in commodity solvent tiers is intensifying because MEE permitting bottlenecks in Zhejiang are constraining regional supply elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Henkel's European captive facilities, H.B. Fuller's North American plants, and Sika's integrated construction-grade operations across Germany and China. Geographic supply concentration centers on China for water-based polychloroprene, Germany for reactive polyurethane systems, and the US Midwest for automotive hot melt qualification. Raw material dependencies hinge on petrochemical feedstocks from Gulf Coast crackers, isocyanate supply from BASF and Covestro, and natural rubber sourcing from Southeast Asian processors. Single-source vulnerability runs through isocyanate intermediates where European production rationalization has consolidated supply. Distribution runs through direct specification relationships with automotive OEMs and contractor channels in commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive hot melt technology is collapsing the performance gap with solvent systems while EPA NESHAP enforcement accelerates capital replacement cycles, creating a high-growth disruption window for formulation specialists with compliant product pipelines.
For Market Incumbents: Entrench specification influence through IATF 16949 certification investments and direct OEM engineering relationships before automotive procurement consolidation eliminates tier supplier intermediation. Backward integration into captive polychloroprene or polyurethane resin production defends margin position against petrochemical feedstock volatility. Prioritize capacity addition in Zhejiang and Guangdong to capture China's domestic electric vehicle supply chain demand. For New Entrants and Emerging Players: Establish a beachhead in India's commercial construction laminate bonding segment where BIS standards are pressuring informal solvent channels toward specification-grade alternatives. Target water-based woodworking applications in Nordic markets where Environmental Product Declaration requirements now gate tender participation. Pursue licensing partnerships with European R&D houses to shortcut 18-24 month automotive qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across reactive hot melt production as equipment standardization eliminates custom solvent handling infrastructure. Long-term viability favors specialists with bio-based feedstock validation and REACH registration assets over commodity solvent formulators facing stranded capacity risk. Acquisition target archetype: mid-tier European water-based technology holders with automotive specification positions but limited geographic scale. Monitor MEE permitting announcements in Yangtze River Delta provinces as inflection indicator for Chinese supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Water-based and hot melt capacity investments capture EPA NESHAP compliance premiums in US Midwest automotive corridors. |
| Backward Integration | Captive polychloroprene or polyurethane resin production insulates margins from petrochemical feedstock volatility. |
| Long-term Supply Agreement | Direct specification relationships with Volkswagen or Ford lock in 18-24 month automotive qualification cycles. |
| Joint Venture | Technology licensing partnerships with Zhejiang manufacturers accelerate access to China's domestic electric vehicle supply chains. |
| Capacity Expansion | Solvent-free output scaling in coastal Chinese provinces serves woodworking and footwear export demand under MEE dual carbon goals. |
Methodological Framework
A spread of perspectives from adhesive formulation chemists, automotive tier supplier procurement leads, construction contractor purchasing managers, and EPA compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with plant managers at German and Chinese production facilities, technical R&D directors at European specialists, and distribution channel partners serving Mumbai and Bangalore construction markets. Secondary validation drew from SEC 10-K filings of listed chemical conglomerates, customs and trade data tracking polychloroprene and isocyanate flows, ACC and Cefic industry reports, and REACH registration databases. Bottom-up demand modeling across end-use segments was triangulated against top-down capacity assessments from major production hubs.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning formulation chemistry, application vertical, end-user type, and technology mechanism. Automotive content-per-vehicle estimates for electric platform interior bonding, construction square footage projections for commercial real estate development, and woodworking specification adoption curves informed volume build-ups. CAGRs were derived from regression analysis of historical capacity utilization against regulatory enforcement intensity, with scenario weighting for MEE permitting trajectories and EPA NESHAP compliance cost pass-through assumptions.
Sensitivities concentrate around petrochemical feedstock price volatility, MEE permitting timeline shifts, and automotive OEM platform standardization decisions that could compress or extend qualification cycles. Forecasts reflect assumptions about reactive hot melt technology adoption rates, bio-based feedstock cost parity timelines, and regional regulatory enforcement consistency. Quarterly review of isocyanate contract pricing, Zhejiang provincial emission permit issuance, and automotive OEM specification bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market