
 Global Polyolefin Pipes Market | 2026-2036
Global Polyolefin Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyolefin Pipes Market Outlook
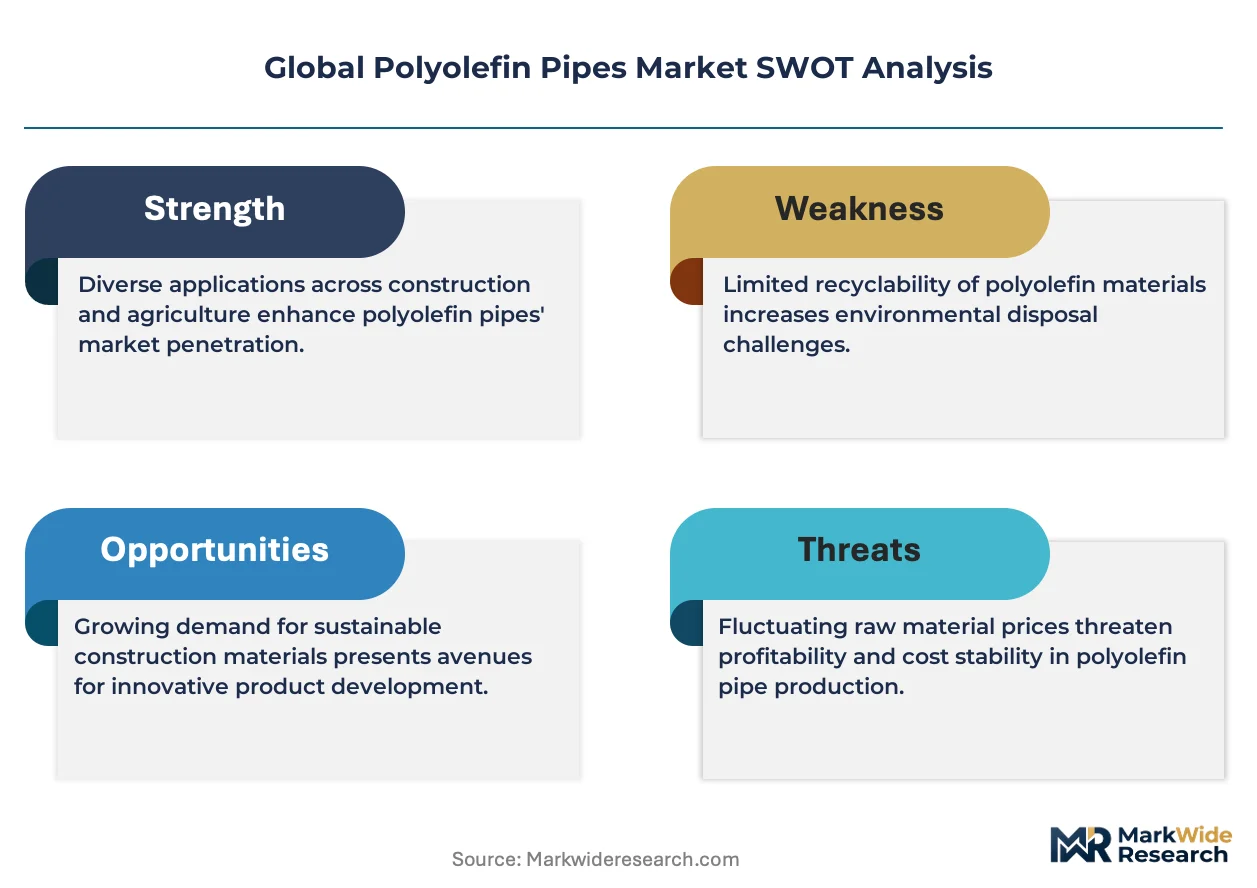
Project finance arrangements for municipal water infrastructure is reconfiguring competitive access across the polyolefin pipes value chain, allowing mid-scale contractors to bid on previously capital-intensive distribution networks. JM Eagle leverages vertical integration from resin to finished pipe to sustain margin control across volatile polyethylene cycles. WL Plastics specializes in high-density polyethylene pressure pipe for North American gas distribution, occupying a defensible niche against commodity competitors. GF Piping Systems anchors European market presence through extensive specification relationships with engineering firms and water authorities.
Polyolefin pipes are thermoplastic piping systems manufactured from polyethylene and polypropylene resins, typically extruded in diameters ranging from small-bore household plumbing to meter-scale drainage culverts, with HDPE grades offering stress-crack resistance above 500 hours per ASTM F1473. These pipes serve primarily to transport fluids and gases across water, sewage, energy, and agricultural systems with corrosion immunity and fusion-welded joint integrity. HDPE pipe commands the largest product type position due to its dominance in water supply and gas distribution applications where flexibility and trenchless installability reduce total project cost. Irrigation application growth is accelerating fastest among application categories as precision agriculture and drip-line networks expand across water-stressed growing regions. Underground installation type carries the deepest margin pool because it demands engineered wall thickness, bedding specifications, and long-term deflection performance that commodity above-ground products cannot match.
EPA drinking water standards and ASTM material specifications govern product acceptance in US municipal procurement, while REACH and the EU F-Gas Regulation shape resin formulation and additive disclosure requirements across European supply chains. China's SAMR enforces GB standards for pressure-rated pipe in infrastructure, creating a fragmented compliance landscape that favors manufacturers with multi-jurisdictional certification capabilities. Stakeholders must monitor how evolving PFAS restrictions and microplastic regulations redirect material innovation toward certified virgin resins and traceable recycling streams.
Market Dynamics
HDPE pipe specification standards are tightening across major procurement jurisdictions, forcing resin suppliers and extruders to synchronize certification documentation or face disqualification from municipal water infrastructure tenders. This compliance convergence is compressing supplier bases while elevating technical barriers to market entry.
Growth Catalysts
- Canal modernization mandates:India's federal irrigation programs are specifying large-diameter HDPE for canal lining and distribution laterals, creating sustained order flow for pressure-rated products.
- REACH material disclosure:ECHA's expanding SVHC candidate list is accelerating substitution away from legacy metal pipes toward traceable polyolefin systems with full additive transparency.
- Trenchless rehabilitation:Horizontal directional drilling methods are displacing open-cut installation in urban utility corridors, favoring flexible HDPE over rigid PVC or concrete alternatives.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins swing with crude oil benchmarks, compressing pipe extruder margins when resin contracts reset quarterly.
- Specialty additive supply concentration:Carbon black masterbatch and UV stabilizer production clusters in Northeast Asia create single-source vulnerability for compounders elsewhere.
- Stress-crack resistance thresholds:ASTM F1473 testing protocols exceeding 500 hours disqualify commodity PE80 grades from critical gas distribution applications.
Strategic Opportunities
- Indonesia's archipelago water networks:Dispersed island communities lacking centralized treatment infrastructure represent addressable demand for small-bore PE distribution systems.
- Hydrogen-ready gas infrastructure:Distribution utilities in Germany and the Netherlands are pre-qualifying HDPE formulations for blended hydrogen service at elevated pressures.
- Blockchain resin traceability:Digital chain-of-custody verification is enabling premium pricing for certified recycled content in European specification pipe.
Industry Challenges
- Fusion technician certification backlog:Butt and electrofusion welding qualifications require 40+ hours of supervised field practice, constraining installation crew scaling.
- Multi-jurisdiction specification alignment:Manufacturers serving both EPA-regulated US utilities and SAMR-governed Chinese projects must maintain parallel testing regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyolefin Pipes Market |
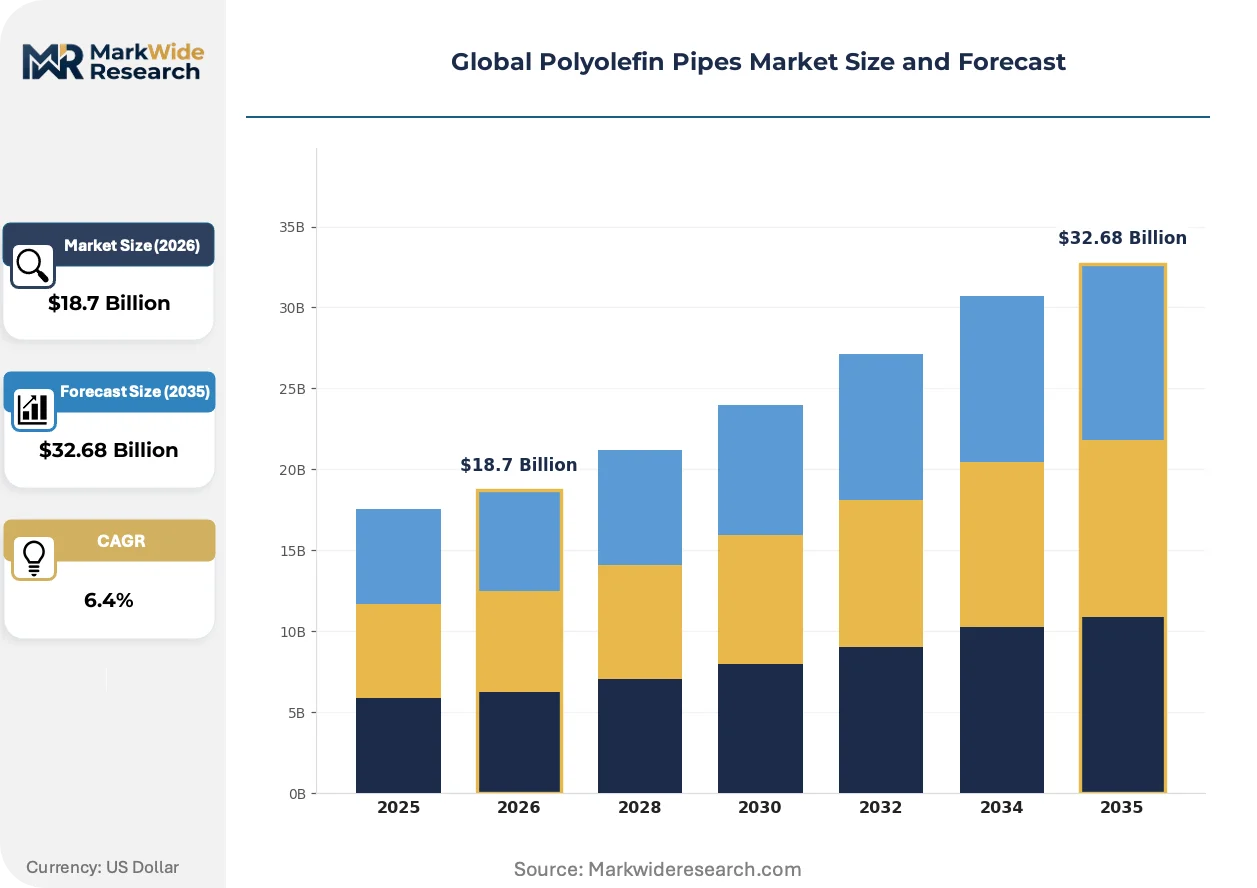
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, LDPE, PP-R, PP, Others Application: Water Supply, Sewage, Gas Distribution, Irrigation End User: Construction, Agriculture, Oil & Gas, Infrastructure Installation Type: Above Ground, Underground, Onshore, Offshore |
| Companies Covered | AGRU, GF Piping Systems, Advanced Drainage Systems, Aliaxis, JM Eagle, Aquatherm, Chevron Phillips Chemical Company, WL Plastics, Prinsco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyolefin Pipes Market Strategic Shifts
Embedded sensor integration and predictive analytics are transforming polyolefin pipes from passive conduits into monitored infrastructure assets, with leakage detection and pressure profiling becoming standard specification requirements.
Smart pipe systems incorporating fiber-optic sensing cables and distributed acoustic monitoring are digitizing condition assessment for buried water and gas networks. Municipal utilities in Singapore and Dubai are mandating real-time pressure telemetry for new trunk main installations. This instrumentation layer is digitizing maintenance scheduling and compressing failure response intervals from days to hours.
REACH Article 33 disclosure obligations and the EU F-Gas Regulation are forcing reformulation of antioxidant packages and blowing agents used in foam-core pipe insulation. Compounders are accelerating validation of bio-based stabilizers and halogen-free flame retardants. Water authority procurement in France and Belgium now requires full material passport documentation, shifting competitive advantage toward vertically integrated resin-to-pipe manufacturers with in-house analytical capabilities.
Specification-driven procurement is consolidating buyer power among engineering-procurement-construction firms managing bundled infrastructure contracts. Distributor-led spot purchasing is losing share to multi-year framework agreements with certified fabricators. This channel compression is most pronounced in Australia's urban water privatizations and Brazil's integrated sanitation concessions, where single-source accountability for pipe supply and joint integrity testing has become a tender prerequisite.
Global Polyolefin Pipes Market Segmentation
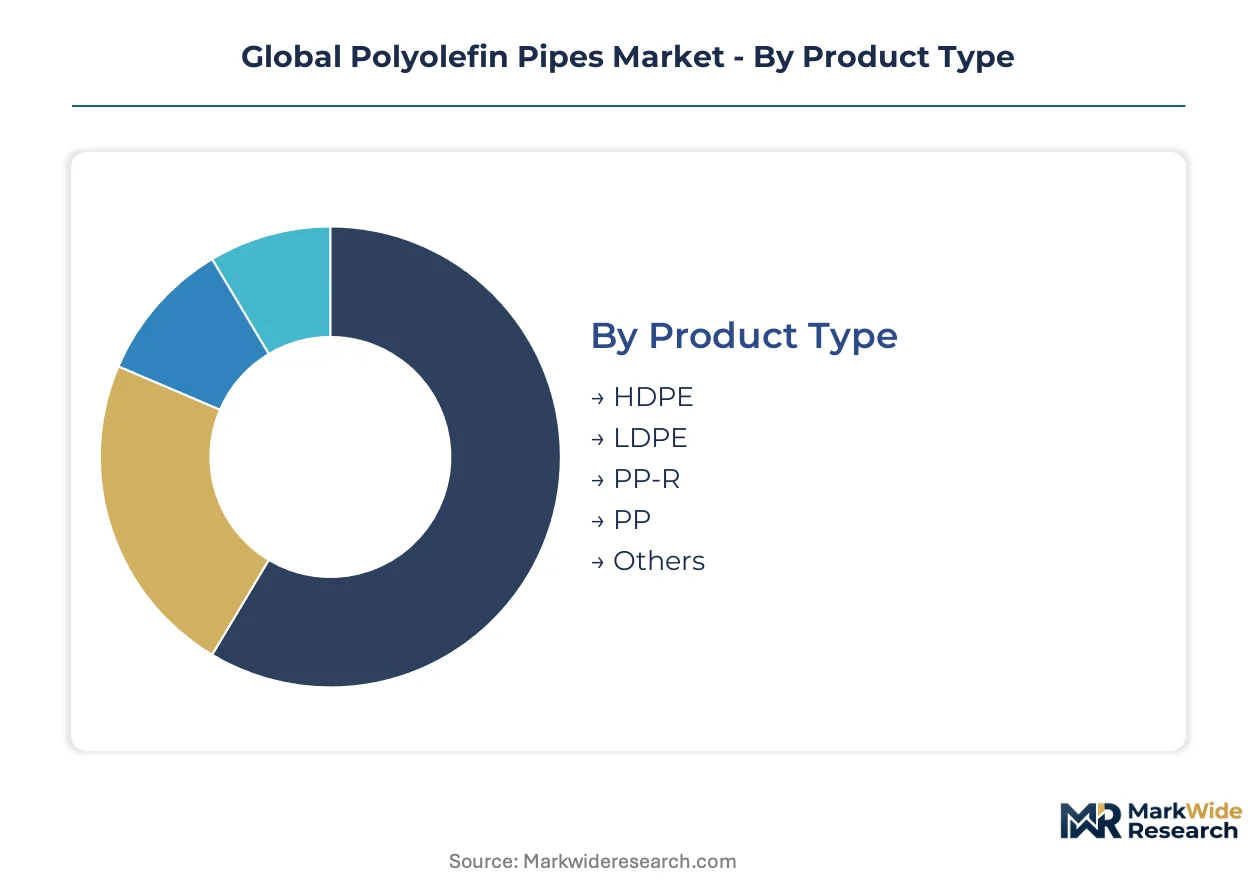
Polyolefin pipe specifications diverge sharply across pressure ratings, chemical resistance needs, and installation environments. Procurement officers segment demand by material grade, application criticality, and burial conditions to align CAPEX with service life requirements.
Product Type:
Material composition determines pressure tolerance, fusion characteristics, and regulatory acceptance across water, gas, and industrial systems.
- HDPE:High-density polyethylene delivers stress-crack resistance exceeding 500 hours per ASTM F1473, qualifying it for critical gas distribution and municipal water trunk mains. Water utilities in Southeast Asia specify HDPE for trenchless rehabilitation of aging metal networks.
- LDPE:Low-density polyethylene offers superior flexibility and elongation for drip irrigation laterals and low-pressure agricultural distribution. India's federal canal modernization programs are concentrating demand for large-diameter LDPE in surface irrigation conveyance.
- PP-R:Random copolymer polypropylene serves pressurized hot water plumbing and hydronic heating with thermal stability to 70°C. European residential construction specifications favor PP-R for potable distribution over metal alternatives.
- PP:Homopolymer polypropylene provides chemical resistance for industrial process piping and aggressive effluent transport. Chemical processing clusters in Germany specify PP for acid waste drainage.
- Others:Cross-linked polyethylene and specialty compounded grades address niche high-temperature or ultra-pure water applications.
HDPE commands the established base. The steepest expansion runs through PP-R as hydronic heating retrofits accelerate across European housing stock.
Application:
End-use function dictates wall thickness calculations, joint integrity standards, and inspection protocols throughout project lifecycles.
- Water Supply:Potable distribution systems require NSF/ANSI 61 certification and leaching compliance for direct human consumption. EPA drinking water standards govern municipal procurement specifications across US utilities.
- Sewage:Gravity and pressure sewer lines demand ring stiffness for soil loading and chemical resistance to hydrogen sulfide degradation. Dubai's sanitation infrastructure expansion is specifying HDPE for trunk sewer replacement.
- Gas Distribution:PE100 and PE80 grades for natural gas service must pass slow crack growth testing under ISO 13479 protocols. German distribution utilities are pre-qualifying formulations for blended hydrogen service.
- Irrigation:Drip-line and sprinkler networks prioritize UV stabilization and root intrusion resistance for buried agricultural deployment. Water-stressed growing regions in Spain and California are driving specification upgrades to pressure-compensating systems.
Water supply commands the established base. The steepest expansion runs through irrigation as precision agriculture penetrates water-scarce cultivation zones.
End User:
Customer category shapes order scale, specification complexity, and channel relationships from resin compounders to installation contractors.
- Construction:Residential and commercial building contractors source small-diameter plumbing and drainage through distributor networks. Multi-family housing developers in Brazil specify bundled piping packages for integrated sanitation concessions.
- Agriculture:Farm operators and irrigation districts purchase large-diameter conveyance and micro-irrigation components directly from certified fabricators. Australia's Murray-Darling Basin water recovery programs are consolidating buyer power among regional irrigation authorities.
- Oil & Gas:Upstream gathering systems and downstream process units require API-certified pipe for hydrocarbon service. Gathering line operators in the Permian Basin specify HDPE for corrosion-resistant flowline replacement.
- Infrastructure:Municipal utilities and transportation agencies procure engineered pressure pipe through engineering-procurement-construction frameworks. Singapore's national water agency mandates real-time pressure telemetry for new trunk main installations.
Infrastructure commands the established base. The steepest expansion runs through agriculture as federal irrigation modernization redirects capital toward polymer conveyance systems.
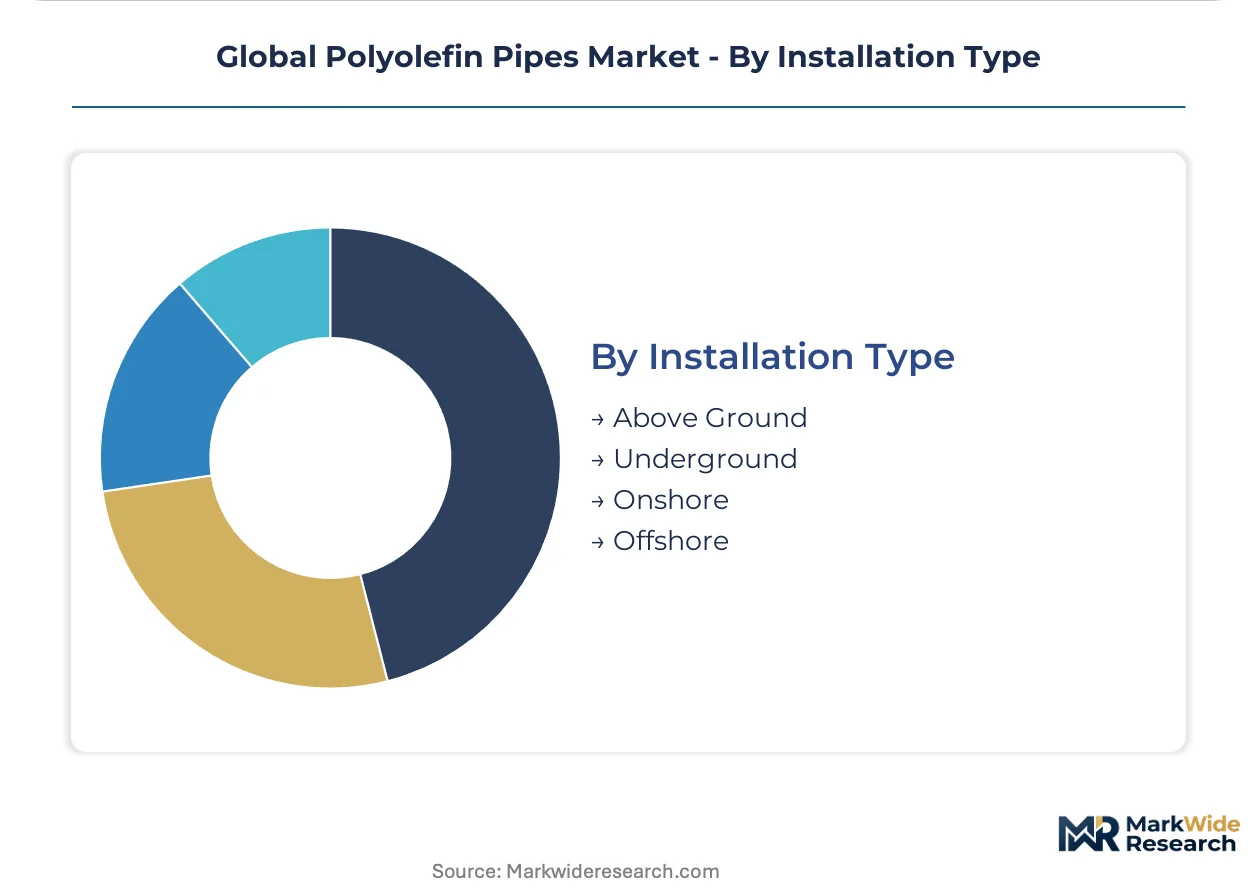
Installation Type:
Burial condition determines structural loading, bedding specifications, and long-term deflection performance requirements.
- Above Ground:Exposed installations require UV stabilization and thermal expansion accommodation for process piping and temporary conveyance. Industrial facilities in the Netherlands specify above-ground HDPE for chemical transfer skids.
- Underground:Buried systems demand engineered wall thickness and soil-structure interaction analysis for municipal water and gas distribution. Horizontal directional drilling methods are displacing open-cut installation in urban utility corridors.
- Onshore:Terrestrial pipeline routes traverse varied soil conditions requiring cathodic isolation and mechanical protection. Onshore gathering systems in West Texas specify HDPE for corrosion immunity in high-salinity soils.
- Offshore:Subsea installations require buoyancy control, marine growth resistance, and dynamic stress analysis for riser applications. Offshore aquaculture operations in Norway are deploying HDPE for submerged cage mooring and feed delivery.
Underground commands the established base. The steepest expansion runs through offshore as marine aquaculture and coastal desalination intake systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal canal modernization programs in India and EPA drinking water standards in the United States are redirecting procurement budgets toward certified HDPE infrastructure. REACH compliance in Europe and GB standards enforcement in China are synchronizing material certification requirements across major jurisdictions.
United States
Municipal water utilities are replacing aging cast-iron distribution networks with trenchless HDPE rehabilitation systems. EPA drinking water standards and ASTM material specifications govern product acceptance in federal procurement tenders. The Permian Basin in West Texas specifies corrosion-resistant HDPE for upstream gathering line replacement in high-salinity soil conditions.
Germany
Distribution utilities are pre-qualifying HDPE formulations for blended hydrogen service at elevated pressures in anticipation of energy transition infrastructure. The EU F-Gas Regulation and REACH Article 33 disclosure obligations are forcing reformulation of antioxidant packages in pipe compounds. Industrial chemical processing clusters in North Rhine-Westphalia specify homopolymer polypropylene for acid waste drainage systems.
China
SAMR enforcement of GB standards for pressure-rated pipe is fragmenting compliance landscapes and favoring manufacturers with multi-jurisdictional certification capabilities. The country's dual carbon goals are accelerating specification upgrades in municipal water infrastructure. Manufacturing concentrations in the Yangtze River Delta are scaling certified resin production for domestic pressure pipe extrusion.
India
Federal irrigation programs are specifying large-diameter HDPE for canal lining and distribution laterals, creating sustained order flow for pressure-rated products. BIS certification requirements are tightening material traceability for agricultural procurement schemes. Water supply utilities in Maharashtra and Gujarat are expanding HDPE networks to replace aging metal infrastructure in peri-urban corridors.
Indonesia
Dispersed island communities lacking centralized treatment infrastructure represent addressable demand for small-bore PE distribution systems. The country's national standards body enforces material specifications for pressure pipe in public works tenders. Infrastructure development in the Java-Bali corridor is concentrating demand for flexible piping in coastal desalination intake and distribution networks.
Global Polyolefin Pipes Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated resin-to-pipe manufacturers and specialized pressure pipe fabricators with multi-jurisdictional certification capabilities. The vendor base separates into three strategic archetypes: integrated petrochemical-pipe conglomerates controlling resin supply, regional extrusion specialists dominating specification-driven municipal tenders, and technology-focused innovators embedding sensor systems. Capacity expansion in certified PE100 compounding and strategic partnerships for hydrogen-ready formulation development represent the dominant competitive moves.
Among North American fabricators, WL Plastics occupies a defensible position in high-density polyethylene pressure pipe for gas distribution, while JM Eagle exemplifies vertical integration from resin production through finished pipe extrusion. GF Piping Systems anchors European market presence through specification relationships with engineering firms and water authorities. These three companies represent distinct competitive vectors: specialized niche defense, upstream supply control, and specification-engineering integration.
| Leading Market Players |
|---|
| AGRU |
| GF Piping Systems |
| Advanced Drainage Systems |
| Aliaxis |
| JM Eagle |
| Aquatherm |
| Chevron Phillips Chemical Company |
| WL Plastics |
| Prinsco |
| Others |
Value Chain & Pricing Dynamics
Northeast Asian carbon black masterbatch production clusters anchor compounder cost structures, pushing margin pools toward certified PE100 resin suppliers with captive additive blending capabilities. Pipe extruders face compressed spreads when naphtha-cracker margins swing, while specification-grade fabricators capture premiums through multi-jurisdictional certification maintenance.
Pricing Analysis
Certification level (ASTM F1473/ISO 13479/GB standards) creates the primary spread between commodity PE80 and engineered PE100 pressure pipe. Three-tier pricing structure across premium, standard, and economy levels reflects stress-crack resistance thresholds, fusion technician bundling, and project-scale volume discounts. Cost compression in commodity grades is intensifying because resin contract resets track quarterly naphtha benchmarks. Agricultural irrigation districts exhibit highest price sensitivity, while municipal gas utilities prioritize joint integrity guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard for distributor-of-record relationships with municipal EPC contractors. Resin compounding concentrates in China, Saudi Arabia, and the United States, with specialty UV stabilizer production tethered to Northeast Asian chemical clusters. Feedstock volatility represents the dominant structural risk, as ethylene contract prices reset against crude oil benchmarks. Distribution runs through specification-engineering relationships rather than spot-market purchasing, with certified fabricators holding inventory positions for framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyolefin pipe demand sits in early-cycle expansion as federal irrigation modernization across water-stressed regions redirects capital from metal conveyance toward polymer systems. Specification-driven procurement is compressing channel access for uncertified competitors.
For Market Incumbents: Insulate specification relationships by embedding predictive maintenance telemetry into trunk main contracts, and deepen backward integration into certified PE100 resin compounding to offset feedstock volatility. The threat of hydrogen-ready formulation pre-qualification by European utilities demands R&D investment in elevated-pressure testing protocols. For New Entrants and Emerging Players: Build out small-bore PE distribution capabilities for Indonesia's dispersed island communities lacking centralized treatment infrastructure, and target canal lining contracts within India's federal irrigation programs where BIS certification requirements are still consolidating. A go-to-market angle through electrofusion technician training partnerships addresses the certification backlog constraining crew scaling. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional extrusion specialists holding single-jurisdiction certification portfolios. Long-term viability hinges on multi-standard testing capabilities spanning EPA, REACH, and GB regimes. The signal to watch is hydrogen-ready pre-qualification momentum among German and Dutch distribution utilities.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Certified PE100 compounding additions in India address canal modernization demand from federal irrigation programs. |
| Backward Integration | In-house carbon black masterbatch production reduces Northeast Asian supply concentration vulnerability for compounders. |
| Long-term Supply Agreement | Multi-year framework contracts with Australian urban water privatizations lock out spot-market competitors. |
| Joint Venture | Sensor technology partnerships with Singapore's national water agency embed real-time telemetry as tender prerequisite. |
| Geographic Expansion | Indonesia archipelago coverage captures small-bore PE demand from dispersed coastal desalination networks. |
Study Parameters
Desk research of customs trade data, SEC filings from resin producers, and ASTM/ISO certification registries preceded structured interviews with municipal procurement officers, EPC project managers, fusion technician training directors, and pipe extruder plant managers. Primary fieldwork covered specification relationship dynamics across water utility frameworks and agricultural irrigation districts. Bottom-up volume triangulation from resin consumption data was cross-checked against top-down infrastructure budget allocations.
The forecast framework holds ethylene feedstock pricing within historical volatility bands while varying infrastructure investment intensity across the analysis window. Segmentation dimensions modeled include material grade tier, pressure rating class, installation environment, and regional regulatory cluster. CAGRs derive from compound annualization of year-over-year volume shifts. Industry-specific inputs encompass federal irrigation budget flows and REACH SVHC candidate list expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed resin producers would shift outcomes through capacity dumping or subsidized certification support. Macroeconomic deviation, regulatory acceleration of PFAS restrictions, or breakthroughs in competing trenchless rehabilitation materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
PVDF Pipes Market