
 North America Flock Adhesives Market | 2026-2036
North America Flock Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flock Adhesives Market Analytics
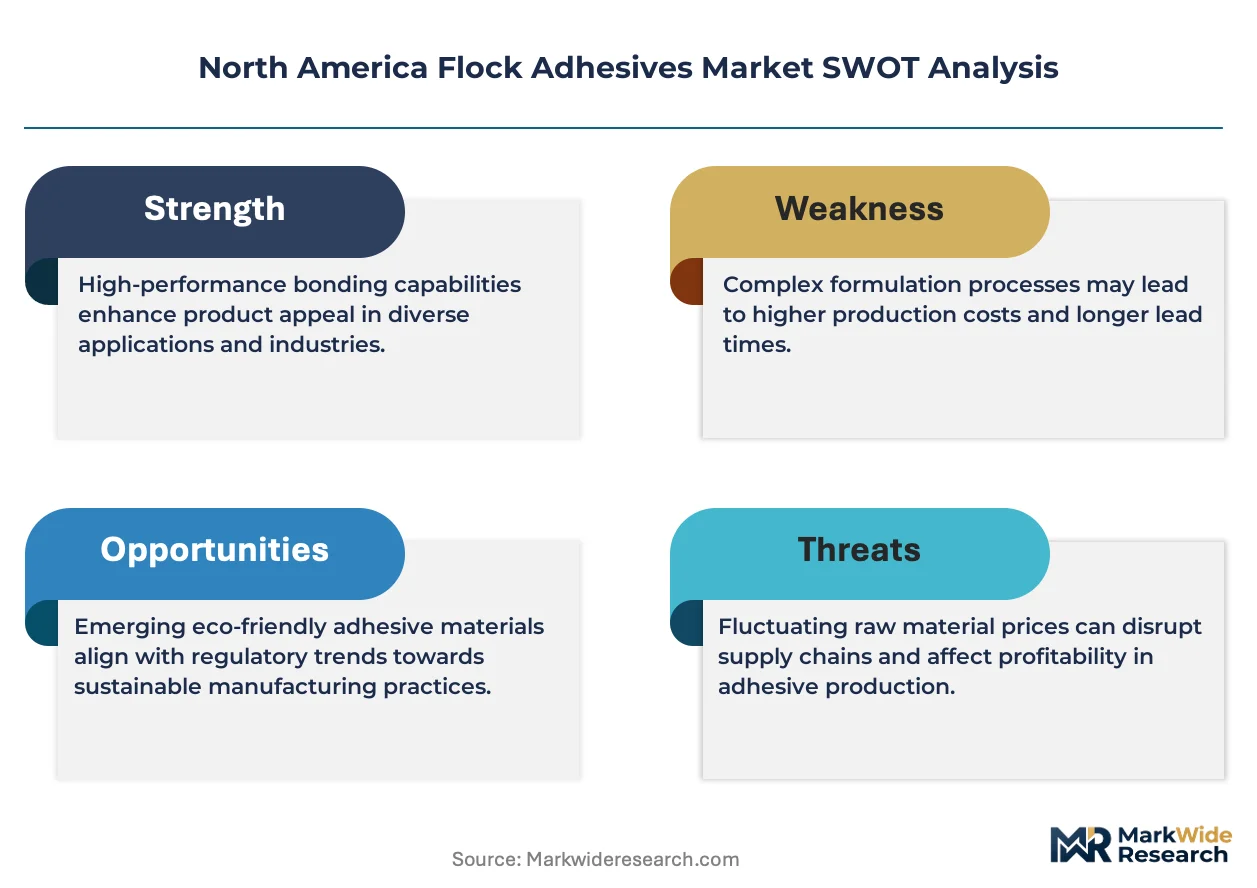
California's Air Resources Board (CARB) VOC limits for adhesive formulations is rebalancing product development priorities across the region. H.B. Fuller Company leverages its water-based technology portfolio to sustain compliance leadership in automotive applications. Dow anchors its position through upstream control over acrylic and polyurethane raw material supply. Henkel AG & Co. KGaA differentiates via specialized hot-melt systems designed for textile backing operations in the southeastern states.
Flock adhesives are bonding agents engineered to secure short fiber filaments (typically 0.3–3.0 mm in length) to substrate surfaces, with viscosities ranging from 500 to 15,000 cPs depending on application method and fiber density requirements. These formulations serve primarily to create velvet-like textures on automotive interior components, upholstery fabrics, and decorative packaging materials where tactile properties and abrasion resistance prove critical. Water-based systems command the largest volume share due to regulatory tailwinds, though reactive formulations capture disproportionate margin pools in premium automotive seating. Hot-melt adhesives represent the fastest-expanding category as manufacturers seek to eliminate drying time and reduce energy intensity in continuous coating operations.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants (NESHAP) shape permissible solvent content in industrial adhesive applications, while OSHA workplace exposure limits influence formulation choices at the plant level. Health Canada's PMRA maintains parallel standards that affect cross-border product registrations for suppliers serving both markets. Stakeholders must monitor evolving state-level chemical disclosure requirements and assess whether reactive curing investments justify the capital outlay against tightening environmental compliance timelines.
Market Dynamics
EPA NESHAP regulations and parallel California CARB VOC limits are compressing solvent-based formulation viability while elevating water-based and reactive curing systems across automotive textile bonding operations.
Growth Catalysts
- Automotive Interior Expansion:Seating manufacturers in Tennessee and Alabama are scaling velvet-texture component production for electric vehicle platforms, pulling specialized adhesive demand.
- EPA NESHAP Compliance Windows:Hazardous air pollutant standards are accelerating facility upgrades toward low-emission coating lines in Michigan and Ohio assembly plants.
- Hot-Melt Speed Advantages:Continuous coating operations are eliminating drying stages through reactive polyurethane systems, cutting energy intensity in southeastern textile mills.
Market Restraints
- Acrylic Monomer Volatility:Feedstock price swings from Gulf Coast petrochemical suppliers compress margin predictability for adhesive compounders.
- Water-Based Performance Ceilings:Humidity sensitivity and slower green-strength development limit water-based system penetration in high-speed automotive seating lines.
- Cross-Border Registration Friction:Health Canada PMRA parallel standards create dual compliance burdens for suppliers serving Ontario and Quebec textile operations.
Strategic Opportunities
- Mexico Nearshoring Momentum:Automotive seating suppliers are relocating bonding operations to Querétaro and Puebla to access USMCA tariff advantages and lower facility costs.
- UV-Curable Formulation Gaps:Energy-curable acrylate systems remain underdeveloped for flock applications, offering first-mover positioning for specialized compounders.
- California ZEV Procurement Mandates:State fleet electrification rules are expanding premium interior specifications that favor abrasion-resistant velvet textures in municipal vehicle conversions.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Polyurethane and acrylic polymerization expertise is concentrating at legacy suppliers, constraining new entrant R&D velocity.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating lines to hot-melt or water-based systems demands capital outlays that mid-tier textile processors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flock Adhesives Market |
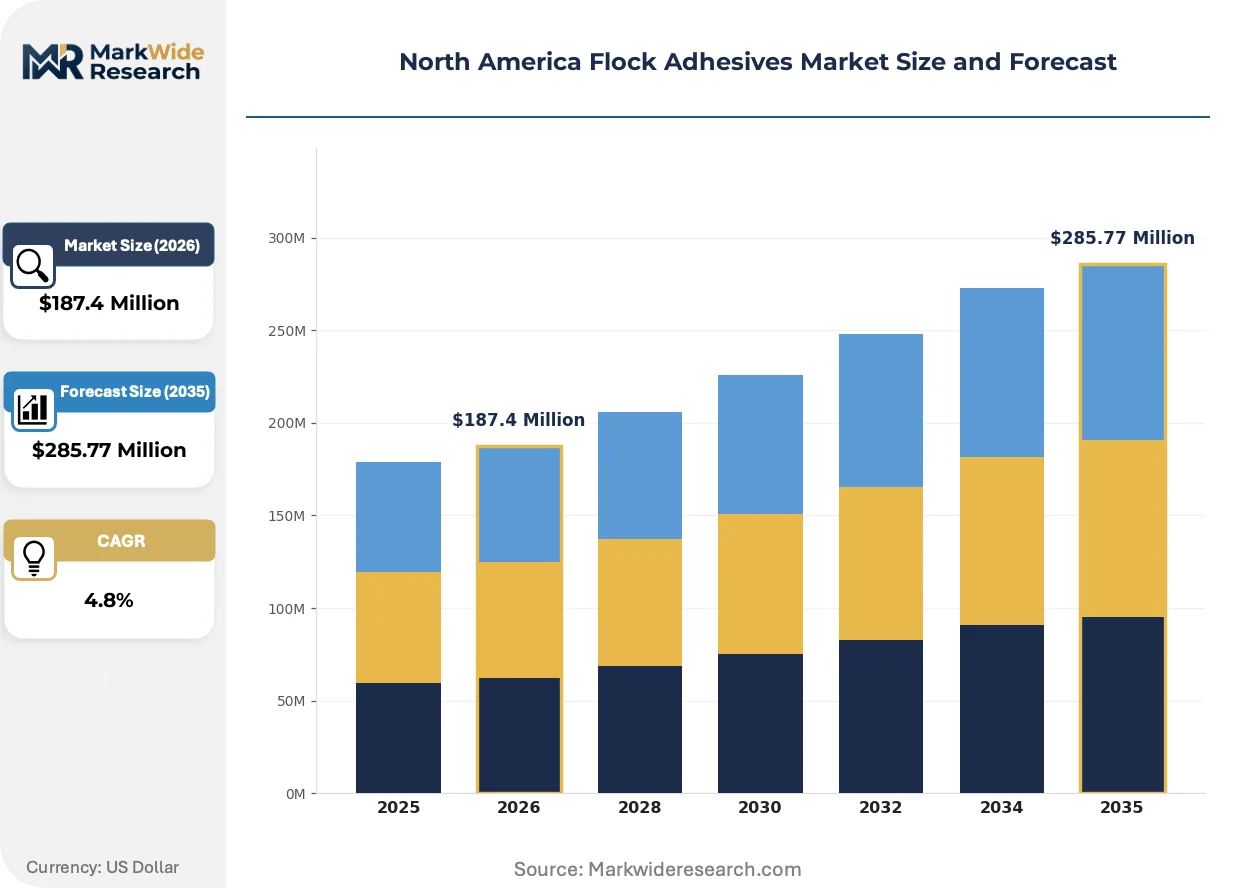
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot-Melt, Reactive End User: Textile, Automotive, Furniture, Packaging Application: Coating, Bonding, Laminating, Sealing Form: Liquid, Paste, Solid, Spray |
| Companies Covered | Parker Hannifin Corporation, Arkema, H.B. Fuller Company, International Coatings, Argent International, Henkel AG & Co. KGaA, Dow, Avient Corporation, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flock Adhesives Market Evolving Landscape
Reactive curing technologies and regulatory compliance automation are compressing traditional formulation development cycles while opening performance differentiation pathways for specialized compounders.
UV-curable acrylate oligomers are integrating into pilot production lines for decorative packaging applications, enabling instant cure speeds that eliminate thermal drying stages. Premium automotive seating suppliers in South Carolina are testing these systems for dashboard and door panel velvet textures. The technology is integrating color-stable, low-VOC finishing into previously solvent-dependent operations.
California CARB Suggested Control Measures for adhesive products are tightening VOC content thresholds ahead of federal benchmarks, forcing reformulation roadmaps that prioritize water-based and 100-percent-solids systems. Automotive Tier-1 suppliers are accelerating compliance investments to maintain state procurement eligibility. The regulation is compressing solvent-based inventory positions across West Coast distribution channels.
Automotive OEMs are consolidating adhesive specifications across platform architectures, reducing approved supplier lists from multiple regional compounders to single-source national contracts. Tier-1 seating manufacturers are responding with long-term offtake agreements that lock volume commitments and technical service support. This concentration is visible most acutely in Michigan and Tennessee assembly corridor procurement patterns.
North America Flock Adhesives Market Segmentation
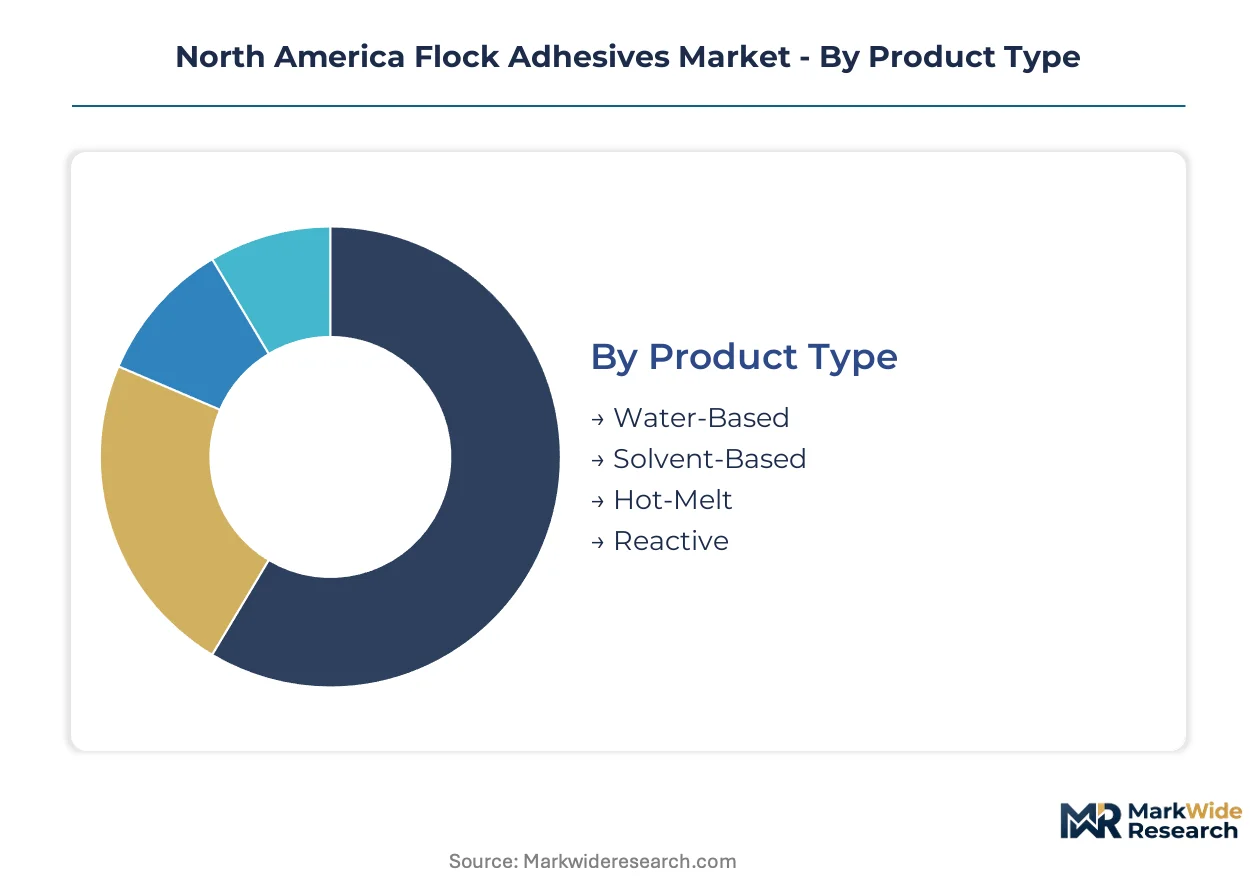
Segmentation in flock adhesives reveals how formulation chemistry, application method, and end-use requirements create distinct competitive arenas. Manufacturers configure product portfolios across these axes to match regulatory constraints in California and Michigan while capturing volume in southeastern textile corridors.
Product Type:
Formulation chemistry determines emission profiles, curing mechanisms, and performance ceilings across automotive and textile bonding operations.
- Water-Based:Acrylic and polyurethane dispersions suspended in aqueous carriers achieve viscosity ranges of 500–5,000 cPs for spray and roll-coating deployment. EPA NESHAP compliance windows in Michigan and Ohio assembly plants are accelerating specification shifts toward these systems despite humidity sensitivity during green-strength development.
- Hot-Melt:Thermoplastic formulations—primarily ethylene-vinyl acetate and reactive polyurethane variants—deliver instant tack without thermal drying stages. Tennessee and Alabama seating manufacturers are adopting these systems to eliminate energy-intensive oven lines in continuous coating operations.
- Solvent-Based:Traditional solutions of nitrocellulose or chlorinated rubber in aromatic hydrocarbon carriers retain niche positioning where rapid solvent evaporation enables high-speed textile backing.
- Reactive:Two-component polyurethane and moisture-cure silicone systems build cross-linked polymer networks delivering superior abrasion resistance for premium automotive velvet textures.
Mature deployment sits with solvent-based formulations in legacy textile mills. Newer deployment is concentrated in hot-melt systems across southeastern automotive seating corridors.
End User:
Customer concentration patterns trace regional manufacturing clusters and procurement consolidation trends.
- Automotive:Tier-1 seating suppliers in Michigan, Tennessee, and South Carolina specify adhesives for dashboard, door panel, and headliner velvet textures. OEM platform consolidation is compressing approved supplier lists toward single-source national contracts with embedded technical service requirements.
- Textile:Upholstery fabric mills in North Carolina and Georgia bond short fiber filaments to woven substrates for residential and contract furniture applications. CARB VOC thresholds are forcing reformulation roadmaps that prioritize water-based and 100-percent-solids alternatives.
- Furniture:Decorative surface applications for case goods and seating frames in Arkansas and Mississippi operate on thinner margin structures with limited R&D investment capacity.
- Packaging:Premium box and display manufacturers employ flock adhesives for tactile differentiation in cosmetic and spirits packaging, with demand concentrated in Illinois and New Jersey converting facilities.
Procurement consolidation is most advanced in automotive. Specification autonomy remains strongest in furniture.
Application:
Process method selection governs equipment capital requirements and line speed economics.
- Coating:Direct roll, knife-over-roll, and rotary screen methods apply adhesive films at controlled thicknesses before fiber embedding. Continuous coating lines in Alabama textile mills are eliminating drying stages through reactive polyurethane adoption.
- Bonding:Discrete component attachment operations for automotive interior subassemblies demand precise viscosity control and open-time management.
- Laminating:Multi-layer textile constructions for seating and wall covering applications require adhesives with balanced flow and green-strength characteristics.
- Sealing:Perimeter and edge-finishing operations in upholstery manufacturing use specialized formulations to prevent fiber shedding and enhance durability.
Equipment intensity peaks in coating. Process flexibility is greatest in bonding.
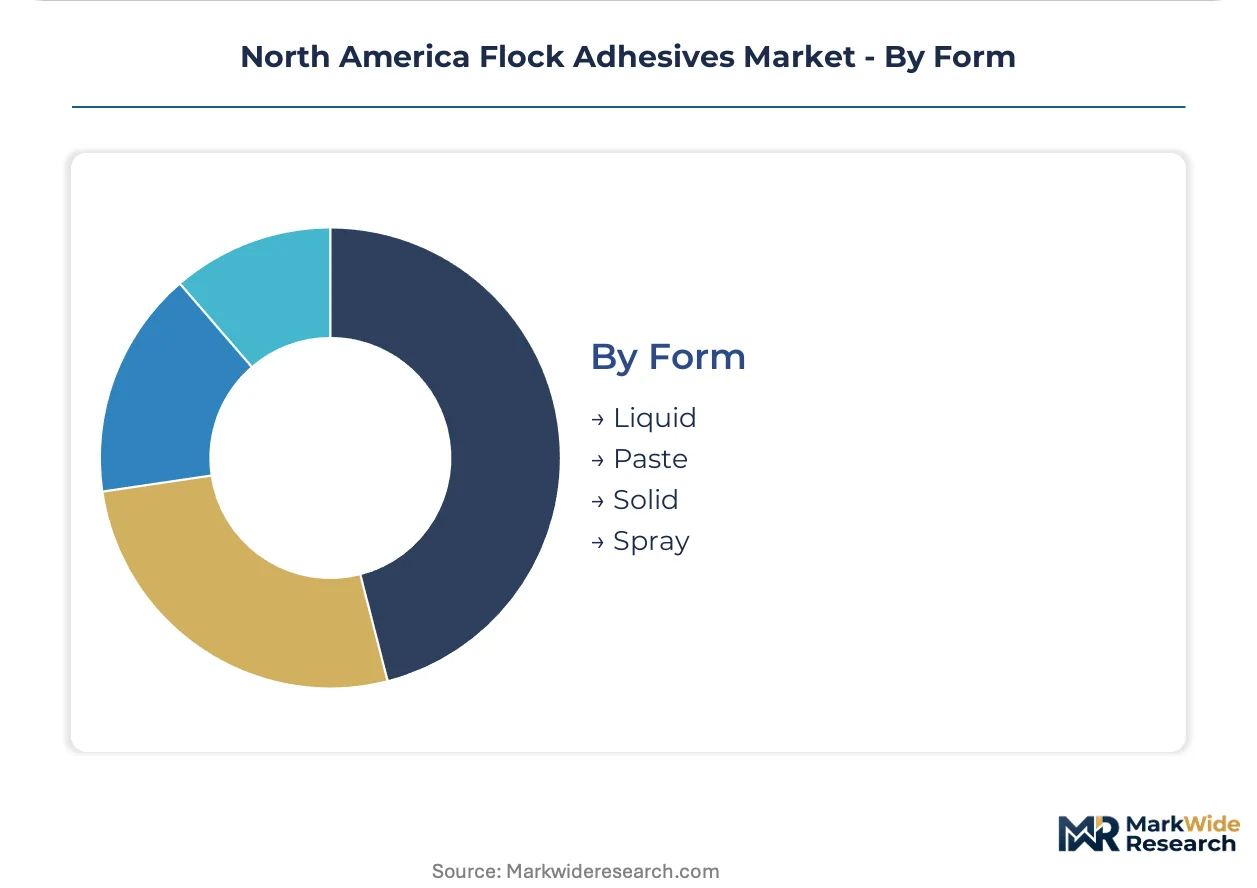
Form:
Physical state determines handling infrastructure, storage requirements, and application precision.
- Liquid:Pumpable dispersions dominate high-volume automotive and textile operations where automated metering systems ensure consistent film weights.
- Paste:Thixotropic formulations maintain vertical hold on complex geometries and textured substrates in furniture assembly.
- Solid:Block and pellet forms enable clean handling and precise melt temperature control in hot-melt delivery systems.
- Spray:Aerosol and bulk spray configurations serve repair, prototyping, and low-volume decorative packaging applications with minimal capital investment.
Automation compatibility is highest in liquid. Capital barriers are lowest in spray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in southeastern United States automotive corridors while Canadian chemical manufacturing supplies cross-border raw material streams. Mexican nearshoring momentum is pulling bonding operations southward to capture USMCA tariff advantages and lower facility costs.
United States
Automotive seating manufacturers in Tennessee and Alabama are scaling velvet-texture component production for electric vehicle platforms. EPA NESHAP hazardous air pollutant standards are accelerating facility upgrades toward low-emission coating lines in Michigan and Ohio assembly plants. The southeastern textile corridor spanning Georgia and North Carolina operates the continent's densest concentration of flock bonding capacity.
Canada
Chemical compounders in Ontario and Quebec serve as upstream suppliers of acrylic and polyurethane dispersions to US automotive Tier-1s. Health Canada PMRA maintains parallel standards that affect cross-border product registrations for suppliers serving both markets. Toronto-area distribution hubs coordinate just-in-time adhesive deliveries to Detroit-Windsor automotive assembly zones.
Mexico
Automotive seating suppliers are relocating bonding operations to Querétaro and Puebla to access USMCA tariff advantages and lower facility costs. Mexican environmental regulations under SEMARNAT are tightening VOC monitoring at industrial facilities. The Bajío Region automotive cluster is attracting hot-melt adhesive warehousing investments from multinational compounders.
North America Flock Adhesives Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with adhesive divisions rather than pure-play specialists. Three to four multinational suppliers control the majority of automotive OEM approvals, while regional compounders serve furniture and packaging niches. Strategic archetypes include raw-material-integrated conglomerates, application-specific technology licensors, and automotive-focused service providers. Dominant competitive moves involve backward integration into acrylic monomer production and long-term offtake agreements with Tier-1 seating manufacturers.
Among North American chemical conglomerates, Dow and H.B. Fuller Company exemplify the raw-material-integrated archetype, with the former anchoring positions through upstream polymer supply control. Henkel AG & Co. KGaA occupies a position within the automotive-specialist tier, while Arkema and Sika AG represent European-based multinationals competing through technology licensing and regional manufacturing footprints.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Arkema |
| H.B. Fuller Company |
| International Coatings |
| Argent International |
| Henkel AG & Co. KGaA |
| Dow |
| Avient Corporation |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Tier-1 automotive seating manufacturers in Michigan and Tennessee concentrate procurement volume through single-source national contracts, compressing adhesive compounders into long-term offtake agreements with embedded technical service obligations. This buyer consolidation enforces contract-based pricing with volume-scaled tiers that penalize mid-tier compounders lacking backward integration into acrylic monomer supply.
Pricing Analysis
Cost compression in water-based formulations accelerates as EPA NESHAP compliance deadlines force facility upgrades toward low-emission coating lines. Three-tier pricing structure across premium reactive systems, standard water-based dispersions, and economy solvent-based alternatives separates automotive OEM approvals from furniture and packaging applications. Price differentiation hinges on CARB VOC certification tier and captive raw material supply. Furniture processors in Arkansas and Mississippi exhibit highest price sensitivity due to thin margin structures, while premium automotive seating lines in South Carolina absorb technical premiums for abrasion-resistant reactive systems.
Supply Chain Analysis
Automotive OEM qualification protocols gate adhesive approvals through 18-24 month validation cycles that lock out unqualified suppliers. Raw material supply concentrates in the United States Gulf Coast for acrylic monomers, Ontario for polyurethane dispersions, and Germany for specialty isocyanates. Formulation chemistry draws from petrochemical feedstocks, textile-grade additives, and curing catalysts. Single-source vulnerability sits with Gulf Coast propylene oxide supply disruptions. Distribution runs through Detroit-Windsor automotive corridors and southeastern textile mill networks with just-in-time drum and tote delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot-melt reactive polyurethane systems are displacing solvent-based formulations across automotive interior bonding, creating technology-transition windows for compounders with curing expertise and capital access.
For Market Incumbents: Anchor compliance leadership through CARB Suggested Control Measures pre-certification investments that lock out reformulation-lagged competitors. Defend automotive OEM approved supplier lists by embedding technical service teams in Tennessee and Alabama seating plants. Prioritize backward integration into acrylic dispersion capacity to offset Gulf Coast monomer volatility. For New Entrants and Emerging Players: Direct-to-compound digital channels bypass legacy distributor markups in furniture and packaging segments where specification autonomy remains strongest. Target UV-curable formulation gaps in decorative packaging applications with energy-curable acrylate pilot programs. Penetrate Mexican nearshoring corridors in Querétaro through SEMARNAT-compliant water-based system partnerships with relocated Tier-2 suppliers. For Investors and Strategic Acquirers: The window for entry favors polyurethane polymerization specialists with reactive curing IP and existing automotive validation records. Long-term viability centers on compounders capturing platform consolidation tailwinds as OEMs reduce approved supplier lists from regional fragmented bases to national single-source contracts. Monitor California ZEV procurement mandate expansion as inflection signal for premium interior specification pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Gulf Coast petrochemical supply control insulates margin compression from propylene oxide volatility. |
| CARB Pre-Certification Investment | California Air Resources Board compliance leadership secures West Coast automotive procurement eligibility ahead of federal benchmarks. |
| Mexico Nearshoring Partnership | Querétaro and Puebla facility co-location captures USMCA tariff advantages for southeastern US automotive supply. |
| UV-Curable Formulation Development | Energy-curable acrylate systems address unmet decorative packaging demand for instant-cure velvet textures. |
| Long-Term Offtake Agreement with Tier-1 Seating Manufacturers | Tennessee and Alabama volume commitments lock out competitors during electric vehicle platform ramp cycles. |
Research Methodology
Trade databases, EPA regulatory filings, and automotive production statistics formed the secondary backbone for demand quantification. Primary interviews with adhesive R&D directors, Tier-1 seating procurement managers, textile mill operations heads, and distribution channel partners validated formulation adoption timelines and specification shifts. Bottom-up and top-down triangulation reconciled plant-level capacity data against end-use consumption patterns.
Bottom-up modeling built from individual facility production rates, adhesive consumption per vehicle, and textile backing line throughput across the analysis window. Top-down verification cross-checked against ACC chemical shipment data and customs import records. Segmentation dimensions included formulation chemistry, end-use vertical, application method, and regional manufacturing cluster. CAGRs derived from regression analysis of historical specification shifts and regulatory compliance investment cycles, with inputs from electric vehicle platform launch schedules and CARB regulatory phase-in timelines.
The model holds under stable EPA NESHAP enforcement trajectories and continued automotive OEM platform consolidation; deviation in California ZEV mandate acceleration or Gulf Coast petrochemical supply disruption would shift volume and value projections. A model refresh is warranted upon material change in CARB VOC threshold tightening or USMCA tariff renegotiation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Global Epoxy Tooling Board Market