
 Europe Bone Glue Market | 2026-2036
Europe Bone Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bone Glue Market Foresight
CE-marked medical-grade specifications is reorganizing procurement criteria across European orthopedic departments. Johnson & Johnson leverages its broad surgical portfolio to sustain hospital formulary presence. Baxter International Inc. anchors European distribution through specialized surgical supply chains. B. Braun Melsungen AG dominates German-speaking markets with manufacturing scale in Melsungen.
Bone glue comprises adhesive biomaterials formulated from cyanoacrylate, calcium phosphate, or fibrin-based compositions, designed to bond osseous tissue under physiological conditions without thermal necrosis. The substance serves primarily to stabilize fractures, augment hardware fixation, and seal bone defects in operative settings. Natural formulations retain strong positions in cardiac and neurological applications where bioresorption profiles match tissue healing timelines. Synthetic segments capture expanding share in orthopedics due to tunable setting times and lower immunogenicity risk. Hospitals remain the dominant end-user channel, though ambulatory surgical centers in Scandinavia and the Benelux are building dedicated orthopedic day-case capacity.
EMA Medical Device Regulation and CE marking requirements shape product entry pathways, while REACH chemical safety protocols govern raw material sourcing for synthetic polymer feedstocks. France's ANSM and Germany's BfArM enforce national vigilance reporting that influences manufacturer post-market surveillance investments. Stakeholders must monitor evolving EUDAMED database integration and notified body capacity constraints that could delay new formulation approvals.
Market Dynamics
EMA Medical Device Regulation recertification timelines are compressing competitive windows across European orthopedic supply chains, forcing manufacturers to accelerate clinical data generation while notified body capacity constraints extend approval cycles.
Growth Catalysts
- Aging surgical volumes:France and the United Kingdom report expanding spinal fusion caseloads as demographic profiles shift toward osteoporotic fracture management. German trauma centers are scaling synthetic bone glue protocols for complex pelvic reconstructions.
- REACH chemical safety protocols:Standardized raw material sourcing for cyanoacrylate and calcium phosphate feedstocks reduces batch-to-batch variability. Synthetic polymer manufacturers gain predictable formulation pathways.
- Benelux ambulatory expansion:Dedicated orthopedic day-case facilities in Belgium and the Netherlands are building same-discharge arthroscopy capacity. Fibrin-based adhesives match shorter procedural windows.
Market Restraints
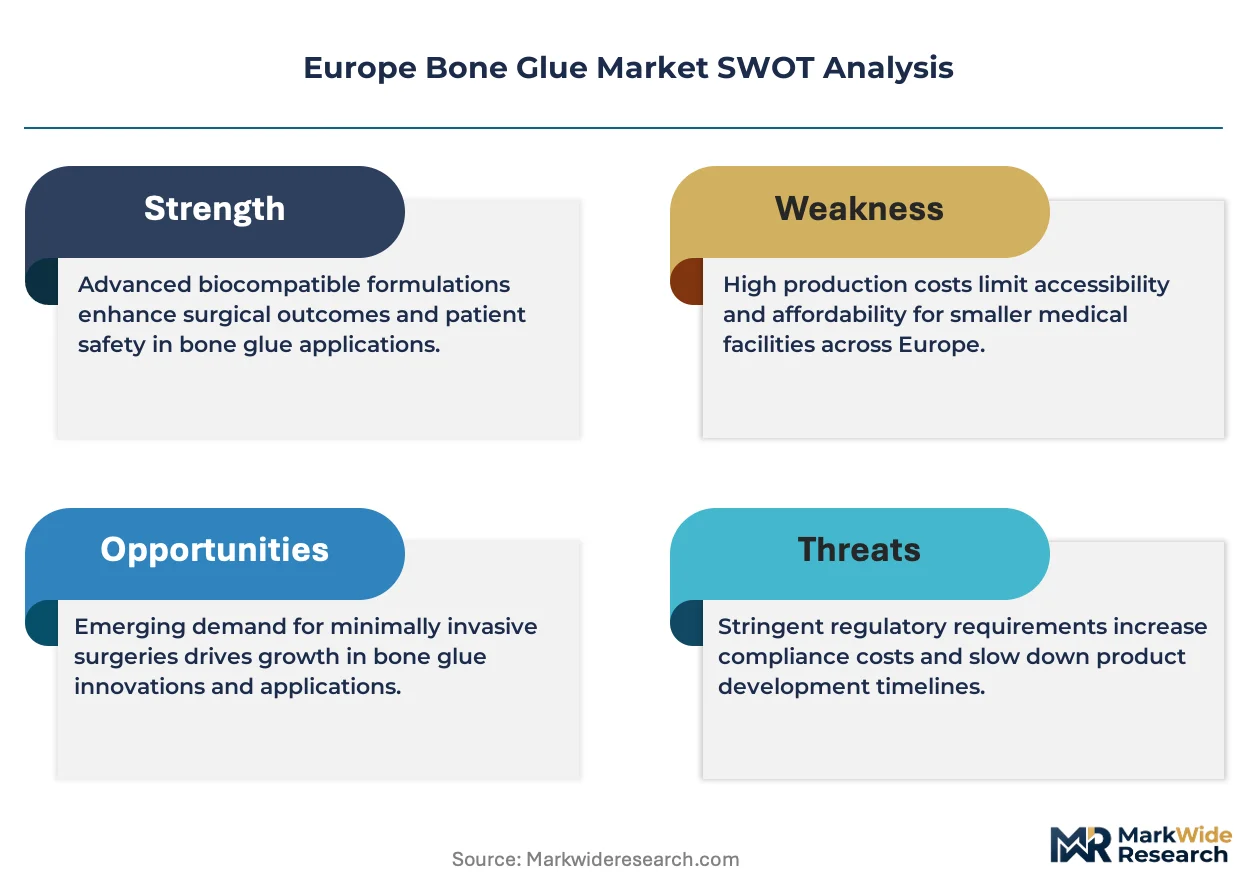
- Notified body bottlenecks:EUDAMED database integration delays and limited MDR-designated assessment capacity extend CE marking timelines by 12-18 months for novel formulations.
- Natural glue supply concentration:Bovine-derived fibrinogen sourcing depends on slaughterhouse byproduct streams concentrated in Eastern European processing facilities. Price volatility tracks cattle herd cycles.
- Biocompatibility testing burden:Tightened EMA cytotoxicity and sensitization standards require expanded animal studies and histopathological validation. Small manufacturers lack in-house toxicology infrastructure.
Strategic Opportunities
- Scandinavian day-surgery networks:Sweden and Denmark are consolidating orthopedic procedures into specialized high-volume centers. Synthetic bone cements with rapid setting profiles match compressed turnaround requirements.
- CSRD sustainability disclosure:EU corporate reporting mandates create procurement preference for bioabsorbable formulations with documented carbon footprint trajectories. Hospital purchasing committees weight environmental metrics.
- 3D printing convergence:Patient-specific implant fabrication in German university hospitals integrates bone glue deposition into additive manufacturing workflows. Custom defect-matching expands addressable indications.
Industry Challenges
- Bioengineer recruitment gaps:Formulation chemists with combined polymer science and orthopedic clinical knowledge command premium compensation. Manufacturing scale-up teams struggle to staff Melsungen and Tuttlingen clusters.
- Legacy sterilization validation:Gamma and ethylene oxide protocols for heat-sensitive cyanoacrylates require extensive endotoxin and sterility assurance testing. Facility requalification absorbs capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bone Glue Market |
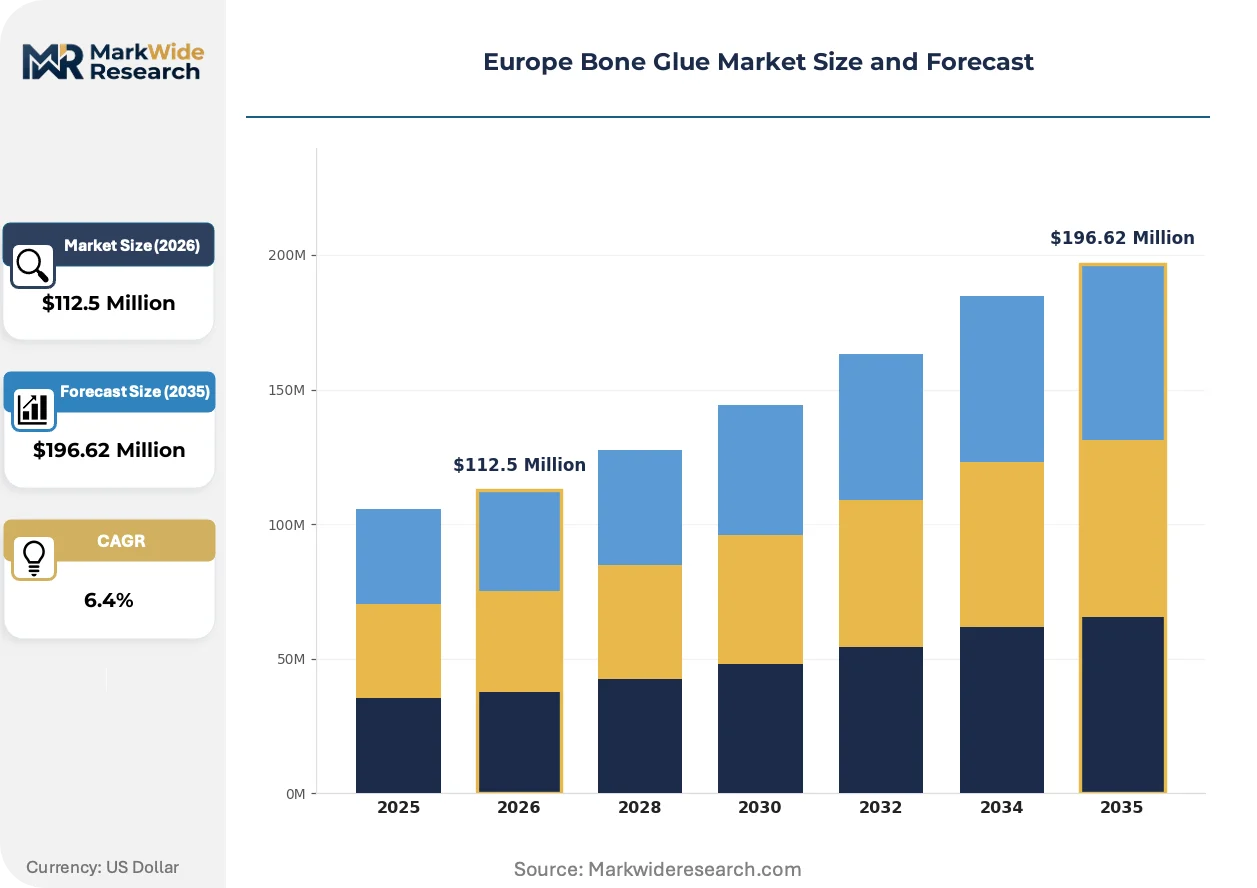
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $196.62 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Hybrid, Biodegradable Application: Orthopedics, Dentistry, Neurology, Wound Care End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Labs Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Johnson & Johnson, Baxter International Inc., CryoLife, Inc., B. Braun Melsungen AG, Integra LifeSciences Corporation, Luna Innovations Incorporated, Cohera Medical, Inc., Tissuemed Ltd., Chemence Medical, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bone Glue Market Shifts & Advancements
Formulation chemistry and regulatory data architecture are converging to reshape product development cycles, with manufacturers investing in predictive bioresorption modeling and real-world evidence capture systems.
Synthetic calcium phosphate composites with tunable osteoconductivity profiles are supplanting traditional PMMA bone cements in spinal fusion applications. Belgian and Dutch orthopedic departments are adopting these formulations for vertebroplasty procedures. The shift compresses revision surgery rates and extends hardware-free fixation indications.
EU Medical Device Regulation Annex XVI expansion reclassifies certain bone glue applications as Class III devices requiring clinical investigation. Manufacturers face expanded post-market surveillance obligations and periodic safety update reports. German BfArM vigilance reporting systems are absorbing increased adverse event volumes from high-volume hospital networks.
Hospital procurement committees in France and the United Kingdom are consolidating supplier relationships into dual-source frameworks with volume-commitment pricing. Specialized surgical distributors lose share to direct manufacturer contracts. The restructuring concentrates purchasing power within Paris and London hospital procurement consortia.
Europe Bone Glue Market Segmentation
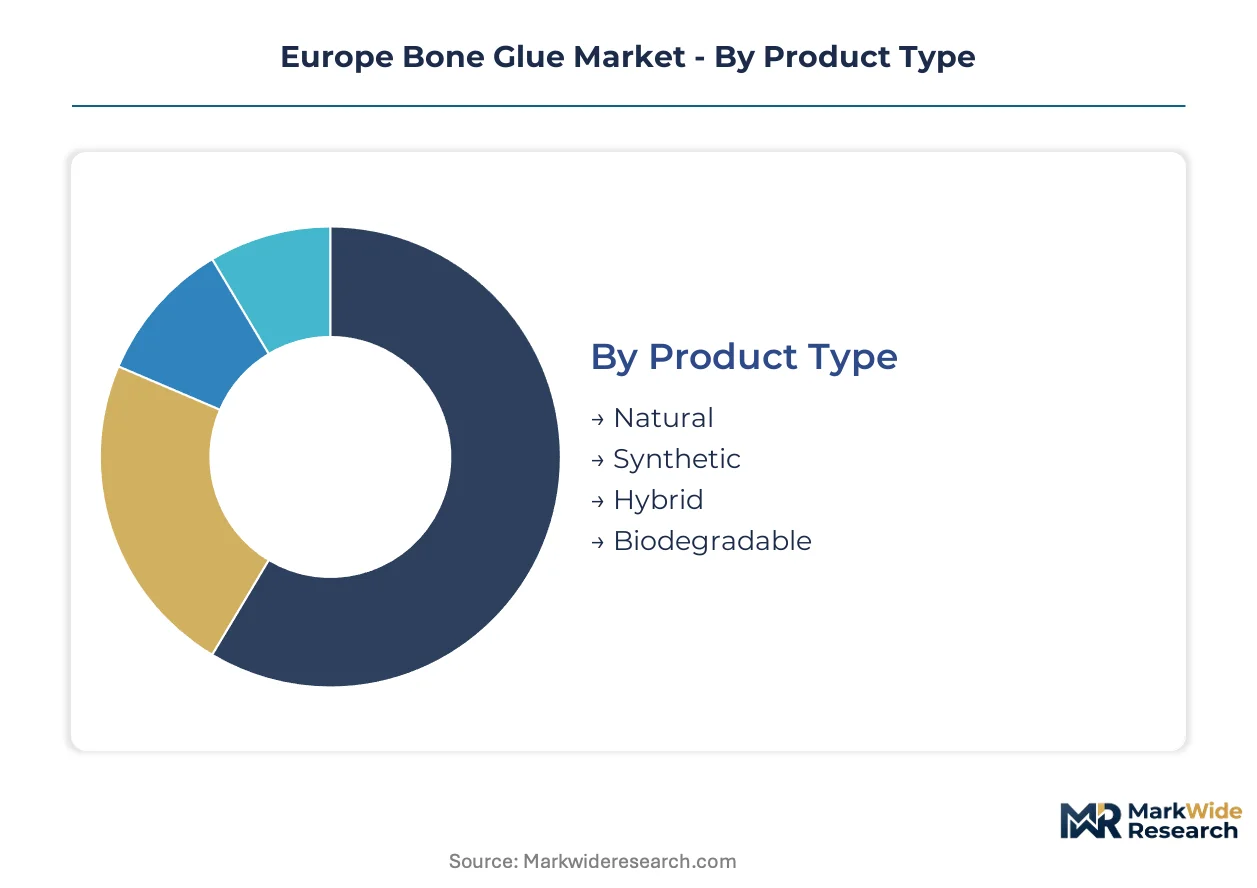
Segmentation in the Europe Bone Glue Market reveals how EMA Medical Device Regulation tiers and REACH chemical safety protocols create distinct competitive corridors. Manufacturers navigate divergent clinical validation burdens and raw material sourcing constraints across each category.
Product Type:
EMA biocompatibility standards and REACH feedstock protocols differentiate formulation pathways, with Class III device classifications concentrated in synthetic and hybrid categories.
- Natural:Fibrin-based and collagen-derived compositions leverage bovine and autologous sourcing. French cardiac surgery units and German neurological departments favor these formulations for matched bioresorption timelines, though Eastern European slaughterhouse supply concentration introduces price volatility.
- Synthetic:Cyanoacrylate and calcium phosphate polymers dominate orthopedic trauma applications. German university hospitals are expanding synthetic protocols for complex pelvic reconstructions as tunable setting times reduce thermal necrosis risk.
- Hybrid:Combines natural bioactivity with synthetic mechanical strength for spinal fusion.
- Biodegradable:PLA-PEG copolymers designed for complete resorption without inflammatory residue.
Established volume favors Natural; emerging adoption favors Synthetic.
Application:
Procedure reimbursement rates and surgical volume trajectories concentrate investment across clinical specialties, with orthopedic day-case expansion reshaping demand profiles.
- Orthopedics:Spinal fusion and fracture fixation consume the majority of bone glue volumes. United Kingdom and French aging demographics drive expanding caseloads, while Belgian and Dutch ambulatory centers adopt rapid-setting formulations for same-discharge arthroscopy.
- Neurology:Dural sealants and cranial reconstruction applications require ultra-low viscosity formulations. German trauma centers prioritize these specifications for compressed procedural windows.
- Dentistry:Periodontal bone regeneration and implant fixation represent specialized niche demand.
- Wound Care:Combat casualty and burn applications utilize hemostatic bone glue variants.
Orthopedics captures dominant revenue share; Neurology demonstrates steepest expansion trajectory as craniotomy volumes rise.
End User:
Capital equipment requirements and sterilization infrastructure determine facility-level adoption thresholds across European healthcare systems.
- Hospitals:Academic medical centers in Paris, London, and Berlin anchor high-complexity consumption. These institutions maintain dedicated bone glue inventory for trauma, spinal, and neurological services with 24-hour surgical availability.
- Ambulatory Surgical Centers:Scandinavian and Benelux day-case networks are building dedicated orthopedic capacity. Swedish high-volume centers favor synthetic cements with sub-60-second setting profiles to match compressed turnaround requirements.
- Clinics:Private dental and orthopedic practices serve localized procedural demand.
- Research Labs:German university hospitals and Belgian biomaterials institutes drive preclinical formulation development.
Hospitals retain procurement dominance; Ambulatory Surgical Centers are gaining share fastest as day-case networks consolidate.
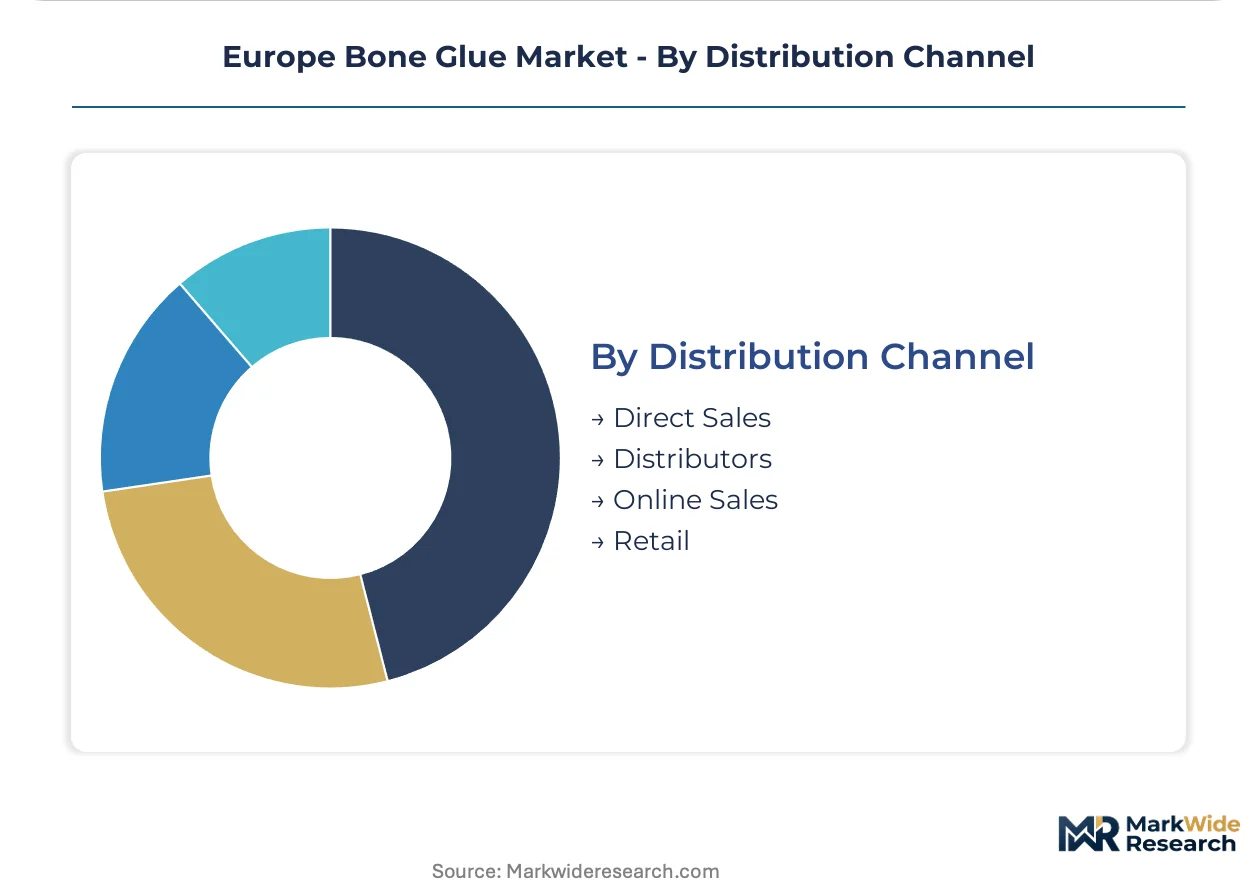
Distribution Channel:
Procurement committee restructuring and volume-commitment contracting are compressing intermediary margins across European supply chains.
- Direct Sales:Manufacturer contracts with Paris and London hospital procurement consortia are displacing specialized surgical distributors. Johnson & Johnson and Baxter International leverage broad surgical portfolios to secure formulary presence through direct negotiation.
- Distributors:Regional surgical supply chains retain relevance in German-speaking markets where B. Braun Melsungen AG anchors distribution through manufacturing proximity in Melsungen.
- Online Sales:E-procurement platforms serve smaller clinics and research labs with standardized product configurations.
- Retail:Limited to veterinary and consumer wound care applications outside regulated medical channels.
Direct Sales commands premium-account access; Distributors defend position in geographically fragmented secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale clusters in German-speaking regions, while demand generation concentrates in aging population centers across Western Europe. Hospital procurement consolidation in Paris and London reshapes distribution economics. Regulatory enforcement diverges between EMA harmonized standards and national vigilance systems.
Germany
Trauma centers in Berlin and Munich are scaling synthetic bone glue protocols for complex pelvic reconstructions. BfArM vigilance reporting requirements absorb increased adverse event volumes from high-volume hospital networks. The Melsungen-Tuttlingen manufacturing corridor anchors European production capacity for cyanoacrylate formulations.
France
ANSM enforcement of biocompatibility standards drives reformulation investments among cardiac surgery units in Paris. Spinal fusion caseloads expand as demographic profiles shift toward osteoporotic fracture management. The Île-de-France hospital procurement consortium concentrates purchasing power through dual-source framework contracts.
United Kingdom
Aging populations in London and the Southeast drive expanding orthopedic volumes, particularly for vertebroplasty procedures. NHS procurement committees are consolidating supplier relationships into volume-commitment pricing structures. Research labs in Oxford and Cambridge drive preclinical formulation development for biodegradable copolymers.
Belgium and Netherlands
Benelux ambulatory surgical centers are building dedicated orthopedic day-case capacity with sub-60-second setting requirements. EUDAMED database integration supports streamlined CE marking pathways for rapid-setting synthetic cements. Belgian biomaterials institutes in Leuven anchor collaborative research with German university hospitals.
Sweden and Denmark
Scandinavian day-surgery networks are consolidating orthopedic procedures into specialized high-volume centers in Stockholm and Copenhagen. Synthetic bone cements with rapid setting profiles match compressed turnaround requirements. National procurement agencies weight CSRD sustainability disclosures in supplier selection criteria.
Europe Bone Glue Market Competitive Landscape
Concentration sits with diversified surgical portfolio holders and specialized biomaterials manufacturers. The vendor base spans three tiers: multinational conglomerates with broad hospital formulary access, mid-scale European specialists with manufacturing proximity advantages, and emerging technology developers focused on hybrid formulations. Two dominant competitive moves are reshaping positioning: direct manufacturer contracting with consolidated procurement consortia, and strategic partnerships with 3D printing implant fabricators for integrated surgical workflows.
Among diversified surgical portfolio holders, Johnson & Johnson and Baxter International exemplify the scale-driven archetype through broad hospital formulary presence. B. Braun Melsungen AG represents the manufacturing-proximity specialist, anchoring German-speaking market access through its Melsungen location. These three entities occupy distinct competitive positions: formulary breadth, distribution infrastructure, and regional manufacturing scale respectively.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International Inc. |
| CryoLife, Inc. |
| B. Braun Melsungen AG |
| Integra LifeSciences Corporation |
| Luna Innovations Incorporated |
| Cohera Medical, Inc. |
| Tissuemed Ltd. |
| Chemence Medical, Inc. |
| Others |
Supply & Pricing Matrix
Synthetic calcium phosphate feedstocks displacing bovine-derived fibrinogen are redrawing raw material sourcing maps from Eastern European slaughterhouse clusters toward German petrochemical corridors, compressing input cost volatility while concentrating pricing power with polymer manufacturers holding REACH-compliant supply contracts.
Pricing Analysis
EMA Medical Device Regulation dictates the pricing tier structure across European bone glue markets, separating CE-marked Class III formulations from lower-classification alternatives through clinical investigation requirements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale, with Paris and London hospital procurement consortia extracting steepest discounts through dual-source framework contracts. Cost compression in standard-tier synthetic cements is intensifying because German university hospitals are consolidating purchasing into direct manufacturer agreements. Ambulatory surgical centers in Scandinavia and the Benelux exhibit highest price sensitivity due to compressed reimbursement margins, while German trauma centers demonstrate lowest sensitivity given procedural complexity premiums.
Supply Chain Analysis
Container availability fluctuations on Rotterdam-Antwerp-Hamburg trade lanes are elevating inbound logistics costs for cyanoacrylate monomer shipments originating from Asian polymer plants. Manufacturing gravity centers on Germany, Belgium, and the Netherlands, with the Melsungen-Tuttlingen corridor anchoring European production capacity. Raw material dependencies include bovine fibrinogen from Eastern European processing facilities, calcium phosphate precursors from Moroccan phosphate rock, and cyanoacrylate monomers from Chinese and Japanese chemical plants. Single-source vulnerability in bovine-derived inputs exposes formulators to cattle herd cycle volatility. Distribution runs through specialized surgical supply chains in German-speaking markets and direct manufacturer contracts with consolidated procurement consortia in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as 3D printing implant fabrication workflows integrate bone glue deposition into additive manufacturing ecosystems, creating interoperability requirements that favor formulation developers with software companion capabilities.
For Market Incumbents: Fortify hospital formulary presence through CE marking acceleration for hybrid formulations that match EUDAMED database integration timelines, while deepening backward integration into calcium phosphate precursor production to offset Eastern European fibrinogen supply volatility. Direct contracting leverage with Paris and London procurement consortia remains the priority defensive position against specialized distributor displacement.
For New Entrants and Emerging Players: Anchor in Scandinavian day-surgery networks where rapid-setting synthetic cements face limited incumbent saturation and national procurement agencies weight CSRD sustainability disclosures in supplier selection. Belgian and Dutch ambulatory centers present the most penetrable geography given sub-60-second setting requirements and compressed turnaround demands. A software-defined companion platform for 3D printing workflow integration offers the clearest go-to-market differentiation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale European biomaterials specialists holding manufacturing proximity advantages in German-speaking markets but lacking direct procurement consortia access. Long-term viability over a multi-year horizon hinges on regulatory data architecture investments and predictive bioresorption modeling capabilities. Watch EUDAMED database integration completion as the signal indicating accelerated CE marking timelines and competitive window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EMA MDR recertification timelines compress competitive windows for novel formulations. |
| Backward Integration into Precursors | Captive calcium phosphate feedstock supply reduces REACH sourcing variability. |
| Hospital System Partnership | Direct contracts with Paris and London consortia displace distributor intermediaries. |
| Software Companion Development | 3D printing workflow integration creates platform-economics lock-in with implant fabricators. |
| Reimbursement Strategy | NHS and French national pricing alignment secures ambulatory center volume commitment. |
Research Methodology
Operator-level perspectives from trauma surgeons, hospital procurement managers, biomedical engineers, and GPO contracts managers anchored the qualitative base, cross-referenced with EMA submission databases, BfArM vigilance reporting systems, hospital procurement databases, and REACH chemical safety filings. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Sensitivity analysis tested forecast robustness across notified body capacity constraint scenarios and alternative biocompatibility standard implementation timelines over the projection horizon. Segmentation dimensions modeled include natural versus synthetic versus hybrid formulation categories, orthopedic versus neurology versus dentistry applications, hospital versus ambulatory surgical center end users, and direct sales versus distributor channel structures. CAGRs derived from procedure volume trajectories, demographic aging curves, and day-case expansion rates in Scandinavian and Benelux markets.
Decision-makers should treat outputs as directional under sustained EMA MDR enforcement and REACH feedstock compliance assumptions; material deviation in notified body designation timelines would warrant model refresh. Practitioners should keep alternative scenarios live as EUDAMED database integration and CSRD sustainability disclosure requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Electronics Adhesives Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Acetate Silicone Sealant Market