
 South Africa Sealants Market | 2026-2036
South Africa Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Sealants Market Analytics
South African chemical formulators is realigning production schedules around imported polymer feedstock availability and domestic blending capacity. Sika AG leverages its Johannesburg technical center to sustain specification-grade supply for major civil contractors. Henkel AG & Co. KGaA anchors its position through adhesive-sealant bundled distribution to automotive tier suppliers in the Eastern Cape. Permoseal (Pty) Ltd competes on localized formulation flexibility and shorter lead times for mid-tier construction projects.
Sealants are elastomeric compounds formulated from silicone, polyurethane, acrylic, or epoxy chemistries that cure to form flexible, impermeable barriers against moisture, air, and chemical ingress, typically specified by Shore A hardness, elongation at break, and movement accommodation factors. Their primary purpose spans structural glazing, expansion joint sealing, and substrate bonding across built assets and manufactured goods. Silicone dominates façade and weatherproofing applications where UV stability and temperature cycling resistance command premium positioning, while polyurethane captures flooring and interior joint work where paint compatibility and hardness drive selection. Water-based acrylic competes on low-VOC compliance and ease of application for interior DIY and light commercial use, though thermal curing reactive systems penetrate industrial OEM assembly lines where bond strength and chemical resistance prove decisive.
South Africa's National Regulator for Compulsory Specifications (NRCS) mandates SABS mark certification for structural sealants used in permanent buildings, while the Department of Trade, Industry and Competition enforces local content thresholds on public infrastructure procurement. These frameworks elevate compliance costs for imported formulations while creating preferential access for domestic blenders meeting SANS 1344 and related performance standards. Stakeholders must monitor feedstock currency exposure and NRCS testing backlog timelines to calibrate inventory and specification strategies.
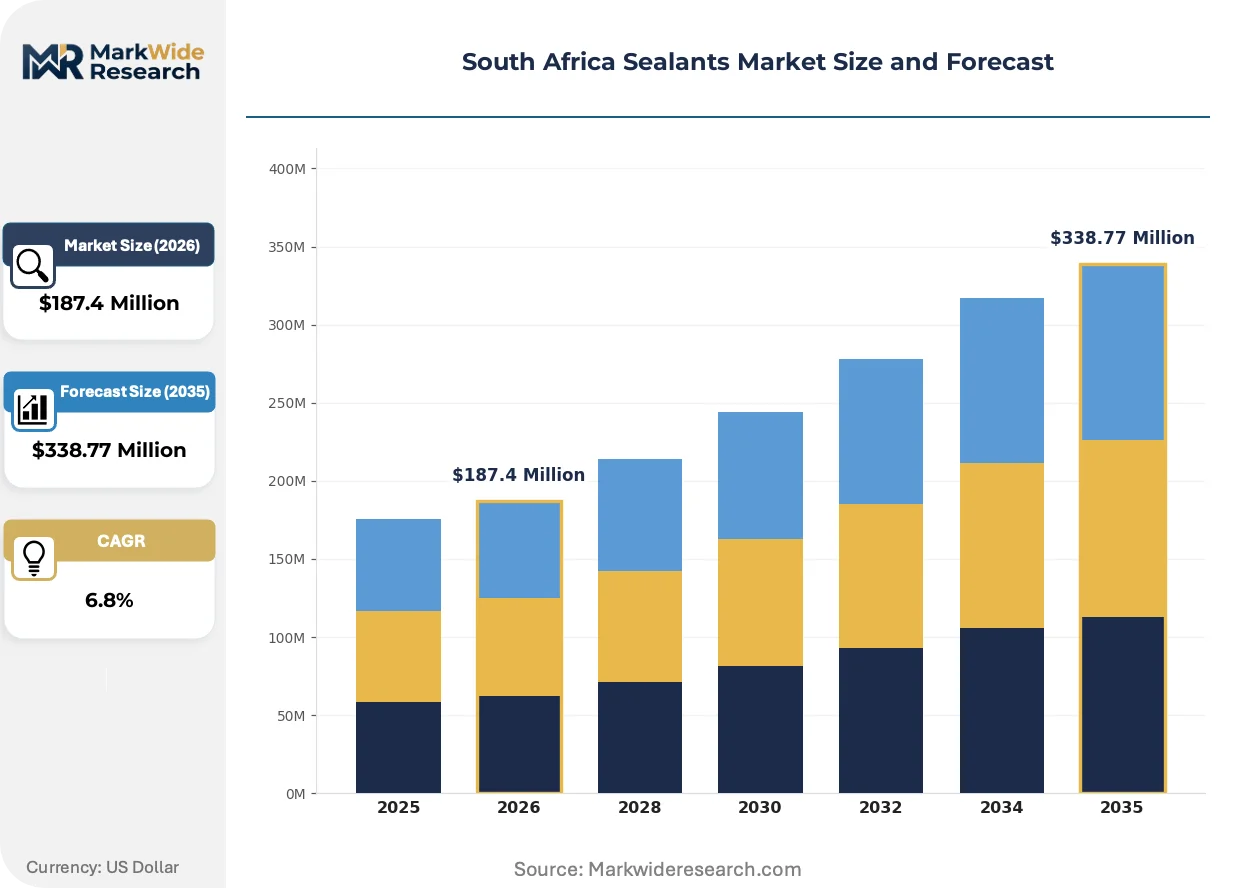
Market Dynamics
South Africa's sealants sector is contending with feedstock import dependency and NRCS certification bottlenecks that compress margins for domestic blenders while elevating compliance barriers for offshore suppliers. The tension between polymer supply security and specification-grade output requirements defines current strategic positioning.
Growth Catalysts
- Public infrastructure procurement mandates:The Department of Trade, Industry and Competition enforces local content thresholds on state-funded construction, directing specification-grade volume toward SABS-certified domestic producers.
- Façade remediation cycles:Johannesburg's commercial building stock and Cape Town's coastal infrastructure are entering accelerated joint-replacement windows, pulling moisture-cure polyurethane and neutral-cure silicone formulations.
- Automotive assembly localization:OEM tier suppliers in the Eastern Cape are expanding adhesive-sealant bundling for vehicle sealing applications, tightening specification ties between formulators and assemblers.
Market Restraints
- Polyol and isocyanate import concentration:South Africa lacks domestic MDI/TDI production, exposing polyurethane formulators to currency volatility and Baltic-Asia shipping schedule disruptions.
- NRCS testing backlog:The regulator's SABS mark certification queue for structural sealants extends project timelines by four to eight months, freezing specification decisions for permanent building applications.
- Acrylic water-based substitution ceiling:Interior DIY segments trade down to lower-performance acrylics where movement accommodation and chemical resistance are non-critical, capping premium silicone penetration.
Strategic Opportunities
- Western Cape infrastructure rehabilitation:Cape Town's water treatment and harbor expansion projects are specifying potable-water-grade and immersion-resistant formulations under SANS 1344 variants.
- Solar PV mounting system integration:Module frame sealing and junction box potting applications are creating specification pathways for UV-stable silicone and thermally conductive formulations in renewable energy EPC contracts.
- Direct contractor technical service:Bypassing traditional distributor networks, formulators are embedding application engineers with Gauteng civil contractors to capture specification authority at the joint-design stage.
Industry Challenges
- Competent applicator scarcity:Proper installation of movement-capable joint sealants requires trained technicians conversant with SANS 2001-CC1 substrate preparation standards, and this skill pool is concentrated in major metros.
- Batch-to-batch certification continuity:Maintaining SABS mark validity across polymer feedstock lot variations demands internal testing infrastructure that mid-tier blenders struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Sealants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy Application: Construction, Automotive, Aerospace, Electronics End User: Contractors, Manufacturers, Distributors, DIY Consumers Technology: Thermal Curing, Solvent-Based, Water-Based, Reactive |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, Arkema Group, Dow, Soudal Holding N.V., H.B. Fuller Company, 3M, Permoseal (Pty) Ltd, MAPEI S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Sealants Market Evolving Landscape
Formulation chemistry and procurement mechanics are diverging from historical patterns as feedstock constraints and certification requirements force structural adaptation across South Africa's construction supply chain.
Hybrid silyl-modified polymer (SMP) chemistries are rewriting competitive positioning in expansion joint applications. These formulations combine silicone's weathering resistance with polyurethane's paint compatibility and primerless adhesion. Gauteng commercial contractors are specifying SMP systems for mixed-substrate façades where thermal cycling and aesthetic finish requirements coexist. The technology is compressing the traditional silicone-polyurethane application boundary and enabling single-specification coverage across complex building envelopes.
South Africa's NRCS is tightening SANS 1344 enforcement for structural glazing sealants used in high-rise curtain walling, mandating accelerated UV and heat-aging test protocols that exceed prior validation requirements. This regulatory compression is disqualifying uncertified imported formulations and consolidating specification authority among domestic blenders with in-house SABS testing capability. Façade engineering consultancies in Johannesburg are revising master specifications to exclude non-NRCS-marked products from tender eligibility.
Buying patterns among mid-tier construction contractors are fragmenting specification authority away from merchant distributors toward direct technical engagement with formulator field engineers. Contractors in the Western Cape are demanding substrate-specific compatibility guarantees and on-site application training as bundled purchase conditions. This disintermediation is visible most acutely in Cape Town's infrastructure rehabilitation sector, where project-scale joint sealing packages are negotiated directly with Sika and Permoseal technical teams rather than through building material retailers.
South Africa Sealants Market Segmentation
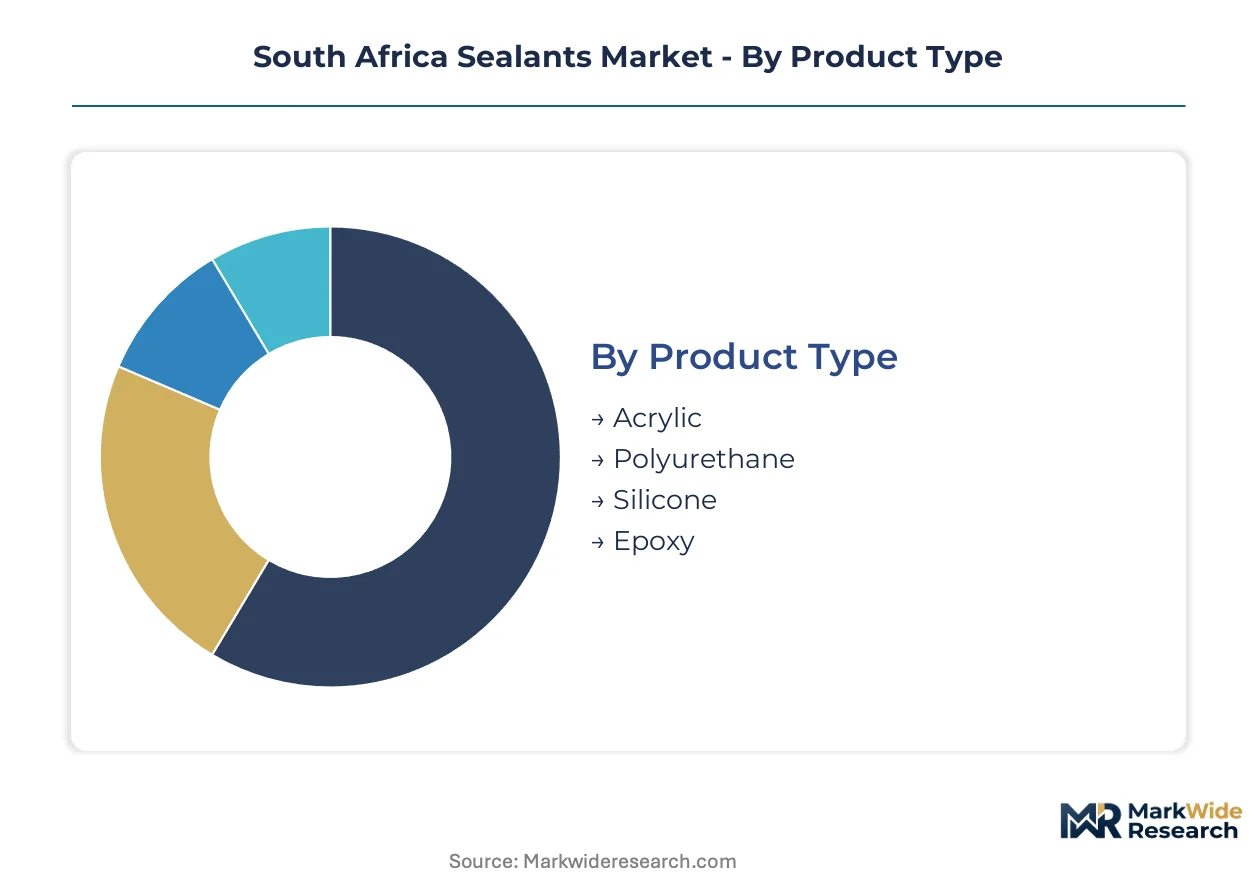
Sealant specification in South Africa follows distinct technical hierarchies where polymer chemistry, cure mechanism, and end-use severity determine procurement authority. Understanding how these dimensions intersect reveals where margin concentrates and where volume flows.
Product Type:
Upgrade cycles in Gauteng commercial façades and Cape Town coastal infrastructure are pulling differentiated polymer formulations as building owners replace failed joints with specification-grade alternatives.
- Silicone:Neutral-cure and oxime-cure formulations dominate high-rise curtain walling and structural glazing where UV stability, temperature cycling resistance, and 25-year service life expectations command premium positioning. Johannesburg's commercial building stock replacement wave specifies SANS 1344-certified silicones for movement accommodation exceeding 25%.
- Polyurethane:Moisture-cure systems capture flooring expansion joints, parking deck sealing, and interior applications where paint compatibility and Shore A hardness between 35-50 drive selection. Cape Town's harbor rehabilitation projects specify immersion-grade polyurethanes under SANS 1344 variants for potable water contact.
- Acrylic:Water-based formulations serve interior DIY and light commercial perimeter sealing where low-VOC compliance and ease of application outweigh movement accommodation requirements.
- Epoxy:Rigid, high-strength systems penetrate industrial assembly and structural bonding applications where chemical resistance and load-bearing capacity supersede flexibility needs.
Polyurethane sits at the top of the volume ranking, with silicone climbing the fastest as façade remediation accelerates across Johannesburg and Cape Town.
Application:
Cost-tier differentiation separates specification-grade projects with engineer-certified joints from commodity applications where contractor discretion dominates material selection.
- Construction:Structural glazing, expansion joint sealing, and waterproofing across commercial, residential, and infrastructure assets. Gauteng civil contractors and Western Cape rehabilitation projects concentrate premium formulation demand.
- Automotive:OEM tier suppliers in the Eastern Cape specify adhesive-sealant bundles for vehicle body sealing, windshield bonding, and underbody coating applications.
- Aerospace:Specialized fuel tank sealing and airframe bonding applications requiring SABS-certified performance under extreme thermal and pressure cycling.
- Electronics:Potting and encapsulation for junction boxes, control modules, and renewable energy components where thermal conductivity and dielectric stability matter.
Construction commands the largest revenue pool, with electronics gaining share fastest as solar PV installation scales.
End User:
Customer-type concentration shapes how technical service bundles with product—contractors demand field engineering while DIY segments prioritize retail accessibility.
- Contractors:Gauteng and Western Cape civil and commercial builders who specify through direct formulator engagement, demanding substrate compatibility guarantees and on-site application training.
- Manufacturers:Automotive assemblers and industrial OEMs in the Eastern Cape procuring adhesive-sealant systems through tier-supplier integration.
- Distributors:Building material merchants serving mid-tier projects where specification authority fragments between retailer and contractor.
- DIY Consumers:Residential renovators selecting low-VOC acrylics through retail channels for interior sealing and weatherproofing.
Contractors represent the highest-value channel, with manufacturers expanding most quickly through automotive localization.
Technology:
Supply concentration around imported polymer feedstock limits domestic blending capacity for reactive and thermal-cure systems, compressing margins on advanced formulations.
- Reactive:Two-component polyurethane and epoxy systems curing through chemical reaction, specified where bond strength and chemical resistance prove decisive. NRCS certification bottlenecks extend timelines for structural applications.
- Thermal Curing:Heat-activated formulations penetrating industrial OEM assembly lines where production throughput demands controlled cure acceleration.
- Solvent-Based:Traditional construction sealants facing regulatory pressure from VOC emissions standards, gradually displaced in interior applications.
- Water-Based:Acrylic emulsions capturing interior DIY and light commercial segments where application ease and environmental compliance drive selection.
Reactive technology leads on margin contribution, with water-based formulations expanding volume fastest through retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as formulators migrate toward jurisdictions with streamlined certification pathways and localized feedstock access. South Africa's NRCS framework creates compliance cost differentials that favor domestic blending capacity over direct importation.
Gauteng Province
Johannesburg's commercial building stock drives specification-grade silicone demand for high-rise curtain walling and structural glazing replacement cycles. The NRCS enforces SANS 1344 certification for structural sealants used in permanent buildings, extending project timelines through testing backlogs. Pretoria's civil engineering consultancies are revising master specifications to exclude non-NRCS-marked products from tender eligibility.
Western Cape
Cape Town's coastal infrastructure rehabilitation and harbor expansion projects specify immersion-grade polyurethane formulations under SANS 1344 variants for potable water contact. The Department of Trade, Industry and Competition applies local content thresholds to state-funded construction, directing volume toward SABS-certified domestic producers. Stellenbosch's water treatment facilities are specifying potable-water-grade sealants for municipal upgrade programs.
Eastern Cape
Automotive OEM tier suppliers in Port Elizabeth and East London are expanding adhesive-sealant bundling for vehicle body sealing and windshield bonding applications. The national automotive masterplan incentivizes component localization, tightening specification ties between formulators and assemblers. Gqeberha's industrial zones are concentrating procurement authority among manufacturers with technical service capabilities.
KwaZulu-Natal
Durban's port infrastructure and logistics corridors sustain demand for expansion joint sealants in heavy-vehicle loading facilities and container terminal maintenance. The provincial public works department applies SABS standards to infrastructure procurement, filtering specification authority toward certified suppliers. Richards Bay's industrial harbor complex is specifying chemical-resistant formulations for marine exposure environments.
South Africa Sealants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specification-grade certification and direct contractor engagement to bypass traditional distribution channels. The vendor base clusters around three maturity levels: multinational formulators with Johannesburg technical centers, domestic blenders with localized formulation flexibility, and merchant distributors serving retail-accessible segments. Two strategic archetypes dominate: integrated chemical suppliers leveraging polymer feedstock security, and application-focused specialists embedding field engineers with civil contractors. Competitive moves center on NRCS certification acquisition and direct technical service deployment.
Among multinational integrated suppliers, Sika AG and Henkel AG & Co. KGaA exemplify the technical-center archetype, anchoring specification authority through Johannesburg-based application engineering and SABS-certified production. Permoseal (Pty) Ltd occupies a position within the domestic specialist tier, representing localized formulation adaptability and shorter lead-time competitiveness for mid-tier construction projects. These three entities illustrate the competitive tension between global scale and regional responsiveness that defines procurement dynamics.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| Arkema Group |
| Dow |
| Soudal Holding N.V. |
| H.B. Fuller Company |
| 3M |
| Permoseal (Pty) Ltd |
| MAPEI S.p.A. |
| Others |
Value Network & Pricing Analysis
Imported polyol and isocyanate feedstock costs cascade through South Africa's sealants market, concentrating margin pressure on polyurethane formulators while SABS-certified domestic blenders capture premium positioning through NRCS compliance arbitrage. Currency volatility on Baltic-Asia shipping routes amplifies cost tier separation between specification-grade silicone and commodity acrylic alternatives.
Pricing Analysis
Distributor margins compress as Gauteng civil contractors negotiate direct technical service bundles with Sika and Permoseal field engineers, bypassing traditional merchant markups. Three-tier pricing structure across premium SANS 1344-certified, standard industrial-grade, and economy DIY tiers reflects certification investment and volume scale differentiation. Pricing pressure stems from acrylic water-based substitution in interior segments where movement accommodation requirements relax. DIY consumers exhibit highest price sensitivity, while façade engineering consultancies prioritize 25-year service life guarantees over unit cost.
Supply Chain Analysis
Direct-to-contractor channels handle specification-grade demand from Johannesburg commercial builders and Cape Town infrastructure rehabilitators, while merchant distributors serve retail-accessible acrylic segments. Polymer feedstock draws from China, Germany, and Belgium, exposing formulators to shipping schedule disruptions and euro-rand volatility. MDI and TDI isocyanate dependencies create single-source vulnerability given South Africa's absence of domestic aromatic diisocyanate production. Distribution runs through Johannesburg blending facilities to Gauteng and Western Cape project sites, with NRCS certification queues extending inventory holding requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's sealants market offers margin expansion through hybrid SMP chemistry premiumization and direct contractor engagement that displaces distributor markups. Feedstock currency hedging and SABS certification investment separate sustainable returns from commodity trap exposure.
For Market Incumbents: Hedge NRCS testing backlog risk by building in-house SANS 1344 validation capability that accelerates batch-to-batch certification continuity. Secure polymer feedstock through long-term offtake agreements with Baltic-Asia suppliers, locking in margin before rand depreciation intensifies. Vertical integration into silyl-modified polymer formulation protects against silicone-polyurethane substitution erosion. For New Entrants and Emerging Players: Hybrid silyl-modified polymer chemistries offer specification-grade entry without incumbent certification backlogs, targeting Gauteng mixed-substrate façade contractors seeking paint-compatible weathering resistance. Western Cape potable-water-grade polyurethane applications present white-space opportunity where SANS 1344 variant compliance remains thin. Embed application engineers directly with Stellenbosch municipal water treatment procurement teams to capture specification authority at joint-design stage. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier domestic blenders with localized formulation flexibility because NRCS certification barriers protect acquired customer relationships from import competition. Target SABS-certified producers with underutilized testing infrastructure and established contractor technical service protocols. Watch NRCS queue clearance timelines as inflection indicator—accelerated certification throughput would erode domestic blender protection premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive MDI/TDI supply from German or Belgian sources insulates margin from rand volatility. |
| SANS 1344 Certification Investment | NRCS mark acquisition blocks imported competitors from Johannesburg high-rise curtain walling tenders. |
| Direct Contractor Technical Service Deployment | Field engineer embedding with Gauteng civil builders captures specification authority before distributor involvement. |
| Hybrid SMP Formulation Development | Single-specification coverage across complex envelopes compresses silicone-polyurethane application boundaries. |
| Western Cape Infrastructure Rehabilitation Focus | Potable-water-grade polyurethane demand from Cape Town harbor expansion commands SANS 1344 variant premiums. |
Research Methodology
Multiple input streams — technical director interviews at Sika Johannesburg, procurement lead discussions with Gauteng civil contractors, and NRCS certification timeline documentation — were reconciled against customs data on polyol and isocyanate import volumes. Secondary validation drew from SABS standards documentation, Department of Trade and Industry local content procurement circulars, and Baltic-Asia shipping schedule disclosures. Plant managers at Eastern Cape automotive tier suppliers and distribution channel partners in Durban provided downstream demand calibration. Bottom-up project pipeline aggregation and top-down chemical consumption estimates were triangulated to anchor volume assumptions.
Historical Cape Town infrastructure rehabilitation spend patterns were cross-referenced against panel input from façade engineering consultancies revising master specifications. The analytical framework modeled segmentation across polymer chemistry, cure mechanism, application severity, and end-user procurement authority throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves and feedstock cost pass-through assumptions. Solar PV mounting system integration and automotive assembly localization served as industry-specific volume drivers in the projection model.
The model holds under stable NRCS certification throughput and rand-euro exchange rate bands; deviation in Baltic-Asia shipping disruption frequency or SABS standards revision timing would shift supply security assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
South America Reactive Adhesives Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market