
 Specialty Monomer Market | 2026-2036
Specialty Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Monomer Market Outlook
Project finance tied to green chemistry infrastructure is fragmenting competitive entry in specialty monomer production. BASF SE leverages its integrated Verbund site network to sustain cost-advantaged acrylate supply chains. Mitsubishi Chemical Corporation anchors its position through proprietary methacrylate process technology and captive raw material access.
Specialty monomers are reactive molecules with defined functional groups—typically acrylate, methacrylate, or styrenic backbones—engineered for controlled polymerization in molecular weights ranging from 100 to 500 g/mol, serving as precursors for coatings, adhesives, and engineered plastics with tunable glass transition temperatures. Acrylates dominate volume flows in waterborne coating formulations where fast cure kinetics command premium pricing, while methacrylates capture disproportionate margin pools in optical and dental applications demanding exceptional clarity and biocompatibility. The electronics application segment is expanding fastest as semiconductor packaging and display adhesives require ultra-purity monomer grades with sub-ppm metal ion specifications.
EPA New Chemicals Program reviews and REACH registration requirements in Europe are tightening market access for imported monomer streams and forcing reformulation toward registered, lower-toxicity chemistries. China's MEE enforces GB standards on volatile organic compound emissions from coating raw materials, redirecting domestic production toward waterborne-compatible monomer architectures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Specialty monomer production is consolidating around integrated petrochemical complexes capable of capturing economies of scale while simultaneously accommodating batch-scale flexibility for custom functionalization. This dual-mode operational requirement is compressing margins for standalone producers lacking captive feedstock access or downstream polymerization partnerships.
Growth Catalysts
- REACH registration deadlines:European chemical safety mandates under ECHA are accelerating reformulation toward pre-registered monomer architectures, pulling demand toward established suppliers with complete dossier portfolios.
- Semiconductor packaging:Advanced flip-chip and fan-out wafer-level packaging processes require ultra-high-purity acrylate monomers with sub-ppm ionic contamination specifications.
- Waterborne coating transition:China's MEE enforcement of GB VOC emission standards is redirecting architectural and industrial coating formulations toward hydroxy-functional acrylate monomers with rapid ambient cure kinetics.
Market Restraints
- Propylene oxide supply volatility:Methacrylate monomer production depends on propylene oxide as a critical intermediate, with pricing exposed to cracker operating rates and seasonal derivative demand swings.
- Specialty catalyst scarcity:Controlled radical polymerization initiators and organometallic catalysts for living polymerization architectures face concentrated supply from limited fine chemical manufacturers.
- Substitution by bio-epoxy systems:lignin-derived and plant oil-based epoxy resins are capturing share in certain adhesive applications previously served by acrylate UV-cure systems.
Strategic Opportunities
- India specialty chemicals corridor:Gujarat and Maharashtra industrial zones offer feedstock proximity and PLI scheme incentives for import-substituting monomer production serving domestic coatings and adhesives demand.
- Photopolymer dental restoration:Methacrylate monomers with tuned refractive index matching and low polymerization shrinkage are expanding into chairside CAD/CAM restorative workflows.
- EU Green Deal carbon border adjustments:CBAM implementation is creating first-mover advantage for European producers with verified low-carbon process routes and renewable feedstock certifications.
Industry Challenges
- Process analytical technology integration:Real-time spectroscopic monitoring of exothermic polymerization reactions requires scarce automation engineering talent familiar with PAT framework implementation.
- Dual-use export control alignment:Monomers with semiconductor-grade purity specifications face evolving BIS and EU dual-use regulation alignment, complicating cross-border shipment documentation.
- Legacy batch reactor retrofitting:Continuous flow microreactor adoption for hazardous monomer synthesis demands capital-intensive reconfiguration of existing plant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Monomer Market |
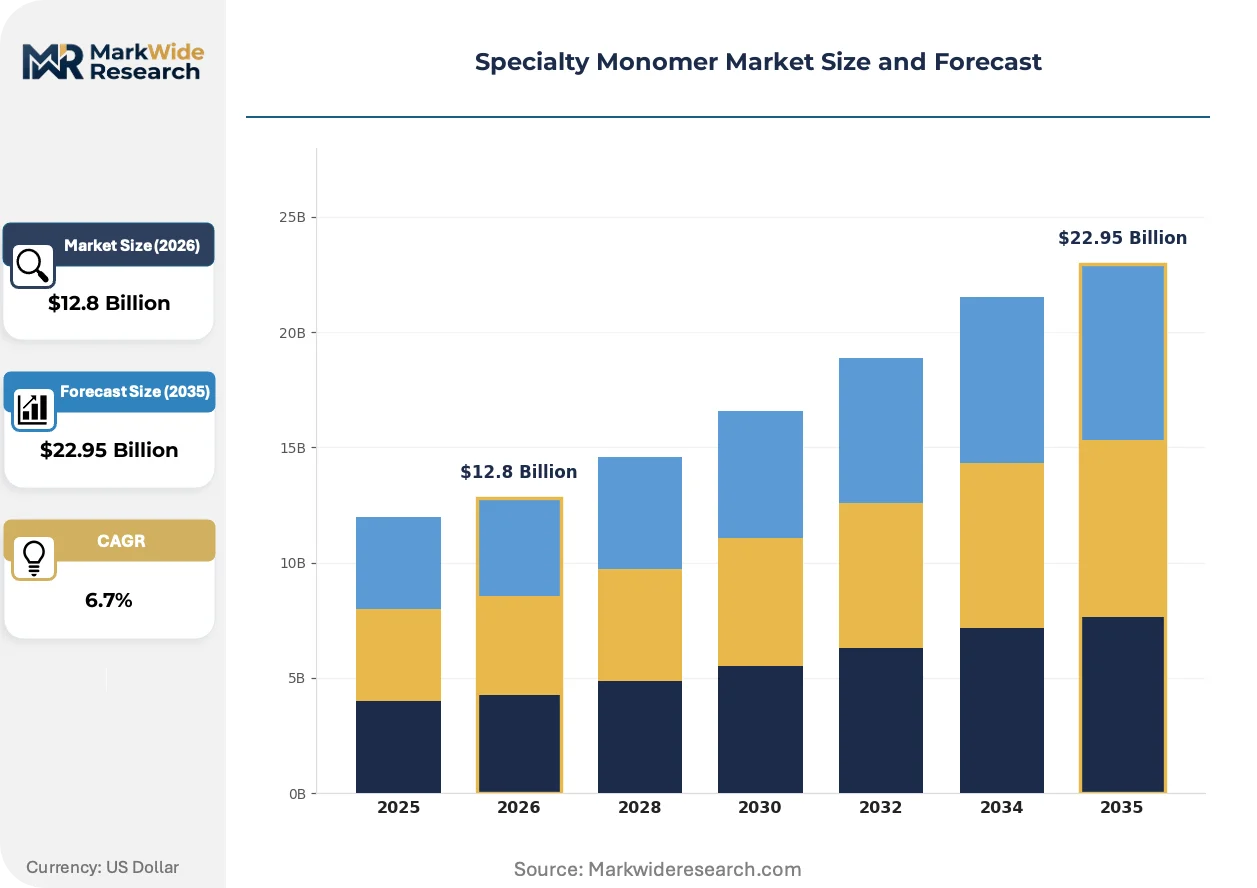
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylates, Methacrylates, Styrenics, Others End Use Industry: Adhesives, Coatings, Plastics, Textiles Form: Liquid, Solid, Powder, Paste Application: Electronics, Automotive, Construction, Healthcare |
| Companies Covered | BASF SE, Mitsubishi Chemical Corporation, Evonik Industries AG, Arkema S.A., Dow Inc., Solvay S.A., LG Chem Ltd., Sumitomo Chemical Co., Ltd., Allnex Belgium SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Monomer Market Strategic Shifts
Reactive processing architectures and digital formulation platforms are compressing development cycles for application-specific monomer grades. These advances are simultaneously enabling mass customization while eroding traditional specification moats.
Continuous flow microreactor technology is collapsing the economic threshold for producing small-lot specialty monomers with precise molecular weight distribution control. Custom synthesis houses serving pharmaceutical and electronics end-uses are adopting modular flow chemistry skids that slash minimum order quantities from multi-ton to kilogram scale. This capability fragmentation is collapsing the volume-premium correlation that historically protected commodity acrylate producers from specialty competition.
EPA New Chemicals Program review timelines under TSCA Section 5 are extending pre-market authorization periods for novel monomer structures, forcing innovators toward existing chemical substance lists. Industrial consequence includes defensive patenting around pre-1990 monomer architectures and accelerated investment in bio-based feedstocks qualifying for existing substance exemptions. Electronics-grade monomer importers face particular friction as metal ion specification testing protocols lack harmonization between EPA and downstream semiconductor customer requirements.
Specification-driven procurement consolidation is compressing supplier panels as coatings formulators reduce qualified monomer sources to streamline incoming quality assurance. Large architectural coatings manufacturers are replacing spot-market purchasing with multi-year framework agreements tying volume commitments to dedicated production line allocation. This shift is most visible in China, where domestic waterborne coating leaders are integrating backward into captive monomer production or securing exclusive offtake from regional acrylate specialists.
Specialty Monomer Market Segmentation
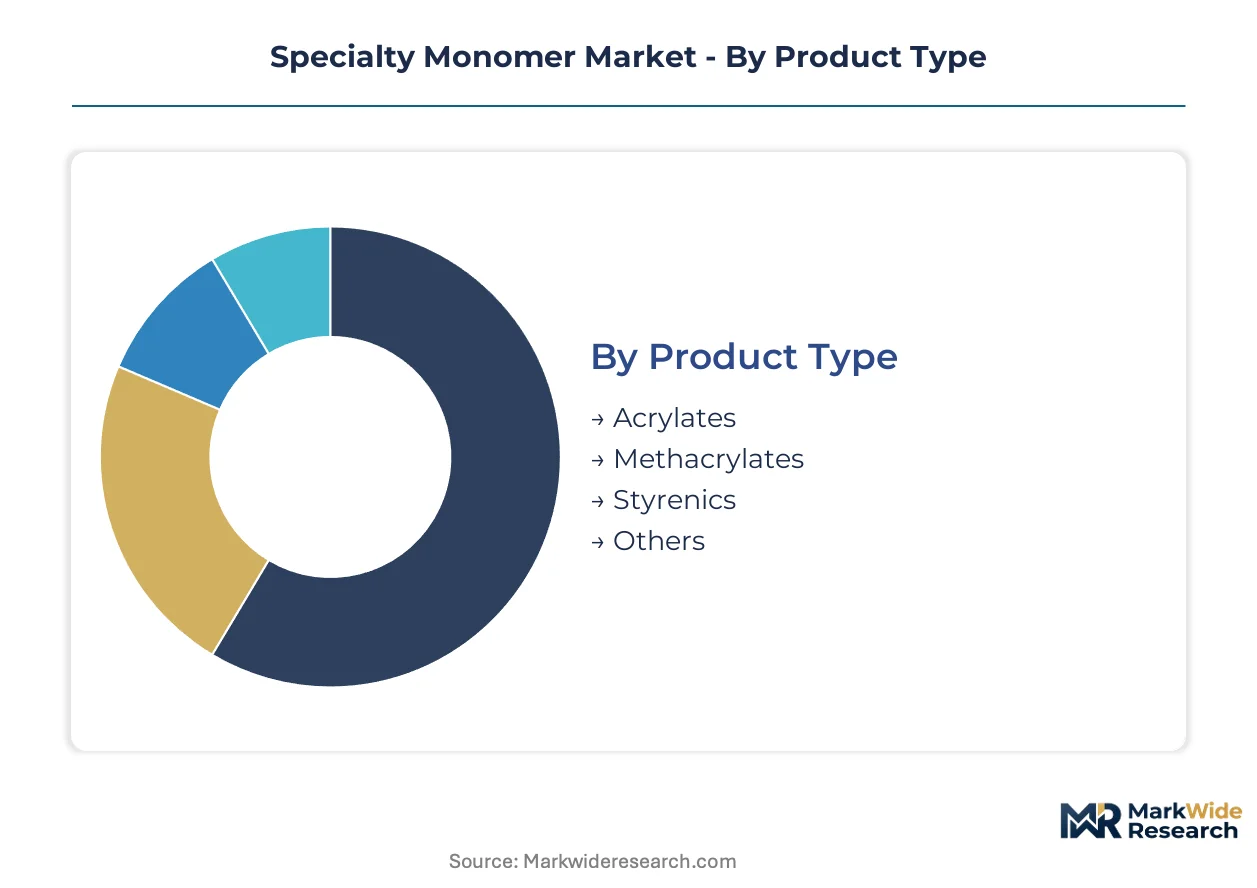
Specialty monomer procurement decisions cascade through multiple technical dimensions simultaneously. Formulators must reconcile polymerization kinetics, regulatory registration status, and supply security across each segmentation axis.
Product Type:
After-sales technical service intensity varies dramatically across monomer chemistries, with acrylates demanding formulation troubleshooting support and methacrylates requiring optical property optimization assistance.
- Acrylates:Fast-curing monomers with activated double bonds enable rapid polymerization in ambient conditions. Waterborne coating formulators in China prioritize hydroxy-functional acrylates to meet MEE GB VOC emission standards while maintaining cure speed.
- Methacrylates:Methyl methacrylate derivatives deliver exceptional optical clarity and biocompatibility for demanding applications. Dental restoration workflows and semiconductor packaging adhesives in Japan and South Korea drive specification-grade demand with sub-ppm metal ion requirements.
- Styrenics:Vinyl aromatic monomers provide cost-effective rigidity and thermal resistance for engineering plastics compounding.
- Others:Specialty functional monomers including vinyl ethers, allyl compounds, and fluorinated variants serve niche electronics and medical applications.
Acrylates hold the largest share; momentum sits with methacrylates.
End Use Industry:
Cost tier stratification separates commodity volume applications from specification-driven segments where purity premiums command three-to-five-fold pricing multiples.
- Adhesives:Structural bonding formulations leverage acrylate UV-cure systems for electronics assembly and automotive component attachment. Electronics-grade specifications with ionic contamination limits below 100 ppb are displacing standard industrial grades in flip-chip packaging.
- Coatings:Architectural and industrial protective films represent the highest volume consumption segment. China's waterborne transition under MEE enforcement is redirecting solventborne acrylic formulations toward hydroxy-functional monomers with rapid ambient crosslinking.
- Plastics:Engineering polymer compounding utilizes methacrylates and styrenics for impact modification and weatherability enhancement.
- Textiles:Fiber finishing and nonwoven binder applications consume lower-purity acrylate emulsions with moderate durability requirements.
Coatings command the greatest volume; adhesives are climbing the fastest on semiconductor packaging demand.
Form:
Supply chain handling requirements and shelf stability constraints differentiate procurement patterns across physical states.
- Liquid:Standard bulk delivery format for acrylates and methacrylates enables automated metering in continuous polymerization systems. Tanker truck and ISO-tank logistics dominate regional supply within China, Germany, and the United States.
- Solid:Flake and pellet forms reduce shipping costs for remote formulations operations and extend storage stability for slow-turn inventory.
- Powder:Spray-dried emulsion polymers serve powder coating and dry-mix adhesive applications where solvent elimination is mandatory.
- Paste:High-viscosity prepolymer dispersions simplify handling in small-batch custom compounding operations.
Liquid forms dominate commercial flows; powder is gaining share fastest on coating industry solvent reduction mandates.
Application:
Customer maturity separates specification-driven procurement with dedicated quality agreements from spot-market purchasing with minimal technical qualification.
- Electronics:Semiconductor packaging, display adhesives, and printed circuit board coatings require ultra-high-purity monomers with comprehensive ionic and organic impurity characterization. EPA New Chemicals Program review timelines and REACH registration requirements restrict qualified supplier pools.
- Automotive:Exterior coatings and structural adhesives demand weathering resistance and crash-durability performance validated through OEM specification protocols.
- Construction:Architectural coatings and sealants consume volume flows with moderate purity requirements and price-sensitive procurement.
- Healthcare:Dental restorations, medical device coatings, and drug delivery matrices require biocompatibility certifications and extractables testing under ISO 10993 frameworks.
Construction absorbs the greatest volume; electronics shows the steepest expansion trajectory on advanced packaging proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in specialty monomers diverge sharply across major economies, with China running structural surpluses in acrylate derivatives while the United States and Germany maintain deficits in ultra-high-purity grades for semiconductor packaging. This asymmetry is reshaping regional investment patterns and cross-border supply security strategies.
China
Domestic waterborne coating demand and advanced packaging proliferation are absorbing methacrylate and acrylate output from expanding coastal petrochemical complexes. MEE enforcement of GB VOC emission standards is redirecting solventborne formulations toward hydroxy-functional architectures. The Yangtze River Delta cluster around Shanghai anchors the fastest capacity additions for electronics-grade monomer production.
United States
Semiconductor packaging reshoring under CHIPS Act incentives is pulling ultra-purity acrylate imports from Asian suppliers while domestic methacrylate production serves dental and optical applications. EPA New Chemicals Program reviews under TSCA Section 5 are extending pre-market authorization timelines for novel monomer structures. The Gulf Coast petrochemical corridor retains cost advantages for standard-grade acrylate production.
Germany
REACH registration dossiers held by established producers are creating defensive moats against imported monomer streams lacking complete substance portfolios. ECHA deadlines are accelerating reformulation toward pre-registered architectures in coatings and adhesives. The Ludwigshafen integrated Verbund site sustains cost-advantaged supply chains for acrylate derivatives serving continental European formulators.
Japan
Optical-grade methacrylate demand for display adhesives and semiconductor packaging is sustaining premium pricing for specification-compliant output. METI industrial policy supports domestic production of ultra-purity grades with sub-ppm metal ion certification. The Chubu region around Nagoya concentrates precision chemical manufacturing for electronics end-uses.
India
Import substitution in coatings raw materials is accelerating under PLI scheme incentives for specialty chemicals manufacturing in Gujarat and Maharashtra industrial zones. Domestic architectural coating growth is absorbing acrylate emulsion capacity expansions. The Dahej and Mundra clusters are attracting backward-integrated investments from regional formulators seeking captive monomer supply.
Specialty Monomer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with proprietary process technology and captive feedstock access. The specialty monomer market structures around three tiers: integrated petrochemical conglomerates with Verbund economics, mid-scale regional specialists with flexible batch capabilities, and custom synthesis houses serving pharmaceutical and electronics niches. Dominant competitive moves include backward integration into propylene oxide and acrylic acid intermediates, plus exclusive offtake agreements with waterborne coating formulators consolidating supplier panels.
Within the integrated conglomerate tier, BASF SE and Mitsubishi Chemical Corporation exemplify divergent competitive positioning. BASF anchors European supply security through its Ludwigshafen Verbund network, while Mitsubishi Chemical Corporation represents Japanese precision in methacrylate process technology. Among diversified chemical groups, Evonik Industries AG occupies a position linking specialty monomer production to downstream additives and coatings formulations. These three entities collectively illustrate how feedstock integration and application-specific technical service separate profitable participants from margin-compressed commodity suppliers.
| Leading Market Players |
|---|
| BASF SE |
| Mitsubishi Chemical Corporation |
| Evonik Industries AG |
| Arkema S.A. |
| Dow Inc. |
| Solvay S.A. |
| LG Chem Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Allnex Belgium SA |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's acrylate derivatives sector is compressing spot-market margins while simultaneously concentrating pricing power among integrated producers with captive propylene oxide supply. This utilization asymmetry rewards Verbund-structured suppliers with cost-advantaged feedstock positions and penalizes standalone batch operators exposed to intermediate price volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the specialty monomer landscape. Three-tier pricing stratifies across semiconductor-grade premium, waterborne coating standard, and textile emulsion economy levels, with ionic contamination certification thresholds and volume scale as primary differentiation drivers. Cost compression in standard-grade acrylates is intensifying because Chinese coastal capacity additions outpace MEE-compliant formulation demand growth. Powder coating formulators exhibit the highest price sensitivity due to thin margin structures, while semiconductor packaging houses accept three-to-five-fold premiums for sub-ppm metal ion specifications.
Supply Chain Analysis
Dual-use export controls under BIS and EU alignment frameworks are restricting ultra-high-purity monomer flows to semiconductor packaging destinations. Supply concentrates in China, Germany, and Japan, with methacrylate production drawing from propylene oxide, acetone cyanohydrin, and sulfuric acid inputs. Single-source vulnerability sits with organometallic catalyst supply from limited fine chemical manufacturers. Distribution runs through tanker truck and ISO-tank logistics for liquid acrylates within regional clusters, with solid flake formats serving remote compounding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty monomer production rewards scarce process analytical technology engineering talent capable of implementing real-time spectroscopic monitoring for exothermic polymerization control. The gap between qualified automation specialists and retrofit demand across legacy batch infrastructure is widening competitive moats for first movers in continuous flow adoption.
For Market Incumbents: Build regulatory dossier moats by completing REACH substance portfolios ahead of ECHA deadlines and securing EPA pre-manufacture notifications for existing chemical architectures. Backward integration into acrylic acid intermediates at Ludwigshafen or Gulf Coast Verbund sites defends margin position against propylene oxide price swings. Patent defensively around pre-1990 monomer structures to block novel chemistry pathways facing extended TSCA Section 5 review timelines. For New Entrants and Emerging Players: Pursue specialty catalyst manufacturing as the most penetrable white-space target, given concentrated supply from limited fine chemical houses serving living polymerization architectures. Gujarat and Maharashtra industrial zones offer PLI scheme incentives for import-substituting acrylate emulsion production serving domestic waterborne coating demand. Target photopolymer dental restoration workflows with methacrylate monomers tuned for low polymerization shrinkage and refractive index matching, leveraging chairside CAD/CAM adoption curves. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronics-grade monomer sub-segments as sub-ppm metal ion certification demands cleanroom infrastructure and dedicated production line allocation. Mid-scale regional specialists with flexible batch capabilities and captive feedstock access represent the preferred acquisition archetype over commodity acrylate producers facing margin compression. Watch for MEE enforcement intensity in China as the signal indicating waterborne formulation pull-through rates and hydroxy-functional monomer demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive intermediate supply insulates methacrylate margins from cracker operating rate volatility. |
| Continuous Flow Microreactor Adoption | Modular flow chemistry skids collapse minimum order quantities for small-lot specialty grades. |
| REACH Dossier Completion | Full substance portfolios accelerate reformulation pull-through from ECHA deadline pressures. |
| Exclusive Offtake Agreements | Multi-year frameworks with waterborne coating formulators lock volume against spot-market erosion. |
| Electronics-Grade Certification Investment | Sub-ppm metal ion testing protocols qualify supply for flip-chip packaging reshoring under CHIPS Act incentives. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at integrated petrochemical complexes, procurement leads at downstream coating formulators, technical R&D directors at adhesive manufacturers, and distribution channel partners serving pharmaceutical and electronics niches, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA New Chemicals Program submission records. Bottom-up capacity and demand modeling triangulated with top-down macro chemical consumption trends.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from fitted growth curves calibrated to capacity utilization signals and regulatory enforcement intensity trajectories. Forecast inputs included MEE GB VOC standard adoption rates in China and semiconductor packaging reshoring progress under CHIPS Act incentives.
Macroeconomic conditions sit as an overlay; deviation in propylene feedstock pricing, cracker operating rates, or coating construction activity would shift the trajectory. Forecasts reflect assumptions around regulatory deadline adherence and cleanroom infrastructure buildout timelines. Material shifts in dual-use export control alignment or REACH substance list revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Dammar Gum Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Lentein Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market