
 Anti-Adhesion Products Market | 2026-2036
Anti-Adhesion Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Adhesion Products Market Analysis
North American polymer synthesis capacity is expanding as specialty chemical producers scale hydrogel precursor output for medical-grade applications. Baxter International leverages its hemostasis and sealant portfolio to cross-sell adhesion barriers into integrated surgical kits. Johnson & Johnson anchors its position through Ethicon's extensive surgeon training networks and direct hospital contracting. Integra LifeSciences specializes in regenerative tissue matrices that double as anti-adhesion substrates in neurosurgical and orthopedic settings.
Anti-adhesion products are mechanical or chemical barriers, typically formulated from hydrogels, silicone derivatives, or resorbable polymers such as polylactic acid, designed to separate injured tissue surfaces during the critical healing window and prevent fibrous scar formation. These products function by creating a temporary physical interface that degrades or absorbs as mesothelial regeneration completes, with gel and film formulations dominating current surgical practice due to their ease of intraoperative application and conformability to anatomical contours. Film-based barriers currently occupy the largest revenue share given their established reimbursement codes and surgeon familiarity, while liquid formulations represent the fastest-expanding category as spray application systems reduce operative time and improve coverage uniformity in laparoscopic procedures. Hydrogel materials command premium positioning owing to their tissue-like compliance and controlled degradation profiles, whereas polyethylene-based products compete primarily on cost in high-volume hospital purchasing agreements.
The FDA regulates anti-adhesion products as Class II or Class III medical devices under 510(k) or PMA pathways, with clinical data requirements intensifying for novel resorbable formulations seeking broad surgical indications. The European Medicines Agency and notified bodies enforce MDR compliance with heightened post-market surveillance obligations, while Japan's PMDA maintains distinct biocompatibility testing protocols that lengthen registration timelines for foreign manufacturers. Stakeholders must monitor evolving payer evidence requirements as health technology assessment bodies in Germany, France, and England increasingly demand adhesion-specific quality-of-life endpoints beyond traditional safety metrics.
Market Dynamics
Bioresorbable polymer validation requirements are intensifying as FDA and EMA demand adhesion-specific efficacy endpoints beyond traditional safety metrics, forcing manufacturers to redesign clinical trial protocols and extend development timelines.
Growth Catalysts
- Laparoscopic spray systems:Liquid barrier application is displacing manual film placement in minimally invasive gynecological procedures, reducing operative time and improving anatomical coverage uniformity.
- MDR post-market surveillance:Europe's heightened clinical follow-up obligations are creating competitive moats for manufacturers with robust real-world evidence infrastructure.
- Ambulatory surgical center expansion:United States outpatient facility volume growth is concentrating demand for single-use, ready-to-deploy barrier formats.
Market Restraints
- PLA precursor supply concentration:Medical-grade polylactic acid feedstock depends on a limited number of specialty chemical producers in Germany and the United States.
- PMDA biocompatibility protocols:Japan's distinct testing requirements extend registration timelines by 18-24 months for foreign hydrogel manufacturers.
- Generic polyethylene competition:Commodity barrier materials compete on cost in high-volume hospital purchasing agreements, compressing margin for differentiated formulations.
Strategic Opportunities
- Neurosurgical matrix extension:Regenerative tissue substrates validated for dural repair are expanding into spinal adhesion prevention with minimal incremental R&D.
- Health technology assessment alignment:Germany's IQWiG and England's NICE are piloting adhesion-specific quality-of-life endpoints that reward clinically differentiated products.
- Integrated surgical kit bundling:Cross-selling adhesion barriers with hemostasis and sealant portfolios captures purchasing decisions at the integrated delivery network level.
Industry Challenges
- Surgeon training standardization:Spray application technique variability across laparoscopic specialties creates inconsistent clinical outcomes and complicates label expansion.
- 510(k) predicate device erosion:FDA intensifying scrutiny of historical comparator products for novel resorbable formulations is lengthening regulatory pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Adhesion Products Market |
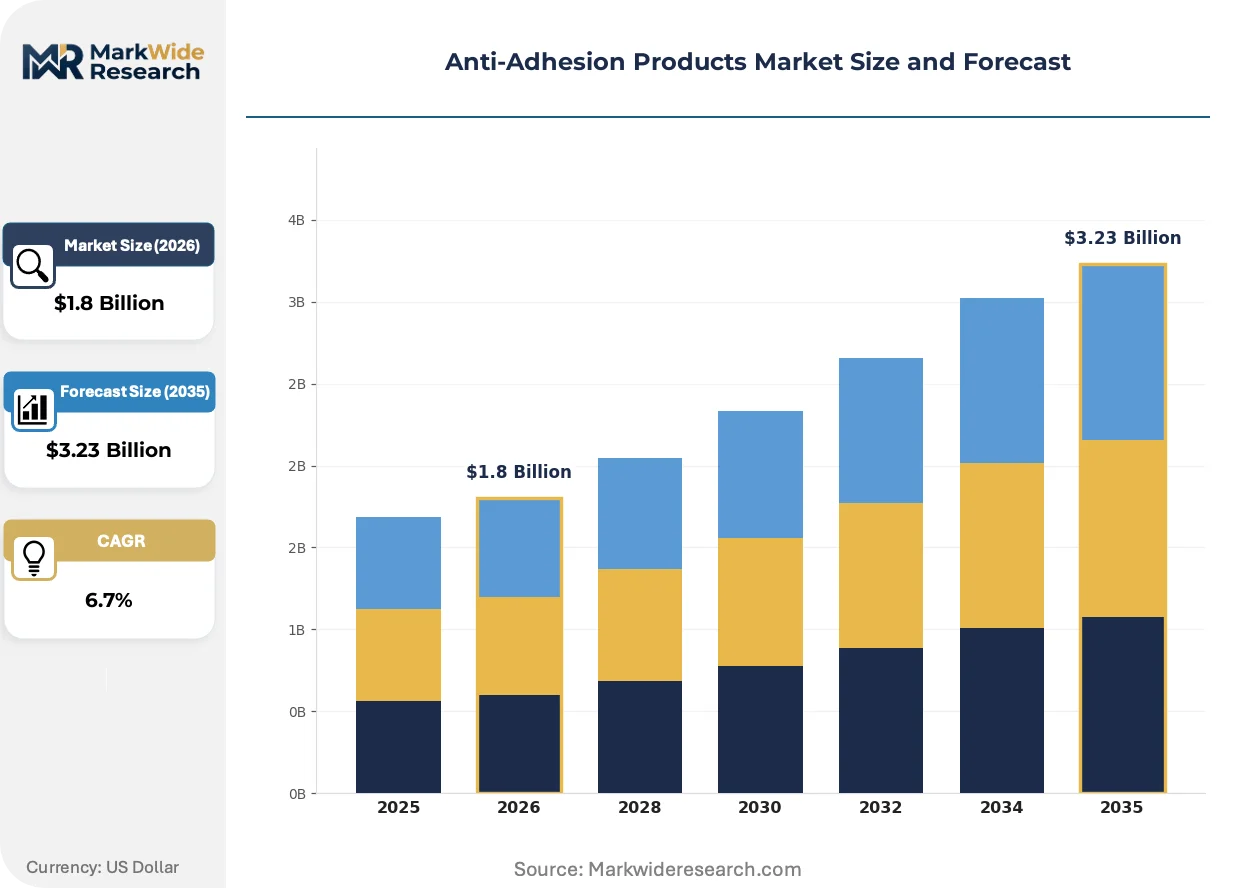
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Films, Liquids, Coatings Application: Surgeons, Orthopedics, Gynecology, Cardiology Material: Hydrogels, Silicone, Polyethylene, Polylactic Acid End User: Hospitals, Clinics, Outpatient Surgical Centers, Research Labs |
| Companies Covered | Baxter International, Johnson & Johnson, Integra LifeSciences, Anika Therapeutics, Sanofi, FzioMed, Ethicon, MAST Biosurgery, W.L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Adhesion Products Market Emerging Trajectories
Spray-applied liquid barriers are displacing conventional films in laparoscopic settings while regulatory bodies on both sides of the Atlantic rewrite evidence standards for bioresorbable implants.
Hydrogel precursor synthesis is modularizing across specialty chemical producers. Medical-grade polyethylene glycol and modified cellulose formulations now ship as dual-component systems requiring only sterile water activation at point of care. Ambulatory surgical centers in the United States are adopting these pre-filled applicators to eliminate pharmacy compounding steps. This modularity is compressing the barrier between raw material supplier and finished device manufacturer, enabling toll formulation partnerships that bypass traditional OEM supply chains.
Europe's MDR transition is reshaping clinical evidence requirements for Class III resorbable devices. Notified bodies now mandate prospective adhesion-specific endpoints rather than proxy safety metrics, forcing manufacturers to extend follow-up periods to 12-24 months. German and French health technology assessment bodies have synchronized their evidence demands with CE marking technical files, creating a unified documentation burden. Small and mid-cap developers without dedicated regulatory affairs infrastructure are outsourcing post-market surveillance to specialized CROs.
Hospital procurement committees are consolidating anti-adhesion purchasing into integrated surgical supply agreements. United States integrated delivery networks now bundle barriers with sutures, sealants, and mesh under single-source contracts spanning 3-5 years. This concentration is displacing individual surgeon preference decisions and elevating standardized application protocols. Gynecological service lines within these networks are piloting outcome-based supplier rebates tied to readmission rates for adhesion-related complications.
Anti-Adhesion Products Market Segmentation
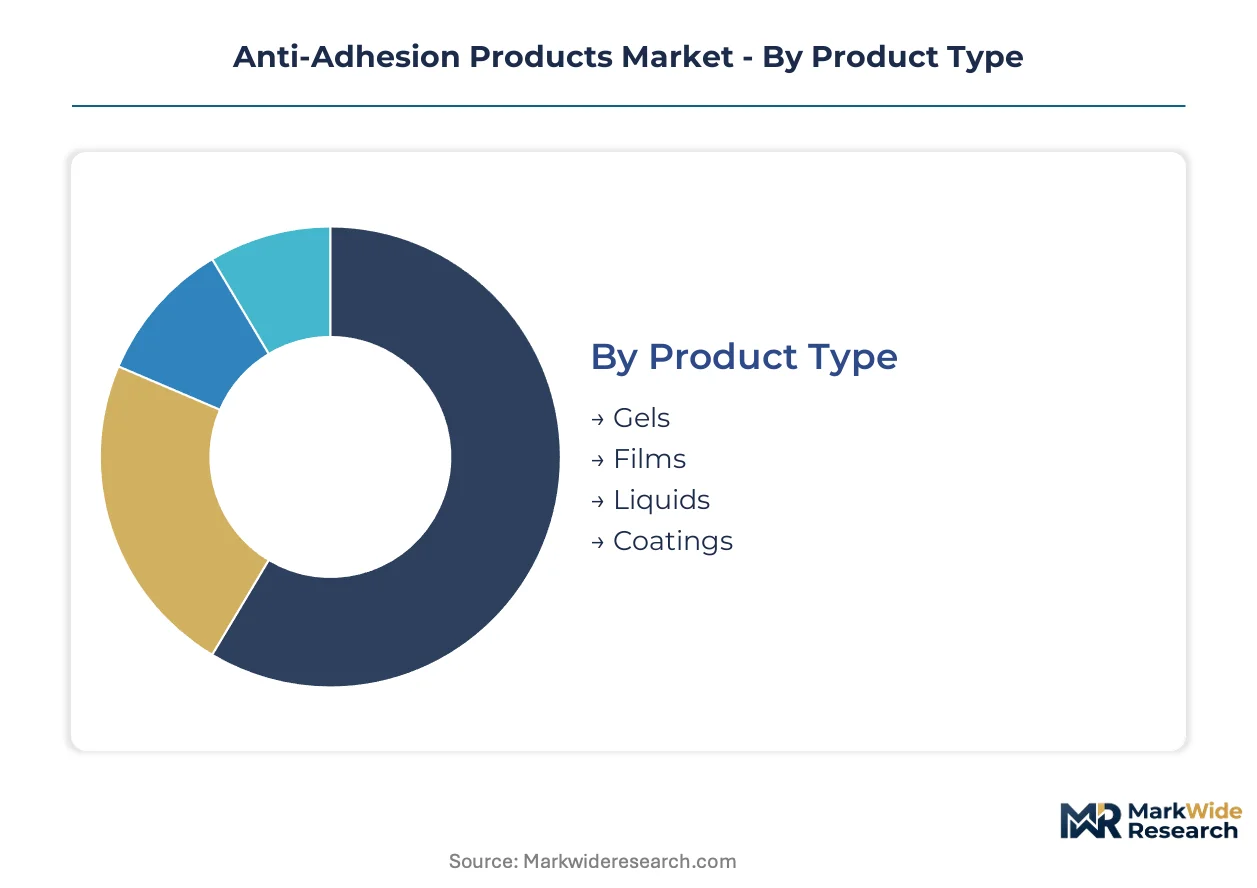
Anti-adhesion product selection hinges on surgical setting, anatomical site, and reimbursement pathway. Formulation chemistry and application method determine clinical utility across procedure types. Each segmentation dimension reveals distinct margin structures and competitive dynamics.
Product Type:
Film formulations command premium positioning in open procedures, while liquid spray systems capture volume growth in minimally invasive surgery.
- Films:Resorbable polymer sheets deliver predictable barrier duration with established CPT reimbursement codes. Demand concentrates in United States hospital systems with standardized gynecological protocols, though film placement time limits adoption in laparoscopic settings.
- Liquids:Spray-applied hydrogels achieve conformal coverage in complex anatomical spaces through laparoscopic delivery systems. United States ambulatory surgical centers favor single-use applicators that eliminate pharmacy compounding, driving fastest share gains across the analysis window.
- Gels:Viscous formulations provide tactile feedback during manual application in orthopedic and neurosurgical procedures.
- Coatings:Surface-integrated barriers suit mesh and implant combination products with extended degradation profiles.
Today's leader: Films. Tomorrow's challenger: Liquids.
Application:
Procedure-specific efficacy requirements shape formulation selection and regulatory strategy.
- Gynecology:Adhesion prevention in pelvic surgery carries the highest quality-of-life stakes, with FDA and EMA demanding procedure-specific endpoints. German and French health technology assessment bodies now require fertility outcome data for broad reimbursement.
- Orthopedics:Tendon and joint applications favor hydrogel compliance matching native tissue mechanics. United States sports medicine practices drive demand for rapid-application formats in high-volume arthroscopy.
- Surgeons:General surgical applications span multiple anatomical sites with varying barrier duration requirements.
- Cardiology:Pericardial and vascular applications demand specialized biocompatibility profiles with thromboresistant properties.
Gynecology generates the steepest expansion trajectory as fertility preservation protocols tighten adhesion prevention standards.
Material:
Raw material chemistry dictates degradation kinetics, manufacturing cost, and regulatory classification intensity.
- Hydrogels:Crosslinked polyethylene glycol and modified cellulose networks provide tissue-matched compliance with tunable resorption windows. Premium positioning reflects complex precursor synthesis and sterile activation requirements at point of care.
- Polylactic Acid:Aliphatic polyester barriers offer predictable hydrolytic degradation with established toxicology profiles. Supply concentrates among German and United States specialty chemical producers, creating procurement vulnerability for finished device manufacturers.
- Silicone:Non-resorbable sheets serve permanent separation indications with simplified 510(k) pathways.
- Polyethylene:Commodity-grade barriers compete on unit cost in high-volume hospital purchasing agreements, compressing margin for differentiated alternatives.
Margin concentrates in hydrogels; volume concentrates in polyethylene.
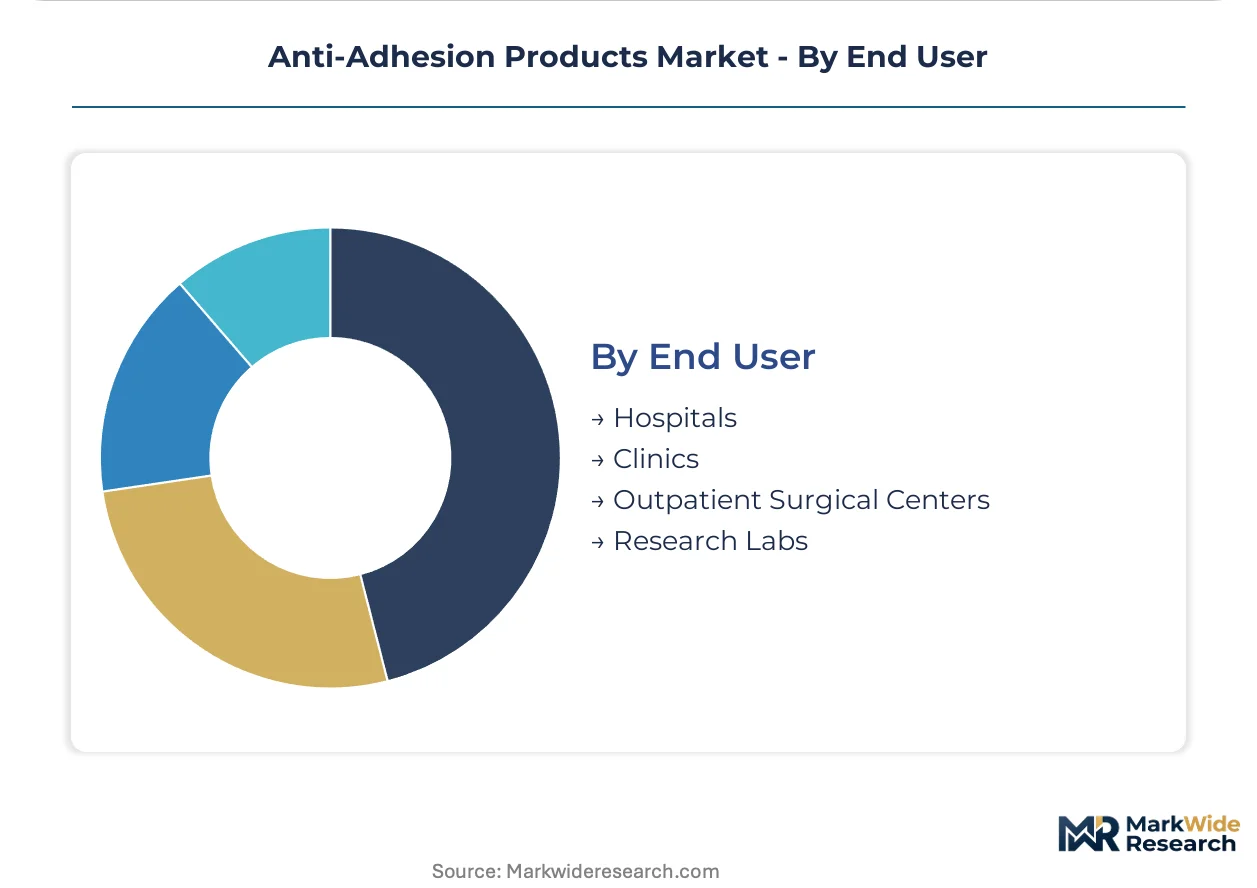
End User:
Site-of-care economics reshape packaging, pricing, and distribution architecture.
- Hospitals:Integrated delivery networks in the United States bundle barriers into multi-year surgical supply contracts spanning sutures, sealants, and mesh. Standardized protocols displace individual surgeon preference, elevating outcome-based supplier selection criteria.
- Outpatient Surgical Centers:Freestanding facilities prioritize ready-to-deploy formats eliminating pharmacy preparation steps. Pre-filled applicators and dual-component activation systems reduce staff training burden and infection control risk.
- Clinics:Office-based procedures favor compact packaging with extended shelf stability.
- Research Labs:Preclinical and clinical trial supply demands batch consistency documentation and investigational device exemption support.
Procurement centralization favors integrated delivery networks; agility favors outpatient surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates higher ambulatory surgical center volumes than Germany, yet both markets face tightening reimbursement evidence requirements for adhesion prevention technologies.
United States
Ambulatory surgical centers in Texas and Florida drive ready-to-deploy barrier adoption as outpatient gynecological procedures expand. FDA intensifies 510(k) scrutiny for novel resorbable formulations, extending regulatory timelines. The Boston-Cambridge corridor concentrates regenerative matrix R&D activity with proximity to major academic medical centers.
Germany
Specialty chemical producers in North Rhine-Westphalia scale medical-grade polylactic acid precursor output for hydrogel manufacturers. IQWiG pilots adhesion-specific quality-of-life endpoints that reshape health technology assessment criteria. The Rhine-Main cluster around Frankfurt hosts contract research organizations managing post-market surveillance for MDR compliance.
Japan
PMDA biocompatibility protocols extend registration timelines for foreign hydrogel manufacturers seeking peritoneal barrier indications. Tokyo and Osaka metropolitan areas concentrate laparoscopic surgery training centers that standardize spray application techniques. METI funding supports domestic development of controlled-degradation polymer platforms.
France
HAS demands fertility outcome data for broad gynecological reimbursement, elevating clinical evidence requirements. Lyon and Grenoble host medical polymer synthesis facilities serving barrier manufacturers. ANSM post-market surveillance obligations align with EMA guidance on resorbable implant safety monitoring.
China
NMPA accelerates review pathways for imported anti-adhesion devices while domestic manufacturers develop polyethylene glycol hydrogel alternatives. Shanghai and Suzhou concentrate medical device contract manufacturing for multinational barrier producers. Provincial procurement platforms in Guangdong and Jiangsu pilot volume-based purchasing for surgical supplies.
Anti-Adhesion Products Market Vendor Landscape
United States producers anchor one tier; Swiss and Irish specialists hold differentiated positions in regenerative substrates. The vendor base clusters around three strategic archetypes: diversified medical device conglomerates with cross-selling capabilities, pure-play regenerative medicine specialists, and commodity polymer converters competing on unit cost. Capacity expansion and outcome-based contracting with integrated delivery networks represent the dominant competitive moves reshaping market access.
Within the diversified conglomerate tier, Baxter International and Johnson & Johnson exemplify portfolio breadth that enables surgical kit bundling. Integra LifeSciences occupies a specialist position in regenerative tissue matrices. These three entities represent distinct strategic postures: integrated delivery network contracting leverage, surgeon training infrastructure, and regenerative substrate expertise respectively.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson |
| Integra LifeSciences |
| Anika Therapeutics |
| Sanofi |
| FzioMed |
| Ethicon |
| MAST Biosurgery |
| W.L. Gore & Associates |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty chemical producers in North Rhine-Westphalia and the Boston-Cambridge corridor exercise outsized influence on both medical-grade polylactic acid feedstock availability and hydrogel precursor pricing discipline. Their consolidated ownership structures enable coordinated capacity announcements that signal price floors to finished device manufacturers while limiting spot-market volatility.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for medical-grade polylactic acid while hydrogel precursors retain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates hydrogel formulations from polyethylene commodity barriers from silicone permanent implants. Cost compression in polyethylene tiers is intensifying because hospital purchasing committees consolidate procurement into multi-year integrated delivery network contracts. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement rates, while academic medical centers prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Boston, and Tokyo maintain hub-and-spoke patterns that position finished barriers within 48-hour delivery windows of major hospital systems. Geographic supply concentrates in Germany, the United States, and Japan for medical-grade polymer synthesis. Raw material dependencies rest on polyethylene glycol feedstock, modified cellulose derivatives, and aliphatic polyester precursors. Single-source vulnerability from limited polylactic acid specialty chemical producers creates procurement concentration risk. Distribution runs through integrated delivery network central purchasing with direct manufacturer contracting displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers can capture margin expansion by locating hydrogel precursor synthesis in Germany while serving United States ambulatory surgical center demand with ready-to-deploy formats. The regulatory cost differential between FDA 510(k) pathways and EMA MDR compliance creates strategic positioning opportunities.
For Market Incumbents: Acquire real-world evidence infrastructure and post-market surveillance capabilities to defend against emerging pure-play regenerative medicine specialists. Baxter International and Johnson & Johnson should deepen backward integration into hydrogel precursor production to secure supply against German specialty chemical producer consolidation. Investment in surgeon training networks for spray application standardization protects label expansion opportunities. For New Entrants and Emerging Players: Enter via neurosurgical matrix extension where regenerative tissue substrates face lower regulatory barriers than primary adhesion prevention claims. Target United States ambulatory surgical centers with pre-filled, ready-to-deploy liquid applicators that eliminate pharmacy compounding steps. Position against commodity polyethylene barriers through outcome-based contracting tied to readmission rate reductions. For Investors and Strategic Acquirers: Diversified medical device conglomerates are the most active acquirer in this space, seeking surgical kit bundling capabilities. Long-term viability hinges on MDR compliance infrastructure and health technology assessment alignment across German and French payer systems. Monitor IQWiG and NICE pilot programs for adhesion-specific quality-of-life endpoints as inflection indicators for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance with 12-24 month follow-up requirements anchors European market access for resorbable formulations. |
| Hospital System Partnership | Integrated delivery network bundling agreements with United States gynecological service lines secure multi-year volume commitments. |
| Backward Integration | In-house production of polyethylene glycol hydrogel precursors reduces dependency on German specialty chemical producers. |
| Reimbursement Strategy | FDA procedure-specific endpoints and HAS fertility outcome data alignment unlocks broad payer coverage in pelvic surgery. |
| Software Companion Development | Spray application technique guidance systems standardize laparoscopic outcomes across surgeon training variability. |
Methodological Framework
Direct dialogue with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs leads at barrier manufacturers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across formulation types and top-down market sizing through surgical procedure volume analysis enabled triangulation.
Bottom-up segmentation modeling tracked film, liquid, gel, and coating formulations across gynecological, orthopedic, general surgical, and cardiology applications. Hydrogel, polylactic acid, silicone, and polyethylene material chemistry provided vertical granularity. End-user splits between hospitals, outpatient surgical centers, clinics, and research labs captured site-of-care economics. CAGRs were derived from procedure volume growth rates and penetration assumptions across the analysis window.
Inputs from FDA premarket notification databases and EMA notified body guidance documents were available through the study window; gaps in real-world evidence for novel resorbable formulations introduce uncertainty bands around adoption curve assumptions. Forecasts reflect documented assumptions regarding regulatory timeline extensions and payer evidence requirement evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market