
 Silane Coupling Agents Market | 2026-2036
Silane Coupling Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Silane Coupling Agents Market Outlook
ISO 9001 certification cycles are reorganizing supplier eligibility across the silane coupling agents sector, forcing mid-tier producers to upgrade quality management systems or exit approved vendor lists. Evonik Industries AG leverages its integrated organosilicon backbone to sustain captive supply of high-purity chlorosilane intermediates. Dow anchors North American supply through Gulf Coast manufacturing complexes with direct pipeline feedstock access. BASF SE competes via specialty amino silane formulations tailored to automotive OEM bonding specifications.
Silane coupling agents are bifunctional organosilicon compounds bearing hydrolyzable alkoxy groups and organofunctional groups that chemically bridge inorganic substrates and organic polymers, typically manufactured through direct synthesis or hydrosilylation routes with purity grades exceeding 98 percent for electronics applications. Their primary industrial purpose is to improve adhesion, moisture resistance, and mechanical strength at interfaces between dissimilar materials. Amino silanes dominate volume consumption in adhesives and sealants where substrate wetting remains critical, while epoxy silanes capture expanding margin pools in electronics encapsulation driven by miniaturization trends. Vinyl silanes maintain mature positioning in wire and cable crosslinking with slower growth but stable replacement demand.
EPA oversight of volatile organic compound emissions from coating applications and REACH registration requirements for organosilicon substances in Europe are elevating formulation disclosure burdens and accelerating substitution toward lower-VOC delivery modes. China's GB standards through SAMR and evolving MEE environmental compliance protocols are reshaping local production qualifications for export-bound manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent purity and disclosure thresholds.
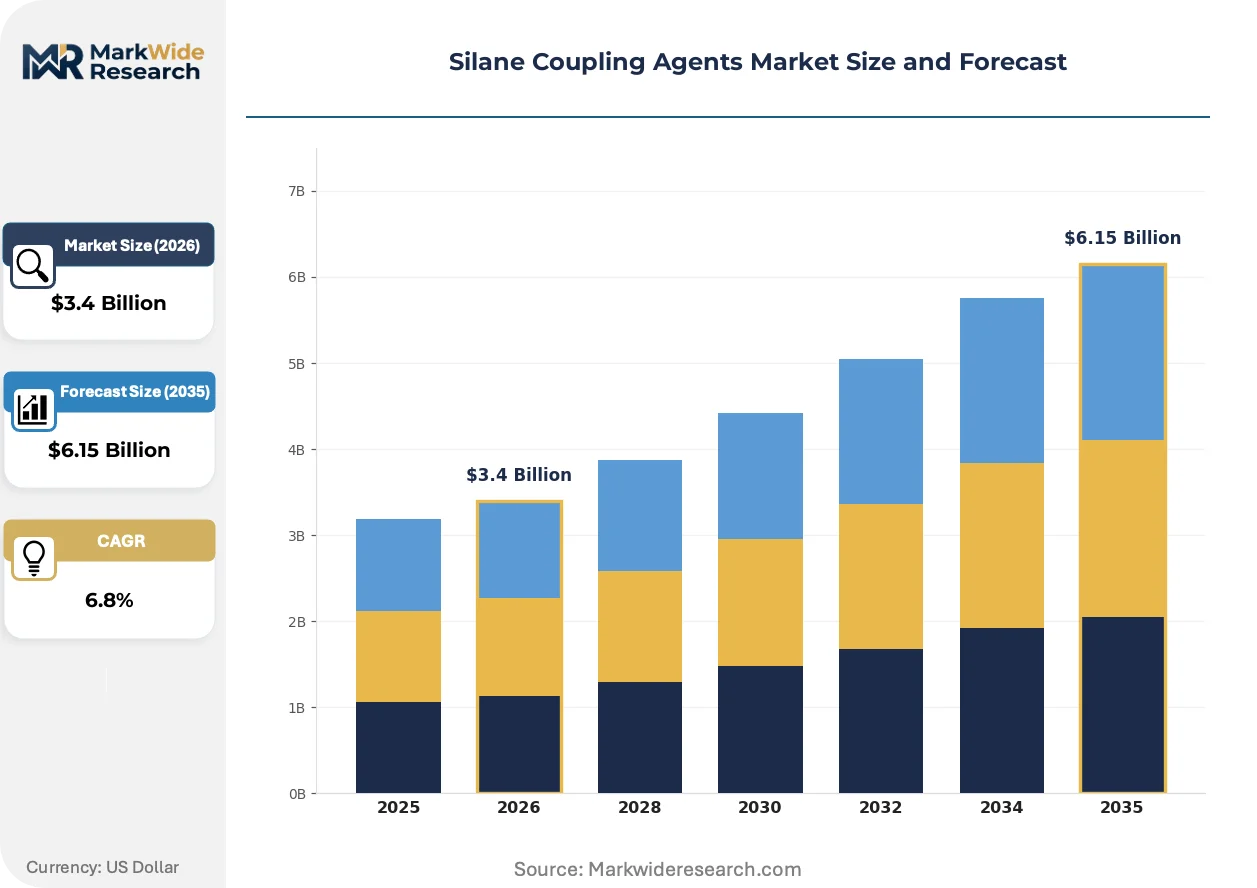
Market Dynamics
Automotive lightweighting mandates and electronics miniaturization are compressing formulation cycles for silane coupling agents, forcing suppliers to reconcile divergent purity specifications across regional regulatory regimes while scaling chlorosilane intermediate capacity.
Growth Catalysts
- EPA VOC emission limits:Coating manufacturers in the United States face tightening volatile organic compound thresholds, accelerating substitution toward waterborne silane delivery systems in architectural and industrial finishes.
- Wire and cable crosslinking:Vinyl silane demand persists in electrical infrastructure upgrades across mature markets, sustaining replacement volume despite slower expansion rates.
- China electronics procurement:Domestic semiconductor packaging and display manufacturing clusters are scaling specialty amino silane consumption for moisture-resistant encapsulation.
Market Restraints
- Chlorosilane feedstock concentration:High-purity intermediate production concentrates among integrated petrochemical complexes with direct silicon metal sourcing, limiting new entrant access.
- REACH substance registration:European organosilicon disclosure requirements impose multi-year compliance timelines and testing burdens on formulation exporters.
- Epoxy adhesive substitution:Cyanoacrylate and polyurethane systems capture select bonding applications where rapid cure speed outweighs silane-enhanced durability.
Strategic Opportunities
- India construction chemicals:Infrastructure investment and urbanization are expanding tile adhesive and waterproofing membrane markets where amino silane primers improve substrate bonding.
- Photovoltaic encapsulation:Bifacial solar module manufacturing requires advanced ethylene-vinyl acetate formulations with silane crosslinkers for edge-seal integrity.
- EU Green Deal chemistry:Sustainable-by-design criteria and bio-based feedstock incentives favor silane producers developing renewable carbon content verification.
Industry Challenges
- ISO 9001 recertification cycles:Mid-tier suppliers face compressed audit timelines and documentation upgrades to maintain automotive OEM approved vendor status.
- Legacy coating line retrofit costs:Waterborne silane system adoption requires capital expenditure for spray equipment corrosion resistance and drying capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silane Coupling Agents Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Silanes, Epoxy Silanes, Vinyl Silanes, Chlorosilane Application: Adhesives, Sealants, Coatings, Composites End User: Automotive, Construction, Electronics, Textiles Delivery Mode: Liquid, Powder, Paste, Emulsion |
| Companies Covered | DuPont, BASF SE, Evonik Industries AG, Wacker Chemie AG, Momentive, Dow, Shin-Etsu Chemical Co Ltd, TORAY Industries, Inc., AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silane Coupling Agents Market Strategic Shifts
Formulation chemistry is pivoting toward lower-VOC, higher-purity delivery modes as regulatory disclosure burdens intensify and end-use specifications diverge across automotive, electronics, and construction verticals.
Waterborne silane emulsion technology is decomposing solvent-based application dominance in architectural coatings. European decorative paint manufacturers are adopting these systems ahead of F-Gas Regulation phase-down schedules. The shift is compressing margins for conventional solvent carriers while rewarding emulsion stabilizer expertise.
REACH registration requirements for organosilicon substances are elevating supply chain transparency obligations across European coatings and adhesives sectors. Formulators must now document full substance composition down to 0.1 percent concentration thresholds. Specialty amino silane grades for electronics encapsulation face the steepest compliance cost escalation.
Specification-driven procurement now dominates automotive OEM silane sourcing, with bonding performance warranties replacing commodity spot purchasing. Tier-1 adhesive suppliers in Germany and Japan are consolidating approved vendor lists to single-source relationships with integrated chlorosilane producers. This concentration is most visible in electric vehicle battery module structural bonding applications.
Silane Coupling Agents Market Segmentation
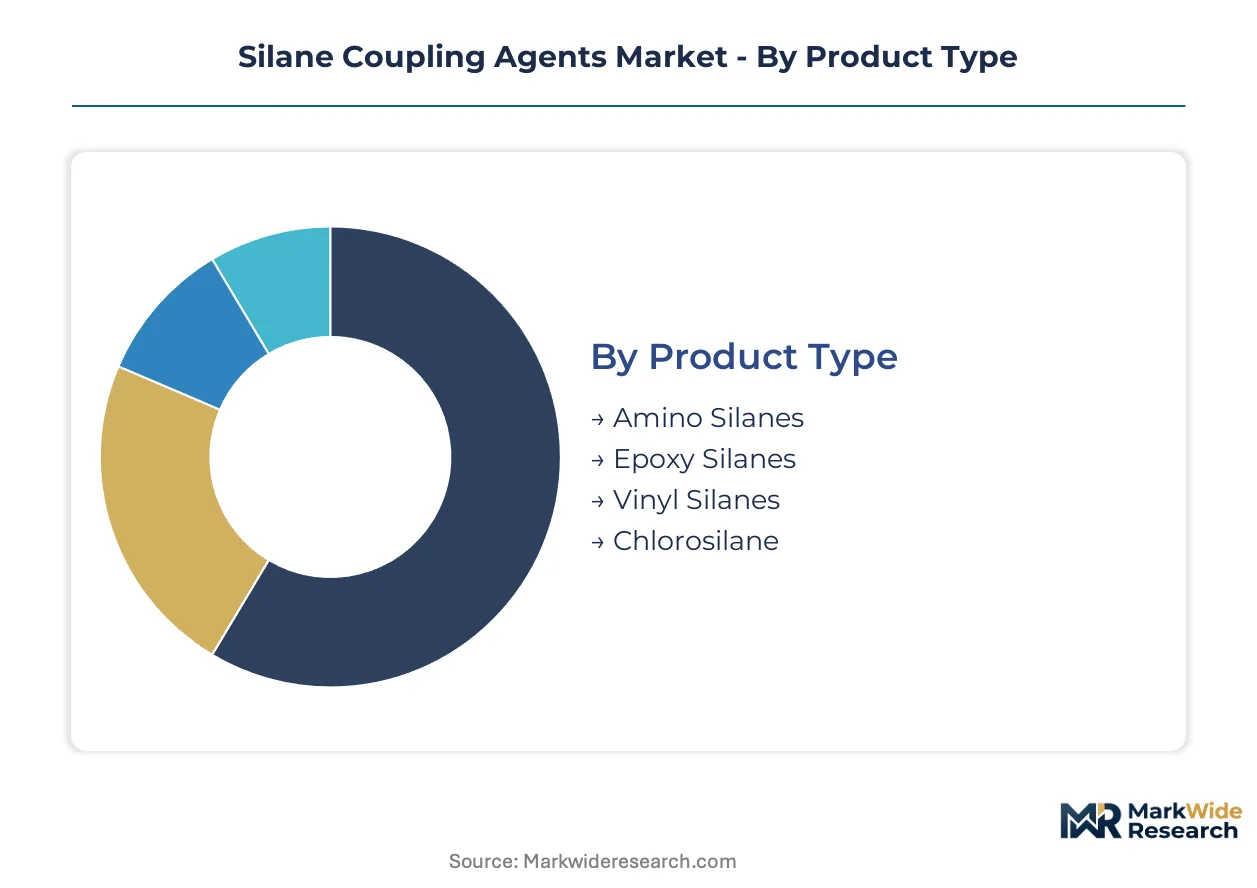
Silane coupling agents serve divergent purity and performance specifications across automotive bonding, electronics encapsulation, and construction waterproofing. Segmentation reveals where formulation chemistry investments concentrate and which delivery modes command premium positioning.
Product Type:
Margin pools concentrate in electronics-grade specialty grades where purity thresholds exceed 98 percent, while commodity amino silanes face pricing pressure from Asian capacity expansion.
- Amino Silanes:These compounds feature organofunctional amine groups attached to hydrolyzable alkoxy silanes, enabling strong substrate wetting for polar surfaces. Demand concentrates in construction adhesives across India and Southeast Asia where tile bonding specifications are tightening. India's BIS certification requirements for structural adhesives are elevating amino silane inclusion rates in cementitious formulations.
- Epoxy Silanes:Bifunctional molecules combining glycidoxy organofunctionality with trialkoxy silane moieties deliver superior moisture resistance for electronics applications. Semiconductor packaging clusters in South Korea and Taiwan are scaling epoxy silane procurement for advanced display encapsulation. Taiwan's Industrial Development Bureau incentives for domestic chemical self-sufficiency are accelerating local formulation capacity.
- Vinyl Silanes:Mature wire and cable crosslinking applications sustain replacement demand through electrical infrastructure renewal cycles.
- Chlorosilane:High-purity intermediates for captive synthesis dominate supply among integrated petrochemical producers with direct silicon metal access.
Amino silanes hold installed capacity across Chinese and Indian manufacturing bases. Epoxy silanes are rotating up the share rankings on semiconductor packaging demand.
Application:
Application mix tracks end-use durability requirements, with composites commanding specification premiums and coatings facing VOC compliance cost escalation.
- Adhesives:Structural bonding formulations for automotive lightweight composites require silane primers to bridge dissimilar substrates. Germany's KBA vehicle certification standards mandate documented adhesion performance for crash-critical bonded joints. OEM specification tightening is consolidating approved vendor lists toward integrated chlorosilane suppliers.
- Sealants:Moisture-cure polyurethane and silicone systems incorporate silane crosslinkers for durability in expansion joint applications. Japan's METI building energy efficiency standards are expanding high-performance sealant specifications for commercial construction. Tokyo's 2025 building code revisions target reduced thermal bridging through advanced joint sealing.
- Coatings:Architectural and industrial finishes face EPA VOC emission thresholds accelerating waterborne system adoption.
- Composites:Fiber-reinforced polymer manufacturing for wind turbine blades and electric vehicle structures depends on silane sizing agents for fiber-matrix adhesion.
Adhesives hold installed capacity from automotive specification lock-in. Composites are climbing the fastest on renewable energy and electric vehicle structural demand.
End User:
End user concentration reflects regional industrial structure, with electronics procurement scaling fastest in East Asian manufacturing clusters.
- Automotive:Electric vehicle battery module structural bonding and lightweight body-in-white applications specify amino and epoxy silane grades. US NHTSA crashworthiness standards are elevating adhesive performance documentation requirements for bonded aluminum-intensive vehicles. Michigan and South Carolina assembly plants are consolidating single-source relationships with Tier-1 adhesive suppliers.
- Construction:Tile adhesives, waterproofing membranes, and concrete repair systems incorporate silane primers for substrate compatibility. Saudi Arabia's MOHAP building material certification protocols are expanding silane-modified cementitious product registrations for Gulf megaproject procurement.
- Electronics:Semiconductor packaging, display encapsulation, and printed circuit board protection drive highest-purity silane consumption.
- Textiles:Fiber finishing and dye fixation applications maintain steady but slower-expanding silane demand.
Automotive holds installed capacity from specification-driven OEM procurement. Electronics is gaining share fastest on semiconductor packaging capacity expansion.
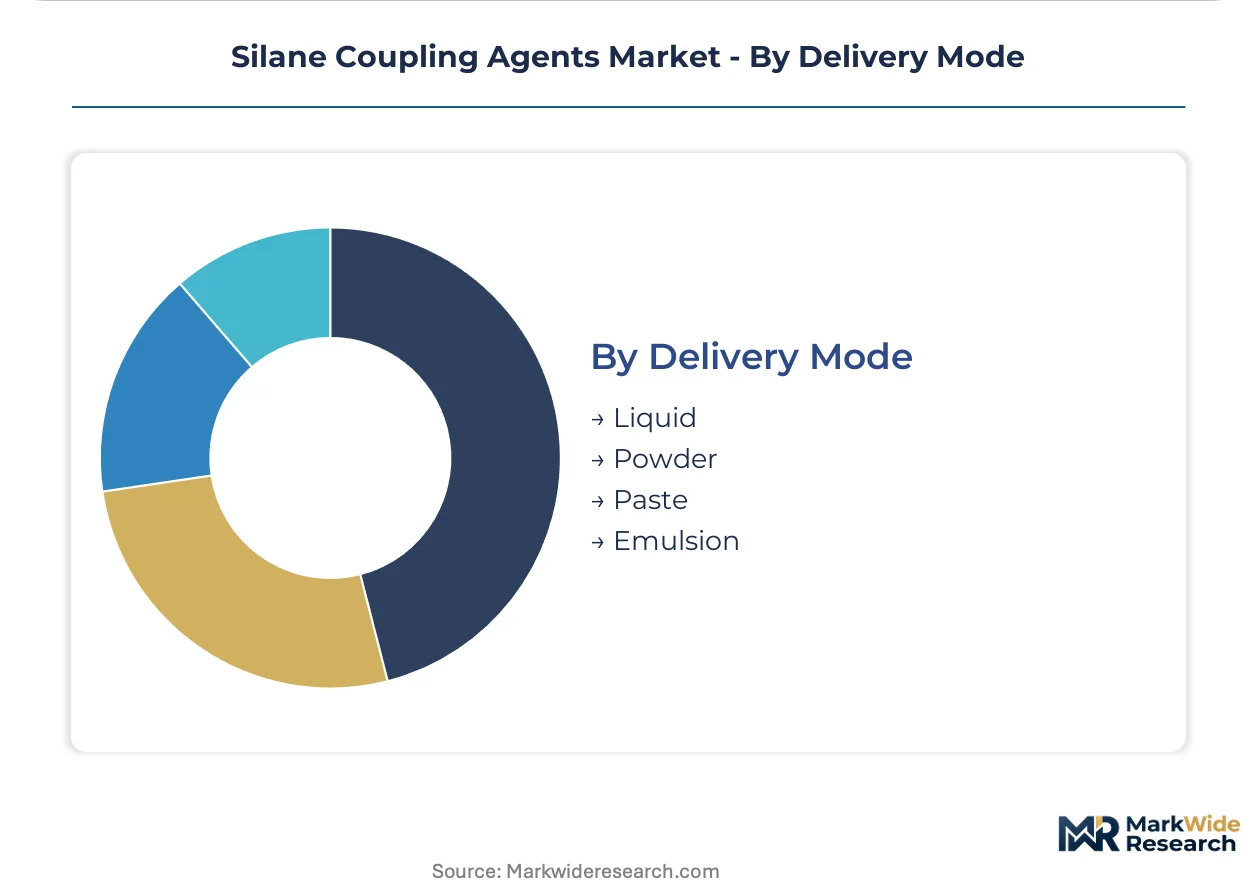
Delivery Mode:
Delivery mode economics pivot on solvent regulatory pressure, with waterborne emulsions displacing liquid carriers in coating applications.
- Liquid:Solvent-borne concentrates dominate industrial coatings and high-performance adhesives where rapid film formation remains critical. European F-Gas Regulation phase-down schedules are compressing solvent carrier margins ahead of emulsion technology maturation.
- Powder:Solid silane formulations serve high-temperature thermoset composite manufacturing where volatilization control matters.
- Paste:Thixotropic systems enable vertical surface application in construction sealants and repair mortars.
- Emulsion:Waterborne delivery systems are capturing architectural coating share as EPA VOC limits tighten and spray equipment corrosion resistance improves.
Liquid formulations hold installed capacity from industrial coating legacy infrastructure. Emulsion systems are rotating up the share rankings on regulatory-driven solvent substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission limits and REACH registration timelines are redrawing procurement geography for silane coupling agents. Manufacturers now site capacity to align with regulatory disclosure thresholds rather than feedstock proximity alone.
United States
Automotive OEMs in Michigan and South Carolina are consolidating single-source adhesive supplier relationships for electric vehicle battery bonding. NHTSA crashworthiness documentation requirements for bonded aluminum-intensive vehicles elevate specification burdens. Gulf Coast petrochemical complexes anchor chlorosilane intermediate supply with direct pipeline feedstock access.
Germany
KBA vehicle certification standards mandate documented adhesion performance for crash-critical bonded joints in lightweight automotive structures. REACH organosilicon substance registration imposes multi-year compliance timelines on formulation exporters. Frankfurt and Stuttgart adhesive clusters are narrowing approved vendor lists to integrated chlorosilane producers.
China
Domestic semiconductor packaging and display manufacturing clusters in Shanghai and Suzhou are scaling specialty amino silane consumption. GB standards through SAMR and MEE environmental compliance protocols reshape production qualifications for export-bound manufacturers. Yangtze River Delta chemical parks concentrate specialty silane formulation capacity.
Japan
METI building energy efficiency standards expand high-performance sealant specifications for commercial construction in Tokyo and Osaka. Tokyo's 2025 building code revisions target reduced thermal bridging through advanced joint sealing. Kansai region adhesive formulators are consolidating procurement relationships with regional silane suppliers.
India
Infrastructure investment and urbanization expand tile adhesive and waterproofing membrane markets in Maharashtra and Gujarat. BIS certification requirements for structural adhesives elevate amino silane inclusion rates in cementitious formulations. Mumbai-Pune industrial corridor construction chemical manufacturers are upgrading formulation specifications.
Silane Coupling Agents Market Competitive Environment
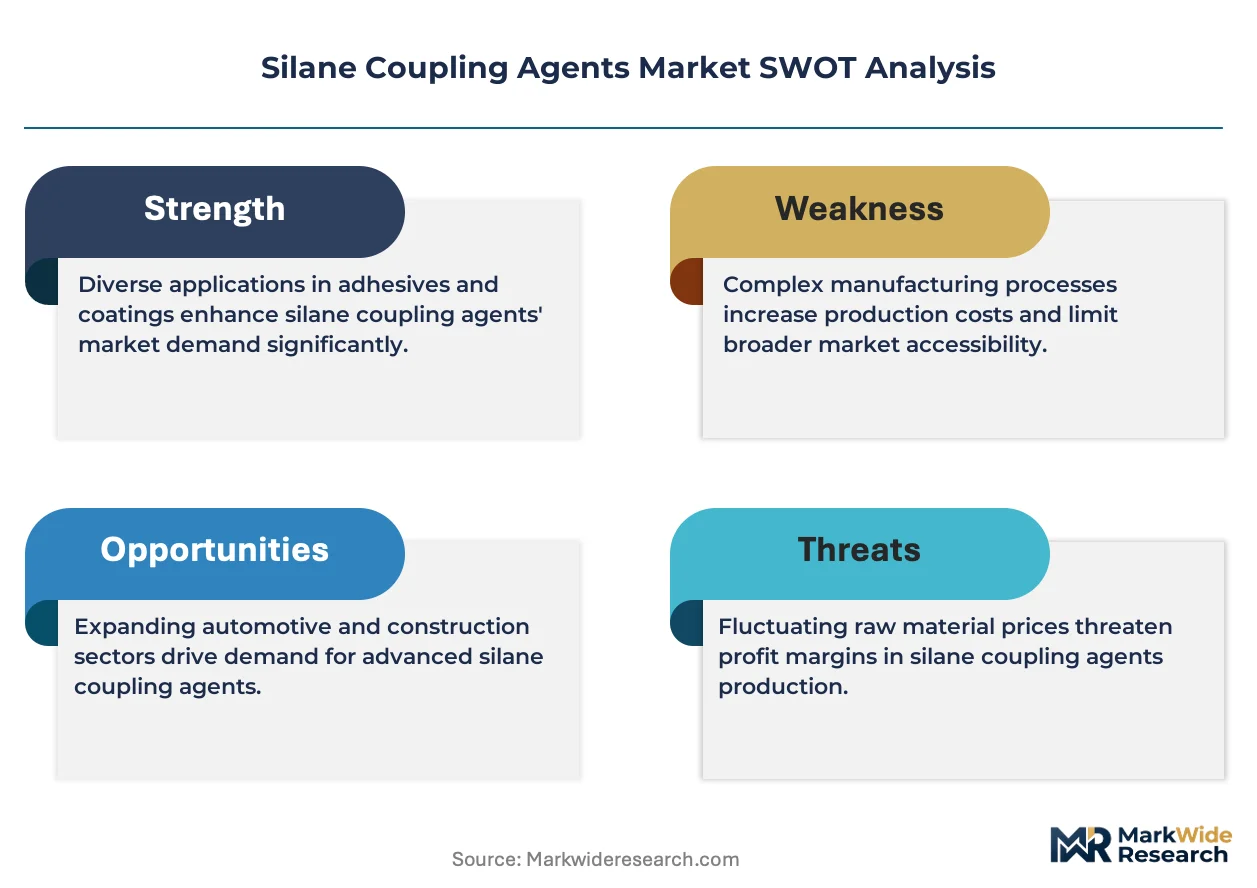
Player mix skews toward integrated petrochemical conglomerates with captive chlorosilane supply and specialty chemical divisions focused on organosilicon derivatives. The vendor base stratifies across three tiers: global diversified materials conglomerates, regional European and Asian chemical specialists, and emerging Chinese manufacturers scaling electronics-grade capacity. Two dominant competitive moves define positioning: backward integration into high-purity intermediate production and specification-driven partnerships with automotive Tier-1 adhesive suppliers.
Among integrated materials conglomerates, Evonik Industries AG, Dow, and BASF SE exemplify distinct strategic archetypes. Evonik occupies a position anchored on organosilicon backbone integration. Dow represents Gulf Coast manufacturing scale with direct feedstock pipeline access. BASF SE sits within the specialty formulation tier, emphasizing amino silane grades tailored to automotive OEM bonding specifications. These three companies illustrate how competitive positioning diverges across supply chain control points versus formulation specialization.
| Leading Market Players |
|---|
| DuPont |
| BASF SE |
| Evonik Industries AG |
| Wacker Chemie AG |
| Momentive |
| Dow |
| Shin-Etsu Chemical Co Ltd |
| TORAY Industries, Inc. |
| AkzoNobel N.V. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day chlorosilane intermediate lead times concentrate pricing power among integrated Gulf Coast and Yangtze River Delta producers with direct silicon metal sourcing, compressing margin capture for non-integrated formulators dependent on spot procurement.
Pricing Analysis
Certification level creates the primary spread across silane coupling agent tiers, with electronics-grade ISO 9001-certified formulations commanding substantial premiums over industrial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in purity thresholds, with 98-plus-percent grades for semiconductor encapsulation priced distinctly from construction adhesives. Cost compression in commodity amino silanes is intensifying because of Chinese capacity expansion. Construction chemical buyers exhibit highest price sensitivity, while automotive OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate chlorosilane procurement among integrated petrochemical complexes, while just-in-time inventory management prevails among downstream adhesive formulators with limited storage infrastructure. Supply concentrates in the United States, China, and Germany, with high-purity intermediate production anchored in Gulf Coast pipeline corridors and Yangtze River Delta chemical parks. Manufacturing draws from silicon metal, methanol, and chlorine feedstocks. Single-source vulnerability persists for electronics-grade specialty grades dependent on Taiwan and South Korean packaging clusters. Distribution runs through direct pipeline supply for integrated producers and regional chemical distributors for formulation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silane coupling agents constitute a high-growth disruption as EPA VOC emission limits and REACH registration timelines force formulation chemistry pivots toward waterborne delivery systems and elevated purity thresholds.
For Market Incumbents: Fortify captive chlorosilane supply through backward integration into high-purity intermediate production, eliminating feedstock vulnerability to spot market volatility. Deepen ISO 9001 certification investment to maintain automotive OEM approved vendor status against emerging Chinese electronics-grade competitors. Prioritize specification-driven partnerships with Tier-1 adhesive suppliers in Germany and Japan.
For New Entrants and Emerging Players: Differentiate on India construction chemicals penetration, where BIS certification requirements and infrastructure investment create adhesive formulation white space underserved by integrated conglomerates. Target photovoltaic encapsulation crosslinker supply for bifacial module manufacturers seeking domestic sourcing alternatives. Pursue technical service partnerships with regional construction chemical distributors as primary go-to-market channel.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates seeking to divest non-core organosilicon divisions amid portfolio rationalization pressures. Long-term viability hinges on exposure to semiconductor packaging and electric vehicle structural bonding demand trajectories. Monitor EPA VOC rulemaking timelines and F-Gas Regulation phase-down schedules as inflection indicators for waterborne emulsion technology adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Intermediates | Captive supply secures margin capture against feedstock volatility in Gulf Coast and Yangtze River Delta corridors. |
| Waterborne Emulsion Technology Scale-Up | EPA VOC compliance and F-Gas Regulation alignment position formulators for architectural coating substitution cycles. |
| ISO 9001 Certification Investment | Automotive OEM approved vendor retention depends on documented quality management system compliance. |
| India Construction Chemical Partnership | BIS certification pathways and infrastructure procurement expand amino silane primer inclusion in cementitious formulations. |
| Photovoltaic Encapsulation Crosslinker Supply | Bifacial module edge-seal specifications drive ethylene-vinyl acetate formulation demand for renewable energy manufacturing. |
Study Parameters
A standing panel of chlorosilane plant managers, automotive Tier-1 adhesive procurement leads, electronics packaging R&D directors, and construction chemical distribution channel partners provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR GB standards documentation. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value outputs.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled grade tier, end-use industry, delivery mode, and regional production hub segmentation dimensions. CAGRs were derived from historical trajectory analysis and demand elasticity modeling. Forecast inputs incorporated EPA regulatory timeline assumptions, semiconductor packaging capacity expansion patterns, and electric vehicle production cluster localization trends.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or REACH registration compliance timelines would require recalibration. Forecasts reflect documented assumptions regarding chlorosilane feedstock availability and regional regulatory divergence. Revision becomes warranted when China GB standard implementation or F-Gas Regulation phase-down schedules cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Global Electronics Adhesives Market