
 Canada Sealants Market | 2026-2036
Canada Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Sealants Market Outlook
CSA A440.4 qualification for fenestration sealant performance is collapsing the supplier pool as smaller compounders exit the certification cycle. Sika AG dominates Western Canada's infrastructure envelope segment with captive distribution networks. Henkel AG & Co. KGaA leverages its Loctite industrial platform to anchor automotive OEM supply chains in Southern Ontario. Dow Inc competes on silicone chemistry breadth across building and electronics applications.
Canada sealants comprise elastomeric compounds—typically silicone, polyurethane, acrylic, or butyl polymers cured through moisture, heat, or UV initiation—that form impermeable barriers between substrates, with Shore A hardness ranging from 15 to 50 and movement accommodation of ±25% to ±50%. Silicone formulations lead commercial building envelopes due to UV stability and 20-year service life expectations, while polyurethane captures infrastructure expansion joints where dynamic load tolerance matters. Acrylic segments occupy the paintable interior finishing tier with thinner margin pools, and butyl remains entrenched in preformed tape applications for automotive NVH dampening.
Health Canada's PMRA governs biocide-containing formulations under the Pest Control Products Act, while Environment and Climate Change Canada enforces VOC concentration limits under the Canadian Environmental Protection Act that disqualify solvent-based systems from federal projects. The Canadian Construction Materials Centre maintains evaluation protocols that gate provincial building code adoption, particularly in Quebec and Alberta. Stakeholders must monitor impending federal green procurement standards that will privilege low-embodied-carbon sealant chemistries in infrastructure tenders.
Market Dynamics
CSA A440.4 certification requirements for fenestration sealants are consolidating the Canadian supplier base as smaller compounders abandon the costly qualification cycle, while Environment and Climate Change Canada's low-VOC mandates simultaneously filter product portfolios.
Growth Catalysts
- Seismic-resistant building codes:Vancouver's stringent structural requirements for high-rise envelope systems are accelerating specification of high-performance polyurethane and silicone formulations in British Columbia's commercial construction sector.
- Health Canada PMRA compliance reviews:Biocide-containing sealant formulations face rigorous evaluation under the Pest Control Products Act, creating competitive advantage for pre-approved compounders in federal infrastructure tenders.
- Greater Toronto Area high-rise concentration:Ontario's dense urban development pipeline generates sustained demand for 20-year service life silicone systems in curtain wall and window wall applications.
Market Restraints
- Silicone monomer supply concentration:Western Canadian distributors remain dependent on Asian and US Gulf Coast feedstock sources, exposing margins to trans-Pacific shipping volatility and currency fluctuation.
- Solvent-based formulation disqualification:Canadian Environmental Protection Act VOC concentration limits have eliminated conventional solvent chemistries from federal procurement channels without cost-competitive waterborne alternatives.
- CSA A440.4 testing burden:The Canadian Standards Association's fenestration sealant qualification protocol imposes six-figure certification costs that bar regional compounders from specification-grade commercial projects.
Strategic Opportunities
- Alberta industrial retrofit wave:Calgary and Edmonton's aging petrochemical infrastructure presents untapped demand for high-temperature silicone and polysulfide joint sealants in turnaround maintenance cycles.
- Federal green procurement standards:Impending low-embodied-carbon mandates for infrastructure tenders will privilege bio-based and recycled-content sealant formulations ahead of conventional petroleum-derived products.
- Automotive OEM supply chain reconfiguration:Southern Ontario electric vehicle battery plant construction is decomposing traditional paint-shop adhesive specifications, opening entry points for advanced hybrid sealant technologies.
Industry Challenges
- Formulation chemist talent scarcity:Canadian universities produce limited graduates with specialized polymer curing expertise, forcing compounders to recruit from European and American competitor pools.
- CCMC evaluation timeline compression:The Canadian Construction Materials Centre's provincial building code adoption protocols create 18-24 month lag between product submission and commercial specification eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Sealants Market |
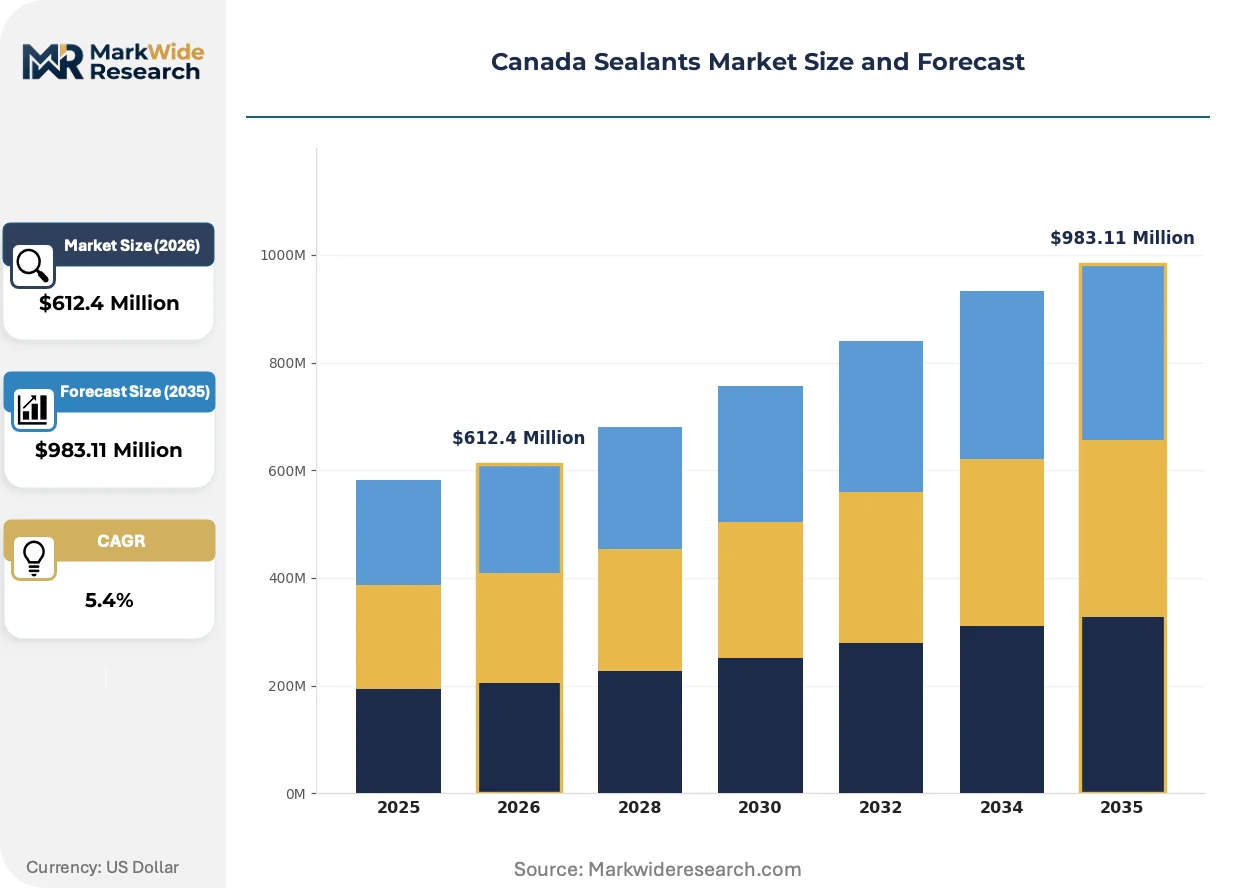
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $983.11 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Butyl End User: Construction, Automotive, Electronics, Aerospace Application: Sealing, Bonding, Insulation, Waterproofing Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller, Dow Inc, Tremco, Bostik, Mapei, Wacker Chemie AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Sealants Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based feedstocks and hybrid polymer systems as regulatory pressure compounds with end-user sustainability mandates across Canadian construction and industrial channels.
Hybrid silyl-terminated polyether (STPE) technology is decomposing the traditional silicone-polyurethane segment boundary by combining UV stability with paintability. Ontario commercial envelope contractors are specifying STPE for mixed-substrate curtain walls where aesthetic flexibility matters. The technology is decomposing established supplier relationships as building envelope consultants rewrite master specifications around performance metrics rather than polymer chemistry families.
Environment and Climate Change Canada's 2024-2028 VOC concentration limit phase-down is eliminating solvent-based acrylics from federal infrastructure procurement. Alberta and Quebec provincial building codes are adopting the federal thresholds ahead of schedule, compressing the transition window for remaining solvent-dependent compounders. Interior finishing contractors in Toronto and Montreal are switching to waterborne acrylics despite thinner margin profiles and extended cure times.
Building envelope commissioning protocols now mandate third-party adhesion testing before final payment release. Ontario's condominium developers are inserting performance bonds into sealant subcontractor agreements, transferring 10-year warranty risk to applicators. This behavioral shift concentrates specification authority with commissioning agents rather than general contractors in Vancouver and Toronto high-rise projects.
Canada Sealants Market Segmentation
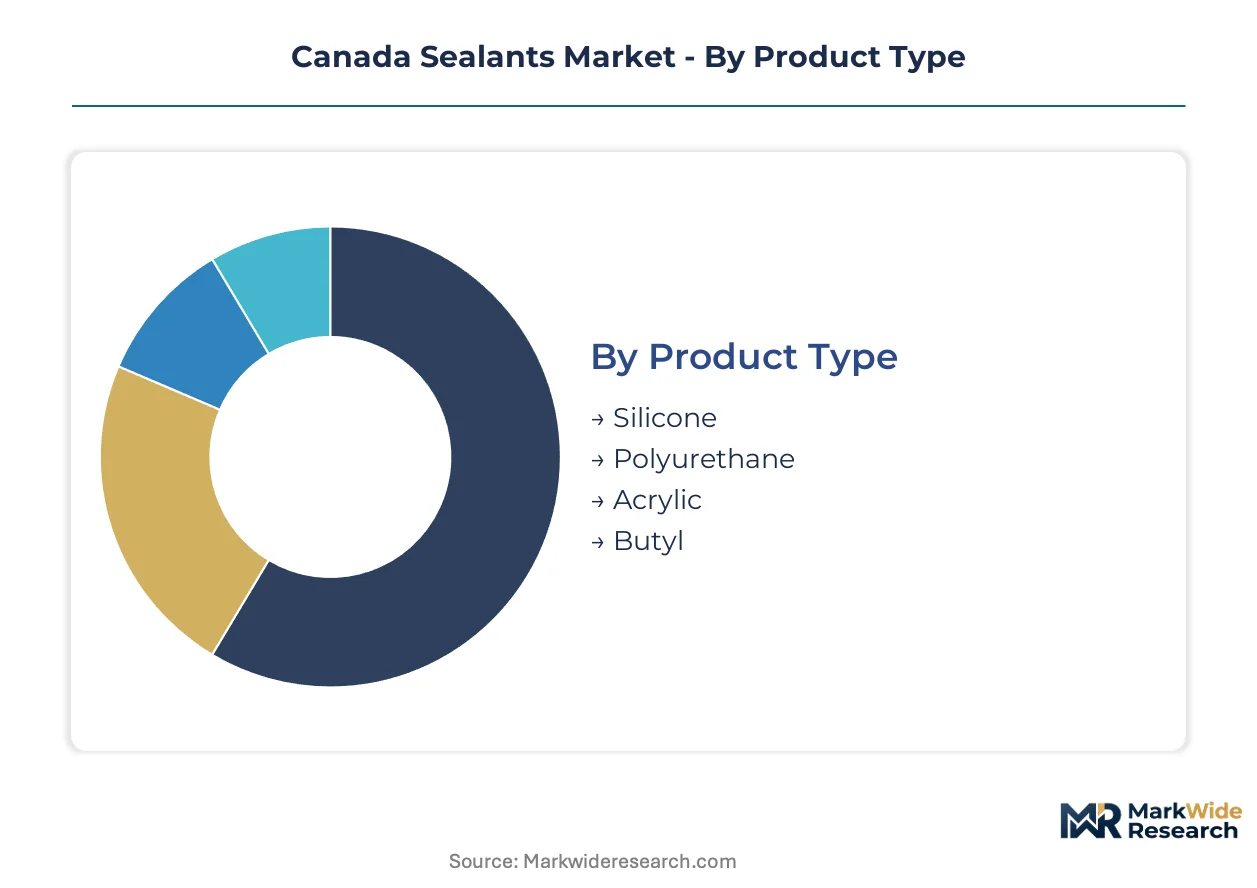
Segmentation in the Canada sealants market reveals distinct channel economics and specification hierarchies. Product chemistry determines margin pools, while end-use verticals dictate certification burdens and distribution access.
Product Type:
Channel mix varies sharply by polymer chemistry—silicone and polyurethane flow through specification-grade distributor networks, while acrylic and butyl segments split between retail hardware and direct industrial procurement.
- Silicone:UV-stable formulations with 20-year service life dominate commercial envelope specifications in Vancouver and Toronto high-rises. Demand concentrates in curtain wall applications where Health Canada PMRA-compliant biocide systems are mandatory for federal infrastructure.
- Polyurethane:Dynamic load-tolerant compounds capture infrastructure expansion joints and seismic-resistant building systems in British Columbia. Alberta's petrochemical turnaround maintenance cycles are driving specification of high-temperature variants.
- Acrylic:Paintable waterborne formulations serve interior finishing contractors in Montreal and Toronto despite extended cure times and thinner margins.
- Butyl:Preformed tape applications anchor automotive NVH dampening supply chains in Southern Ontario's OEM assembly plants.
By volume, silicone leads. By growth pace, polyurethane is expanding most quickly.
End User:
Cost tier stratification separates specification-grade construction and aerospace from price-sensitive automotive and electronics procurement channels.
- Construction:Building envelope contractors in the Greater Toronto Area and Vancouver specify CSA A440.4-certified systems with 10-year performance bonds. Low-VOC mandates from Environment and Climate Change Canada are filtering product portfolios toward waterborne and hybrid chemistries.
- Automotive:Southern Ontario electric vehicle battery plant construction is decomposing traditional paint-shop adhesive specifications, creating entry points for advanced hybrid sealant technologies.
- Electronics:Dow Inc competes on silicone chemistry breadth for device assembly applications with shorter qualification cycles than construction.
- Aerospace:Specialized high-performance compounds face extended CCMC evaluation timelines and limited domestic compounding capacity.
Construction generates the deepest specification authority. Automotive is gaining share fastest amid EV supply chain reconfiguration.
Application:
Application function determines margin structure—waterproofing and insulation command premium pricing, while commodity sealing and bonding face thinner pools.
- Sealing:Fenestration and expansion joint work requires CSA A440.4 certification that consolidates supplier pools around Sika AG and Henkel's captive distribution networks.
- Bonding:Structural adhesive applications in Ontario's high-rise envelope systems demand third-party adhesion testing before final payment release.
- Insulation:Thermal barrier specifications in Alberta's industrial retrofit wave privilege high-temperature silicone and polysulfide formulations.
- Waterproofing:Below-grade and plaza deck applications in Vancouver's seismic code environment specify movement-accommodating polyurethane systems.
Waterproofing holds the steepest pricing power. Bonding is climbing fastest as envelope commissioning protocols expand.
Distribution Channel:
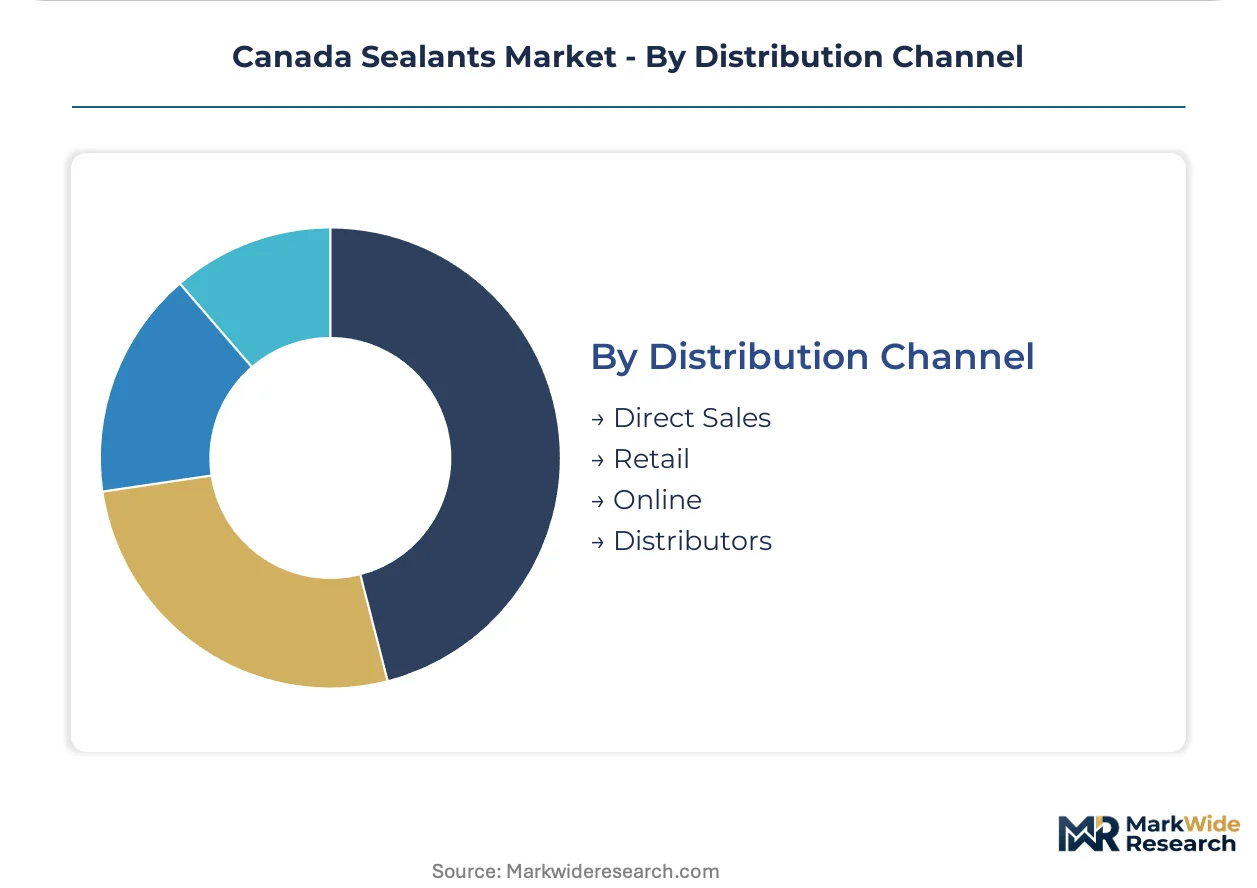
Customer type and geography fragment channel access—direct sales serve OEM automotive and aerospace, while retail and online capture maintenance-repair-operators and residential finishing.
- Direct Sales:Automotive OEM supply chains in Southern Ontario and federal infrastructure tenders require direct technical support and PMRA compliance documentation.
- Retail:Home improvement channels in Toronto and Montreal stock waterborne acrylics for interior finishing contractors switching from solvent-based systems.
- Online:E-commerce penetration remains limited to commodity maintenance products; specification-grade sealants resist digital procurement due to adhesion testing requirements.
- Distributors:Sika AG's captive Western Canada infrastructure envelope network exemplifies specification-grade channel control.
Distributors dominate value capture. Direct sales are expanding most quickly as federal green procurement standards reshape tender requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans Mountain Pipeline expansion underwrites Western Canada's industrial sealant demand through Calgary and Edmonton petrochemical maintenance cycles. Ontario's Highway 401 corridor anchors Eastern Canadian construction specification authority.
Ontario
The Greater Toronto Area's high-rise envelope pipeline generates sustained demand for 20-year service life silicone systems in curtain wall applications. Environment and Climate Change Canada's low-VOC mandates filter product portfolios toward waterborne formulations in federal infrastructure tenders. Hamilton's steel fabrication cluster drives specification of high-temperature joint sealants in industrial retrofit cycles.
British Columbia
Vancouver's seismic-resistant building codes accelerate adoption of movement-accommodating polyurethane formulations in commercial high-rises. Health Canada's PMRA compliance reviews under the Pest Control Products Act create competitive advantage for pre-approved biocide-containing compounders. The Vancouver-Seattle Cascadia corridor concentrates specification-grade distributor networks serving envelope contractors.
Alberta
Calgary and Edmonton's aging petrochemical infrastructure presents demand for high-temperature silicone and polysulfide joint sealants in turnaround maintenance. The Canadian Environmental Protection Act disqualifies solvent-based systems from federal procurement channels. The Industrial Heartland northeast of Edmonton anchors specification of thermal barrier sealants in refinery expansion projects.
Quebec
Montreal's condominium development pipeline drives interior finishing demand for paintable waterborne acrylics despite extended cure times. The province's adoption of federal VOC thresholds ahead of schedule compresses transition windows for solvent-dependent compounders. Quebec City's institutional construction sector specifies CSA A440.4-certified fenestration systems in government building envelopes.
Atlantic Canada
Halifax's port infrastructure expansion generates marine-grade sealant demand for corrosion-resistant below-grade waterproofing. The Canadian Construction Materials Centre evaluation protocols gate provincial building code adoption in Nova Scotia and New Brunswick. St. John's offshore oil maintenance cycles drive specification of subsea-qualified polyurethane formulations.
Canada Sealants Market Competitive Environment
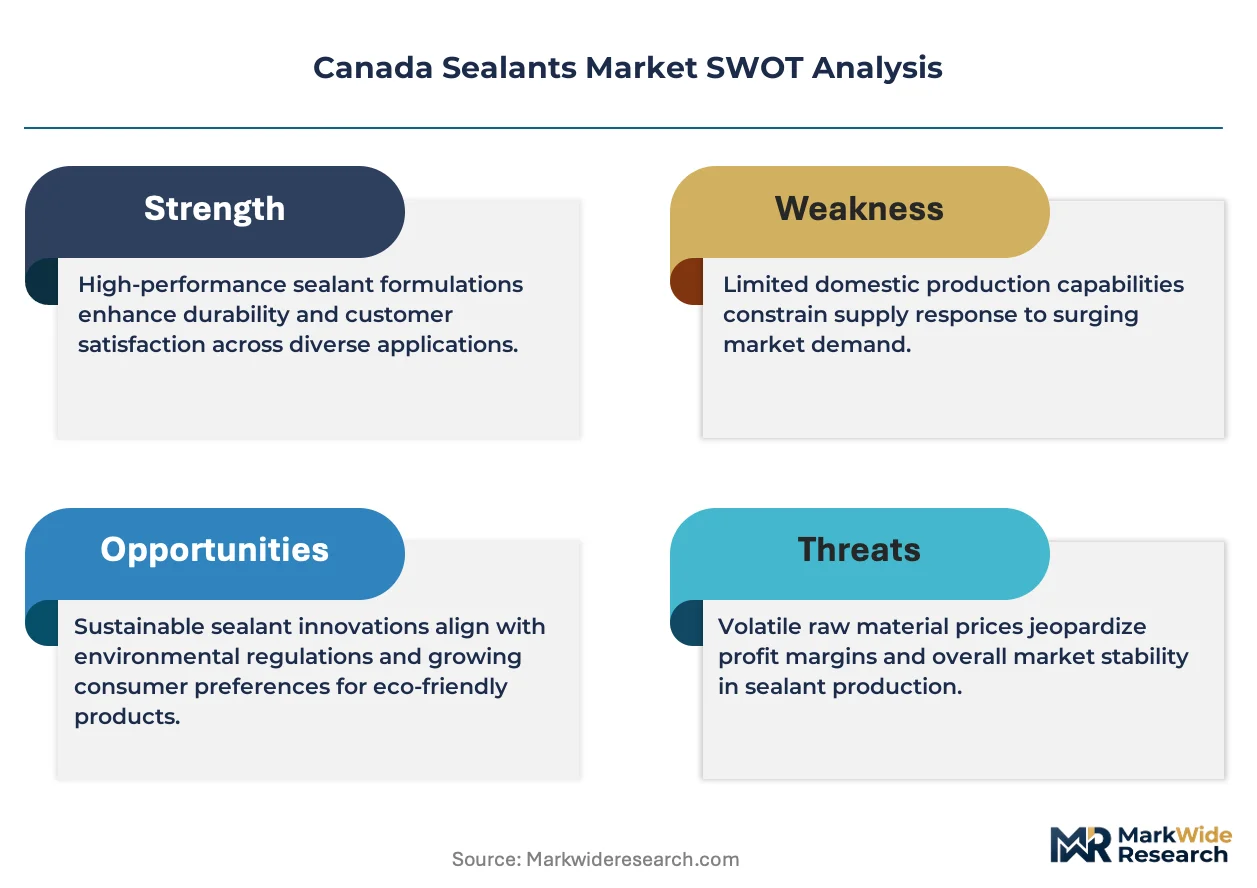
Listed leaders compete with private specialists across certification burden and distribution access in Canada's sealant sector. Sika AG and Henkel AG & Co. KGaA anchor the consolidated tier through captive specification-grade networks, while regional compounders retreat from CSA A440.4 qualification cycles. Three archetypes dominate: integrated chemical conglomerates with polymer breadth, construction-focused specialists with envelope expertise, and automotive-industrial hybrids with Southern Ontario OEM access. Competitive moves concentrate on M&A for regional distributor control and portfolio diversification into hybrid STPE technologies.
Within the construction-specialist tier, Sika AG exemplifies Western Canada infrastructure envelope dominance through specification-grade channel control. Henkel AG & Co. KGaA occupies a position anchoring automotive OEM supply chains in Southern Ontario through its Loctite industrial platform. Dow Inc represents the integrated chemical conglomerate archetype, competing on silicone chemistry breadth across building and electronics applications.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller |
| Dow Inc |
| Tremco |
| Bostik |
| Mapei |
| Wacker Chemie AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Western Canadian distributors and Asian silicone monomer suppliers lock in both feedstock access and margin visibility against trans-Pacific shipping volatility and currency fluctuation. These arrangements insulate compounders from spot market spikes while embedding freight cost pass-through clauses that shift logistics risk downstream to envelope contractors in Vancouver and Toronto.
Pricing Analysis
Certification level creates the primary spread across the Canada sealants market, with CSA A440.4-qualified systems commanding substantial premiums over uncertified alternatives in commercial envelope specifications. Three-tier pricing structure separates specification-grade silicone and polyurethane from standard waterborne acrylics and economy retail hardware segments. Pricing pressure stems from Environment and Climate Change Canada's VOC phase-down eliminating solvent-based margins without cost-competitive replacements. Residential finishing contractors in Montreal and Toronto exhibit highest price sensitivity, while federal infrastructure tenders anchored by Health Canada PMRA compliance show lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as Canadian compounders buffer against Asian silicone monomer supply disruptions and US Gulf Coast feedstock volatility. Supply concentrates in China, South Korea, and the United States for silicone base polymers, isocyanates for polyurethane synthesis, and acrylic emulsion precursors. Raw material dependencies rest on silane coupling agents, polyether polyols, and titanium dioxide pigment grades. Single-source vulnerability from concentrated Asian monomer production exposes margins to tariff escalation and shipping chokepoint disruption. Distribution runs through Sika AG's captive Western Canada infrastructure envelope network and Henkel's specification-grade channels serving Ontario automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada sealants market tracks a cyclical recovery pattern as Alberta's petrochemical turnaround maintenance wave and Ontario's electric vehicle battery plant construction reactivate industrial demand channels. Residential construction permits in the Greater Toronto Area and Vancouver provide the confirming cyclical driver.
For Market Incumbents: Fortify specification-grade channel control through accelerated CSA A440.4 certification investment and captive distributor acquisition in British Columbia's seismic-resistant building envelope segment. Hybrid STPE technology penetration from European competitors threatens silicone-polyurethane segment boundaries, demanding counter-investment in bio-based formulation R&D to preempt federal green procurement standards. For New Entrants and Emerging Players: CCMC evaluation fast-track partnerships with Quebec and Alberta provincial building code authorities unlock specification eligibility in compressed 12-18 month windows versus standard protocols. Alberta's aging petrochemical infrastructure presents the most penetrable white-space target for high-temperature silicone and polysulfide joint sealants. Direct technical sales to Calgary and Edmonton turnaround maintenance contractors bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Regional compounders with Health Canada PMRA pre-approved biocide formulations and established CCMC evaluation track records represent the priority acquisition archetype. Long-term viability hinges on low-embodied-carbon chemistry transitions ahead of federal infrastructure tender mandates. Watch Environment and Climate Change Canada's green procurement standard finalization as the inflection signal triggering portfolio revaluation toward bio-based and recycled-content specialists.| Strategic Initiative | Industry Significance |
|---|---|
| CSA A440.4 Certification Acceleration | Qualification cycles consolidate supplier pools around pre-certified compounders in federal tenders. |
| Backward Integration into Silicone Monomer Supply | Captive feedstock production insulates margins from trans-Pacific shipping volatility and currency fluctuation. |
| Hybrid STPE Technology Platform Development | STPE formulations decompose traditional silicone-polyurethane segment boundaries in Ontario curtain wall specifications. |
| CCMC Evaluation Partnership Expansion | Provincial building code adoption protocols in Quebec and Alberta compress commercial eligibility timelines. |
| Bio-based Formulation Portfolio Transition | Low-embodied-carbon chemistries align with impending federal green procurement standards for infrastructure tenders. |
Study Parameters
A spread of perspectives from building envelope consultants, specification-grade distributor principals, compounder R&D directors, and federal procurement officers converged on the working assumptions underlying demand segmentation. Primary interviews with Ontario and British Columbia envelope contractors, Alberta petrochemical maintenance planners, and Health Canada PMRA compliance specialists were cross-validated against secondary sources including Canadian Construction Materials Centre evaluation protocols, Environment and Climate Change Canada VOC regulatory filings, and provincial building code adoption schedules. Bottom-up volume builds from end-use application sizing were reconciled with top-down market value estimates across the analysis window.
Segmentation dimensions modeled include polymer chemistry family, end-use vertical, certification tier, and regional construction pipeline intensity. Demand projections incorporate housing permit flows in the Greater Toronto Area, Vancouver high-rise development pipelines, and Alberta industrial maintenance cycle timing throughout the forecast period. CAGRs were derived from elasticity-adjusted volume trajectories and value-per-unit trends by chemistry tier. Industry-specific forecast inputs capture CSA A440.4 certification adoption curves and PMRA biocide approval timelines.
Decision-makers should treat outputs as directional under sustained residential construction permit levels and federal infrastructure spending commitments; material deviation would warrant model refresh. Specific risk factors include silicone monomer supply disruption from Asian production concentration and accelerated VOC regulatory phase-down ahead of schedule. Revision becomes warranted when hybrid STPE technology adoption crosses threshold penetration in Ontario commercial envelope specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market