
 Asia-Pacific Reactive Adhesives Market | 2026-2036
Asia-Pacific Reactive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Reactive Adhesives Market Outlook
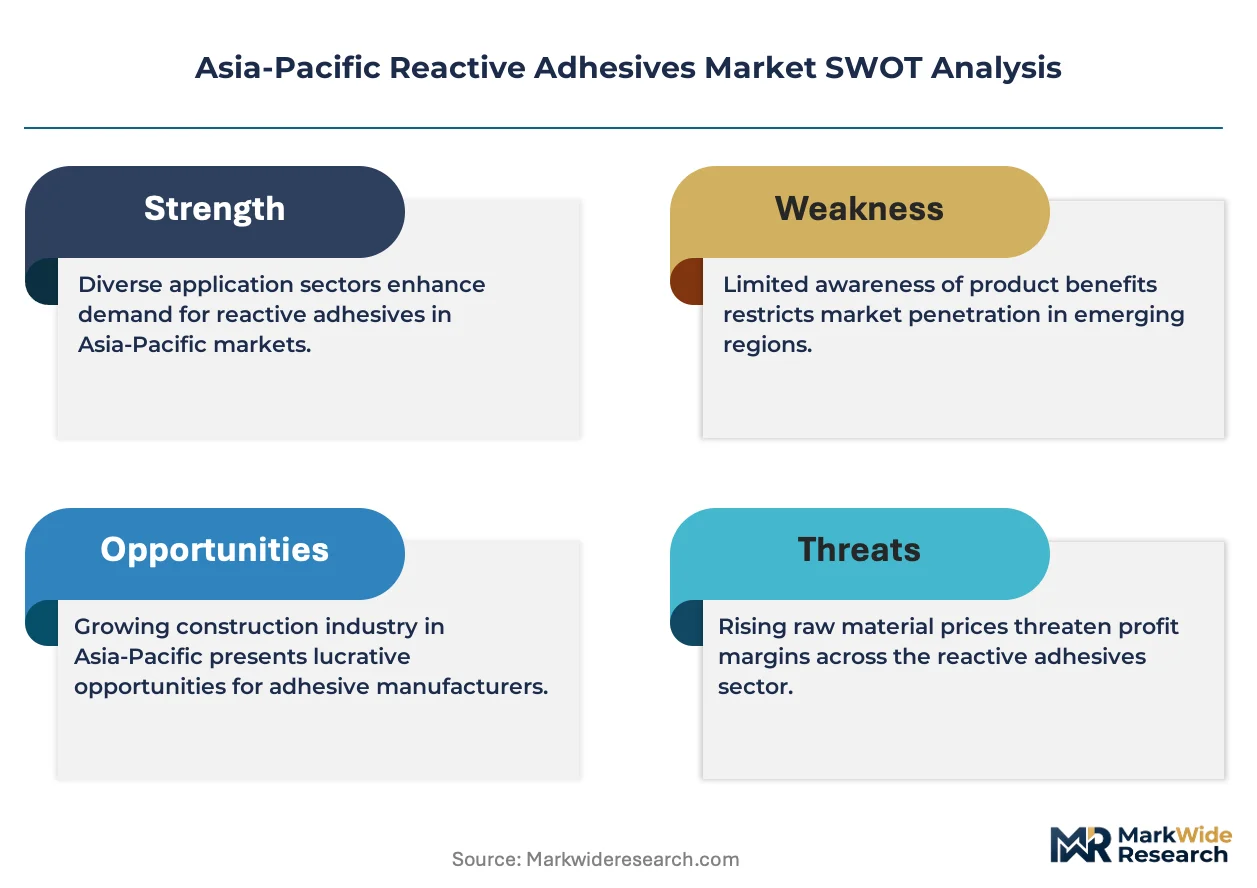
Asset-light leasing models for specialty chemical production equipment is tilting competitive dynamics toward regional formulators with lower capital barriers. Henkel AG & Co. KGaA leverages its R&D footprint in Shanghai to sustain technology leadership in automotive-grade polyurethanes. Sika AG anchors its position through backward integration into resin intermediates across Southeast Asian manufacturing hubs. Dow competes on manufacturing scale, operating bulk epoxy facilities that supply multiple application segments.
Reactive adhesives are thermosetting polymer systems that cure through chemical reaction rather than solvent evaporation, typically achieving structural bond strengths exceeding 10 MPa with temperature resistance from -40°C to 150°C depending on chemistry. These formulations serve primary industrial functions including load-bearing assembly, environmental sealing, and thermal management in bonded joints. Epoxy systems dominate margin pools in electronics and aerospace applications where dielectric properties and outgassing control command specification premiums. Polyurethane adhesives represent the fastest-growing chemistry in automotive lightweighting programs across the region. Water-based technology remains mature in packaging and textile segments where regulatory pressure on solvent emissions has accelerated formulation transitions.
China's MEE enforces GB standards limiting volatile organic compound content in industrial adhesives, directly reshaping product development priorities for domestic and imported formulations. Japan's METI coordinates JIS certification requirements that govern adhesive performance in automotive and electronics supply chains, creating differentiated market access conditions. South Korea's MFDS maintains material safety protocols affecting healthcare and consumer-facing applications. Stakeholders must monitor how divergent national standards evolve and whether harmonization initiatives emerge through regional trade frameworks.
Market Dynamics
China's MEE enforcement of GB standards for VOC emissions is compressing formulation timelines across the Asia-Pacific reactive adhesives supply chain, forcing rapid transitions from solvent-based to thermosetting chemistries.
Growth Catalysts
- Automotive Lightweighting Mandates:Thailand and Vietnam OEMs are expanding structural bonding operations for aluminum-intensive vehicle platforms, pulling polyurethane and epoxy consumption into final assembly.
- GB Standards Compliance Pressure:China's MEE regulations limiting volatile organic compound content in industrial adhesives are accelerating domestic formulator R&D investment in water-based and 100% solids systems.
- Electronics Manufacturing Clustering:Eastern China's contract manufacturers are specifying dielectric-grade epoxy systems for semiconductor packaging and display assembly, concentrating demand in the Yangtze River Delta.
Market Restraints
- Petrochemical Feedstock Volatility:Epoxy resin and isocyanate intermediate pricing tracks crude oil and benzene derivatives, compressing margin predictability for regional formulators without captive supply.
- Specialty Chemical Equipment Concentration:Asset-heavy reactor and dispersion technology suppliers concentrate in Japan and South Korea, creating capital access barriers for Southeast Asian entrants.
- Technical Performance Floors:Automotive and aerospace applications require JIS or GB-certified bond strengths exceeding 15 MPa with thermal cycling resistance, excluding commodity-grade formulations from specification pools.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Electronics and automotive FDI in Bac Ninh and Hai Phong industrial zones is outpacing local adhesive supply, creating white space for technical service partnerships.
- Dual Carbon Policy Alignment:China's national carbon neutrality targets are incentivizing low-cure-energy epoxy formulations and bio-based polyurethane feedstocks through provincial green manufacturing certification.
- Digital Formulation Platforms:AI-accelerated rheology modeling and predictive cure kinetics are compressing new product development cycles for custom automotive and electronics specifications.
Industry Challenges
- Formulation Chemist Scarcity:Southeast Asian technical universities produce limited graduates with polymer synthesis and adhesive rheology expertise, forcing Japanese and Korean multinationals to staff regional labs with expatriate talent.
- Multi-Standard Certification Burden:Suppliers serving China, Japan, and South Korea simultaneously must maintain parallel GB, JIS, and MFDS testing protocols, extending product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Reactive Adhesives Market |
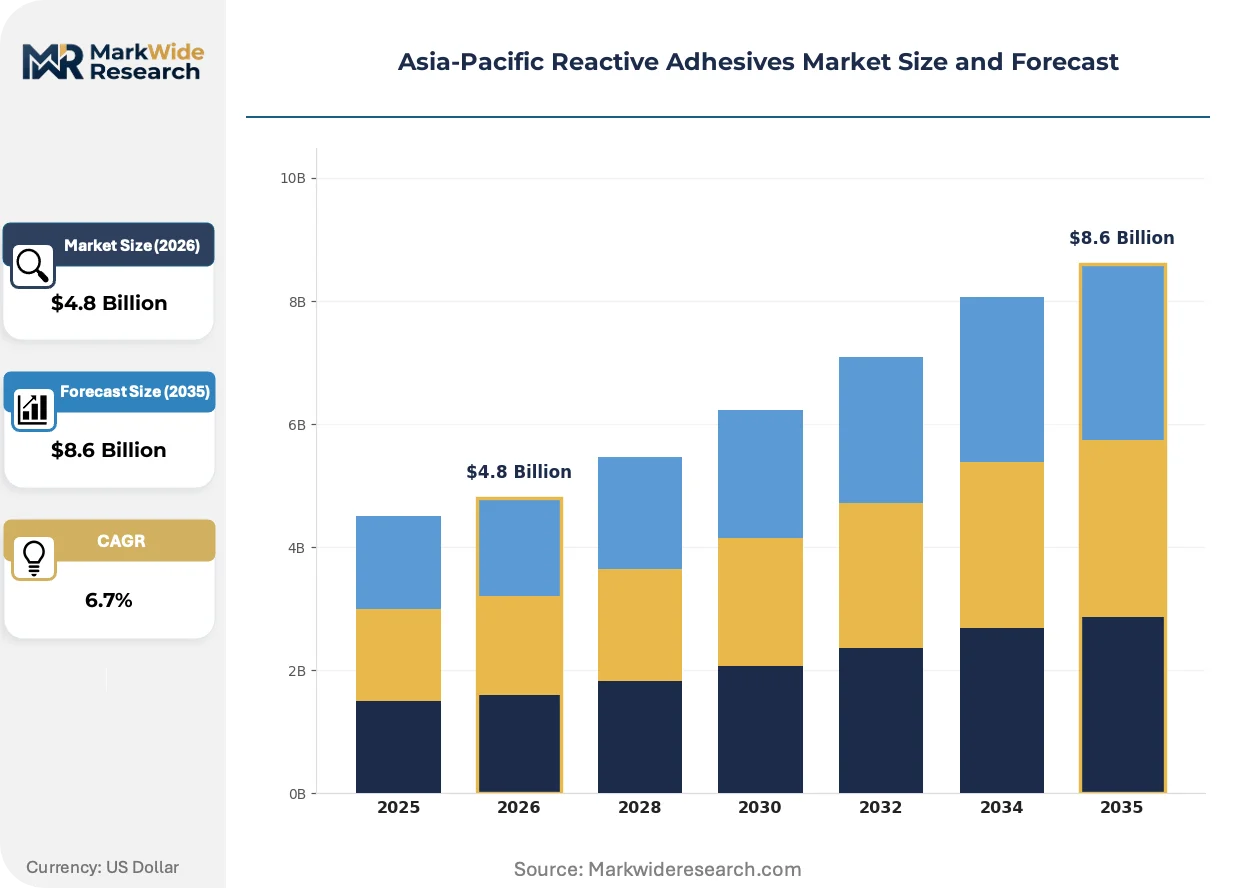
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Cyanoacrylate Application: Automotive, Construction, Electronics, Packaging End User: Aerospace, Manufacturing, Healthcare, Textile Technology: Water-Based, Solvent-Based, Hot Melt, UV-Cured |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, H B Fuller Company, Arkema Group, Dow, Huntsman International LLC, Avery Dennison Corporation, BASF SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Reactive Adhesives Market Strategic Shifts
Reactive adhesive technology is bifurcating between ultra-high-performance thermosets for structural applications and process-optimized systems for high-speed automated assembly, with regulatory chemistry constraints accelerating both tracks.
Two-component epoxy systems with sub-60-second snap-cure profiles are rendering obsolete conventional heat-cure formulations in electronics contract manufacturing. Foxconn and Luxshare facilities in Shenzhen and Kunshan are qualifying these systems for smartphone and tablet assembly lines. The technology is compressing work-in-process inventory requirements and enabling just-in-sequence bonding stations.
Japan's METI has tightened JIS K 6806 performance requirements for automotive structural adhesives, mandating crash-durable bond retention at elevated temperatures. Tier-1 suppliers serving Toyota and Honda are reformulating polyurethane systems to meet the revised shear and peel specifications. The regulation is diverting R&D investment toward hybrid epoxy-urethane chemistries with superior energy absorption.
Contract manufacturers are consolidating adhesive procurement under technical specification contracts rather than commodity spot purchasing. Electronics assemblers in eastern China now require suppliers to embed application engineering support and statistical process control data into supply agreements. The shift is most visible in display panel manufacturing, where BOE and CSOT facilities specify adhesive performance guarantees tied to yield rates.
Asia-Pacific Reactive Adhesives Market Segmentation
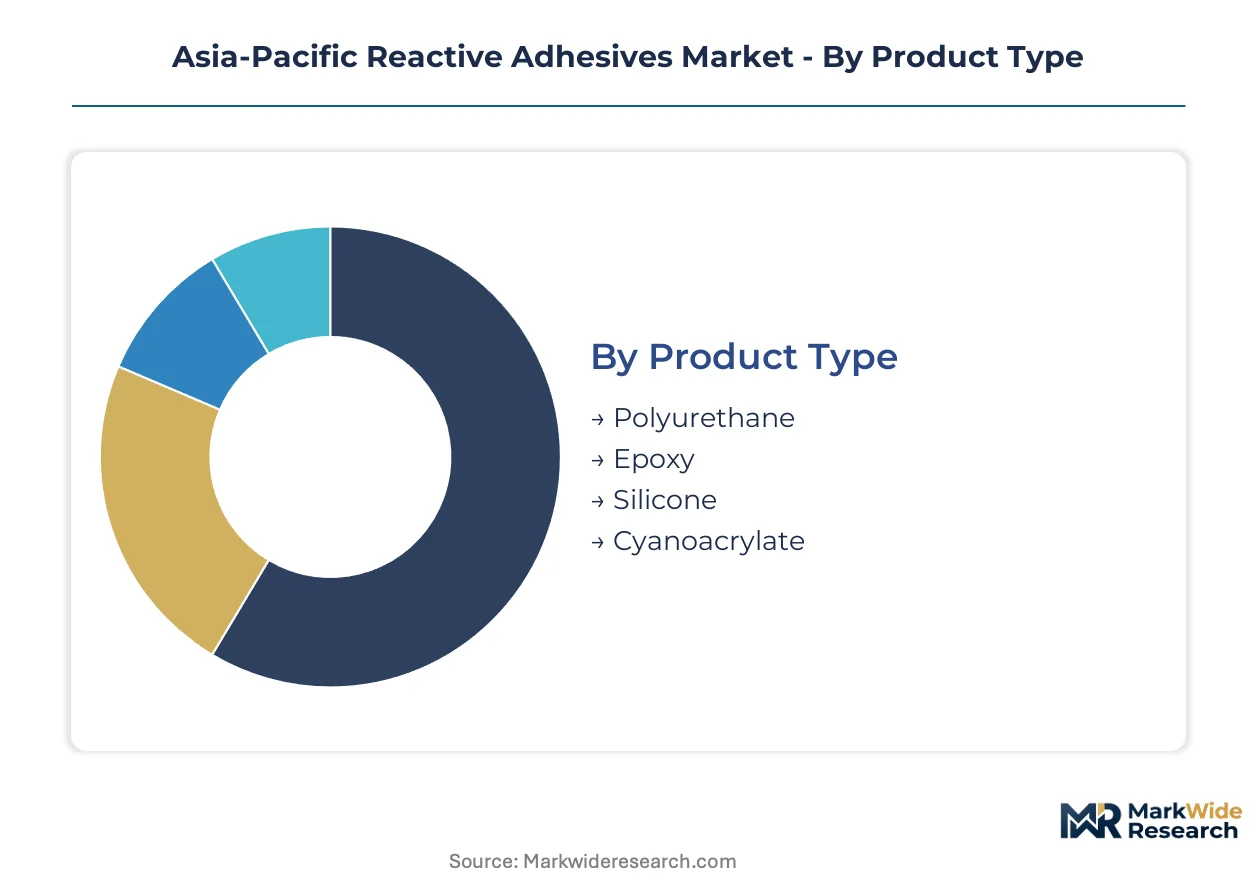
Reactive adhesives serve divergent performance requirements across the Asia-Pacific region, from structural crash-durable bonds in Thai automotive plants to dielectric encapsulation in eastern Chinese semiconductor packaging. Chemistry selection, cure mechanism, and certification grade create distinct competitive battlegrounds that resist simple commoditization.
Product Type:
Polyurethane and epoxy systems anchor the highest-value specification pools, while silicone and cyanoacrylate chemistries occupy specialized niches with distinct technical barriers to entry.
- Polyurethane:Two-component systems cure through isocyanate-hydroxyl reaction to form elastomeric bonds with superior impact resistance and substrate flexibility. Thai and Vietnamese OEMs specify these formulations for aluminum-intensive vehicle platforms where crash-durable adhesion is mandatory.
- Epoxy:Thermosetting polymers built from epoxide monomers deliver dielectric stability and outgassing control critical to semiconductor packaging. Eastern China's Yangtze River Delta contract manufacturers concentrate procurement of high-purity grades for display assembly and chip encapsulation.
- Silicone:Room-temperature-vulcanizing systems dominate thermal management applications requiring sustained performance across -50°C to 200°C operating windows.
- Cyanoacrylate:Instant-bonding monomeric adhesives serve high-speed electronics assembly where fixture times below 10 seconds justify premium positioning.
The dominant share belongs to epoxy systems, while polyurethane is closing the gap fastest on automotive lightweighting mandates.
Application:
End-use concentration tracks manufacturing FDI patterns, with electronics and automotive commanding formulation premiums that construction and packaging segments cannot match.
- Automotive:Structural bonding operations for mixed-material vehicle platforms require JIS K 6806-certified formulations with crash-durable retention at elevated temperatures. Japanese OEM supply chains enforce the strictest qualification protocols.
- Electronics:Dielectric-grade systems for semiconductor packaging and display assembly concentrate demand in Shenzhen, Kunshan, and Shanghai manufacturing clusters. Foxconn and Luxshare facilities specify sub-60-second snap-cure epoxies for smartphone assembly lines.
- Construction:Structural glazing and panel bonding applications favor moisture-cure polyurethanes with extended working times for field adjustment.
- Packaging:Water-based and hot-melt systems dominate food-contact applications where China's GB standards for VOC emissions have accelerated solvent-to-aqueous transitions.
Electronics applications capture the steepest margin premiums, with automotive expanding most quickly on Southeast Asian OEM investment.
End User:
Customer sophistication varies sharply across verticals, with aerospace and healthcare enforcing certification burdens that exclude commodity suppliers.
- Aerospace:Outgassing-controlled epoxy systems must meet stringent thermal cycling and flame-resistance specifications for interior and structural airframe bonding.
- Manufacturing:Broad industrial maintenance and assembly operations consume volume quantities of two-component polyurethane and epoxy systems with less stringent certification requirements.
- Healthcare:South Korea's MFDS maintains material safety protocols affecting medical device bonding applications, creating differentiated market access conditions.
- Textile:Lamination and seam-sealing operations favor hot-melt reactive polyurethanes with soft-hand finish characteristics.
Manufacturing commands the largest volume position, though aerospace specifications deliver unmatched pricing power per kilogram applied.
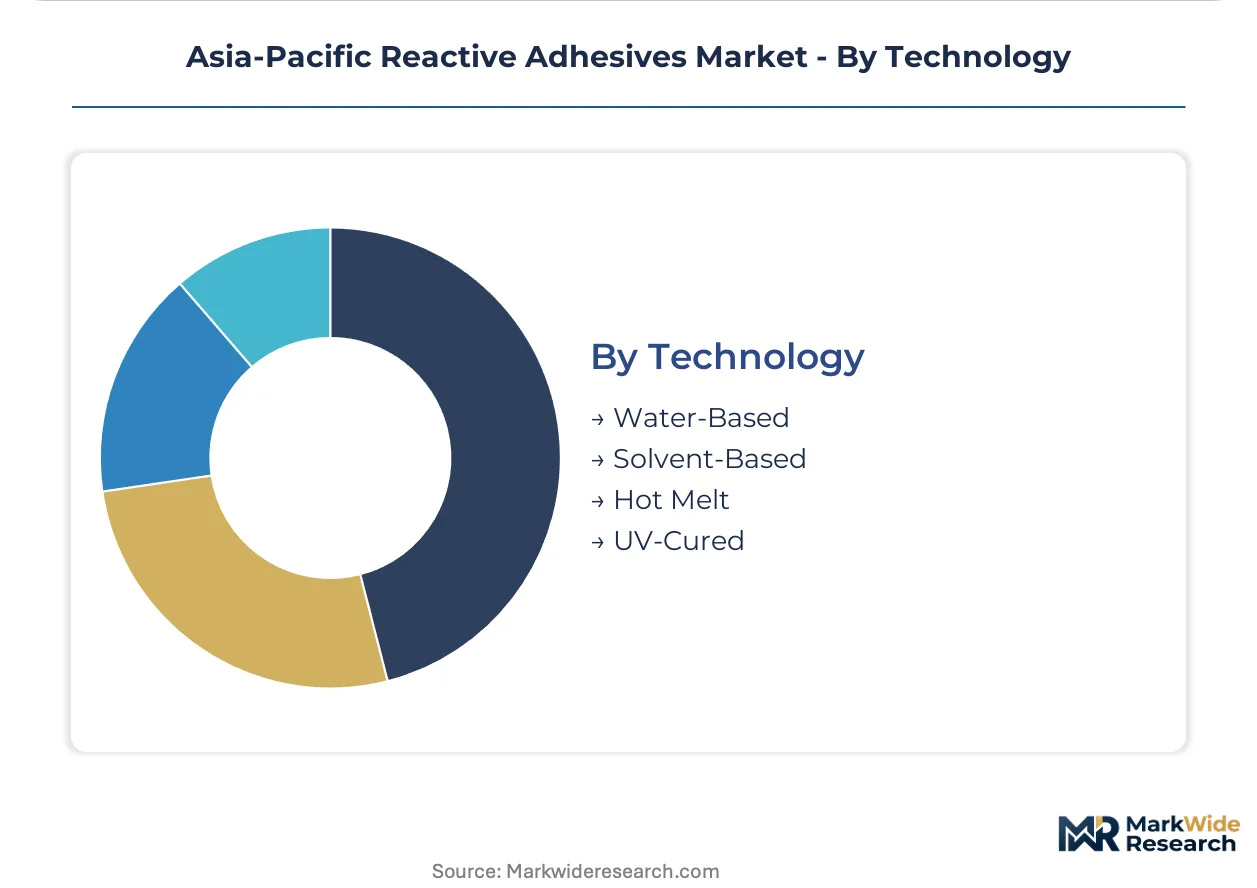
Technology:
Cure mechanism selection reflects regulatory pressure, capital intensity, and line-speed requirements in tension across regional manufacturing bases.
- Water-Based:Emulsion systems with latent crosslinkers serve packaging and textile segments where China's MEE VOC regulations have mandated solvent reduction. Curing requires elevated temperature and extended dwell time.
- Solvent-Based:Solution adhesives with reactive hardeners retain niche positions in aerospace and specialty industrial applications where performance floors override emissions concerns.
- Hot Melt:Reactive polyurethane hot melts combine application speed with thermosetting durability, gaining share in automated furniture and appliance assembly.
- UV-Cured:Photoinitiated acrylate and epoxy systems enable instantaneous processing for electronics display lamination where work-in-process inventory compression justifies equipment investment.
Water-based technology holds the broadest installed base, while UV-cured systems are gaining share fastest on electronics automation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy framework is redirecting capital toward low-cure-energy adhesive formulations across provincial manufacturing bases. Japanese METI certification requirements and South Korean MFDS protocols are creating parallel compliance tracks that fragment technical qualification pathways.
China
Eastern manufacturing clusters in Shenzhen and Kunshan are specifying sub-60-second snap-cure epoxies for smartphone assembly lines. MEE enforcement of GB standards for VOC emissions is compressing formulation timelines toward water-based and 100% solids systems. Yangtze River Delta contract manufacturers concentrate procurement of dielectric-grade systems for semiconductor packaging.
Japan
Automotive OEM supply chains are reformulating polyurethane systems to meet revised JIS K 6806 crash-durable bond retention requirements. METI coordinates certification protocols that govern adhesive performance in Toyota and Honda assembly operations. Tier-1 suppliers in Nagoya and Tokyo industrial corridors are diverting R&D investment toward hybrid epoxy-urethane chemistries.
South Korea
Display panel manufacturers including BOE and CSOT facilities specify adhesive performance guarantees tied to yield rates. MFDS maintains material safety protocols affecting medical device bonding applications. Seoul Capital Area electronics assemblers require suppliers to embed statistical process control data into technical specification contracts.
Thailand
OEMs are expanding structural bonding operations for aluminum-intensive vehicle platforms where crash-durable adhesion is mandatory. Board of Investment incentives for automotive FDI are pulling polyurethane and epoxy consumption into final assembly. Rayong and Chonburi industrial zones host expanding bonding operations for Japanese and Korean vehicle exports.
Vietnam
Electronics and automotive FDI in Bac Ninh and Hai Phong industrial zones is outpacing local adhesive supply. Provincial authorities are accelerating technical service partnerships to address formulation chemist scarcity. Samsung and Foxconn supplier parks are qualifying domestic formulators for secondary assembly applications.
Asia-Pacific Reactive Adhesives Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: multinational chemical conglomerates with captive resin production, regional formulators with asset-light leasing models, and specialized technology licensors. German and Swiss engineering-intensive players occupy premium specification pools. Japanese and Korean equipment suppliers concentrate reactor and dispersion technology. Competitive moves center on backward integration into resin intermediates and AI-accelerated formulation platforms.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Sika AG exemplify the engineering-intensive archetype with sustained technology leadership in automotive-grade systems. Dow occupies a position at the scale-driven end, operating bulk epoxy facilities that supply multiple application segments. These three anchors represent distinct competitive vectors: R&D footprint consolidation, backward integration into resin intermediates, and manufacturing scale economics.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| H B Fuller Company |
| Arkema Group |
| Dow |
| Huntsman International LLC |
| Avery Dennison Corporation |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in bulk epoxy production across eastern China is compressing spot prices for commodity-grade formulations while tightening supply for JIS-certified automotive systems. This utilization divergence rewards backward-integrated suppliers with captive resin capacity and squeezes asset-light regional formulators exposed to benzene derivative volatility.
Pricing Analysis
Certification level (JIS K 6806/GB standards-grade) creates the primary spread between premium structural adhesives and commodity industrial formulations. Three-tier pricing structure across JIS-certified, GB-compliant, and uncertified product tiers reflects qualification burden and technical service bundling. Cost compression in electronics-grade epoxies is intensifying because Foxconn and Luxshare procurement teams are consolidating suppliers under yield-guarantee contracts. Packaging and textile segments exhibit highest price sensitivity due to water-based technology commoditization, while aerospace and semiconductor packaging buyers prioritize dielectric performance over unit cost.
Supply Chain Analysis
Benzene and propylene feedstock pricing in South Korea and Japan anchors raw material cost structures for isocyanate and epoxy resin intermediates. Regional formulators draw from petrochemical complexes in Ulsan, Yokkaichi, and Singapore Jurong Island for specialty chemical inputs. Single-source vulnerability concentrates in Japanese and Korean reactor technology suppliers, creating capital access barriers for Southeast Asian entrants. Distribution runs through technical service partnerships with electronics contract manufacturers and Tier-1 automotive suppliers rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital formulation platforms are transforming reactive adhesives into data-embedded specification products, where AI-accelerated rheology modeling creates ecosystem lock-in through integrated application engineering.
For Market Incumbents: Pre-empt asset-light regional competitors by embedding statistical process control data into long-term technical specification contracts with BOE and CSOT. Accelerate backward integration into bio-based polyurethane feedstocks to align with China's Dual Carbon Policy provincial certification requirements. Defensive consolidation around AI-driven cure kinetics capabilities will raise barriers against emerging digital-native formulators. For New Entrants and Emerging Players: Pursue technical service partnerships in Vietnam's Bac Ninh and Hai Phong industrial zones where Samsung and Foxconn supplier parks are qualifying domestic formulators for secondary assembly. Electronics contract manufacturing in Vietnam represents the most penetrable geography due to formulation chemist scarcity forcing Japanese multinationals to staff with expatriate talent. A go-to-market angle anchored in localized application engineering support can bypass capital-heavy reactor requirements through equipment leasing models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light formulation platforms utilizing leased dispersion technology and AI-accelerated product development. Long-term viability favors targets with embedded technical service relationships in automotive or electronics supply chains rather than commodity-grade volume players. The signal to watch is consolidation of adhesive procurement under yield-rate guarantee contracts, indicating specification power shifting toward downstream assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Sika AG's captive supply of polyurethane intermediates insulates margin from benzene derivative volatility. |
| AI-Accelerated Formulation Platforms | Predictive cure kinetics compress development cycles for custom JIS K 6806 automotive specifications. |
| Technical Service Partnership Expansion | Localized application engineering in Vietnam addresses formulation chemist scarcity for Samsung supplier parks. |
| Bio-Based Feedstock Transition | Provincial green manufacturing certification in China rewards low-carbon polyurethane systems with procurement preference. |
| Yield-Rate Guarantee Contracts | BOE and CSOT facilities now embed adhesive performance guarantees tied to display panel production yields. |
Study Parameters
Operator-level perspectives from adhesive R&D directors, Tier-1 automotive procurement managers, electronics contract manufacturing engineers, and specialty chemical distribution channel heads anchored the qualitative base. Primary interview insights combined with secondary validation from customs/trade data, SEC 10-K filings of listed chemical conglomerates, MEE GB standards documentation, and JIS certification registries. Bottom-up volume modeling across chemistry types and end-use segments triangulated against top-down market sizing from regional production cluster analysis.
Scenario-bracketing around regulatory enforcement intensity and automotive FDI momentum shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry type, cure mechanism technology, certification grade tier, end-use industry concentration, and regional manufacturing hub. CAGRs derived from elasticity-adjusted volume projections incorporating feedstock price scenarios and substitution dynamics between solvent-based and thermosetting systems.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, yuan-dollar exchange rates, or automotive export demand would shift the trajectory. Forecasts reflect documented assumptions regarding MEE enforcement consistency and JIS revision implementation timelines. Cross-checking against IHS Markit vehicle production databases and regional electronics contract manufacturing capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
High Temperature Sealants Market