
 Space on Board Computing Platform Market | 2026-2036
Space on Board Computing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Space on Board Computing Platform Market Intelligence
The end-user mix for space computing is pivoting from a dominant reliance on government aerospace agencies toward a more balanced model incorporating private space companies. Lockheed Martin Corporation leverages its long-standing relationships with defense and civil space programs for large-scale contracts. BAE Systems specializes in radiation-hardened electronics critical for mission longevity in harsh environments. Honeywell International Inc. competes with a broad portfolio of integrated avionics and control systems for various space platforms.
A space on board computing platform is the integrated hardware and software system responsible for data processing, command execution, and control functions on a spacecraft. These systems must be radiation-hardened to withstand the space environment and operate reliably under extreme thermal cycles. Their primary purpose is enabling autonomous operations, payload management, and communications for satellites, launch vehicles, and robotic explorers. The adoption of FPGA technology is reshaping the market due to its post-launch reconfigurability, while demand for high-performance computing is rising for data-intensive Earth observation missions.
Regulatory frameworks profoundly influence system design and market access. In the United States, export controls like the International Traffic in Arms Regulations (ITAR) govern the sale and transfer of sensitive space computing technology. Concurrently, standards from bodies like the ISO promote interoperability and reliability across international space programs. Vendor success will depend on navigating these complex export control regimes while developing modular, scalable computing architectures for diverse mission profiles.
Market Dynamics
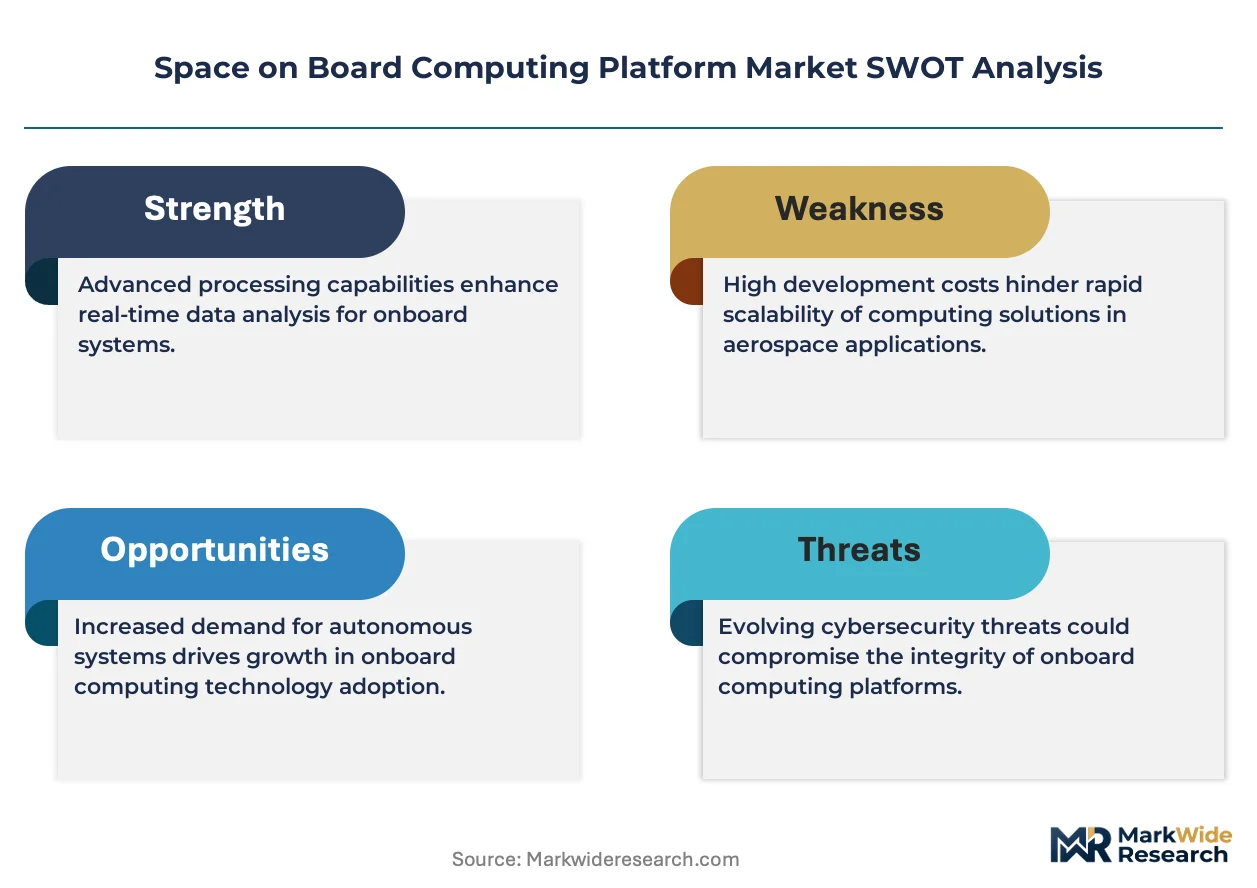
The defining tension in the space computing market is the conflict between the demand for cost-effective, commercial off-the-shelf (COTS) components, driven by large satellite constellations, and the stringent reliability requirements that have traditionally mandated expensive, radiation-hardened electronics.
Growth Catalysts
- Large Constellation Deployment:The rapid build-out of large low Earth orbit (LEO) satellite constellations for global broadband internet and continuous Earth observation services creates sustained, high-volume demand for standardized on-board computing platforms.
- Reconfigurable FPGA Technology:The shift toward Field-Programmable Gate Arrays allows for post-launch software updates and hardware reconfiguration, enabling satellite operators to adapt to new mission requirements, correct flaws, and extend the operational life of assets in orbit.
- Government Space Privatization:National policies, such as initiatives managed by IN-SPACe in India, are actively encouraging private sector participation in space activities, opening new domestic markets and fostering a competitive ecosystem for platform suppliers.
Market Restraints
- Export Control Regimes:Stringent regulations like the United States' International Traffic in Arms Regulations (ITAR) restrict the transfer of sensitive computing technology, complicating international partnerships and limiting the addressable market for certain vendors.
- Radiation Hardening Process:The lengthy and costly qualification and testing cycle for radiation-hardened and radiation-tolerant electronic components creates significant barriers to entry and slows the adoption of newer, more powerful processing architectures.
- High Development Costs:The non-recurring engineering costs associated with designing, verifying, and validating a new space computing platform are substantial, making it difficult for new entrants to compete with established players on large government programs.
Strategic Opportunities
- On-Orbit Servicing and Manufacturing:Emerging applications like satellite refueling, repair, and in-space assembly require sophisticated autonomous computing for robotics, rendezvous, and docking maneuvers, creating a new market for high-performance edge processors.
- AI and Machine Learning at the Edge:Integrating dedicated AI/ML accelerators into computing platforms allows for real-time, on-board data processing and analysis, reducing the immense data downlink burden for Earth observation and signals intelligence missions.
- Emerging National Space Programs:Nations in the Middle East and Southeast Asia are investing in sovereign space capabilities, presenting opportunities for platform vendors to establish partnerships and supply computing systems for new satellite and exploration missions.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers possessing the rare combination of expertise in radiation effects on electronics, real-time embedded systems, and modern fault-tolerant software design constrains development capacity across the industry.
- Supply Chain Bottlenecks:The global supply of space-grade components relies on a very small number of specialized foundries and suppliers, creating vulnerability to geopolitical disruptions, long lead times, and limited production capacity.
- Lack of Interoperability Standards:The slow and fragmented adoption of open architecture standards like SpaceVPX hinders the development of a truly modular, plug-and-play ecosystem, increasing integration complexity and costs for satellite prime contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space on Board Computing Platform Market |
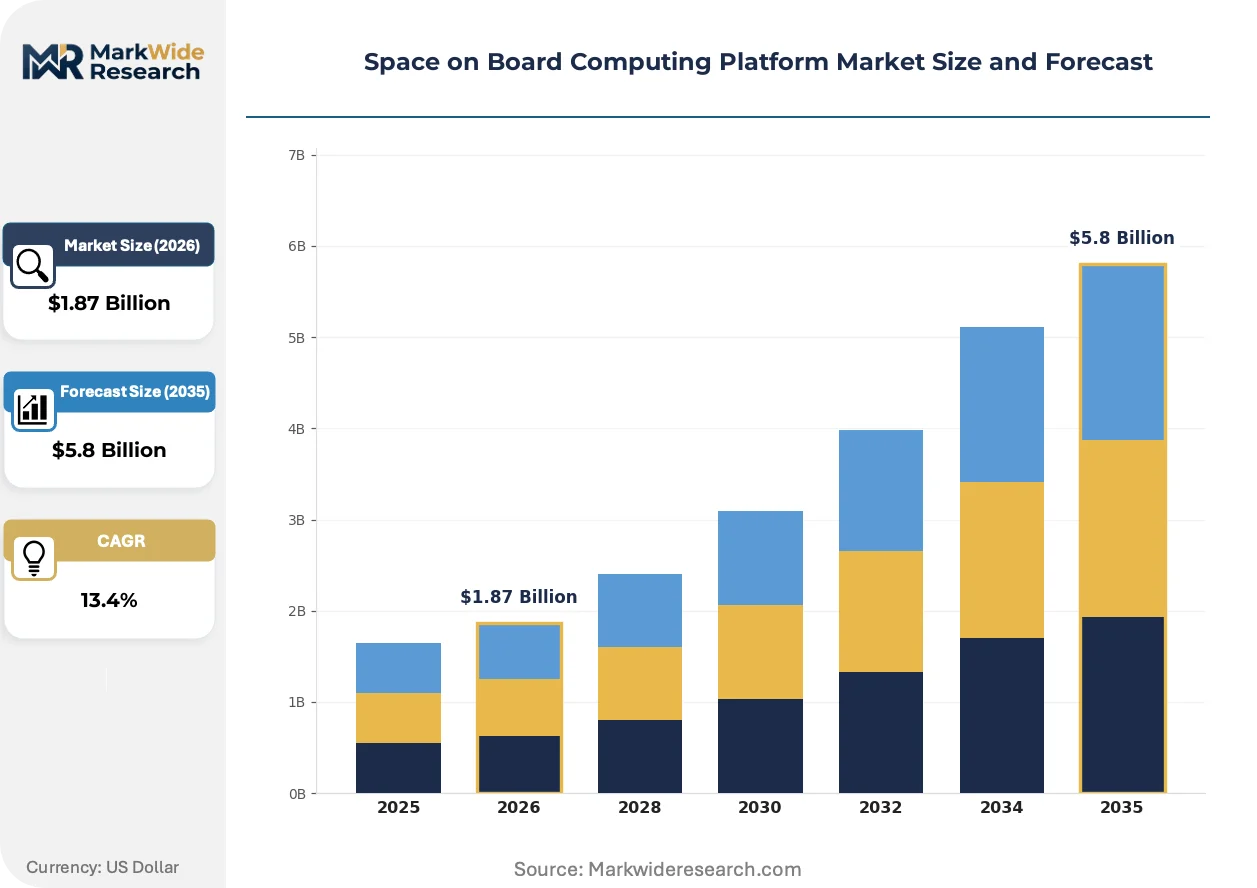
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $5.8 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Server, Processor, Memory Module, Storage Device Application: Satellite Operations, Launch Vehicles, Space Robotics, Ground Control End User: Aerospace Agencies, Private Space Companies, Defense Contractors, Research Institutions Technology: Embedded Systems, FPGA, High-Performance Computing, Real-Time Processing |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman, BAE Systems, Honeywell International Inc., RTX, Airbus, Thales Alenia Space, L3Harris Technologies, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space on Board Computing Platform Market Strategic Shifts & Innovations
A fundamental shift is underway from bespoke, single-mission computers toward scalable, software-defined architectures. This evolution allows a common hardware platform to be adapted for diverse mission profiles, from small satellites to deep space probes, primarily through software reconfiguration.
System-on-Chip (SoC) devices are a key enabling technology, integrating processors, memory, and peripherals onto a single silicon die. Satellite manufacturers are rapidly adopting these solutions to reduce the size, weight, power, and cost (SWaP-C) of their avionics. This integration trend is absorbing functions previously performed by multiple discrete components on a circuit board, simplifying spacecraft design and enhancing reliability.
International standards from bodies like the ISO, specifically through its technical committee on space systems (ISO/TC 20), are promoting greater system interoperability. These frameworks simplify multinational cooperation by establishing common protocols for communication, data handling, and component interfaces. The launch vehicle and large satellite segments are most impacted, as their complex supply chains often span multiple countries and require seamless integration.
Customer acquisition models are evolving toward the purchase of on-orbit data and services rather than the direct procurement of an entire spacecraft. This "space-as-a-service" approach favors platform providers who can deliver flexible and scalable computing resources that can be shared or leased. This pattern is particularly evident in the commercial Earth observation and IoT/M2M communication sectors concentrated in North America and Europe.
Space on Board Computing Platform Market Segmentation
Space on-board computing platforms require distinct solutions tailored to specific operational demands. Market segmentation illuminates the diverse requirements shaping hardware and software development across various mission profiles. Understanding these categories reveals where innovation concentrates and where established technologies maintain dominance. This granular view guides strategic investment.
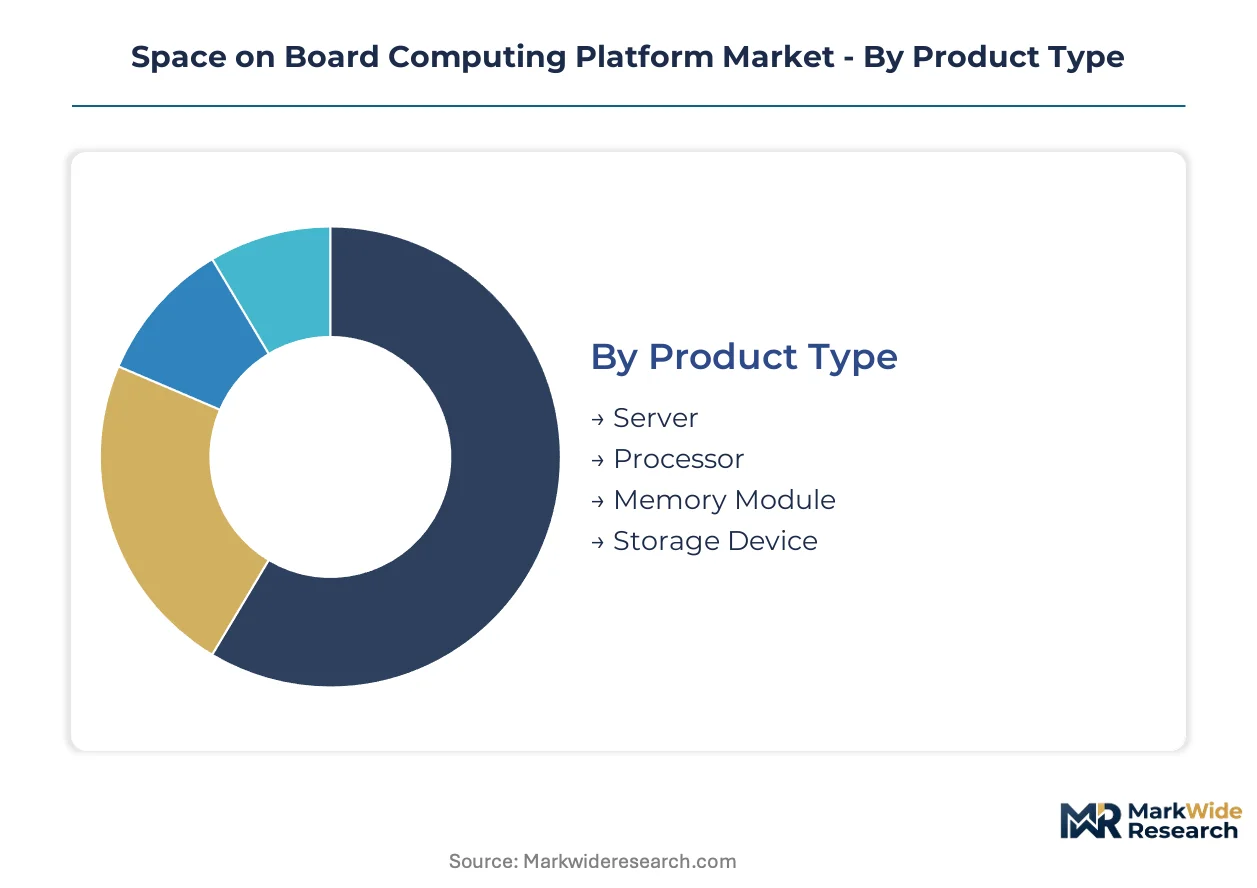
Product Type:
The product type segmentation for space computing platforms highlights the ongoing tension between highly customized components and increasingly standardized modules.
- Processor:These integrated circuits execute instructions and perform computations, forming the central brain of any space system. Demand concentrates in satellite operations, driven by the need for enhanced data processing capabilities for complex Earth observation and communication tasks.
- Server:Servers provide robust, centralized computing power for larger spacecraft, often managing multiple payloads and extensive data streams. Their demand is increasing within large constellation deployments, enabling advanced on-orbit data analytics and resource management.
- Memory Module:These components store program instructions and data, crucial for real-time operations and mission autonomy.
- Storage Device:Non-volatile storage devices retain mission-critical data and telemetry, essential for post-mission analysis and fault recovery.
Most installed capacity flows through Processor units. Expansion is steepest in Server configurations.
Application:
Application-specific requirements dictate the computational architecture and reliability standards for space computing platforms.
- Satellite Operations:This segment covers computing for data handling, attitude control, and communication within orbiting spacecraft, often requiring radiation-hardened designs. Demand is concentrated in LEO constellations in the United States, supporting global broadband and Earth observation services.
- Space Robotics:Computing platforms for robotic explorers and on-orbit servicing demand high-performance edge processing for autonomous navigation and manipulation. This segment sees demand for advanced AI/ML capabilities for complex rendezvous and docking maneuvers.
- Launch Vehicles:On-board computers manage guidance, navigation, and control during ascent, ensuring precise orbital insertion.
- Ground Control:These systems process telemetry, issue commands, and manage mission operations from terrestrial facilities.
The largest volume of deployed computing resources supports Satellite Operations. Emerging growth is prominent in Space Robotics, driven by on-orbit servicing.
End User:
The end-user segmentation reflects varied procurement models and mission objectives across the space computing market.
- Aerospace Agencies:These government entities, such as NASA and ESA, procure highly customized, ultra-reliable computing platforms for scientific missions and exploration. Their demand emphasizes radiation hardening and long-term mission assurance for deep space probes.
- Private Space Companies:This segment includes commercial satellite operators and launch service providers, seeking cost-effective, scalable computing solutions for large constellations. Demand from these companies in the United States drives the adoption of COTS components and agile development.
- Defense Contractors:These firms integrate computing platforms into military satellites and surveillance systems, prioritizing secure and resilient operations.
- Research Institutions:Universities and laboratories utilize space computing for experimental payloads and scientific data collection.
Traditional purchasing power resides with Aerospace Agencies. However, Private Space Companies are rapidly expanding their share of procurement.
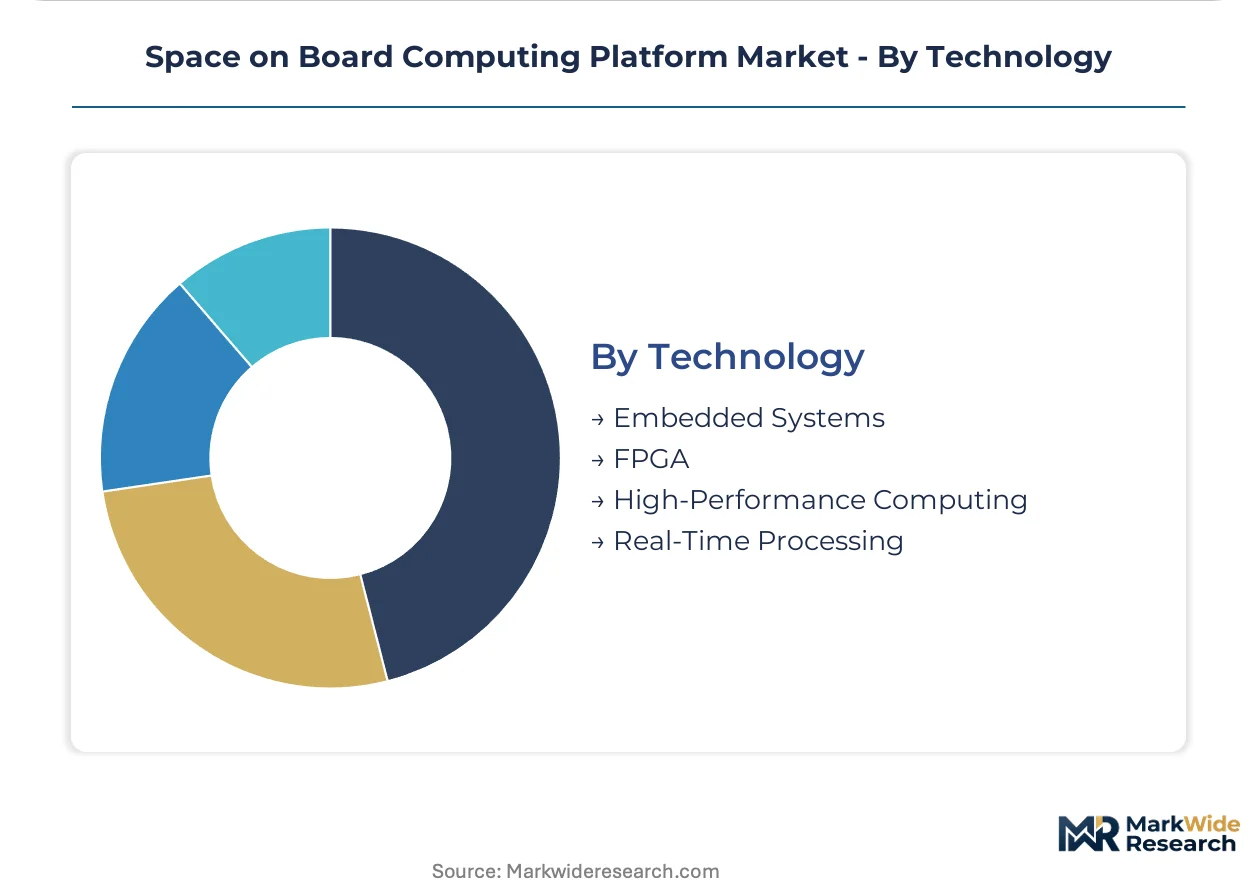
Technology:
Technological advancements and integration levels define the capabilities and flexibility offered by space on-board computing platforms.
- FPGA:Field-Programmable Gate Arrays offer post-launch reconfigurability, allowing operators to update hardware functions and adapt to evolving mission needs. This technology is critical for LEO constellations, enabling extended satellite lifespan and mission flexibility.
- High-Performance Computing:HPC solutions provide immense processing power for data-intensive applications like Earth observation and scientific modeling. Demand for HPC is accelerating as AI/ML integration becomes crucial for on-board data analysis.
- Embedded Systems:These dedicated systems provide specialized control and data acquisition functions for specific spacecraft subsystems.
- Real-Time Processing:Critical for immediate decision-making in autonomous operations and attitude control, ensuring rapid response times.
The foundation of most systems remains Embedded Systems. However, FPGA technology is gaining significant traction due to its adaptability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Space computing platform production sometimes shifts due to varying regulatory compliance costs among nations. Stringent export controls in some regions push manufacturers to establish facilities in areas with more favorable trade policies. This arbitrage strategy balances the need for high-reliability components with broader market access considerations for suppliers.
United States
Demand is driven by large constellation deployments and a dynamic private space sector. The International Traffic in Arms Regulations (ITAR) strictly controls the transfer of sensitive space computing technology. Silicon Valley and aerospace hubs in California foster innovation, concentrating high-performance computing development for complex satellite operations.
France
European Space Agency (ESA) programs and national defense contracts sustain significant demand for advanced platforms. French national space policy, aligned with broader European directives, promotes domestic industrial capabilities and technological sovereignty. Toulouse serves as a major European aerospace center, concentrating satellite manufacturing and advanced computing development.
India
The Indian Space Research Organisation (ISRO) missions and a rapidly expanding private sector propel demand. IN-SPACe initiatives actively encourage private sector investment in domestic space technology development and manufacturing. Bengaluru's vibrant tech ecosystem supports the growth of specialized electronics for satellite applications, including on-board processors.
Japan
Demand focuses on scientific exploration and advanced Earth observation missions, requiring ultra-high reliability systems. The Japan Aerospace Exploration Agency (JAXA) sets stringent reliability and qualification standards for all space-grade components. Tokyo and surrounding prefectures host key aerospace manufacturers developing advanced on-board computing for diverse spacecraft.
Germany
European defense projects and commercial satellite communication requirements support demand for robust computing. German space policy emphasizes technological independence and strict adherence to European Union export controls. Munich's aerospace sector contributes significantly to advanced avionics and mission-critical computing solutions for various space platforms.
Space on Board Computing Platform Market Key Industry Players
Strategic partnerships dominate the current landscape, driven by the need to combine specialized expertise for complex space missions and accelerate development cycles. The market structure exhibits a tiered consolidation, with established aerospace primes coexisting with agile new space startups. Archetypes include traditional defense contractors, specialized radiation-hardened electronics suppliers, and integrated avionics systems providers. Portfolio diversification into new application areas and technology licensing agreements are common competitive moves to expand market reach.
Within the defense and aerospace prime archetype, Lockheed Martin Corporation exemplifies companies leveraging long-standing government relationships for large-scale contracts. BAE Systems occupies a position among specialists providing radiation-hardened electronics, critical for mission longevity in harsh space environments. Honeywell International Inc. sits within the integrated systems providers, offering broad portfolios of avionics and control systems for various space platforms. These entities collectively anchor the market's high-reliability segment, influencing technology roadmaps and supply chain resilience. Their presence underscores the importance of established trust and extensive qualification processes in securing major program wins.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman |
| BAE Systems |
| Honeywell International Inc. |
| RTX |
| Airbus |
| Thales Alenia Space |
| L3Harris Technologies |
| Boeing |
| Others |
Cost & Logistics Intelligence
Private space companies’ demand for cost-effective computing platforms drives a pricing model balancing COTS affordability with mission-critical reliability. This dynamic influences component selection and system integration strategies across the industry.
Pricing Analysis
Distributor margins are compressed as large satellite operators increasingly procure directly from component manufacturers for volume discounts. Project-based pricing dominates for highly customized, radiation-hardened solutions supplied to aerospace agencies. Price differentiation stems from radiation hardening levels and post-launch reconfigurability features. Pricing softness reflects the push for commercial off-the-shelf components, particularly from LEO constellation developers. Private space companies exhibit the highest price sensitivity, while defense contractors prioritize mission assurance over cost.
Supply Chain Analysis
Regional distribution centers for space-grade components are limited, concentrating supply in specialized foundries primarily in the United States and Japan. Raw material dependencies include high-purity silicon and specialized rare earth elements for radiation shielding. Single-source vulnerability for radiation-hardened microprocessors presents a significant supply chain risk. Direct-to-OEM distribution models dominate for critical components, with integrators managing complex sub-component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a stable compounder, driven by the sustained build-out of large satellite constellations for global communication and Earth observation. Continuous investment in space infrastructure underpins steady, long-term growth.
For Market Incumbents: Extend existing relationships with government aerospace agencies by offering modular, scalable computing architectures tailored for diverse mission profiles. Diversify into on-orbit servicing applications, which require high-performance edge processors for autonomous robotics. This moves against the threat of new entrants offering cheaper, less qualified COTS solutions. Invest in advanced radiation hardening techniques to maintain a competitive edge.
For New Entrants and Emerging Players: A price-point gap exists between highly customized, expensive platforms and basic commercial off-the-shelf offerings, creating an entry opportunity. Target the rapidly expanding LEO constellation segment with cost-effective, reconfigurable FPGA-based solutions. Focus on providing software-defined architectures that enable post-launch updates and mission flexibility. A go-to-market angle emphasizing rapid prototyping and agile development can attract private space companies.
For Investors and Strategic Acquirers: Defense contractors are the most active acquirers in this space, seeking to integrate specialized radiation-hardened electronics and AI/ML capabilities. The long-term viability for space computing platforms remains strong over the next decade, fueled by increasing satellite deployments and deep space exploration. Target specialized firms with proven expertise in radiation-hardened System-on-Chip (SoC) development. The signal to watch is the successful on-orbit validation of new commercial off-the-shelf (COTS) components in demanding mission profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Modular Computing Architectures | This allows common hardware to serve diverse mission profiles, reducing development costs for satellite primes. |
| Invest in Radiation-Hardened SoC Technology | Integrating processors and memory on a single chip enhances reliability and reduces SWaP-C for demanding missions. |
| Expand FPGA-based Product Portfolio | Reconfigurable FPGAs enable post-launch updates, extending satellite operational life and mission flexibility. |
| Form Partnerships for AI/ML Integration | Collaborations accelerate on-board data processing capabilities, reducing downlink burdens for Earth observation. |
| Target Emerging National Space Programs | Supplying new satellite and exploration missions in regions like the Middle East presents significant growth avenues. |
Research Approach
Bottom-up satellite operations modeling reconciled against top-down component supplier tracking forms the analytical core for this study. Primary interviews with space computing architects, mission systems engineers, aerospace procurement leads, and regulatory affairs specialists provided qualitative insights. Secondary validation included analysis of aerospace agency reports, satellite operator financial filings, and technical specifications from component manufacturers. This triangulation ensures robust data integrity.
Historical trendline analysis of satellite deployments and technology adoption patterns informed the quantitative projections across the analysis window. Segmentation dimensions modeled include product type, application, end-user, technology, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from market size evolution and anticipated technological shifts. Key forecast inputs included planned constellation launches and advancements in radiation-hardened component efficiency.
Caveats apply where geopolitical disruptions, unexpected regulatory changes, or rapid technological breakthroughs could materially shift the outlook for space computing platforms. Forecasts reflect assumptions documented regarding component availability and mission funding over the projection horizon. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Carrier Rocket Market
Space
Asia-Pacific Space Electronics Market
Space
Space Transportation Market
Space
Space Robotics Market
Space
China Space Electronics Market
Space
Space Designing Market
Space
Germany Space Electronics Market
Space
Orbital Spaceflight Market
Space
Space Management Solutions Market
Space
North America Spacesuit Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Service Market
Space
Space Wheel Market
Space
LAMEA Space As a Service Market
Space
France Space Electronics Market
Space
Suborbital Space Tourism Market