
 Electrically Powered Spacecraft Propulsion Market | 2026-2036
Electrically Powered Spacecraft Propulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Electrically Powered Spacecraft Propulsion Market Insights
Multi-source procurement of thruster subsystems is expanding across prime satellite manufacturers. Safran SA leverages its PPS-5000 Hall effect thruster line to anchor European geostationary satellite programs. Northrop Grumman competes through in-house production of the GEOStar bus with integrated electric propulsion. Busek Co. Inc. specializes in gridded ion thrusters for NASA science missions, sustaining a niche but defensible position.
Electrically powered spacecraft propulsion encompasses electrostatic, electromagnetic, and electrothermal devices that accelerate ionized propellant—typically xenon or krypton—through electric fields to generate thrust in the millinewton range, enabling specific impulses exceeding 3000 seconds. Hall effect thrusters dominate commercial satellite stationkeeping applications due to their thrust-to-power ratio and flight heritage spanning thousands of cumulative operating hours. Ion thrusters lead deep space missions where maximum specific impulse drives mission feasibility, while electrospray thrusters occupy emerging demand from CubeSat constellations requiring miniature precision actuators. Power source segmentation shows solar-electric architectures capturing the majority of near-Earth applications, with radioisotope thermoelectric generators reserved for outer-planet missions beyond practical solar range.
FAA Office of Commercial Space Transportation licensing requirements shape U.S. launch integration protocols for electric propulsion payloads, while ESA cleanliness standards under ECSS-E-ST-35-06C dictate qualification testing for European suppliers. NASA's Technology Readiness Level gatekeeping for Science Mission Directorate selections filters market access for novel thruster architectures. Stakeholders must monitor how emerging on-orbit servicing demand reshapes propulsion duty-cycle specifications and qualification burdens.
Market Dynamics
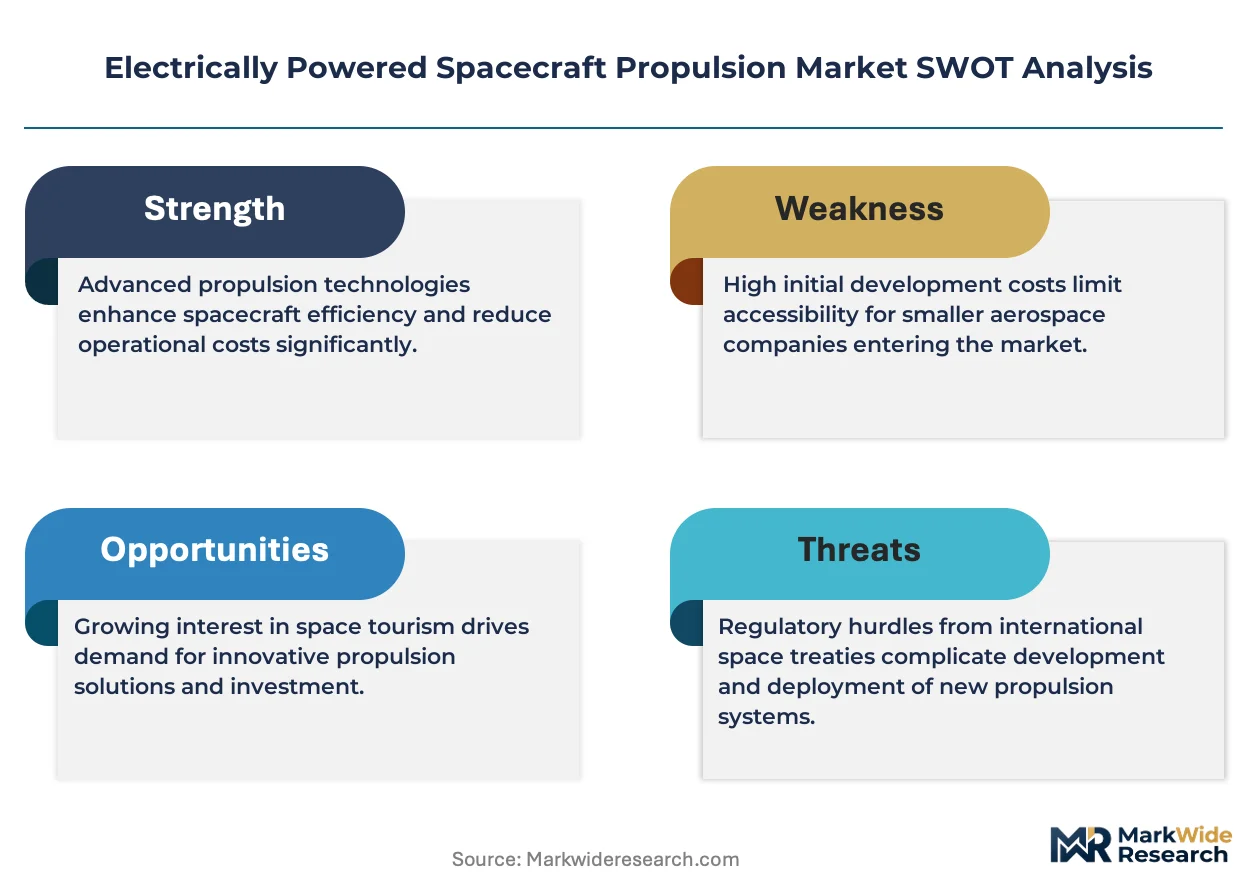
Procurement mandates from NASA and ESA for green propulsion alternatives are compressing qualification timelines and forcing satellite prime contractors to dual-source electric thruster subsystems. This regulatory pull is restructuring supplier relationships across the value chain.
Growth Catalysts
- Space Force launch contracts:The United States Space Force's sustained procurement of national security satellites channels capital toward domestic Hall effect thruster manufacturers, creating captive demand pools.
- SDA constellation architecture:The Space Development Agency's proliferated low-Earth orbit satellite mandates require miniature electric propulsion for precision stationkeeping, opening volume manufacturing pathways.
- REACH propellant restrictions:European chemicals regulation is accelerating qualification of krypton and iodine alternatives to xenon, diversifying supply chains for electrostatic thrusters.
Market Restraints
- Xenon supply concentration:Rare gas extraction concentrates in Russia and Ukraine, creating input cost volatility and geopolitical supply risk for gridded ion thruster operators.
- TRL gatekeeping:NASA's Technology Readiness Level requirements filter novel thruster architectures from Science Mission Directorate selections, extending development-to-revenue cycles.
- Chemical propulsion heritage:Established satellite platforms with hydrazine-based systems resist electric propulsion retrofit due to integration complexity and mission-risk aversion.
Strategic Opportunities
- On-orbit servicing demand:Emerging satellite life-extension missions reshape duty-cycle specifications, requiring electric thrusters optimized for frequent restart and precision maneuvering.
- CubeSat constellation proliferation:Miniaturized electrospray and pulsed plasma thrusters address precision actuation needs for 3U-12U spacecraft in commercial remote sensing.
- EU Green Deal procurement:European public satellite programs now mandate propulsion systems eliminating hydrazine, creating regulatory tailwinds for electric alternatives.
Industry Challenges
- Plasma physics specialization:The talent pool for Hall effect thruster design and plasma diagnostic engineering remains thin, constraining workforce scaling for production ramp.
- ECSS qualification timelines:European Cooperation for Space Standardization cleanliness testing under ECSS-E-ST-35-06C extends product validation by 18-24 months.
- Power subsystem integration:Solar-electric architectures require coordinated development between thruster manufacturers and solar array suppliers, complicating program management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrically Powered Spacecraft Propulsion Market |
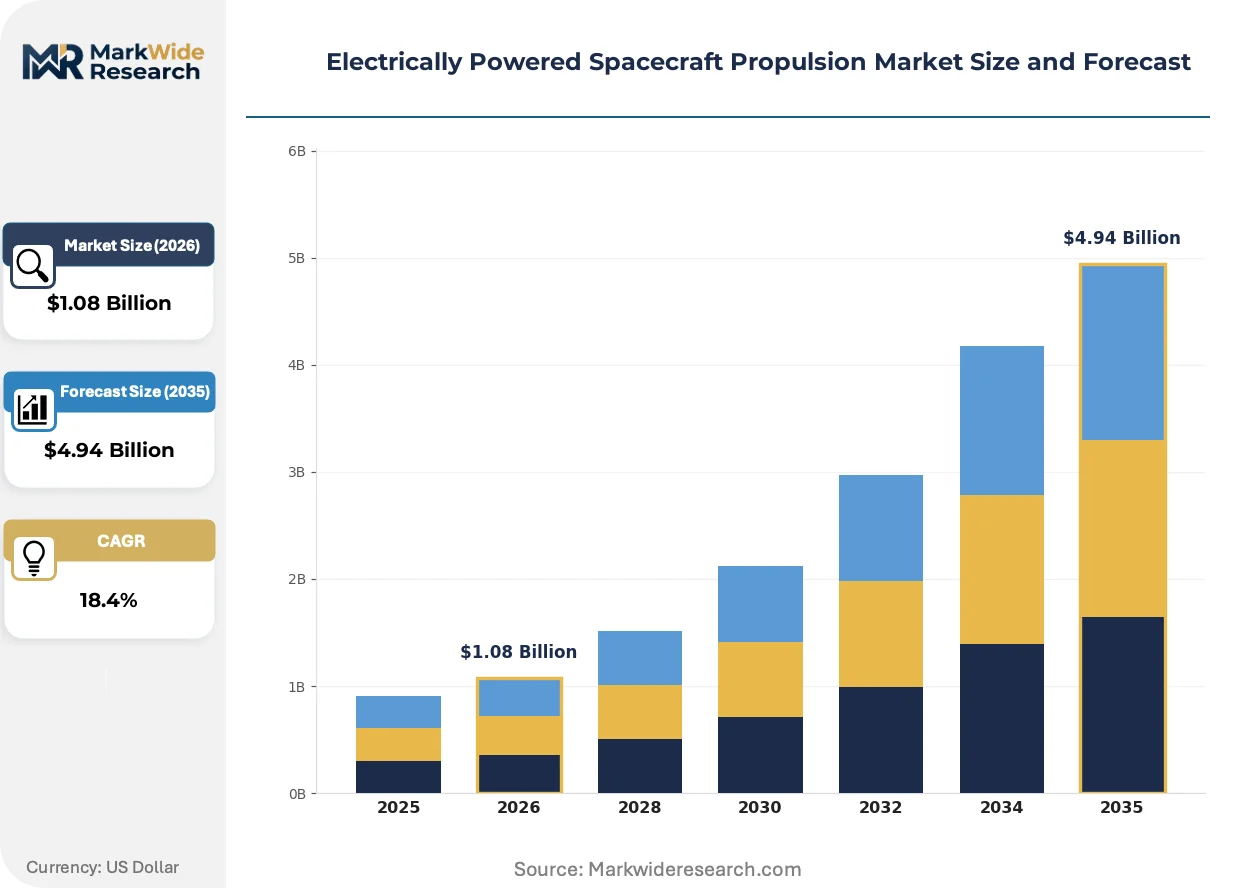
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $4.94 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Ion Thrusters, Hall Effect Thrusters, Magnetoplasmadynamic Thrusters, Electrospray Thrusters, Arcjets Power Source: Solar Panels, Radioisotope Thermoelectric Generators, Battery Systems, Fuel Cells, Nuclear Reactors Application: Satellite Stationkeeping, Deep Space Missions, Orbital Maneuvers, CubeSats, Space Exploration End User: Space Agencies, Commercial Satellite Operators, Research Institutions, Defense Organizations |
| Companies Covered | Busek Co. Inc., Safran SA, Airbus, Thales Alenia Space, Northrop Grumman, L3Harris Technologies, ENPULSION GmbH, Bellatrix Aerospace, Accion Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrically Powered Spacecraft Propulsion Market Trends and Innovations
Active development of iodine-fed electrospray thrusters is reshaping the miniature propulsion segment, while regulatory chemistry restrictions and on-orbit servicing business models simultaneously expand application scope and compress development cycles.
Krypton Hall effect thrusters are absorbing engineering investment previously directed at xenon systems due to supply security concerns and cost structure advantages. Commercial satellite operators in geostationary orbit are adopting krypton variants for stationkeeping maneuvers despite specific impulse trade-offs. The technology is absorbing qualification resources from gridded ion architectures as manufacturers prioritize thrust-to-power optimization over maximum efficiency.
REACH Annex XVII restrictions on hazardous substances are forcing propellant chemistry transitions across European satellite programs. ESA procurement guidelines now exclude hydrazine-based systems from new mission competitions, redirecting prime contractor sourcing toward electric alternatives. Small satellite manufacturers in Germany and France are accelerating iodine and krypton thruster integration to maintain eligibility for public funding.
Life-cycle service contracting is displacing unit-based thruster sales in geostationary satellite programs. Operators now procure propulsion performance guarantees spanning 15-year mission durations, transferring operational risk to subsystem suppliers. This model concentrates most visibly in United States government satellite contracts, where Space Force and NRO programs mandate availability-based payment structures.
Electrically Powered Spacecraft Propulsion Market Segmentation
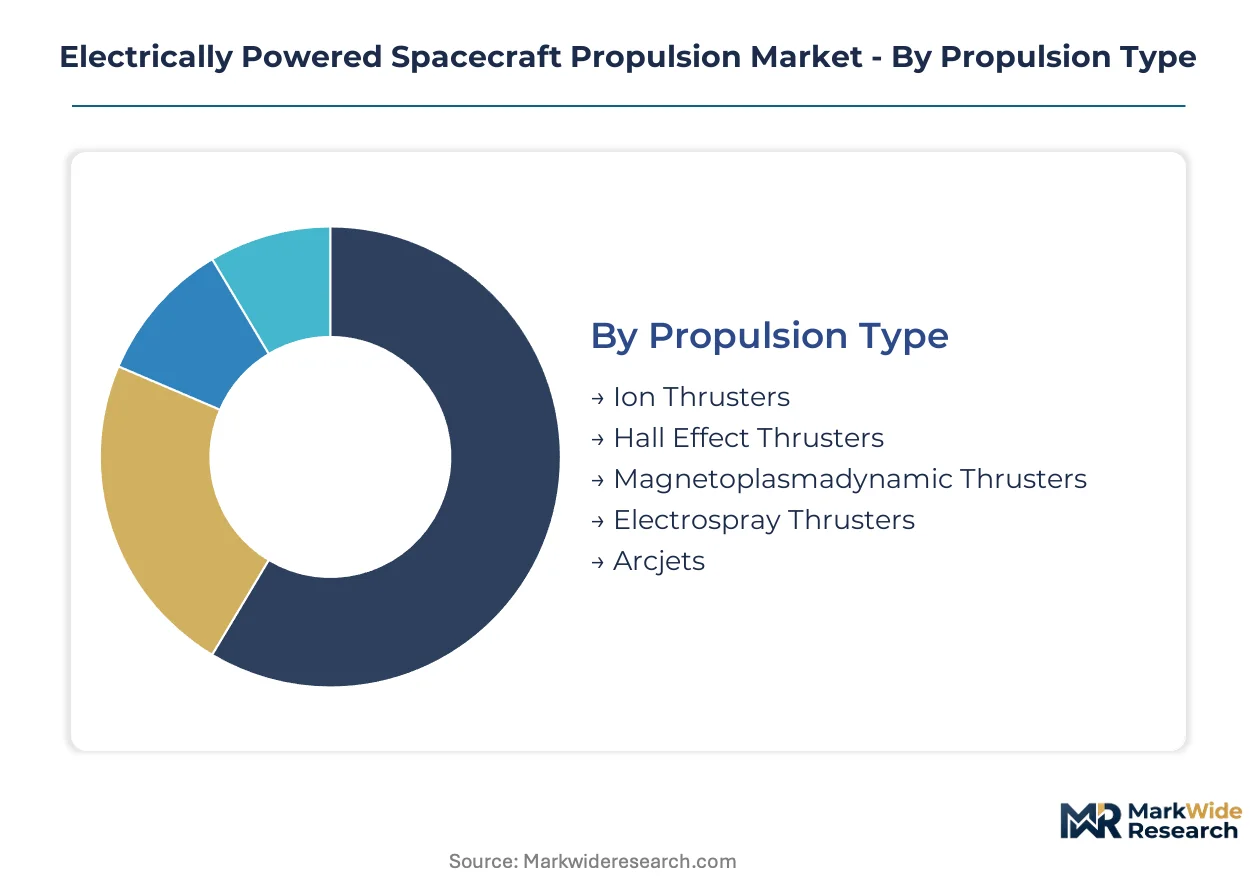
Segmentation in spacecraft propulsion reveals how certification pathways and power constraints fragment procurement across mission classes. Each dimension carries distinct qualification burdens that determine supplier eligibility and contract structures.
Propulsion Type:
NASA's Technology Readiness Level requirements and ESA's ECSS-E-ST-35-06C standards create divergent approval pathways for each thruster architecture, with flight heritage thresholds varying by mission criticality.
- Hall Effect Thrusters:Magnetic field confinement accelerates ions through an annular discharge channel, delivering thrust-to-power ratios superior to electrostatic alternatives. Commercial satellite operators in the United States favor these systems for geostationary orbit stationkeeping due to cumulative flight hours exceeding ten thousand across European and Asian programs.
- Ion Thrusters:Gridded electrostatic extraction produces specific impulses exceeding 3000 seconds through sequential ionization and acceleration stages. Deep space missions led by NASA's Science Mission Directorate concentrate demand here, where maximum propellant efficiency overrides mass and complexity penalties.
- Electrospray Thrusters:Field emission from ionic liquid menisci generates thrust in the micronewton range for precision attitude control.
- Arcjets:Thermal expansion of hydrogen or hydrazine decomposition products through electric arc heating yields moderate specific impulse with simple subsystem integration.
- Magnetoplasmadynamic Thrusters:Lorentz force acceleration of self-field or applied-field plasmas scales to megawatt power levels for heavy cargo transfer.
Leading the category by volume: Hall Effect Thrusters. Growing fastest: Electrospray Thrusters.
Power Source:
Cost tier segmentation separates near-Earth commercial applications from outer-planet science missions, with solar-electric architectures dominating procurement volumes below 50 kilowatts.
- Solar Panels:Photovoltaic arrays with triple-junction gallium arsenide cells supply 80-95% of near-Earth electric propulsion missions. Commercial satellite operators across Germany, France, and the United States specify solar-electric Hall thruster configurations for geostationary communications platforms.
- Radioisotope Thermoelectric Generators:Plutonium-238 decay heat conversion delivers continuous power independent of solar flux. NASA's outer-planet missions and ESA's JUICE program anchor procurement, where solar array mass becomes prohibitive beyond Jupiter's orbit.
- Battery Systems:Lithium-ion or solid-state storage enables pulsed operation modes for small satellite maneuvers.
- Fuel Cells:Regenerative hydrogen-oxygen systems support crewed spacecraft propulsion during eclipse periods.
- Nuclear Reactors:Kilopower-class fission systems target Mars cargo and deep space transport applications.
Highest shipment volumes flow through Solar Panels. Steepest expansion trajectory belongs to Battery Systems.
Application:
Customer maturity varies sharply across mission types, with established geostationary operators demanding 15-year service guarantees while emerging CubeSat builders accept higher technical risk.
- Satellite Stationkeeping:Continuous low-thrust counteraction of orbital perturbations maintains geostationary slot position and inclination. United States Space Force contracts and European commercial operators in Luxembourg and the United Kingdom specify electric systems for this duty cycle.
- Deep Space Missions:High-velocity increment requirements over multi-year durations prioritize specific impulse maximization. NASA Discovery and New Frontiers programs drive ion thruster procurement for asteroid rendezvous and outer-planet orbiters.
- Orbital Maneuvers:Perigee raising and plane change operations for medium Earth orbit constellations.
- CubeSats:Miniature spacecraft from 1U to 12U volumes require millinewton-precision actuation.
- Space Exploration:Crewed vehicle propulsion and lunar lander descent stages.
Dominant revenue share sits with Satellite Stationkeeping. CubeSats are climbing the fastest.
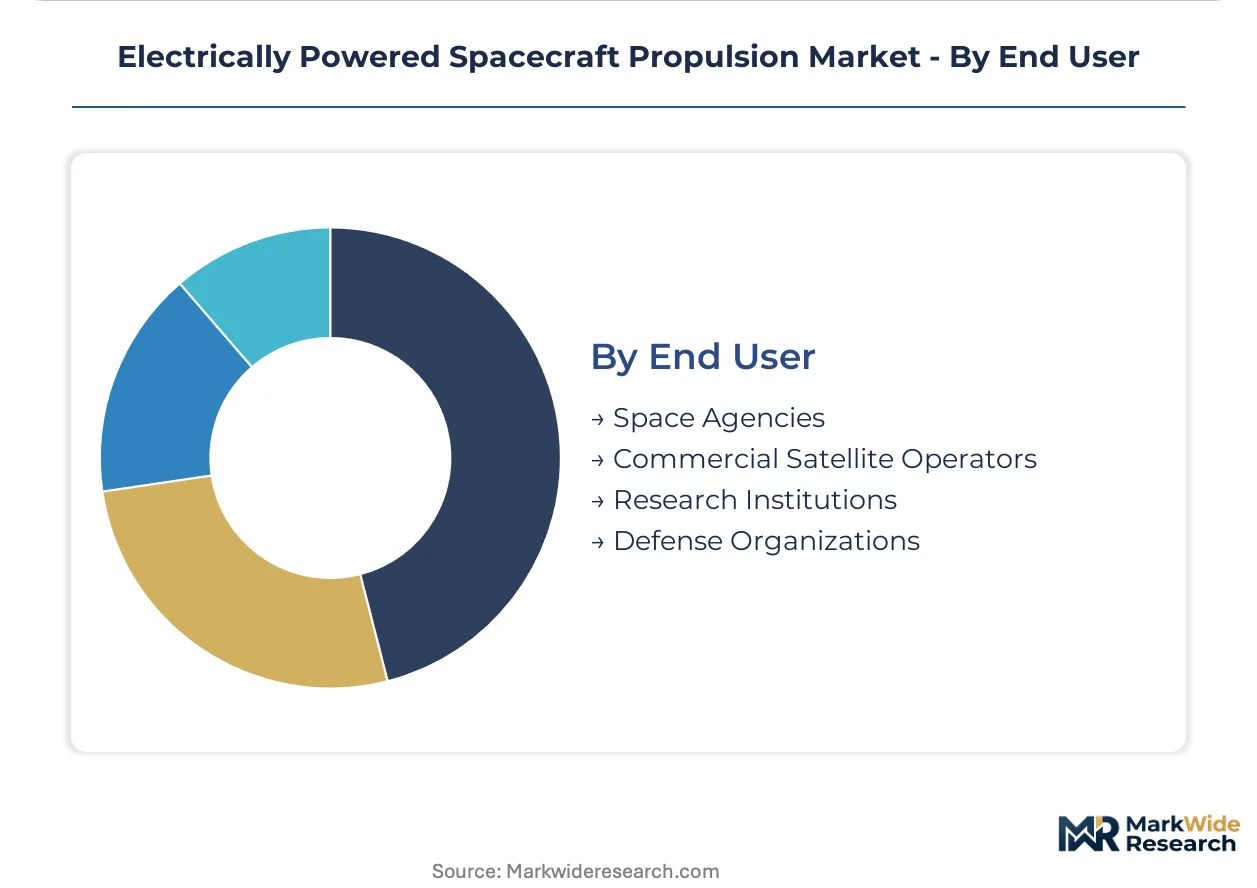
End User:
Procurement authority concentration determines contract structures, with defense organizations mandating domestic supply chains and research institutions tolerating lower Technology Readiness Levels.
- Commercial Satellite Operators:Profit-driven fleet managers in geostationary and low-Earth orbit segments specify electric propulsion for fuel mass reduction. SES, Intelsat heritage programs, and emerging constellation builders in the United States and Europe drive volume procurement of Hall effect systems.
- Space Agencies:NASA, ESA, and JAXA mission directorates fund technology development and flight qualification. Science Mission Directorate selections and ESA's Clean Space initiative create regulatory pull for green propulsion alternatives.
- Defense Organizations:National security satellite programs with classified requirements.
- Research Institutions:University-led technology demonstration missions.
Commercial Satellite Operators command the largest procurement volumes. Space Agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xenon extraction concentrates in Russia and Ukraine, anchoring supply-side geography for electric propulsion feedstocks. Procurement patterns diverge sharply between established space powers with domestic thruster qualification infrastructure and emerging satellite manufacturing clusters.
United States
Space Force launch contracts and SDA constellation awards channel investment toward domestic Hall effect thruster suppliers. FAA Office of Commercial Space Transportation licensing requirements shape payload integration protocols for electric propulsion missions. Los Angeles and Denver metropolitan areas concentrate prime contractor engineering operations for national security satellite programs.
France
Safran SA anchors European geostationary satellite propulsion through its PPS-5000 product line. ESA cleanliness standards under ECSS-E-ST-35-06C dictate qualification testing timelines for French suppliers. The Paris-Saclay cluster hosts plasma physics research facilities supporting thruster development programs.
Germany
REACH Annex XVII restrictions on hazardous substances accelerate krypton and iodine propellant transitions for German satellite manufacturers. The country's chemicals regulator enforces supply chain compliance for electrostatic thruster inputs. Munich and Stuttgart industrial corridors concentrate small satellite builder operations integrating miniature electric propulsion.
Japan
JAXA mission directorates fund ion thruster development for deep space exploration programs. METI industrial policy supports domestic qualification of green propulsion alternatives to hydrazine systems. Tsukuba Science City hosts government research centers advancing plasma diagnostic capabilities.
United Kingdom
Commercial satellite operators in Surrey and Oxfordshire specify electric propulsion for geostationary communications platforms. The UK Space Agency procurement guidelines align with ESA Clean Space initiative requirements. Harwell Campus clusters spacecraft subsystem suppliers addressing European public program mandates.
Electrically Powered Spacecraft Propulsion Market Competitive Landscape
Global majors compete with regional champions across qualification pathways and mission heritage requirements. Market structure shows moderate consolidation around prime satellite manufacturers with captive thruster production, alongside specialized subsystem suppliers serving science mission niches. Three archetypes dominate: aerospace conglomerates with integrated bus offerings, dedicated electric propulsion houses with flight-proven product lines, and venture-backed newcomers targeting CubeSat miniaturization. Competitive moves center on dual-sourcing partnerships with satellite primes and accelerated krypton propellant qualification to bypass xenon supply risks.
Within the established supplier tier, Safran SA and Northrop Grumman exemplify divergent strategic positions. Safran SA represents European geostationary heritage through its French corporate structure and S.A. designation. Northrop Grumman occupies a position as a U.S.-based aerospace conglomerate with integrated satellite bus manufacturing. Busek Co. Inc. anchors the specialized science mission segment, its Co. Inc. suffix indicating American corporate formation. These three entities collectively illustrate how qualification infrastructure and geographic proximity to procurement authorities determine competitive access.
| Leading Market Players |
|---|
| Busek Co. Inc. |
| Safran SA |
| Airbus |
| Thales Alenia Space |
| Northrop Grumman |
| L3Harris Technologies |
| ENPULSION GmbH |
| Bellatrix Aerospace |
| Accion Systems |
| Others |
Pricing and Supply Chain Analysis
Xenon spot pricing volatility in Russian and Ukrainian extraction centers cascades through electric propulsion supply chains, forcing satellite primes to tier procurement contracts by propellant security guarantees and flight heritage thresholds. This raw-material cost pressure splits the market between premium long-term offtake agreements with qualified suppliers and spot-market purchases accepting higher technical risk.
Pricing Analysis
Performance-guarantee bundling now dominates geostationary satellite contracts, with 15-year service availability commitments replacing discrete thruster unit sales. Three-tier pricing structure across mission-critical, standard qualification, and experimental heritage levels reflects ECSS certification investment and cumulative flight hours. Pricing pressure stems from krypton propellant substitution as manufacturers absorb requalification costs to bypass xenon supply risk. Commercial constellation builders exhibit highest price sensitivity, while national security programs prioritize supply assurance over unit economics.
Supply Chain Analysis
Refurbishment flows for Hall effect thruster discharge channels and grid erosion replacement in ion systems create secondary parts markets concentrated in France, Germany, and the United States. Critical inputs draw from Russian and Ukrainian xenon extraction, South Korean krypton refinement, and Japanese precision magnet manufacturing. Single-source vulnerability in rare gas feedstocks exposes suppliers to geopolitical disruption and REACH regulatory chemistry transitions. Distribution runs through prime satellite manufacturers with captive qualification infrastructure, limiting direct subsystem access for emerging spacecraft builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as prime contractors pursue backward control over thruster production to secure procurement priority in Space Force and SDA award cycles.
For Market Incumbents: Deploy captive plasma physics talent pools to accelerate krypton Hall thruster qualification before REACH-driven chemistry mandates reshape European procurement eligibility. Incumbents must consolidate flight heritage databases into proprietary mission assurance packages that emerging iodine thruster competitors cannot replicate, while absorbing electrospray specialists to preempt CubeSat constellation capture by venture-backed miniaturization houses. For New Entrants and Emerging Players: Launch via direct qualification partnerships with German and French small satellite builders facing EU Green Deal hydrazine exclusion deadlines. New entrants should target the 3U-12U CubeSat propulsion segment where heritage requirements remain minimal and iodine electrospray architectures bypass xenon supply concentration entirely, using precision maneuvering demonstrations as technical credibility anchors for upstream geostationary qualification pursuits. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized gridded ion thruster houses with NASA Science Mission Directorate flight heritage in the United States, where TRL gatekeeping creates durable competitive moats. Long-term viability rests on positioning for outer-planet nuclear-electric propulsion architectures beyond practical solar range. Practitioners should monitor Space Development Agency constellation award velocity and ESA Clean Space procurement mandate implementation as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Krypton Propellant Qualification Program | REACH Annex XVII compliance secures European public satellite program eligibility for French and German suppliers. |
| Flight Heritage Database Consolidation | Proprietary mission assurance packages anchored in NASA Science Mission Directorate selections create defensible positioning. |
| CubeSat Electrospray Acquisition | Iodine-fed miniature thruster capabilities address SDA proliferated low-Earth orbit precision stationkeeping mandates. |
| Plasma Physics Workforce Expansion | Talent scarcity in Hall effect discharge channel design constrains production scaling for domestic Space Force contract fulfillment. |
| Life-Cycle Service Contracting Transition | Availability-based payment structures transfer operational risk from United States government satellite operators to subsystem suppliers. |
Research Methodology
NASA Technology Readiness Level documentation, ESA ECSS-E-ST-35-06C qualification records, and Space Force procurement award announcements formed the secondary backbone, cross-referenced with primary interviews involving Hall thruster engineering directors, satellite prime procurement leads, plasma physics research faculty, and rare gas supply specialists. Bottom-up triangulation across propulsion subsystem shipment records and top-down validation against national space agency budget allocations ensured segmentation integrity.
Historical trendline analysis of flight heritage accumulation rates and propellant chemistry transition timelines informed projection modeling across the analysis window. Segmentation dimensions included thruster architecture type, power source configuration, mission application class, and end-user procurement authority. CAGRs were derived from satellite launch manifest projections and constellation deployment schedules, with specific weighting for SDA proliferated architecture mandates and ESA Clean Space regulatory tailwinds.
The model assumes a particular technology adoption path; alternative pathways for iodine-fed electrospray miniaturization would alter the outlook if qualification timelines compress below current ECSS standards. Forecasts reflect assumptions about REACH enforcement consistency and Space Force domestic sourcing requirements. Practitioners should monitor xenon supply disruption indicators and krypton requalification completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Burial Service Market
Space
Space Propulsion Systems Market
Space
Space Robotics Market
Space
Canada Space Electronics Market
Space
Astronaut Spacesuit Market
Space
Space Ground System Market
Space
Space Management Solutions Market
Space
UK Space Propulsion System Market
Space
Spacecraft Market
Space
Rocket Launchpad Market
Space
Space Wheel Market
Space
Space Lander and Rover Market
Space
Space-Based Smart Sensors Market
Space
Asia-Pacific Space Electronics Market
Space
Mexico Space Electronics Market
Space
Germany Space Electronics Market