
 Asia-Pacific Space Electronics Market | 2026-2036
Asia-Pacific Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Space Electronics Market Analytics
ECSS-Q-ST-60-02C qualification for radiation-hardened components is bifurcating the vendor landscape between qualified heritage suppliers and commercial entrants. Honeywell International Inc. leverages its legacy avionics certification to anchor satellite power system contracts across Japanese and Australian programs. STMicroelectronics N.V. competes through European-Asian dual qualification, sustaining foundry access for radiation-hardened ASIC production. Mitsubishi Electric dominates domestic procurement in Japan, controlling geostationary satellite electronics integration from its Kamakura facilities.
Asia-Pacific space electronics encompasses radiation-tolerant processors, power conditioning units, RF communication subsystems, and sensor payloads engineered to operate across orbital regimes from low Earth orbit through deep space transit. These systems employ silicon-on-insulator substrates, triple-module redundancy architectures, and hermetic packaging rated for total ionizing dose thresholds exceeding 100 krad(Si) to ensure mission continuity under proton and heavy ion exposure. Power Systems and Communication Systems represent the largest value pools, with margin concentration in radiation-hardened power management ICs where qualification cycles extend 18-24 months. FPGA technology is displacing fixed-function ASICs in new satellite platforms, as reprogrammable logic reduces non-recurring engineering costs for constellation operators iterating payload designs across multiple launch tranches.
Japan's METI space industry roadmap, India's BIS electronics standards for space-grade components, and Australia's Space Agency regulatory framework collectively shape qualification requirements and cross-border procurement eligibility. Australia's Space Activities Act licensing conditions impose debris mitigation and frequency coordination obligations that cascade into subsystem reliability specifications for electronics vendors seeking launch contracts. Stakeholders must track how national security classification protocols around satellite technology exports reshape partnership structures between Australian constellation operators and Japanese component suppliers.
Market Dynamics
FPGA reprogrammability is decomposing fixed-function ASIC procurement patterns across Asia-Pacific satellite constellations, compressing non-recurring engineering cycles and enabling iterative payload design across sequential launch tranches. This architectural shift reconfigures vendor qualification priorities and foundry capacity allocation.
Growth Catalysts
- India's PLI scheme:Production-linked incentives redirect electronics manufacturing investment toward domestic foundries, expanding radiation-hardened component fabrication capacity for space-grade applications.
- Broadband satellite constellations:Low Earth orbit connectivity networks pull procurement volumes upward across power conditioning and RF communication subsystems.
- ECSS-Q-ST-60-02C qualification pathways:European-Asian dual certification standards enable cross-border supplier eligibility for Japanese and Australian programs.
Market Restraints
- Silicon-on-insulator substrate concentration:Foundry capacity for radiation-hardened wafers concentrates in limited fabrication facilities, creating supply bottleneck risk for power management ICs.
- 18-24 month qualification cycles:Extended radiation-hardening certification timelines lock working capital and delay revenue recognition for component vendors.
- Heavy ion test facility scarcity:Total ionizing dose validation infrastructure concentrates in Japan and select European sites, constraining new entrant validation throughput.
Strategic Opportunities
- Australia's Space Activities Act licensing:Debris mitigation and frequency coordination obligations cascade into subsystem reliability specifications, creating demand for qualified electronics vendors.
- Triple-module redundancy convergence:Fault-tolerant computing architectures merge with commercial semiconductor processes, opening cost reduction pathways for constellation operators.
- Hermetic packaging innovation:Advanced sealing technologies for 100+ krad(Si) tolerance enable penetration of deep space transit missions beyond geostationary orbit.
Industry Challenges
- Radiation effects engineering talent scarcity:Specialized workforce for proton and heavy ion hardening design concentrates in Tokyo and Nagoya satellite component clusters, constraining program scaling.
- Cross-border technology classification friction:National security protocols around satellite electronics exports reshape partnership structures between Australian constellation operators and Japanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Space Electronics Market |
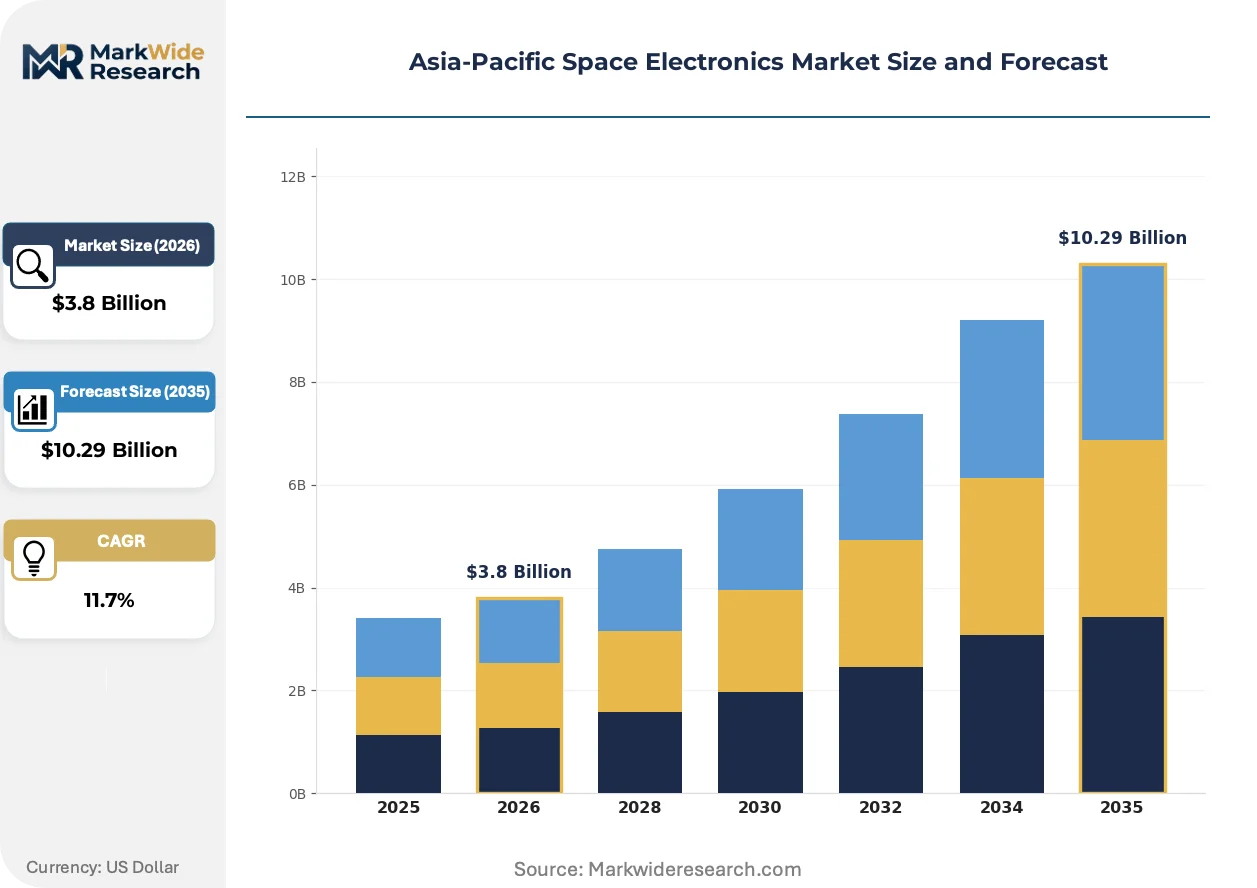
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processors, Power Systems, Communication Systems, Sensors Technology: Radiation-Hardened, FPGA, ASIC, COTS Application: Satellite Systems, Launch Vehicles, Deep Space Exploration, Earth Observation End User: Government Agencies, Commercial Entities, Research Institutions, Military |
| Companies Covered | Honeywell International Inc., STMicroelectronics N.V., Northrop Grumman Corporation, Lockheed Martin Corporation, Thales Alenia Space, Mitsubishi Electric, L3Harris Technologies, Teledyne Technologies Incorporated, Microchip Technology Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Space Electronics Market Evolving Landscape
Reprogrammable logic architectures are actively restructuring procurement economics for Asia-Pacific satellite platforms. Three concurrent developments reshape competitive positioning across radiation-hardened component supply.
FPGA technology is decomposing fixed-function ASIC dominance in new satellite platforms. Constellation operators in Japan and Australia adopt field-programmable gate arrays for payload control systems, enabling design iteration without full mask-set respins. This reprogrammability compresses development timelines and reduces non-recurring engineering exposure across multi-tranch launch programs.
METI's space industry roadmap tightens domestic content requirements for geostationary satellite programs. Japanese procurement rules now mandate local integration for critical electronics subsystems, redirecting foundry contracts toward Kamakura-area facilities. Australian operators seeking Japanese component supply must navigate amended partnership structures under revised technology transfer frameworks.
Buyer consolidation among constellation operators concentrates negotiation leverage for radiation-hardened power management ICs. Large-scale LEO network developers now specify multi-mission qualification packages, displacing single-program vendor relationships. This procurement compression is most visible in power subsystem contracts, where volume commitments extract preferential foundry access from qualified heritage suppliers.
Asia-Pacific Space Electronics Market Segmentation
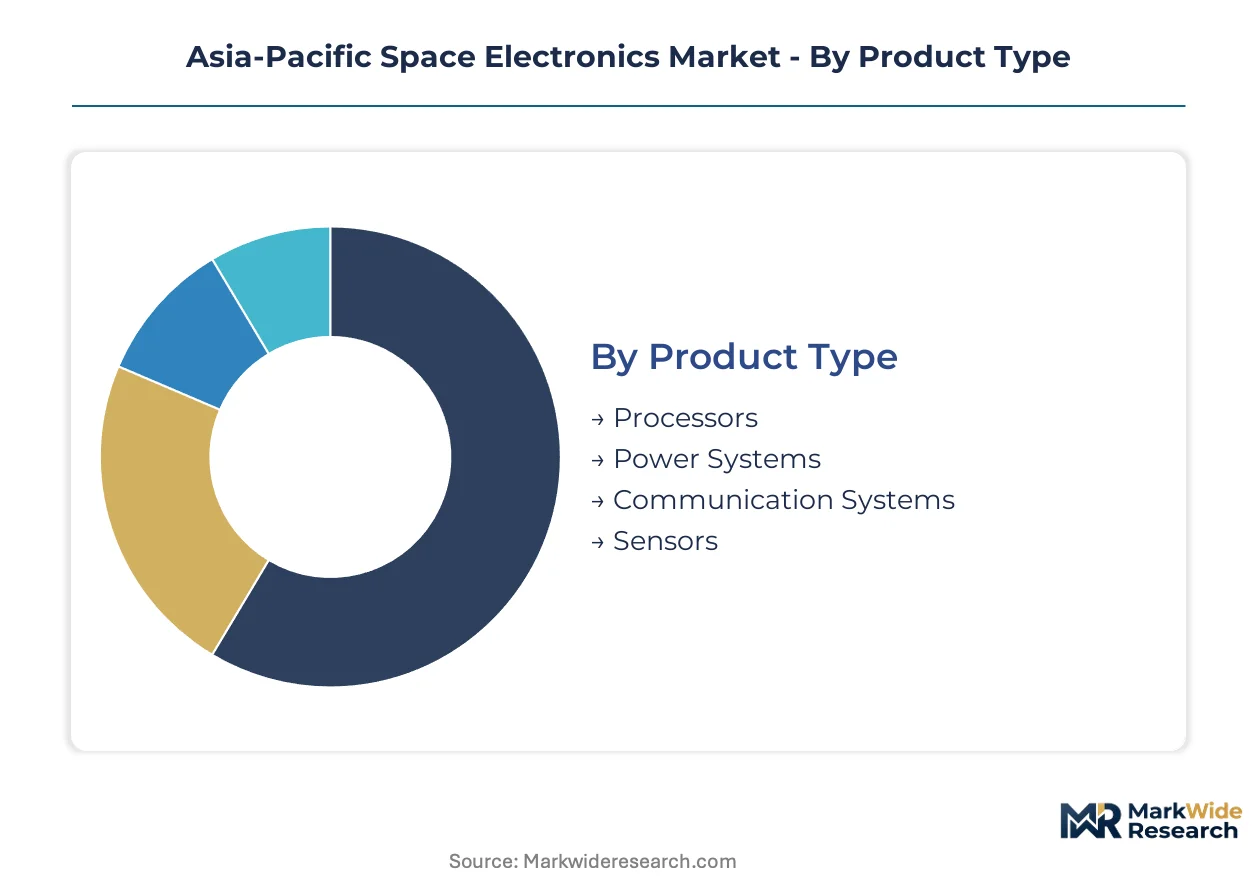
Segmentation reveals how FPGA reprogrammability and qualification tiering fragment procurement patterns across Asia-Pacific satellite programs. Radiation-hardening requirements, foundry access constraints, and constellation operator consolidation reshape value concentration differently across each dimension.
Product Type:
Power Systems face the strongest substitution pressure from commercial-off-the-shelf components in low Earth orbit constellations, while Communication Systems resist displacement due to frequency coordination licensing requirements.
- Power Systems:Radiation-hardened power management ICs and conditioning units regulate voltage across proton-heavy orbital environments. Procurement concentrates in Japanese geostationary programs where METI domestic content rules mandate Kamakura-area integration, though 18-24 month qualification cycles constrain vendor throughput.
- Communication Systems:RF subsystems, transponders, and antenna electronics manage signal integrity under total ionizing dose exposure. Australian constellation operators drive procurement volume through Space Activities Act licensing obligations that cascade into subsystem reliability specifications for debris mitigation compliance.
- Processors:Radiation-tolerant computing modules execute payload control with triple-module redundancy architectures.
- Sensors:Payload instrumentation for Earth observation and deep space transit missions employs silicon-on-insulator substrates rated for 100+ krad(Si) tolerance.
Power Systems retains volume leadership; Communication Systems holds the steepest expansion curve.
Technology:
Cost tier stratification separates heritage-qualified suppliers from commercial entrants, with radiation-hardening investment levels determining foundry access and program eligibility.
- Radiation-Hardened:Components qualified to ECSS-Q-ST-60-02C standards with total ionizing dose validation exceeding 100 krad(Si). Japanese satellite programs anchor demand through METI procurement rules requiring hermetic packaging and heavy ion test documentation.
- FPGA:Field-programmable gate arrays enable payload design iteration without mask-set respins. Australian and Japanese constellation operators compress non-recurring engineering cycles across multi-tranch launch programs through reprogrammable logic adoption.
- ASIC:Fixed-function application-specific integrated circuits retain position in geostationary platforms with stable mission profiles.
- COTS:Commercial-off-the-shelf electronics penetrate low Earth orbit constellations where radiation tolerance requirements relax.
Radiation-Hardened commands premium positioning; FPGA gains share fastest through constellation operator procurement consolidation.
Application:
Customer type divergence separates government-funded deep space programs from commercial constellation operators with contrasting qualification tolerance and volume scale.
- Satellite Systems:Electronics for geostationary, medium Earth orbit, and low Earth orbit platforms span power, communication, and processing subsystems. India's PLI scheme redirects foundry investment toward domestic fabrication capacity serving broadband constellation procurement.
- Launch Vehicles:Avionics and telemetry electronics withstand ascent-phase vibration and thermal profiles. Japanese H3 rocket development anchors component demand through Mitsubishi Electric integration contracts.
- Deep Space Exploration:Transit-rated electronics for lunar and interplanetary missions require extended hermetic packaging validation.
- Earth Observation:Sensor payloads and downlink systems serve agricultural monitoring and maritime surveillance applications.
Satellite Systems dominates procurement volume; Earth Observation climbs the fastest on commercial imaging constellation deployment.
End User:
Supply concentration varies sharply between classified military procurement channels and commercial constellation operator consolidation.
- Government Agencies:National space organizations specify ECSS-qualified heritage components with traceable radiation test histories. Japan's JAXA and India's ISRO anchor procurement through geostationary program continuity.
- Commercial Entities:Constellation operators negotiate multi-mission qualification packages extracting preferential foundry access. Australian broadband network developers consolidate vendor relationships around power subsystem volume commitments.
- Research Institutions:University and laboratory missions access shared heavy ion test facilities in Tokyo and Nagoya clusters.
- Military:Classified satellite programs impose national security protocols reshaping cross-border partnership structures with Japanese component suppliers.
Government Agencies retain qualification gatekeeping authority; Commercial Entities drive the steepest expansion trajectory through procurement consolidation leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing redirects supply chain investment toward domestic foundries serving radiation-hardened component fabrication. Japan's METI space industry roadmap tightens domestic content requirements for geostationary satellite programs. Australia's Space Activities Act licensing conditions impose debris mitigation obligations that cascade into subsystem reliability specifications.
Japan
JAXA anchors procurement through geostationary program continuity and deep space exploration missions. METI procurement rules now mandate local integration for critical electronics subsystems, redirecting foundry contracts toward Kamakura-area facilities. The Tokyo-Nagoya satellite component cluster concentrates radiation effects engineering talent and heavy ion test infrastructure.
India
ISRO drives demand for indigenous power conditioning and RF communication subsystems across broadband constellation deployments. The PLI scheme expands radiation-hardened component fabrication capacity for space-grade applications through domestic foundry investment. Bengaluru and Hyderabad host emerging electronics manufacturing clusters serving satellite payload integration.
Australia
The Australian Space Agency's licensing framework creates demand for qualified electronics vendors through debris mitigation compliance requirements. Space Activities Act frequency coordination obligations cascade into subsystem reliability specifications for constellation operators. South Australia hosts emerging satellite manufacturing capabilities near Adelaide.
South Korea
KARI anchors government-funded satellite programs requiring ECSS-qualified heritage components with traceable radiation test histories. The country's national electronics regulator enforces standards for space-grade component qualification. Seoul Capital Area concentrates semiconductor fabrication capacity serving regional satellite supply chains.
Singapore
Commercial constellation operators leverage the city-state's advanced manufacturing infrastructure for satellite electronics assembly and testing. The national space office coordinates regional launch service access for Asia-Pacific payload developers. Jurong hosts precision manufacturing facilities serving radiation-hardened packaging requirements.
Asia-Pacific Space Electronics Market Competitive Landscape
Player mix skews toward diversified aerospace-electronics conglomerates with legacy qualification portfolios. Market structure concentrates around heritage suppliers holding ECSS-Q-ST-60-02C certification and commercial entrants leveraging FPGA reprogrammability. Two strategic archetypes dominate: vertically integrated satellite prime contractors controlling subsystem integration, and specialized component vendors securing foundry access through dual-qualification strategies. Competitive moves center on capacity expansion into domestic fabrication facilities and strategic partnerships bridging cross-border technology transfer protocols.
Among heritage-qualified suppliers, Honeywell International Inc. and STMicroelectronics N.V. occupy positions reflecting European-Asian dual certification advantages, while Mitsubishi Electric exemplifies the vertically integrated domestic prime archetype serving Japanese geostationary programs through Kamakura-area integration facilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| STMicroelectronics N.V. |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Thales Alenia Space |
| Mitsubishi Electric |
| L3Harris Technologies |
| Teledyne Technologies Incorporated |
| Microchip Technology Incorporated |
| Others |
Value Network & Pricing Analysis
ECSS-Q-ST-60-02C qualification gates both supplier eligibility and price differentiation simultaneously, bifurcating the vendor landscape between heritage-certified incumbents commanding 18-24 month qualification premiums and commercial entrants competing on reprogrammable logic flexibility. This certification architecture concentrates pricing power among dual-qualified suppliers while compressing margins for single-tier vendors locked out of Japanese and Australian government programs.
Pricing Analysis
Certification level creates the primary spread across the Asia-Pacific space electronics market. Three-tier pricing structure across heritage-qualified, dual-certified, and commercial-off-the-shelf levels separates vendors by total ionizing dose validation thresholds and hermetic packaging documentation. Price differentiation rests on heavy ion test facility access and foundry queue priority rather than raw component performance. Cost compression in power management ICs is intensifying because constellation operators now negotiate multi-mission qualification packages extracting volume discounts. Commercial Entities exhibit highest price sensitivity through procurement consolidation leverage, while Government Agencies prioritize traceable radiation test histories over unit economics.
Supply Chain Analysis
Silicon-on-insulator wafer fabrication concentrates in Japan, South Korea, and select European sites as the critical chokepoint constraining radiation-hardened component throughput. Raw material dependencies center on high-resistivity silicon substrates, hermetic ceramic packaging, and specialized heavy ion test services. Single-source vulnerability runs through the Tokyo-Nagoya satellite component cluster where radiation effects engineering talent and validation infrastructure co-locate. Distribution runs through vertically integrated prime contractors controlling subsystem integration from Kamakura-area facilities, with tier-two component vendors feeding into domestic content-mandated programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation effects engineering talent scarcity concentrates in established clusters, constraining program scaling for operators lacking captive workforce development or partnership access. This capability gap rewards early movers securing heavy ion test facility relationships and dual-qualification pathways.
For Market Incumbents: Shield heritage certification portfolios through accelerated ECSS-Q-ST-60-02C renewal cycles ahead of METI domestic content rule tightening. Capacity addition in Indian domestic foundries under PLI scheme incentives captures redirected supply chain investment before commercial entrants achieve qualification parity. Channel control through exclusive heavy ion test facility partnerships in Tokyo and Nagoya clusters constrains new entrant validation throughput. For New Entrants and Emerging Players: Anchor in FPGA reprogrammability as the white-space entry vector where fixed-function ASIC procurement patterns decompose fastest. Australian constellation operators present the most penetrable buyer segment through Space Activities Act licensing obligations cascading into subsystem reliability specifications. Go-to-market execution should target debris mitigation compliance consulting bundled with reprogrammable payload control systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radiation-hardened power management IC fabrication as qualification cycles extend and foundry capacity concentrates. Long-term viability favors acquisition targets holding European-Asian dual certification with traceable heavy ion test documentation rather than pure commercial logic plays. Watch for METI procurement rule amendments tightening domestic integration mandates as the inflection signal for Japanese supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Qualification Investment | ECSS-Q-ST-60-02C plus BIS standards unlock cross-border eligibility for Indian and Australian programs. |
| Domestic Foundry Expansion | PLI scheme incentives redirect capital toward Bengaluru and Hyderabad radiation-hardened fabrication capacity. |
| Heavy Ion Test Partnership | Tokyo and Nagoya facility access constrains new entrant throughput and protects incumbent margins. |
| FPGA Platform Migration | Reprogrammable logic adoption compresses non-recurring engineering cycles for multi-tranch constellation operators. |
| Hermetic Packaging Innovation | 100+ krad(Si) tolerance validation enables penetration of deep space transit missions beyond geostationary orbit. |
Research Methodology
The analysis maps radiation-hardened component fabrication, FPGA reprogrammable logic adoption, and power subsystem procurement patterns, each validated through satellite prime contractor procurement officers, radiation effects engineering specialists, constellation operator technical directors, and domestic foundry investment leads. Primary interview intelligence triangulates against ISRO program disclosures, JAXA procurement documentation, METI space industry roadmap publications, and Australian Space Agency licensing records. Bottom-up segment sizing and top-down macro validation ensure cross-check consistency across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology tier, application mission profile, end-user procurement channel, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from installed base evolution and replacement cycle timing across broadband constellation deployment waves. Forecast inputs incorporate PLI scheme capacity addition schedules and METI domestic content rule amendment trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained constellation operator procurement consolidation and stable qualification timeline structures; material deviation in heavy ion test facility capacity or cross-border technology transfer protocols would warrant model refresh. Practitioners should keep alternative scenarios live as METI procurement rule amendments and Australian Space Agency licensing condition revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Astronaut Spacesuit Market
Space
Space Blanket Market
Space
Asteroid Mining Market
Space
Orbital Spaceflight Market
Space
Space on Board Computing Platform Market
Space
Space Launch Services Market
Space
Space-Based Smart Sensors Market
Space
Space Management Solutions Market
Space
Japan Space Electronics Market
Space
Space Service Market
Space
India Space Electronics Market
Space
Space-Based C4ISR Market
Space
Mexico Space Electronics Market
Space
Space Ground System Market
Space
Space Mining Market
Space
Space Semiconductor Market