
 France Space Electronics Market | 2026-2036
France Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
France Space Electronics Market Insights
Defense and Earth observation is shifting toward multi-satellite constellations requiring radiation-hardened components. Thales Alenia Space leverages its Cannes and Toulouse facilities to dominate payload electronics integration. Airbus sustains broad vertical coverage from satellite platforms to ground segment hardware. Safran competes through specialized propulsion and power management systems for geostationary missions.
France space electronics encompasses radiation-hardened semiconductors, high-reliability power conditioning units, and RF subsystems engineered to withstand orbital thermal cycling between minus 150 and plus 120 degrees Celsius. These systems enable satellite command, telemetry, and payload data processing for institutional and commercial missions. Analog technology leads in power management and sensor interfaces due to proven heritage in long-duration missions. Digital segments are expanding fastest as onboard processing demands rise for Earth observation analytics. RF and microwave categories occupy concentrated margin pools in satellite communications and navigation payloads.
CNES, ESA, and ANSM shape qualification requirements through mission assurance standards that dictate component traceability and radiation tolerance testing. French military procurement regulations under the Direction Générale de l'Armement impose additional cybersecurity and supply chain sovereignty constraints on defense-destined electronics. Stakeholders must monitor how EU space program funding allocations and national preference clauses reshape subcontractor access across the domestic value chain.
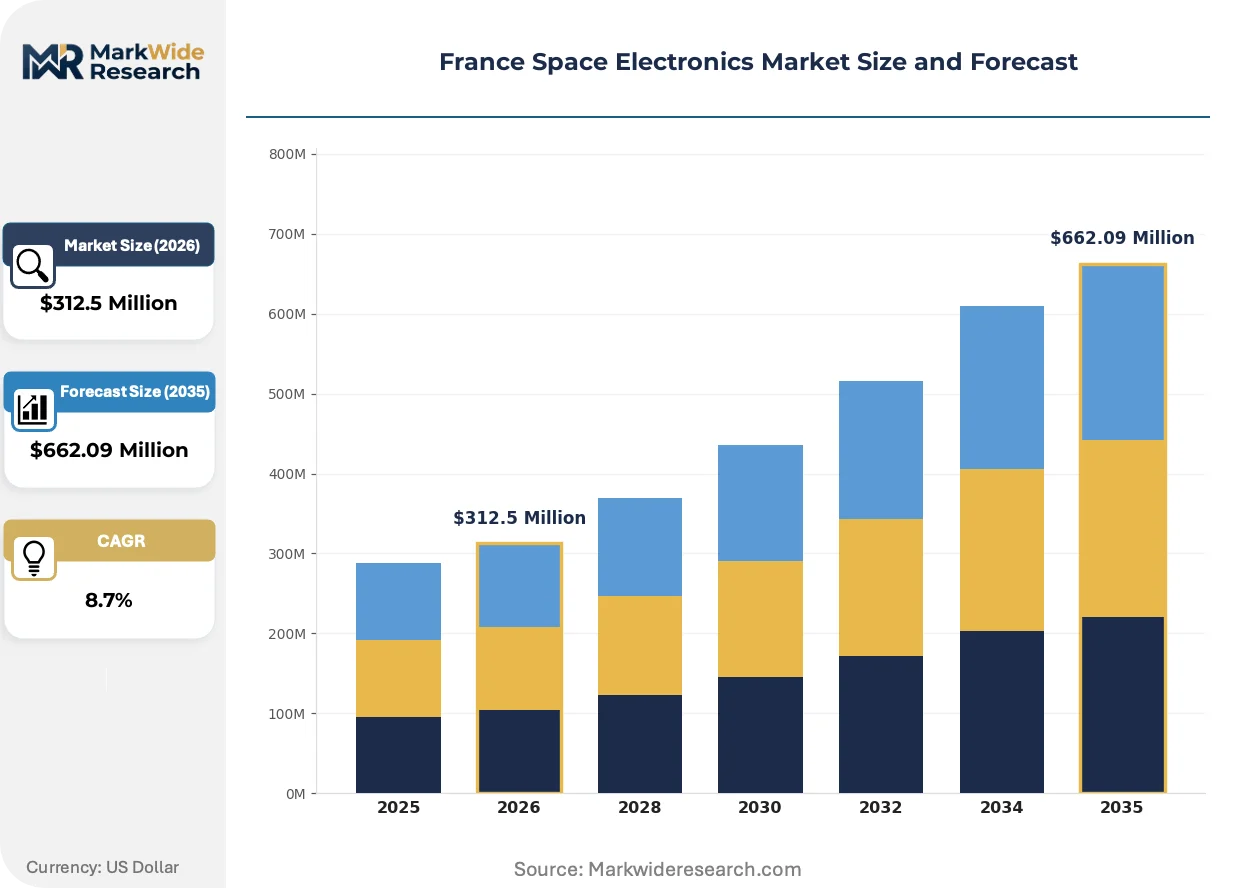
Market Dynamics
ESA's Geographical Return principle and France's national space sovereignty strategy are channeling procurement toward domestic radiation-hardened component suppliers, restructuring subcontractor access across the Toulouse-Cannes manufacturing corridor.
Growth Catalysts
- Earth observation constellations:Commercial and institutional operators are deploying multi-satellite arrays for climate monitoring and defense surveillance, accelerating demand for batch-procured avionics.
- EU Space Programme funding:The European Commission's budget allocations for IRIS² and Copernicus expansion are creating dedicated revenue streams for French payload integrators.
- Radiation-hardening advances:New fault-tolerant FPGA architectures are extending component lifespans in medium Earth orbit, reducing replacement cycle frequency for prime contractors.
Market Restraints
- Wafer supply concentration:Specialty foundry capacity for rad-hard semiconductors clusters at single-source suppliers in the United States and legacy European facilities.
- Qualification timeline friction:CNES mission assurance protocols impose multi-year component validation cycles that compress contract award-to-delivery windows.
- Substitute platform economics:Small satellite operators are adopting commercial-off-the-shelf electronics with orbital redundancy rather than heritage-qualified parts.
Strategic Opportunities
- Onboard AI processing:Edge computing architectures for real-time Earth observation analytics represent unpenetrated demand from French defense and climate agencies.
- Paris-Saclay corridor expansion:Deep-tech incubators around Saclay are cultivating fabless semiconductor startups targeting radiation-tolerant power management.
- Green propulsion integration:Convergence of electric thruster systems with intelligent power distribution electronics opens payload mass optimization for geostationary missions.
Industry Challenges
- Radiation effects engineering talent:The specialized skill set for single-event upset mitigation and total dose testing faces generational scarcity in French aerospace programs.
- ITAR compliance complexity:U.S. export control classifications on dual-use semiconductors create licensing delays for Franco-American component partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Space Electronics Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellites, Launch Vehicles, Ground Equipment, Orbiting Platforms Technology: Analog, Digital, RF, Microwave End User: Government Agencies, Commercial Operators, Research Institutions, Defense Application: Telecommunication, Earth Observation, Scientific Research, Navigation |
| Companies Covered | Thales Alenia Space, Airbus, Thales Group, STMicroelectronics, ArianeGroup, OHB SE, Honeywell International, BAE Systems, Safran, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Space Electronics Market Trends and Innovations
Artificial intelligence integration and sovereign supply chain mandates are compressing development cycles while elevating cybersecurity requirements across French space electronics procurement.
Reconfigurable intelligent field-programmable gate arrays are automating fault detection and autonomous recovery routines in satellite command chains. Thales Alenia Space and Airbus Defence and Space are embedding these devices in next-generation Earth observation platforms. This automation is compressing ground intervention requirements and extending operational autonomy for deep-space missions.
France's national space strategy and the EU Space Law framework are mandating end-to-end component traceability and domestic sourcing quotas for institutional payloads. The Direction Générale de l'Armement has imposed additional cybersecurity certification tiers on defense-destined electronics. Small and mid-tier subcontractors in the Toulouse cluster are restructuring supply relationships to meet these sovereign content thresholds.
Consolidated procurement frameworks are replacing discrete component purchasing with subsystem-level vendor partnerships. Prime contractors are bundling avionics, power management, and RF units under single-source qualification agreements. This concentration is most visible in CNES and ESA institutional satellite programs, where risk-sharing contracts now dominate award mechanisms.
France Space Electronics Market Segmentation
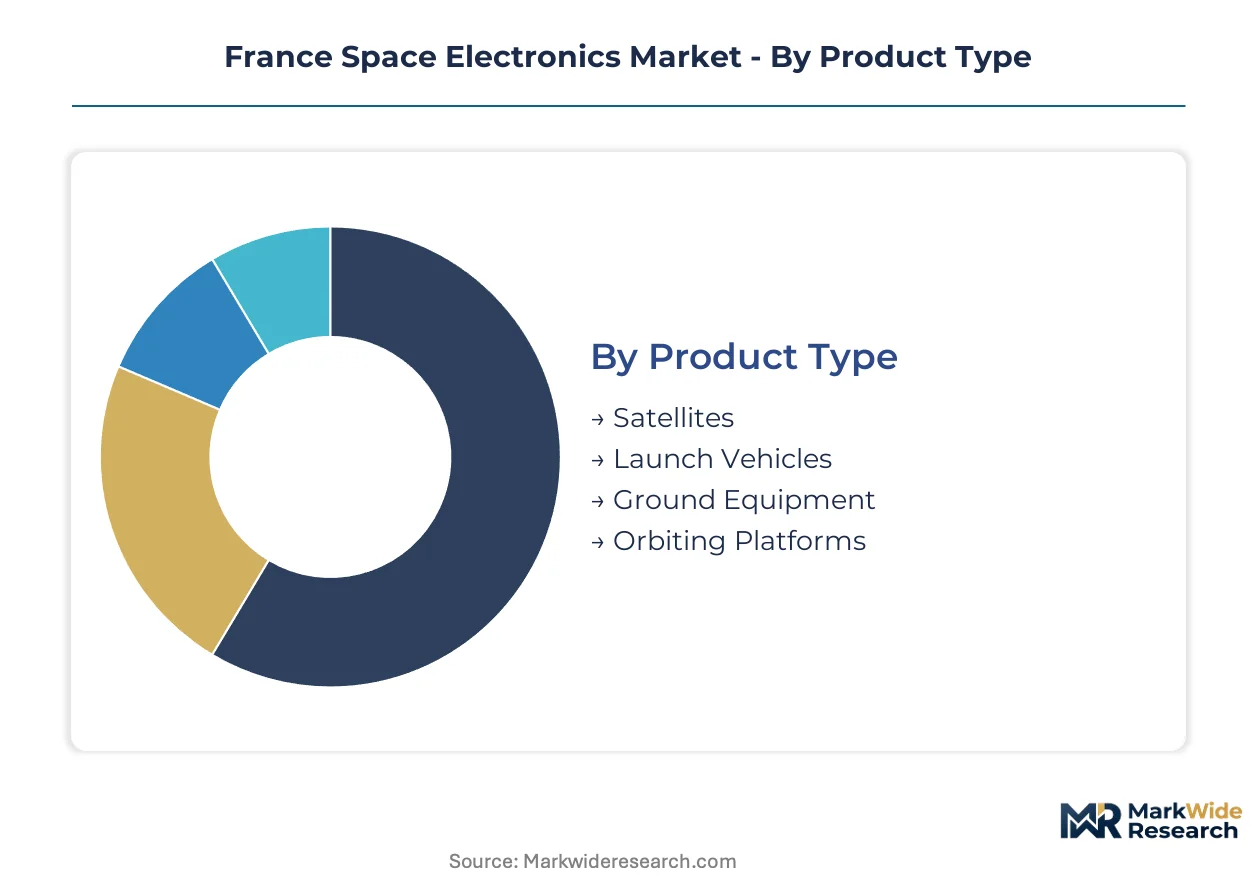
France's space electronics procurement channels through distinct technical and institutional pathways. Each segment boundary reflects sovereign supply chain mandates and mission assurance requirements that reshape vendor access across the Toulouse-Cannes corridor.
Product Type:
Supply concentration clusters around institutional satellite platforms where prime contractors bundle avionics, power systems, and RF units under consolidated qualification agreements.
- Satellites:Bus electronics, payload processors, and power conditioning units engineered for 15-year operational lifespans in geostationary orbit. Demand concentrates in CNES and ESA institutional programs where Thales Alenia Space and Airbus Defence and Space dominate integration contracts.
- Launch Vehicles:Flight computers, telemetry systems, and thrust vector control electronics for Ariane 6 and Vega-C programs. Procurement flows through ArianeGroup's Les Mureaux and Vernon facilities with strict ANSM traceability requirements.
- Ground Equipment:Antenna control systems, signal processors, and mission control infrastructure for satellite operations centers.
- Orbiting Platforms:International Space Station modules and future lunar gateway components requiring dual-use qualification for crewed and robotic missions.
Today's leader: Satellites. Tomorrow's challenger: Orbiting Platforms.
Technology:
Cost tier stratification separates heritage-qualified analog components from emerging digital architectures competing on processing density.
- Analog:Radiation-hardened power management integrated circuits and sensor signal conditioning circuits with proven flight heritage. Toulouse-based suppliers maintain captive foundry relationships for discrete component fabrication.
- Digital:Reconfigurable FPGAs and onboard data processing units enabling real-time Earth observation analytics. Paris-Saclay deep-tech startups are expanding fastest as AI edge computing requirements displace legacy architectures.
- RF:Solid-state power amplifiers, frequency converters, and low-noise receivers for payload communications chains.
- Microwave:Millimeter-wave components for high-throughput satellite links and synthetic aperture radar systems.
Heritage analog commands institutional procurement volumes. Digital segments are climbing the fastest as constellation operators prioritize onboard autonomy.
End User:
Customer type fragmentation splits between sovereign procurement with domestic content quotas and commercial operators optimizing unit economics.
- Government Agencies:CNES, ESA, and EU Space Programme institutional missions with mandated geographical return and cybersecurity certification tiers from Direction Générale de l'Armement.
- Commercial Operators:Constellation deployers and satellite service providers batch-procuring avionics for medium Earth orbit networks.
- Research Institutions:University laboratories and CNRS units accessing technology demonstrator funding for novel component validation.
- Defense:Military satellite programs with additional supply chain sovereignty constraints and encrypted communications requirements.
Institutional agencies anchor procurement volumes. Commercial operators are gaining share fastest as Earth observation constellations scale production.
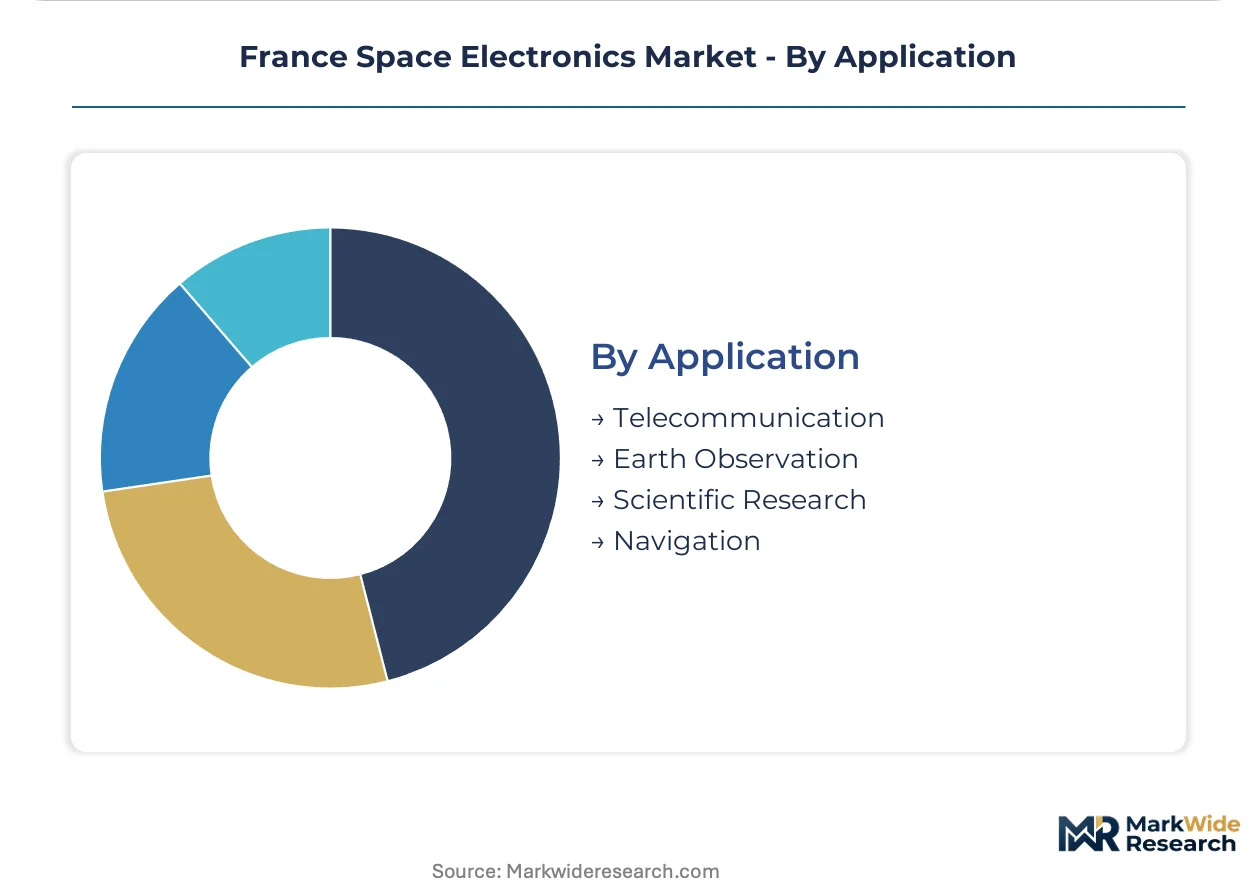
Application:
Application maturity varies across mission types, with telecommunications commanding established margins and Earth observation driving architectural innovation.
- Telecommunication:Geostationary payload electronics for broadcast and broadband services, with prime contractors integrating transponder chains and antenna control systems at Cannes facilities.
- Earth Observation:Optical and radar payload processors, onboard storage, and high-speed downlink electronics for Copernicus expansion and defense surveillance constellations.
- Scientific Research:Deep-space instrumentation, planetary probe avionics, and astrophysics payload electronics with extreme radiation tolerance requirements.
- Navigation:Atomic clock interfaces, signal generation units, and integrity monitoring systems for Galileo constellation sustainment.
Telecommunication sustains revenue concentration. Earth observation represents the steepest expansion trajectory as multi-satellite deployments accelerate batch procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Toulouse aerospace cluster anchors French space electronics procurement, concentrating prime contractor integration facilities and radiation-hardened component suppliers within a 50-kilometer corridor. This concentration shapes subcontractor access patterns across satellite bus and payload electronics manufacturing.
Île-de-France
Paris-Saclay deep-tech incubators cultivate fabless semiconductor startups targeting radiation-tolerant power management for constellation applications. ANSM and CNIL cybersecurity frameworks impose data protection requirements on ground segment electronics developed in this corridor. The plateau's research institutions channel EU Horizon funding toward novel component validation for Earth observation payloads.
Provence-Alpes-Côte d'Azur
Cannes facilities concentrate payload electronics integration for geostationary telecommunications satellites under Thales Alenia Space manufacturing operations. Direction Générale de l'Armement procurement regulations mandate domestic sourcing quotas for defense-destined RF subsystems produced along this coastline. The region's specialized workforce sustains heritage-qualified analog component fabrication for long-duration missions.
Auvergne-Rhône-Alpes
Grenoble's semiconductor ecosystem supplies radiation-hardened power management integrated circuits to Toulouse prime contractors. STMicroelectronics leverages captive foundry relationships in this region for discrete component fabrication meeting CNES mission assurance protocols. The cluster's materials science capabilities support thermal cycling qualification for components operating between minus 150 and plus 120 degrees Celsius.
Nouvelle-Aquitaine
Bordeaux-area ground stations and mission control infrastructure drive demand for antenna control systems and signal processors. The region hosts satellite operations centers supporting Copernicus expansion and defense surveillance constellations. Local engineering firms specialize in telemetry and command electronics for medium Earth orbit networks.
France Space Electronics Market Competitive Landscape
Consolidated procurement frameworks dominate the current landscape, replacing discrete component purchasing with subsystem-level vendor partnerships. Prime contractors bundle avionics, power management, and RF units under single-source qualification agreements, compressing the vendor base around institutional satellite programs. Two strategic archetypes occupy distinct positions: vertically integrated aerospace conglomerates controlling end-to-end platform electronics, and specialized component suppliers capturing margin pools in radiation-hardened semiconductors. Competitive moves concentrate on strategic partnerships for sovereign supply chain compliance and capacity expansion for batch-produced constellation avionics.
Among France-based prime contractors, Thales Alenia Space and Airbus occupy positions exemplifying the integrated platform archetype, anchoring payload electronics integration across CNES and ESA institutional programs. Safran represents the specialized systems tier, competing through propulsion and power management architectures for geostationary missions. These three entities sit within a procurement environment where risk-sharing contracts and geographical return requirements reshape subcontractor access across the domestic value chain.
| Leading Market Players |
|---|
| Thales Alenia Space |
| Airbus |
| Thales Group |
| STMicroelectronics |
| ArianeGroup |
| OHB SE |
| Honeywell International |
| BAE Systems |
| Safran |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed prime contractors anchor procurement discipline across the Toulouse-Cannes corridor, channeling ESA geographical return requirements into long-term qualification agreements that compress price competition for radiation-hardened components. This ownership pattern tightens margin pools around institutional satellite programs while elevating cybersecurity certification costs for defense-destined electronics.
Pricing Analysis
Prime contractor direct-to-CNES contracting eliminates distributor margins, concentrating price negotiation power within consolidated subsystem vendor partnerships. Pricing stratifies across heritage-qualified analog components, reconfigurable digital architectures, and RF subsystems with mission-specific radiation tolerance tiers. Cost compression in batch-procured constellation avionics is intensifying because small satellite operators adopt commercial-off-the-shelf alternatives with orbital redundancy. Commercial operators exhibit highest price sensitivity, while Direction Générale de l'Armement-mandated defense programs tolerate premium qualification costs.
Supply Chain Analysis
Specialty freight for radiation-hardened semiconductor wafers from United States and legacy European foundries elevates landed costs for Toulouse prime contractors. Supply draws from Taiwan for advanced packaging, Germany for precision RF components, and domestic Auvergne-Rhône-Alpes facilities for power management integrated circuits. Single-source vulnerability concentrates at rad-hard wafer foundries subject to ITAR export controls. Distribution runs through ArianeGroup's Les Mureaux and Vernon facilities with ANSM traceability requirements for launch vehicle electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in France space electronics rests on sovereign supply chain localization reducing ITAR-dependent input costs, alongside premium-tier shift toward onboard AI processing architectures commanding higher unit values.
For Market Incumbents: Acquire radiation effects engineering talent pools to counter generational scarcity threatening single-event upset mitigation capabilities. Consolidate fabless semiconductor startups in the Paris-Saclay corridor to secure captive power management supply. Threat from emerging AI edge computing specialists demands backward integration into reconfigurable FPGA architectures. For New Entrants and Emerging Players: Begin with onboard AI processing subsystems for Earth observation constellations, the most penetrable white-space segment displacing legacy digital architectures. Target Paris-Saclay deep-tech incubators for partnership access to CNES technology demonstrator funding. Go-to-market angle: sovereign content compliance bundled with cybersecurity certification tiers. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component suppliers facing prime contractor consolidation pressure rather than integrated platform players. Long-term viability favors radiation-hardened semiconductor specialists with captive foundry relationships across the analysis window. Signal to watch: EU Space Programme funding allocations for IRIS² and Copernicus expansion reshaping subcontractor access.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Radiation-Hardened Semiconductor Specialist | Secures captive foundry capacity for CNES mission assurance protocols. |
| Paris-Saclay Deep-Tech Incubator Partnership | Channels EU Horizon funding toward novel component validation. |
| Onboard AI Processing Architecture Launch | Captures unpenetrated demand from French defense and climate agencies. |
| Ariane 6 Supply Chain Integration | Locks in ANSM traceability requirements for launch vehicle electronics. |
| Green Propulsion-Electric Thruster Convergence | Opens payload mass optimization for geostationary mission contracts. |
Research Methodology
Bottom-up satellite platform modeling reconciled against top-down radiation-hardened component supply tracking forms the analytical core of this study. Primary interviews with payload integration engineers at Thales Alenia Space and Airbus, procurement officers at CNES, radiation effects specialists at STMicroelectronics, and program managers at Direction Générale de l'Armement combined with secondary validation. ESA procurement databases, CNES mission assurance protocols, EU Space Programme budget allocations, and ANSM regulatory filings provided triangulation anchors.
Input-output matrices mapped avionics, power management, and RF subsystem demand against foundry capacity and qualification timeline constraints across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end user category, and application mission. CAGRs derived from satellite constellation deployment schedules and institutional procurement cycle analysis. Industry-specific inputs incorporated Ariane 6 production ramp and IRIS² funding trajectory assumptions.
Caveats apply where ITAR licensing delays, wafer supply concentration, or qualification timeline friction could materially shift the outlook. Forecasts reflect documented assumptions about sovereign supply chain mandates and ESA geographical return enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Europe Space Logistics Market
Space
Space Transportation Market
Space
Rocket Launchpad Market
Space
Near Space Robotics Market
Space
Private Space Travel Market
Space
Space Mobile Service Market
Space
US Reusable Launch Vehicle Market
Space
South Korea Space Electronics Market
Space
US Space Launch Services Market
Space
Space Blanket Market
Space
Germany Space Electronics Market
Space
India Space Electronics Market
Space
China Space Propulsion System Market
Space
Mexico Space Electronics Market
Space
Space Burial Service Market
Space
China Space Electronics Market