
 Aircraft Computers Market | 2026-2036
Aircraft Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Computers Market Analysis
Market Context
Silicon carbide is broadening thermal management economics in engine control units as legacy silicon substrates face power-density limitations. BAE Systems leverages captive semiconductor packaging capabilities to secure military avionics contracts. Honeywell International Inc. anchors its position through integrated flight management systems that span commercial and business aviation platforms. Thales Group competes aggressively in avionics displays, particularly for narrow-body retrofit programs across European carriers.
Technical Definition and Segment Structure
Aircraft computers are hardened electronic systems engineered to operate across temperature extremes from minus 55 to 125 degrees Celsius, executing flight-critical algorithms for navigation, propulsion management, and sensor fusion in real-time. Their primary purpose is to reduce pilot workload while enhancing situational awareness and system reliability during all flight phases. Flight Management Systems generate the deepest margin pools due to software recurring revenue and upgrade cycles, while Unmanned Aerial Vehicles represent the fastest-expanding application as autonomous platforms proliferate in both defense and commercial surveillance roles. Engine Control Units remain structurally mature, with replacement demand tied to airframe longevity rather than fleet expansion.
Regulatory Framework and Outlook
FAA certification under DO-178C and DO-254 governs software and hardware assurance levels, while EASA's CS-25 airworthiness codes enforce equivalent rigor for European-registered platforms. China's CAAC and its GB standards are raising localization requirements for avionics content on domestically assembled airframes. Stakeholders must monitor divergence between FAA and EASA cybersecurity annexes, as incompatible mandates could fragment supplier development roadmaps and certification budgets.
Market Dynamics
DO-178C certification mandates are compressing supplier qualification timelines while concentrating procurement among vertically integrated avionics houses with captive software assurance capabilities.
Growth Catalysts
- Flight deck digitization:Commercial carriers are retrofitting narrow-body fleets with integrated avionics suites to reduce pilot workload and enable single-pilot operations during cruise phases.
- FAA Part 25 airworthiness mandates:Updated certification requirements for synthetic vision systems are forcing fleet-wide hardware refreshes across US-registered commercial aircraft.
- Silicon carbide substrates:Power electronics in engine control units are migrating to wide-bandgap semiconductors that tolerate higher thermal loads than legacy silicon.
Market Restraints
- DO-178C compliance costs:Software verification for Level A criticality consumes 60-80% of development budgets and extends program timelines by 18-24 months.
- Semiconductor foundry concentration:Military-grade packaging capacity clusters in US Department of Defense-trusted facilities with limited surge capacity.
- Legacy airframe longevity:Engine control unit replacement cycles stretch beyond 25 years, capping fleet expansion-driven demand.
Strategic Opportunities
- Unmanned aerial platforms:Autonomous cargo drones and surveillance systems require fault-tolerant computing architectures without crewed-system redundancy overhead.
- China's GB standard localization:CAAC airworthiness requirements for domestically assembled COMAC airframes mandate local avionics content sourcing.
- Model-based systems engineering:DO-178C Tool Qualification is automating verification workflows and compressing certification timelines for new entrants.
Industry Challenges
- DO-254 hardware assurance expertise:FPGA verification engineers with aerospace safety-critical experience command 40% salary premiums over commercial semiconductor roles.
- Legacy MIL-STD-1553 integration:New flight computers must bridge obsolete databus protocols with modern ARINC 664 Ethernet backbones.
Report Scope
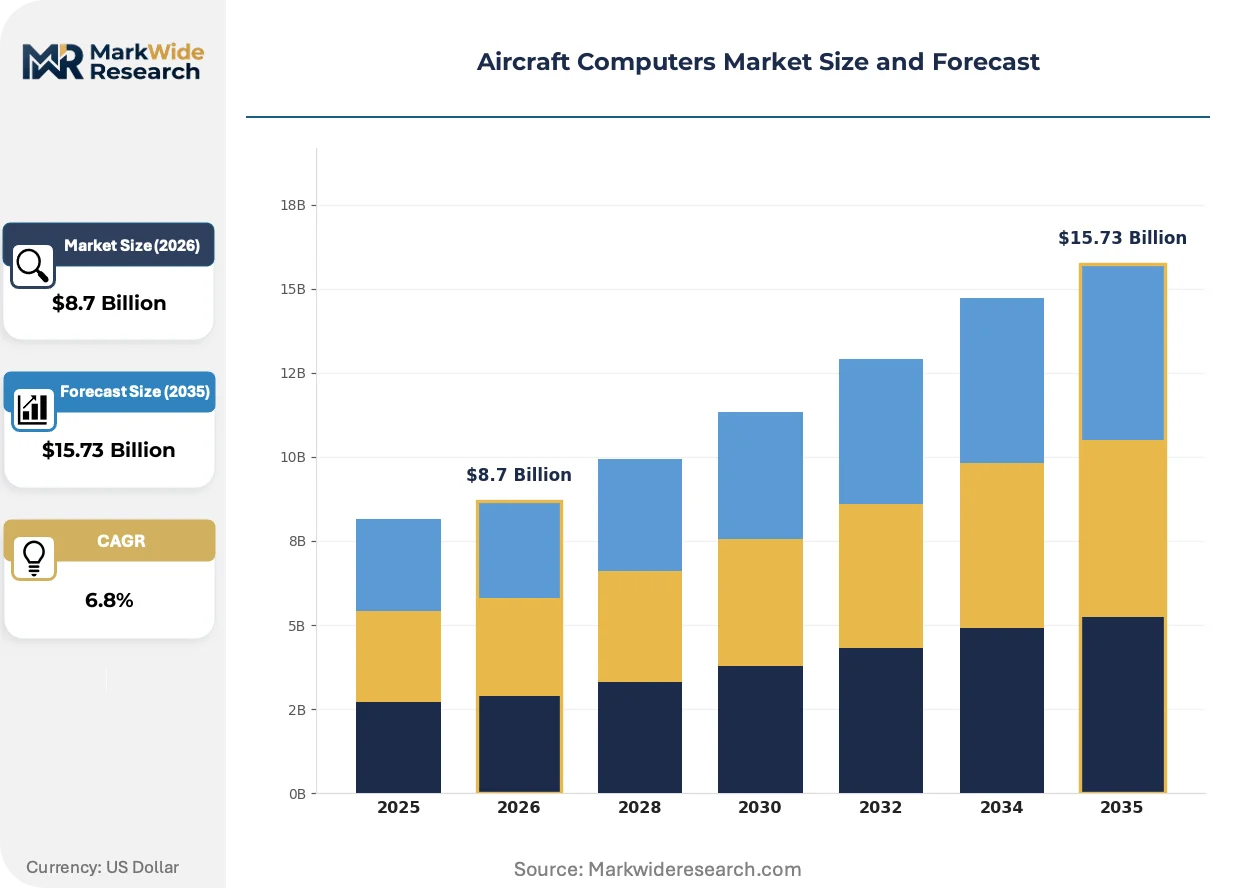
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Computers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Management Systems, Engine Control Units, Data Acquisition Systems, Avionics Displays Application: Commercial Aviation, Military Aviation, Business Aviation, Unmanned Aerial Vehicles Technology: Integrated Circuits, Microprocessors, FPGA, Digital Signal Processors End User: Aerospace Manufacturers, Airlines, Military Operators, Maintenance Providers |
| Companies Covered | BAE Systems, Safran SA, Honeywell International Inc., Collins Aerospace, Curtiss-Wright Corporation, Raytheon Technologies, GE Aerospace, L3Harris Technologies, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Computers Market Emerging Trajectories
Embedded artificial intelligence is penetrating flight-critical systems, forcing revisions to deterministic computing architectures that have governed avionics design for four decades.
Neuromorphic computing architectures are automating sensor fusion workloads that previously required dedicated digital signal processors. Business jet manufacturers are piloting these systems for predictive turbulence detection. The technology is automating real-time decision loops that human pilots previously executed during instrument approach transitions.
EASA's CS-25 cybersecurity annexes are mandating air-gap verification for safety-critical networks. Hardware suppliers must demonstrate intrusion resistance through formal methods. European narrow-body retrofit programs are absorbing 15-20% non-recurring engineering premiums to satisfy these requirements.
Airlines are unbundling avionics upgrade cycles from heavy maintenance checks. Power-by-the-hour contracts now specify minimum computing capability thresholds rather than hardware refresh schedules. This pattern is most pronounced among US ultra-low-cost carriers operating leased narrow-body fleets.
Aircraft Computers Market Segmentation
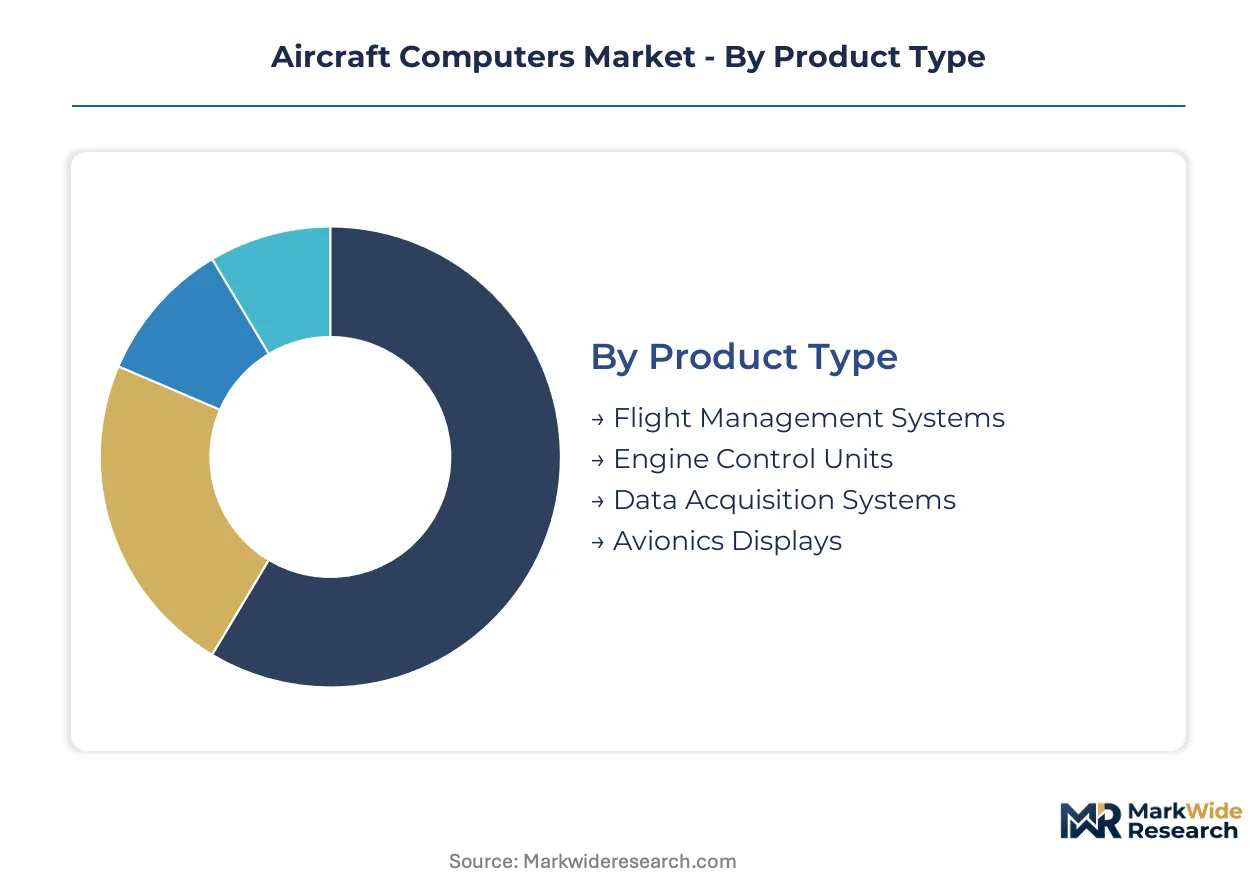
Segmentation in aircraft computers reveals how certification burdens concentrate procurement among suppliers with captive software assurance capabilities. Each dimension exposes different margin structures and qualification thresholds that shape competitive positioning across commercial and defense platforms.
Product Type:
DO-178C Level A certification governs flight-critical systems with the most stringent verification requirements, while Level C and D approvals suffice for monitoring and display functions. Hardware assurance under DO-254 adds FPGA-specific validation costs that vary dramatically by computational complexity.
- Flight Management Systems:These integrated platforms combine navigation databases, performance optimization algorithms, and autopilot interface logic in certified hardware. Demand concentrates in narrow-body retrofit programs across US ultra-low-cost carriers seeking single-pilot cruise capabilities. Recurring software revenue and mandatory upgrade cycles generate the deepest margin pools in the product portfolio.
- Engine Control Units:Full-authority digital engine controllers execute real-time fuel scheduling and thrust management across temperature extremes from minus 55 to 125 degrees Celsius. Replacement demand tracks airframe longevity rather than fleet expansion, with silicon carbide substrates displacing legacy silicon for thermal management in next-generation turbofan applications.
- Data Acquisition Systems:Distributed sensor interfaces aggregate airframe health monitoring and flight recorder inputs for centralized processing.
- Avionics Displays:Primary flight and multifunction displays require DO-178C Level B certification for primary flight information presentation.
Leading the category by volume: Engine Control Units. Growing fastest: Flight Management Systems.
Application:
Military programs demand MIL-STD-810 environmental qualification and MIL-STD-1553 databus compatibility alongside civilian certification, doubling non-recurring engineering overhead. Commercial platforms prioritize ARINC 664 Ethernet backbone integration and weight reduction for fuel efficiency.
- Unmanned Aerial Vehicles:Autonomous cargo drones and surveillance platforms eliminate crewed-system redundancy overhead while requiring fault-tolerant architectures for beyond-visual-line-of-sight operations. Defense modernization programs in the United States sustain procurement volumes for tactical unmanned systems with swappable mission computer payloads.
- Commercial Aviation:Narrow-body and wide-body fleets drive integrated avionics suite procurement for flight deck digitization and synthetic vision mandates.
- Military Aviation:Fighter and transport platforms require hardened computing for electronic warfare and mission management in contested electromagnetic environments.
- Business Aviation:Corporate jet manufacturers pilot neuromorphic computing for predictive turbulence detection and automated approach transitions.
Dominating procurement value: Commercial Aviation. Expanding most quickly: Unmanned Aerial Vehicles.
Technology:
Semiconductor substrate selection determines thermal envelope, radiation tolerance, and power density tradeoffs that cascade through system architecture decisions. Military-grade packaging capacity constraints in US Department of Defense-trusted foundries limit supplier options for highest-reliability applications.
- FPGA:Field-programmable gate arrays enable hardware reconfiguration for evolving mission profiles without board-level redesign. FPGA verification engineers with aerospace safety-critical experience command substantial salary premiums over commercial semiconductor roles, concentrating development among vertically integrated avionics houses with captive expertise.
- Integrated Circuits:Application-specific standard products deliver deterministic performance for well-defined avionics functions with established qualification heritage.
- Microprocessors:General-purpose computing cores execute operating system-hosted applications under ARINC 653 partitioning constraints.
- Digital Signal Processors:Dedicated arithmetic units accelerate sensor fusion and radar processing workloads in real-time signal chains.
Highest certification overhead: FPGA. Gaining adoption fastest: Integrated Circuits with silicon carbide substrates.
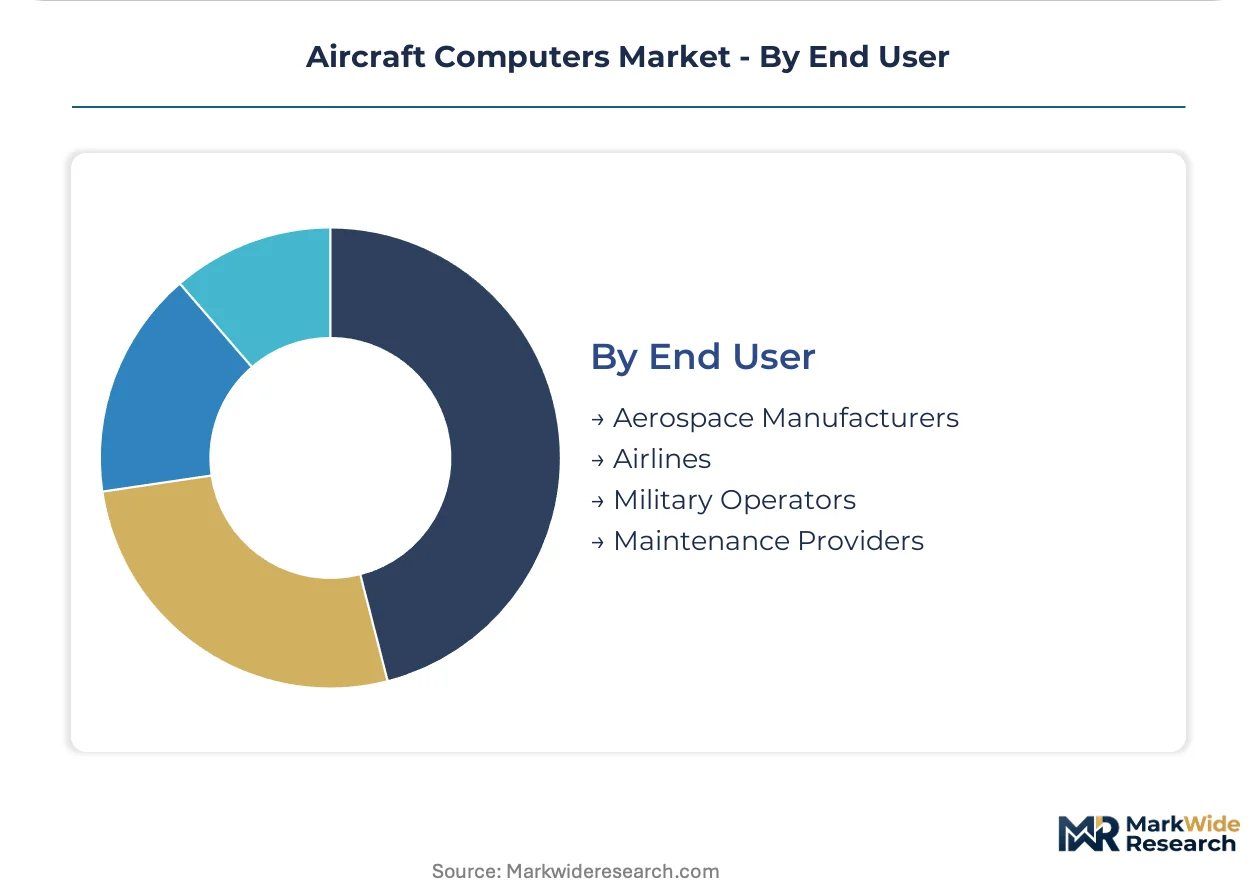
End User:
Procurement authority fragmentation across OEM airframe contracts, airline fleet management, and military program offices creates multiple sales cycles with divergent technical requirements and contracting timelines. Power-by-the-hour service models are shifting hardware refresh accountability from operators to manufacturers.
- Aerospace Manufacturers:Boeing and Airbus supply chain integration demands line-fit avionics with guaranteed production ramp support and long-term obsolescence management. These OEM relationships anchor volume procurement through multi-year platform contracts with embedded upgrade provisions.
- Airlines:Leased narrow-body operators unbundle avionics refresh cycles from heavy maintenance checks, specifying minimum computing capability thresholds in power-by-the-hour contracts.
- Military Operators:Defense agencies mandate MIL-STD compliance and cybersecurity hardening through formal verification methods.
- Maintenance Providers:Third-party repair stations manage post-warranty support and obsolescence mitigation for aging fleet segments.
Controlling largest procurement volume: Aerospace Manufacturers. Shifting contractual terms most rapidly: Airlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates where airframe assembly and defense modernization programs overlap. Boeing's supply chain in the United States, COMAC's domestic content mandates in China, and Airbus's European supplier networks shape regional demand patterns.
United States
Boeing's 737 MAX and 777X production lines sustain flight management system procurement volumes. FAA DO-178C certification mandates tighten supplier qualification for synthetic vision retrofits. Greater Seattle anchors avionics engineering clusters serving both commercial and military platforms.
China
COMAC C919 deliveries accelerate domestic avionics content requirements under CAAC GB standards. The country's national aviation regulator mandates localization thresholds for flight-critical systems. Yangtze River Delta manufacturing bases host captive semiconductor packaging for engine control units.
France
Airbus final assembly lines in Toulouse concentrate flight deck integration demand. EASA CS-25 cybersecurity annexes impose formal verification requirements on narrow-body retrofit programs. Île-de-France hosts Thales Group avionics engineering for European carrier fleets.
Germany
Lufthansa Group fleet modernization drives engine control unit replacement cycles. The country's federal aviation authority enforces EASA-equivalent software assurance for aftermarket installations. Bavaria's precision electronics corridor supplies FPGA verification expertise to Tier-1 avionics houses.
United Kingdom
Royal Air Force Tempest program sustains military computing procurement for next-generation fighter platforms. The UK's Civil Aviation Authority maintains harmonized certification pathways with EASA post-Brexit. BAE Systems' Lancashire engineering centers anchor defense avionics development.
Aircraft Computers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. Vertically integrated avionics houses with captive software assurance capabilities capture flight management system contracts, while component specialists supply FPGA and power electronics to multiple Tier-1 integrators. Three archetypes dominate: full-system integrators, semiconductor packaging specialists, and software certification houses. Consolidation concentrates procurement authority among aerospace conglomerates, while partnerships with trusted foundries secure military-grade packaging capacity.
Among transatlantic system integrators, BAE Systems exemplifies the defense-focused archetype with captive semiconductor capabilities. Honeywell International Inc. and Thales Group occupy positions spanning commercial flight management and military mission computing. These three entities represent contrasting geographic anchors for procurement—UK-based defense specialization, US commercial-military crossover, and European avionics display leadership.
| Leading Market Players |
|---|
| BAE Systems |
| Safran SA |
| Honeywell International Inc. |
| Collins Aerospace |
| Curtiss-Wright Corporation |
| Raytheon Technologies |
| GE Aerospace |
| L3Harris Technologies |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
DO-178C certification mandates for Level A criticality are forcing airlines and OEMs to consolidate procurement among vertically integrated avionics houses with captive software assurance capabilities, compressing supplier margins and concentrating pricing power among qualified incumbents.
Pricing Analysis
Volume procurement of engine control units generates thin commodity margins, while flight management systems command substantial software recurring revenue premiums. Three-tier pricing structure across DO-178C Level A, Level B, and Level C certification grades separates mission-critical from monitoring functions. Cost compression in Level A verification is intensifying because 60-80% of development budgets now flow to software assurance. Airlines operating power-by-the-hour contracts exhibit highest price sensitivity, whereas military program offices prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Boeing and Airbus mandate multi-supplier qualification for flight-critical systems, fragmenting procurement across captive semiconductor packaging facilities in the United States, United Kingdom, and France. Military-grade substrate production draws from gallium nitride foundries in the United States, silicon carbide wafer suppliers in Germany, and legacy silicon packaging in Japan. Single-source vulnerability concentrates in US Department of Defense-trusted foundries with constrained surge capacity. Distribution runs through OEM line-fit contracts and aftermarket retrofit channels serving narrow-body fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as DO-178C compliance costs eliminate subscale competitors unable to sustain 18-24 month certification timelines.
For Market Incumbents: Hedge against FPGA verification engineer scarcity by building captive semiconductor packaging capabilities in US Department of Defense-trusted facilities. Acquire software certification houses with DO-178C Tool Qualification expertise to compress competitor timelines. BAE Systems' defense-focused model and Honeywell's commercial-military crossover demonstrate viable consolidation archetypes. For New Entrants and Emerging Players: Tier-2 avionics integrators represent the most penetrable channel for neuromorphic computing pilots in business aviation turbulence detection. Target unmanned aerial vehicle mission computer payloads where crewed-system redundancy overhead does not apply. Partner with Chinese COMAC supply chain participants to satisfy CAAC GB localization mandates for C919 avionics content. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive DO-254 hardware assurance capabilities before FAA-EASA cybersecurity annex divergence fragments certification budgets. Acquisition targets should demonstrate military-grade packaging relationships and ARINC 664 Ethernet backbone integration expertise. Watch for EASA CS-25 cybersecurity annex implementation as inflection indicator for European retrofit program premiums.| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Tool Qualification Investment | Automates verification workflows, compressing certification timelines for new flight management system entrants. |
| Silicon Carbide Packaging Scale-Up | Enables thermal management in next-generation engine control units for high-bypass turbofan applications. |
| Neuromorphic Computing Pilot Programs | Positions suppliers for predictive turbulence detection contracts with Gulfstream and Bombardier platforms. |
| CAAC Localization Partnerships | Secures avionics content mandates for COMAC C919 deliveries under GB standard requirements. |
| Military-Grade Foundry Access Agreements | Guarantees packaging capacity for MIL-STD-810 qualified mission computers in contested electromagnetic environments. |
Methodological Framework
SEC 10-K filings, FAA certification databases, and EASA CS-25 airworthiness directives formed the secondary backbone for supplier qualification mapping and regulatory timeline analysis. Primary interviews with avionics program managers, DO-178C certification engineers, airline fleet procurement directors, and military acquisition officers validated software assurance cost structures and retrofit demand patterns. Bottom-up triangulation across flight management system upgrade cycles and top-down validation against Boeing and Airbus delivery schedules anchored volume estimates across the analysis window.
Historical trendline analysis of narrow-body fleet age distributions and engine control unit replacement patterns informed the projection framework. Segmentation dimensions modeled include product type certification level, application platform class, semiconductor substrate technology, and end-user procurement authority. CAGRs derived from weighted average of OEM line-fit contracts, aftermarket retrofit schedules, and defense modernization program announcements. Industry-specific inputs encompassed DO-178C compliance cost inflation and silicon carbide substrate adoption curves in next-generation turbofan applications.
Caveats apply where FAA-EASA cybersecurity annex divergence or CAAC localization mandate acceleration could materially shift the outlook. Forecasts reflect assumptions regarding Boeing 737 MAX and 777X production ramp stability, COMAC C919 delivery trajectory, and military-grade foundry capacity expansion. Deviation in DO-178C Level A verification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Display for Avionics Application Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Military Avionic Systems Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Aerospace Avionics Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Aircraft EMI Shielding Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Customized Avionic Systems Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Global Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Military Aircraft Avionics Market