
 Carrier Rocket Market | 2026-2036
Carrier Rocket Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier Rocket Market Analysis
The gap between premium orbital-class systems and commodity small-lift vehicles is expanding. SpaceX leverages full-stack vertical integration to sustain cost leadership on large payloads. Rocket Lab specializes in dedicated small-satellite launches, occupying a distinct tier below heavy-lift competitors.
A carrier rocket is a launch vehicle designed to propel payloads from Earth's surface into orbit or beyond, typically employing staged propulsion with liquid or solid propellants and thrust-to-weight ratios exceeding 1.2 at liftoff. Its primary commercial purpose is deploying satellites, crewed spacecraft, and interplanetary probes for government and private customers. Reusable rocket types now command the strongest margin pools as refurbishment economics improve, while super heavy payload capacity represents the fastest-growing segment driven by lunar and deep-space missions. Government agencies remain the most concentrated market participant category by contract value, though private enterprises are gaining share in launch manifests.
FAA licensing governs commercial launch operations in the United States, while ESA member states coordinate through national space agencies under EU space policy frameworks. China's SAMR and military-civil fusion protocols shape market access for non-domestic suppliers. Stakeholders must track how ITAR export controls and emerging national security space classifications reshape supplier eligibility and cross-border component flows.
Market Dynamics
Reusable first-stage recovery technology is compressing launch economics and redrawing competitive boundaries between heavy-lift and small-satellite operators.
Growth Catalysts
- Satellite constellation deployment:Commercial telecom operators are accelerating procurement cycles for dedicated orbital slots, creating sustained demand for reliable launch cadence.
- FAA commercial licensing:Streamlined approval pathways for reusable vehicle operations are reducing time-to-manifest for domestic operators.
- Staged propulsion advances:Improved liquid oxygen-kerosene engine cycles are extending vehicle reuse intervals and lowering refurbishment costs.
Market Restraints
- Supply concentration in titanium alloys:Russian and Chinese dominance in aerospace-grade titanium sponge creates input cost volatility for nozzle and tank fabrication.
- ITAR export controls:US State Department restrictions on propulsion component transfers limit supplier eligibility for cross-border launch service contracts.
- Range capacity limits:Eastern and western US launch ranges face scheduling bottlenecks that constrain annual manifest growth regardless of vehicle availability.
Strategic Opportunities
- India's emerging launch sector:ISRO's commercial arm and private entrants are building capacity for polar and sun-synchronous orbits at cost points below incumbent providers.
- Lunar logistics services:Artemis program cargo requirements are opening dedicated super-heavy payload contracts for cis-lunar transfer missions.
- Green propellant mandates:ESA member state requirements for reduced-toxicity alternatives to hydrazine are creating first-mover advantages for compliant engine developers.
Industry Challenges
- Turbopump manufacturing expertise:The specialized welding and precision machining skills required for high-pressure oxygen-rich staged combustion remain concentrated at a handful of facilities.
- Flight termination system certification:Range safety approvals for autonomous flight safety systems involve multi-year validation campaigns that delay new vehicle introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrier Rocket Market |
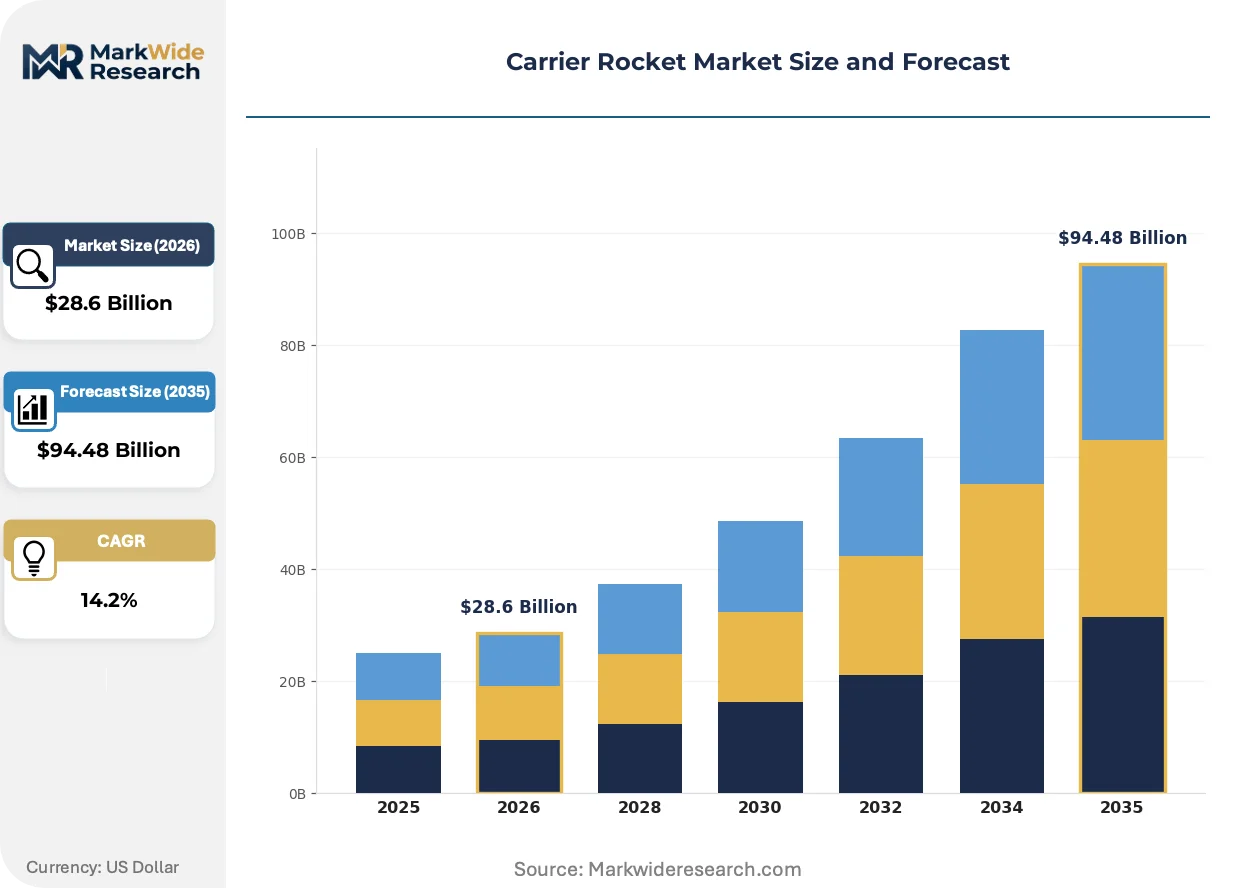
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rocket Type: Reusable, Expendable, Suborbital, Orbital Payload Capacity: Small, Medium, Large, Super Heavy Launch Site: Coastal, Inland, Spaceports, Mobile Platforms Market Participant: Government Agencies, Private Enterprises, International Organizations, Startups |
| Companies Covered | SpaceX, Rocket Lab, Arianespace, Lockheed Martin, Northrop Grumman, Mitsubishi Heavy Industries, United Launch Alliance, Blue Origin, China Aerospace Science and Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier Rocket Market Emerging Trajectories
Propulsion architecture, regulatory frameworks, and procurement patterns are undergoing simultaneous transformation across the carrier rocket sector.
Additive manufacturing is converging with regeneratively cooled chamber design. SpaceX and Rocket Lab are adopting selective laser melting for copper-alloy thrust chamber components, reducing part count and lead time. This convergence is compressing development cycles for engine iterations and enabling rapid design-to-test pipelines.
China's SAMR oversight of military-civil fusion protocols is tightening market access for non-domestic suppliers. Foreign component flows into Chinese launch vehicle supply chains face enhanced scrutiny and domestic substitution requirements. European and US suppliers are responding by redirecting investment toward India and Southeast Asian partnership structures.
Launch service contracting is consolidating around multi-manifest block buys. Satellite operators are trading price premiums for guaranteed slot access, displacing spot-market transactions. This pattern is most visible in US low Earth orbit constellation deployments, where anchor tenants secure multi-year capacity reservations.
Carrier Rocket Market Segmentation
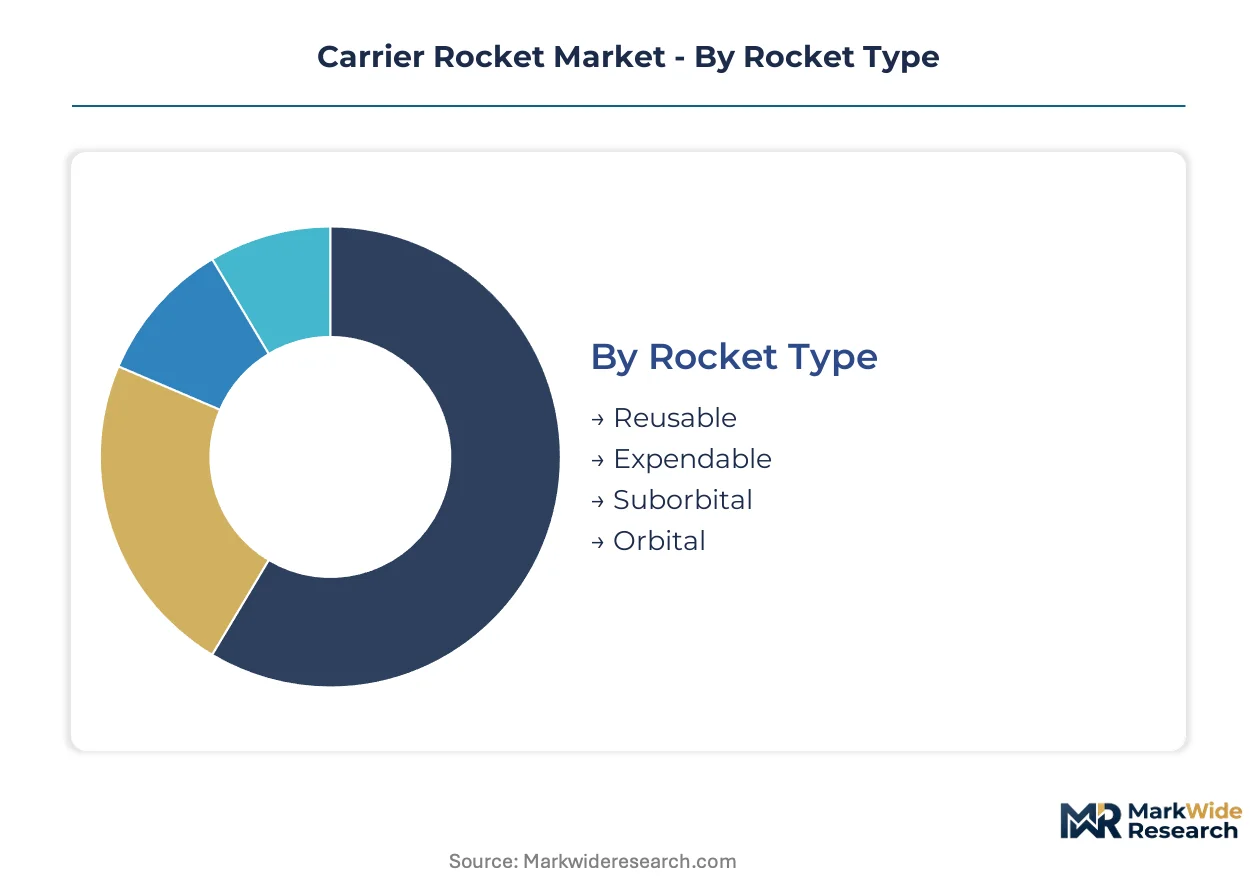
Segmentation in the carrier rocket market reveals how supply chain specialization and customer procurement patterns create distinct competitive arenas. Each dimension exposes different margin structures and barriers to entry that shape vendor positioning.
Rocket Type:
Supply concentration in engine turbopump manufacturing and first-stage recovery systems determines which rocket architectures achieve viable production economics.
- Reusable:First-stage recovery with vertical landing or drone ship capture enables multiple flight cycles per vehicle. Demand concentrates in United States constellation deployments where SpaceX and Blue Origin anchor manifests, driven by per-launch cost compression below expendable alternatives.
- Expendable:Single-use architectures dominate heritage government missions and heavy geostationary payloads where mass margins preclude recovery hardware. Procurement persists at United Launch Alliance and Arianespace for national security and interplanetary science missions where reliability certification outweighs cost optimization.
- Suborbital:Brief trajectory vehicles for research, tourism, and hypersonic testing. Virgin Galactic and Blue Origin New Shepard serve this tier with reduced regulatory burden compared to orbital licensing.
- Orbital:Minimum energy-to-orbit designs required for satellite deployment and crewed missions. ISRO and Rocket Lab specialize in dedicated small-lift orbital services for polar and sun-synchronous insertions.
Today's leader: Reusable. Tomorrow's challenger: Suborbital.
Payload Capacity:
Cost tier stratification separates commodity small-lift services from premium super-heavy contracts with distinct qualification requirements and customer relationships.
- Small:Under 2,000 kg to low Earth orbit, typically serving CubeSat and microsatellite operators. Rocket Lab Electron and ISRO PSLV capture dedicated procurement from commercial Earth observation constellations in India and United States, constrained by range slot availability at coastal facilities.
- Medium:2,000-20,000 kg class serving replenishment of medium Earth orbit navigation and communication assets. Arianespace Soyuz and SpaceX Falcon 9 in expendable configuration compete here for European and North American anchor tenants.
- Large:20,000-50,000 kg for geostationary communication satellites and deep-space probes. United Launch Alliance Atlas V and Delta IV Heavy maintain certified manifests for NASA and Department of Defense missions requiring specific orbital inclinations.
- Super Heavy:Exceeding 50,000 kg for lunar logistics, Mars cargo, and next-generation space stations. SpaceX Starship and NASA Space Launch System are gaining share fastest in Artemis program procurement with multi-year block buy structures.
Super heavy capacity commands the steepest expansion trajectory as lunar infrastructure timelines accelerate.
Launch Site:
Geography of range infrastructure dictates propellant logistics, flight path constraints, and regulatory jurisdiction for manifest access.
- Coastal:Eastern and western United States ranges at Cape Canaveral and Vandenberg host the majority of commercial orbital launches with over-ocean flight corridors. FAA licensing governs operations with streamlined pathways for reusable vehicle approvals.
- Inland:Baikonur Cosmodrome and China's Jiuquan and Taiyuan centers support polar and high-inclination missions with reduced maritime recovery complexity. Russian and Chinese military-civil fusion protocols restrict foreign supplier participation.
- Spaceports:Purpose-built commercial facilities including Spaceport America and UK's SaxaVord seek to capture polar launch demand with reduced range congestion. Regulatory frameworks remain under development at emerging sites.
- Mobile Platforms:Sea Launch and China's maritime platforms enable equatorial access without fixed infrastructure investment. Operational complexity limits adoption to specialized geostationary insertion contracts.
Coastal sites dominate current volume. Spaceports represent the fastest-climbing site category as range capacity constraints intensify.
Market Participant:
Customer type segmentation reveals how procurement authority and risk tolerance shape contract structures and vendor selection criteria.
- Government Agencies:NASA, Department of Defense, ESA, and national space agencies concentrate contract value through cost-plus and fixed-price mechanisms. ITAR and national security classifications limit supplier pools for sensitive missions.
- Private Enterprises:Commercial satellite operators and telecom constellations drive procurement volume through multi-manifest block buys. SpaceX and Amazon's Project Kuiper anchor demand with multi-year capacity reservations.
- International Organizations:Multilateral science missions and climate monitoring consortia aggregate funding across member states. ESA Earth observation programs and World Meteorological Organization satellite coordination exemplify this tier.
- Startups:Venture-backed launch vehicle developers and niche payload integrators seek to displace incumbents on cost or responsiveness. Regulatory capital requirements and flight termination system certification timelines constrain market entry velocity.
Private enterprises are displacing government agencies as the volume anchor. Startups face the steepest certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States launch manifests outpace European procurement volumes by a factor of three, while China's state-directed program accelerates cadence through military-civil fusion protocols. National regulatory frameworks and range infrastructure determine market access trajectories across major rocket-producing economies.
United States
FAA commercial licensing and Cape Canaveral range capacity anchor the heaviest launch volumes globally. The FAA streamlined reusable vehicle approval pathways in 2020, compressing time-to-manifest for domestic operators. SpaceX and United Launch Alliance concentrate activity in Florida and California coastal corridors, with Vandenberg Space Force Base hosting polar orbit insertions for Earth observation constellations.
China
SAMR oversight of military-civil fusion protocols restricts foreign supplier participation in launch vehicle supply chains. The national regulator mandates domestic substitution requirements for critical propulsion components under enhanced scrutiny regimes. Jiuquan and Taiyuan launch centers in inland provinces support high-inclination missions with reduced maritime recovery complexity compared to coastal alternatives.
India
ISRO's commercial arm and private entrants are building capacity for polar and sun-synchronous orbits at cost points below incumbent providers. The country's national space agency coordinates with the Department of Space to license private launch operations under emerging commercial frameworks. Sriharikota spaceport on India's eastern coast hosts the majority of orbital missions, with new facilities planned for Tamil Nadu to expand range capacity.
France
ESA member state requirements for reduced-toxicity propellants are creating first-mover advantages for compliant engine developers serving European institutional customers. The French national space agency CNES coordinates launch service procurement through multilateral frameworks at the Guiana Space Centre. Kourou's equatorial location provides energy advantages for geostationary insertions that northern European sites cannot match.
Japan
METI industrial policy directs public-private partnerships in next-generation propulsion development, with specific focus on reusable engine architectures. The Tanegashima Space Center in Kagoshima Prefecture handles the majority of orbital launches, while the Uchinoura Space Center supports suborbital and small-satellite missions. Mitsubishi Heavy Industries anchors domestic manufacturing in Nagoya industrial corridors with precision machining capabilities for turbopump components.
Carrier Rocket Market Vendor Landscape
Top-tier vendors anchor heavy-lift and super-heavy segments, while mid-tier specialists occupy dedicated small-satellite niches with differentiated service models. The vendor base stratifies across three functional tiers: full-stack vertically integrated operators, component-specialized fabricators, and emerging launch service disruptors. Two dominant competitive moves are reshaping positioning: multi-year block buy contracting that locks in manifest capacity, and backward integration into propulsion component manufacturing to capture margin pools.
Among US-based operators, SpaceX and United Launch Alliance exemplify contrasting strategic archetypes within the same regulatory jurisdiction. SpaceX represents full-stack vertical integration with reusable first-stage recovery, while United Launch Alliance occupies the certified reliability tier for national security missions. Rocket Lab, a US-incorporated specialist with New Zealand launch infrastructure, anchors the dedicated small-lift segment through rapid cadence and responsive scheduling.
| Leading Market Players |
|---|
| SpaceX |
| Rocket Lab |
| Arianespace |
| Lockheed Martin |
| Northrop Grumman |
| Mitsubishi Heavy Industries |
| United Launch Alliance |
| Blue Origin |
| China Aerospace Science and Technology Corporation |
| Others |
Supply Flow & Price Mechanics
Titanium alloy sponge from Russian and Chinese smelters flows through nozzle fabrication and tank welding stages before reaching launch vehicle integrators, with aerospace-grade material costs cascading into super-heavy payload premiums and small-lift commodity pricing tiers.
Pricing Analysis
Capacity additions in India and the United States are reshaping price floors for dedicated small-satellite launches. Pricing stratifies across premium super-heavy, standard medium-to-heavy, and economy small-lift tiers, with differentiation driven by payload certification grade and volume scale commitments. Cost compression in small-lift services is intensifying because ISRO and emerging private entrants undercut incumbent spot-market rates. Commercial constellation operators exhibit highest price sensitivity through multi-manifest block buy negotiations, while government agencies prioritize reliability certification over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for flight-critical turbopumps and thrust chamber assemblies mandate multi-supplier qualification at SpaceX, United Launch Alliance, and Arianespace. Manufacturing concentrates in the United States, France, and Japan for precision-machined components and regeneratively cooled chamber fabrication. The supply chain draws from titanium sponge, high-pressure oxygen-rich combustion alloys, and copper-alloy additive manufacturing feedstock. Single-source vulnerability persists in specialized welding expertise for turbopump housings. Distribution runs through prime contractor vertical integration with captive engine production and tiered subcontractor networks for structural assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carrier rocket market compounds steadily as satellite constellation deployment creates predictable procurement cadence across government and commercial manifests.
For Market Incumbents: Anchor manifest share through multi-year block buy structures that lock in anchor tenants like Amazon's Project Kuiper and Starlink replenishment cycles. Deepen upstream control over turbopump manufacturing capabilities to defend against emerging Indian cost competition. Prioritize FAA certification maintenance for autonomous flight safety systems as range capacity constraints intensify scheduling bottlenecks. For New Entrants and Emerging Players: Begin with polar and sun-synchronous orbit services where range slot availability at Vandenberg and emerging spaceports creates white-space opportunity. Target dedicated small-lift responsiveness for commercial Earth observation constellations underserved by heavy-lift ride-share schedules. Pursue rapid design-to-test pipelines using selective laser melting for copper-alloy thrust chambers as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Consolidation pressure builds where flight termination system certification timelines and range safety validation campaigns create insurmountable barriers for capital-constrained startups. Five-to-ten year viability favors vertically integrated operators with demonstrated reuse economics and government mission certification. Acquisition target archetypes include additive manufacturing specialists for regeneratively cooled chambers and emerging launch service providers with secured range access. Watch for FAA licensing backlog resolution as the signal indicating manifest expansion velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable First-Stage Recovery Scale-Up | SpaceX and Blue Origin compression of per-launch costs below expendable alternatives reshapes competitive boundaries. |
| Multi-Manifest Block Buy Contracting | Amazon's Project Kuiper and Starlink anchor multi-year capacity reservations displacing spot-market transactions. |
| Additive Manufacturing Integration | Selective laser melting adoption at Rocket Lab and SpaceX compresses engine development cycles and lead times. |
| Polar Orbit Capacity Expansion | ISRO and emerging spaceports in Scotland and Alaska capture dedicated small-satellite demand below incumbent pricing. |
| Green Propellant Engine Development | ESA member state hydrazine substitution mandates create first-mover certification advantages for compliant developers. |
Methodological Framework
Multiple input streams — launch manifest databases, propulsion component trade flows, and regulatory filing repositories — were reconciled through structured primary interviews with launch vehicle program managers, FAA licensing officers, satellite constellation procurement leads, and aerospace materials sourcing directors. Secondary validation drew from FAA commercial space launch reports, ESA procurement disclosures, customs records for titanium alloy imports, and SEC filings from publicly traded space infrastructure companies. Bottom-up segment sizing across rocket type, payload capacity, and launch site dimensions was cross-checked against top-down market value reconciliation.
Historical launch cadence trajectories were cross-referenced against panel input from industry stakeholders to model demand elasticity across the projection horizon. Segmentation dimensions included reusable versus expendable architecture, small-to-super-heavy payload tiers, coastal versus inland launch geography, and government versus commercial procurement authority. CAGRs were derived from trend extrapolation adjusted for technology adoption curves and regulatory capacity constraints. Industry-specific forecast inputs incorporated Artemis program cargo requirements, Starlink replenishment schedules, and emerging Indian commercial launch capacity buildout timelines.
Caveats apply where ITAR export control tightening, range safety certification delays, or titanium supply disruption from geopolitical sources could materially shift the outlook. Forecasts reflect modeling assumptions about reuse interval achievement and refurbishment cost trajectories that may diverge from operator execution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
UK Space Propulsion System Market
Space
Space Launch Services Market
Space
France Space Electronics Market
Space
Orbital Spaceflight Market
Space
China Space Electronics Market
Space
Space Radar Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Sensors Market
Space
Space Traffic Management Market
Space
Europe Space Electronics Market
Space
Space Technology (Spacetech) Market
Space
Space Management Solutions Market
Space
Space Blanket Market
Space
Space-Based Solar Power Market
Space
Asia-Pacific Space Logistics Market
Space
LAMEA Space As a Service Market