
 Space Robotics Market | 2026-2036
Space Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Space Robotics Market Analysis
On-orbit servicing revenue is reconfiguring margin pools away from pure manufacturing toward lifecycle support contracts. Lockheed Martin Corporation leverages its deep heritage in satellite assembly to anchor long-term maintenance agreements. Northrop Grumman Corporation sustains competitive position through backward integration into rendezvous and proximity operations sensors. MDA Space specializes in robotic arm architectures that dominate government procurement channels for orbital infrastructure.
Space robotics encompasses electromechanical systems engineered for extraterrestrial manipulation, traversal, and servicing under vacuum, radiation, and thermal cycling conditions, typically operating with positional accuracy below one millimeter for delicate capture tasks. These systems execute satellite repair, debris removal, planetary surface operations, and cargo logistics in environments where human presence remains impractical or prohibitively costly. Satellite Servicing commands the largest current revenue pool as aging orbital fleets require life-extension interventions, while Lunar Exploration represents the fastest-expanding application category driven by Artemis program timelines and commercial lander competitions. Autonomous Navigation technology absorbs disproportionate R&D investment as operators seek to reduce ground-control overhead for deep-mission scenarios.
NASA safety standards and FAA launch licensing requirements shape product development timelines and qualification protocols for commercial space robotics vendors seeking domestic market access. ESA's Clean Space initiative and evolving debris mitigation guidelines from ISO create additional compliance layers for systems targeting European procurement channels or international collaborative missions. Stakeholders must weigh certification investment against the strategic value of multi-agency program eligibility as customer concentration risk intensifies among a handful of national space agencies and prime contractors.
Market Dynamics
Autonomous navigation capabilities are compressing mission timelines and reducing ground-control dependencies for deep-space operations, fundamentally restructuring how operators budget for lifecycle support.
Growth Catalysts
- Artemis program timelines:NASA's accelerated lunar return schedule is generating procurement demand for surface mobility systems and sample handling equipment.
- REACH debris mitigation:European regulatory pressure on orbital sustainability is mandating end-of-life servicing capabilities for satellite operators targeting ESA procurement channels.
- AI-enabled proximity operations:Machine vision advances are reducing sensor payload mass while improving capture precision for rendezvous missions.
Market Restraints
- Radiation-hardened electronics supply:Concentrated fabrication capacity in legacy semiconductor foundries creates single-source vulnerability for critical computing components.
- FAA launch licensing:Extended qualification timelines for novel robotic payloads delay revenue recognition and compress development budgets.
- Human astronaut capability:Continued ISS operations and emerging commercial human spaceflight retain certain servicing tasks that robotics cannot economically displace.
Strategic Opportunities
- Cislunar logistics infrastructure:Gateway station construction creates demand for external robotics and cargo handling systems through 2030.
- ISO 24113 debris compliance:International standardization of post-mission disposal requirements positions servicing providers for multi-agency contracts.
- Terrestrial analog testing:Desert and arctic simulation facilities are emerging as revenue streams for technology validation prior to flight qualification.
Industry Challenges
- Embedded software certification:NASA's Class B software standards impose documentation burdens that extend development cycles by 18-24 months.
- Precision mechanism supply:Limited domestic capacity for harmonic drives and cryogenic actuators forces reliance on Japanese and German component sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Robotics Market |
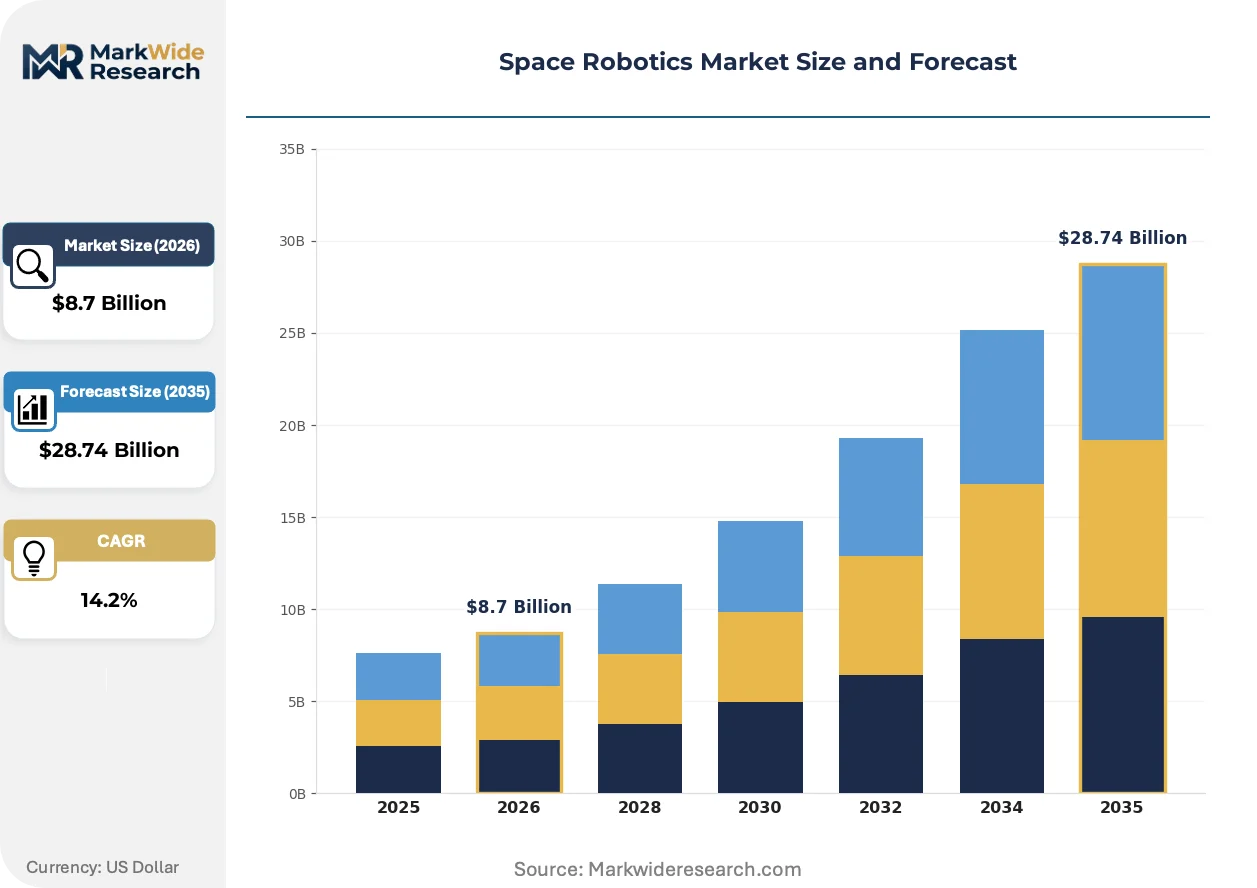
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Satellite Servicing, Lunar Exploration, Planetary Rovers, Cargo Delivery Technology: Autonomous Navigation, Robotic Arms, AI Algorithms, Communication Systems End User: Government Agencies, Commercial Operators, Research Institutions, Defense Contractors Service Type: Launch Services, Maintenance Services, Data Analysis, System Integration |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, SpaceX, MDA Space, Astrobotic Technology, Astroscale Holdings, Maxar Technologies, Honeybee Robotics, Motiv Space Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Robotics Market Emerging Trajectories
Flight heritage requirements are loosening for certain orbital applications, allowing commercial operators to field newer architectures without decade-long validation cycles previously mandated by government primes.
Machine learning-based trajectory planning is hybridizing with classical orbital mechanics to enable real-time collision avoidance during proximity operations. Commercial servicing ventures are adopting these architectures for geostationary satellite life-extension missions. The approach compresses ground-segment staffing requirements while expanding the addressable market to smaller satellite operators previously excluded by control-center costs.
ESA's Clean Space initiative is tightening debris mitigation guidelines for systems seeking European procurement eligibility. Manufacturers must now demonstrate passive deorbiting capability or active removal compatibility in preliminary design reviews. Lunar exploration platforms face the most stringent new requirements, forcing redesign of propulsion architectures for missions targeting ESA co-funding.
Service contract unbundling is separating hardware procurement from multi-year operational support. Defense and intelligence agencies are leading this transition, awarding discrete task orders for on-orbit repair rather than bundled system purchases. The United States exhibits the most advanced procurement sophistication, with NASA's Tipping Point program explicitly structuring agreements around milestone-based payments contingent on orbital demonstration success.
Space Robotics Market Segmentation
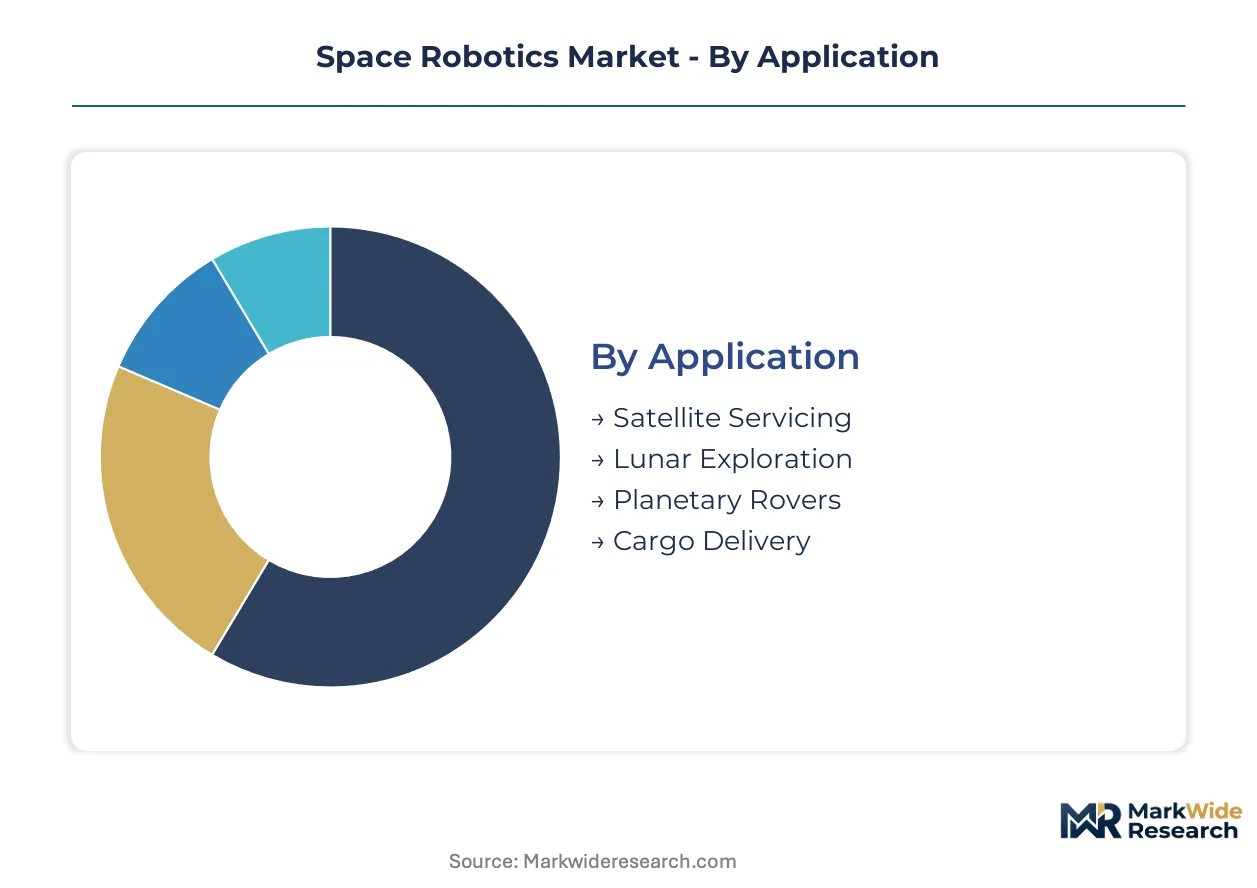
Space robotics segmentation reveals divergent investment cycles across applications and technologies. Procurement patterns vary from rapid-turnover AI software iterations to decade-long hardware qualification programs.
Application:
Satellite Servicing contracts turn over fastest with recurring orbital missions, while Planetary Rovers demand decade-long development cycles before revenue recognition.
- Satellite Servicing:Electromechanical systems execute orbital repair, refueling, and life-extension maneuvers on aging geostationary fleets. NASA and ESA procurement channels in the United States and France concentrate demand as agencies relax heritage requirements for commercial operators.
- Lunar Exploration:Surface mobility platforms and sample handling equipment support Artemis program timelines. Artemis-driven procurement from the United States government absorbs disproportionate capital allocation as commercial lander competitions accelerate fielding schedules.
- Planetary Rovers:Long-traverse vehicles with autonomous hazard avoidance for Mars and outer planet missions. ESA co-funded missions impose stringent Clean Space deorbiting requirements on propulsion architectures.
- Cargo Delivery:Pressurized and unpressurized logistics modules for orbital and cislunar transport. Gateway station construction through 2030 generates discrete procurement windows for external handling systems.
Satellite Servicing dominates installed base. Lunar Exploration is where expansion concentrates.
Technology:
Cost tiers separate mass-producible software stacks from radiation-hardened hardware requiring foundry qualification.
- Autonomous Navigation:Machine vision and trajectory planning algorithms enable real-time collision avoidance during proximity operations. Ground-control overhead reduction drives adoption by smaller satellite operators previously excluded by staffing costs.
- Robotic Arms:Multi-degree-of-freedom manipulators with sub-millimeter positional accuracy for delicate capture tasks. Government procurement channels for orbital infrastructure concentrate demand around MDA Space architectures.
- AI Algorithms:Embedded inference engines for sensor fusion and decision-making under communication latency. NASA Class B software standards impose documentation burdens extending development cycles substantially.
- Communication Systems:Cross-link and ground-relay hardware for deep-space telemetry. Concentrated fabrication capacity in legacy semiconductor foundries creates single-source vulnerability for critical computing components.
Robotic Arms dominate installed base. Autonomous Navigation is climbing the fastest.
End User:
Customer type determines contract structure, with government agencies demanding milestone-based payments and commercial operators seeking operational leases.
- Government Agencies:NASA, ESA, and national space agencies fund technology demonstration missions with extended qualification protocols. FAA launch licensing requirements shape product development timelines for domestic market access.
- Commercial Operators:Satellite fleet owners and servicing ventures purchase lifecycle support contracts separate from hardware procurement. The United States exhibits the most advanced procurement sophistication with milestone-based Tipping Point agreements.
- Research Institutions:Universities and laboratories access flight heritage through piggyback payload arrangements. Terrestrial analog testing facilities generate revenue streams for technology validation prior to qualification.
- Defense Contractors:Intelligence agencies award discrete task orders for on-orbit repair rather than bundled system purchases. Service contract unbundling separates hardware procurement from multi-year operational support.
Government Agencies dominate installed base. Commercial Operators is where expansion concentrates.
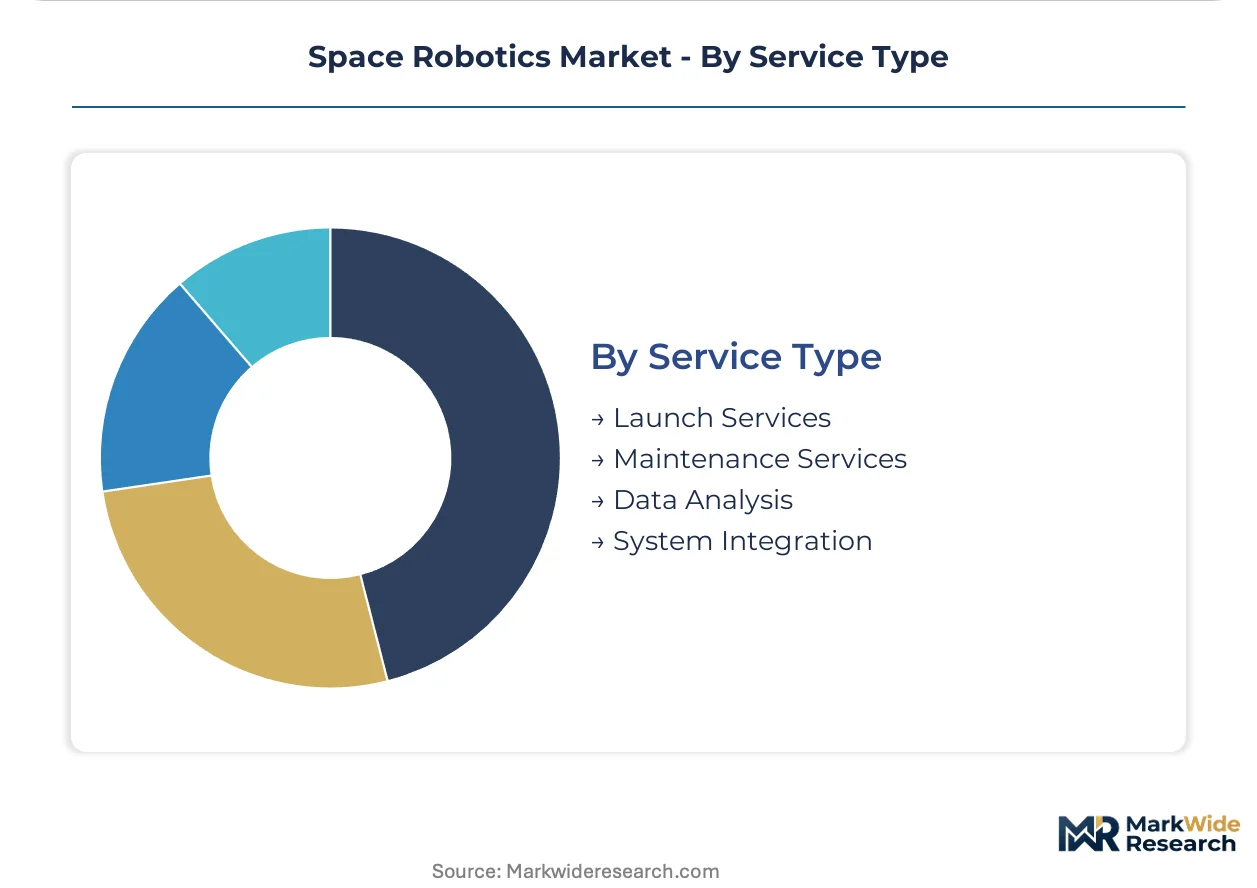
Service Type:
Margin pools shift from one-time launch events toward recurring maintenance and data revenues.
- Launch Services:Payload integration and orbital insertion for robotic systems. FAA extended qualification timelines for novel robotic payloads delay revenue recognition and compress development budgets.
- Maintenance Services:On-orbit repair, software updates, and hardware replacement over extended operational lifecycles. Lockheed Martin leverages satellite assembly heritage to anchor long-term maintenance agreements.
- Data Analysis:Telemetry processing and scientific payload interpretation. Machine learning-based approaches hybridize with classical orbital mechanics to reduce ground-segment staffing requirements.
- System Integration:End-to-end assembly of robotic platforms from subsystems and components. Limited domestic capacity for harmonic drives and cryogenic actuators forces reliance on Japanese and German sources.
Launch Services dominate installed base. Maintenance Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States channels procurement through milestone-based government contracts, while European demand embeds sustainability compliance deeper into design requirements. Japan and emerging space nations prioritize technology validation through terrestrial analog facilities rather than orbital demonstration.
United States
NASA's Tipping Point program and Artemis-driven surface mobility procurement absorb the largest capital allocation. FAA launch licensing requirements shape product development timelines for commercial operators seeking domestic market access. Houston's Johnson Space Center and Denver's satellite manufacturing corridor concentrate prime contractor engineering activity.
France
ESA co-funded missions and Clean Space debris mitigation mandates drive demand for end-of-life servicing capabilities. REACH regulatory pressure on orbital sustainability forces redesign of propulsion architectures for European procurement eligibility. Toulouse's aerospace cluster hosts the agency's technical center and prime contractor integration facilities.
Germany
Precision mechanism supply chains for harmonic drives and cryogenic actuators anchor industrial capability despite limited domestic final assembly. National space agency co-funding for lunar exploration platforms imposes stringent documentation burdens under ISO debris standards. Munich and Bremen house subsystem specialists serving pan-European programs.
Japan
Terrestrial analog testing facilities in desert and arctic environments generate revenue streams for technology validation prior to flight qualification. METI industrial policy supports autonomous navigation R&D for deep-space missions with communication latency challenges. Tsukuba's space center coordinates public-private partnerships for orbital robotics demonstration.
United Kingdom
Defense and intelligence agencies lead service contract unbundling, awarding discrete task orders for on-orbit repair separate from bundled system purchases. Satellite servicing ventures headquartered in London seek operational leases rather than milestone-based government payments. Harwell's space cluster aggregates venture-stage companies targeting commercial procurement channels.
Space Robotics Market Vendor Landscape
Capability concentration sits with heritage-rich system integrators; scale advantage sits with commercial launch operators repurposing terrestrial manufacturing. The market structures around three tiers: prime contractors anchoring long-term maintenance agreements, mid-size specialists dominating robotic arm procurement, and venture-backed entrants fielding AI-enabled proximity operations. Competitive moves center on backward integration into sensor payloads and unbundling of service contracts from hardware sales.
Within the heritage prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify established positioning through satellite assembly lineage and rendezvous sensor integration. MDA Space occupies a distinct specialist position in robotic arm architectures for government orbital infrastructure programs.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| SpaceX |
| MDA Space |
| Astrobotic Technology |
| Astroscale Holdings |
| Maxar Technologies |
| Honeybee Robotics |
| Motiv Space Systems |
| Others |
Supply Flow & Price Mechanics
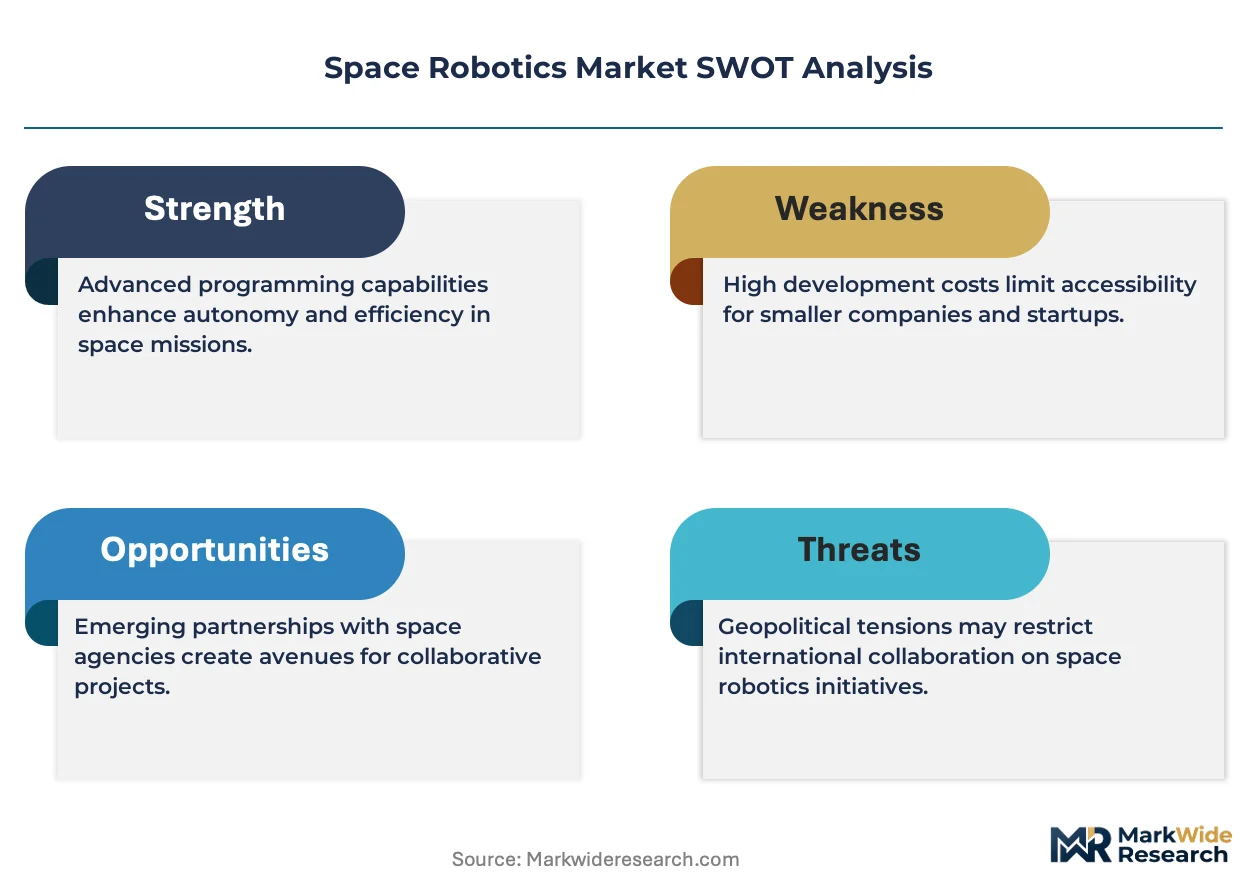
Single-source vulnerability in radiation-hardened semiconductor foundries determines both the three-tier pricing structure across premium, standard, and economy certification levels and the geographic concentration of upstream supply. NASA Class B software standards and FAA launch licensing create regulatory chokepoints that compress margin pools for commercial operators while amplifying pricing power for heritage primes with established qualification pathways.
Pricing Analysis
Long-term lifecycle support contracts dominate procurement structures, separating hardware acquisition from multi-year maintenance agreements. Price differentiation rests on flight heritage certification tier and after-sales service bundling, with government agencies least sensitive due to milestone-based payment structures. Cost compression in commercial operator segments is intensifying because ESA Clean Space compliance adds qualification overhead. Smaller satellite operators exhibit highest price sensitivity, driving demand for autonomous navigation solutions that reduce ground-control staffing.
Supply Chain Analysis
Export-control regimes under ITAR and EAR restrict flows of precision navigation sensors and rendezvous proximity technology across national boundaries. Manufacturing concentrates in the United States, Germany, and Japan for harmonic drives and cryogenic actuators. Raw material dependencies include radiation-hardened substrates, specialty alloys for vacuum-rated mechanisms, and high-reliability connectors. Single-source vulnerability in legacy semiconductor foundries threatens component availability. Distribution runs through prime contractor integration facilities co-located with NASA centers and ESA technical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Space robotics occupies an early-cycle expansion position as Artemis program timelines accelerate procurement velocity for lunar surface systems and cislunar logistics infrastructure.
For Market Incumbents: Entrench competitive position through backward integration into rendezvous sensor payloads and anchoring long-term maintenance agreements separate from hardware sales. Threat vectors include AI-enabled proximity operations ventures unbundling service contracts and REACH debris mitigation mandates forcing propulsion architecture redesigns. Priority levers center on captive supply of radiation-hardened computing components and certification investment for multi-agency program eligibility. For New Entrants and Emerging Players: Pursue terrestrial analog testing facilities as revenue-generating validation pathways prior to orbital qualification, targeting commercial operators previously excluded by ground-control costs. The most penetrable white space sits in autonomous navigation software for smaller satellite operators. A direct go-to-market angle leverages milestone-based payment structures modeled on NASA Tipping Point agreements to reduce customer capital commitment. For Investors and Strategic Acquirers: The market sits at a technology-demonstration phase that favors specialist firms with flight heritage in robotic arm architectures and proximity operations sensors. Long-term viability over the coming decade hinges on positioning for Gateway station construction procurement windows and ISO 24113 debris compliance mandates. The acquisition target archetype combines embedded software capability with demonstrated orbital performance. The signal to watch is ESA co-funding announcements for lunar exploration platforms with stringent Clean Space requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Flight Heritage Acceleration | Reduces decade-long validation cycles for commercial operators seeking NASA procurement eligibility. |
| Backward Integration into Sensors | Captures margin pools in rendezvous proximity technology dominated by Northrop Grumman positioning. |
| Terrestrial Analog Facility Investment | Generates revenue streams for technology validation prior to FAA launch licensing qualification. |
| Service Contract Unbundling | Separates hardware procurement from multi-year maintenance agreements per defense agency procurement shifts. |
| Multi-Agency Certification Investment | Positions servicing providers for ESA Clean Space and NASA Artemis procurement channel access. |
Methodological Framework
Operator-level perspectives from satellite servicing program managers, autonomous navigation engineers, ESA procurement officers, and FAA licensing specialists anchored the qualitative base. Primary interviews combined with secondary validation against NASA Tipping Point award announcements, ESA Clean Space technical documentation, FAA launch license databases, and ISO debris mitigation standards. Bottom-up segment sizing triangulated against top-down agency budget allocation analysis.
Scenario-bracketing around Artemis timeline acceleration and REACH regulatory enforcement variation shaped the analytical framework. Segmentation dimensions modeled include application category, technology type, end-user archetype, and service contract structure across the projection horizon. CAGRs derived from procurement pipeline analysis and technology adoption curve positioning. Industry-specific forecast inputs encompassed satellite fleet age demographics and cislunar infrastructure construction schedules.
Sensitivities concentrate around NASA budget reallocation, ESA co-funding availability, and radiation-hardened electronics supply disruption. Forecasts reflect assumptions on heritage requirement relaxation rates and commercial operator market entry velocity. Material shifts in FAA launch licensing timelines or ITAR export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Lander and Rover Market
Space
Space Frame Market
Space
Space-Based Solar Power Market
Space
Asia-Pacific Space Logistics Market
Space
Space Ground Station Equipment Market
Space
Space Blanket Market
Space
Space Sensors Market
Space
Space As a Service Market
Space
Africa Space Propulsion System Market
Space
Private Space Travel Market
Space
India Aviation, Defense, and Space Market
Space
Carrier Rocket Market
Space
Italy Space Electronics Market
Space
Space Technology (Spacetech) Market
Space
Spain Space Electronics Market
Space
Mexico Space Electronics Market