
 Space Management Solutions Market | 2026-2036
Space Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Space Management Solutions Market Analytics
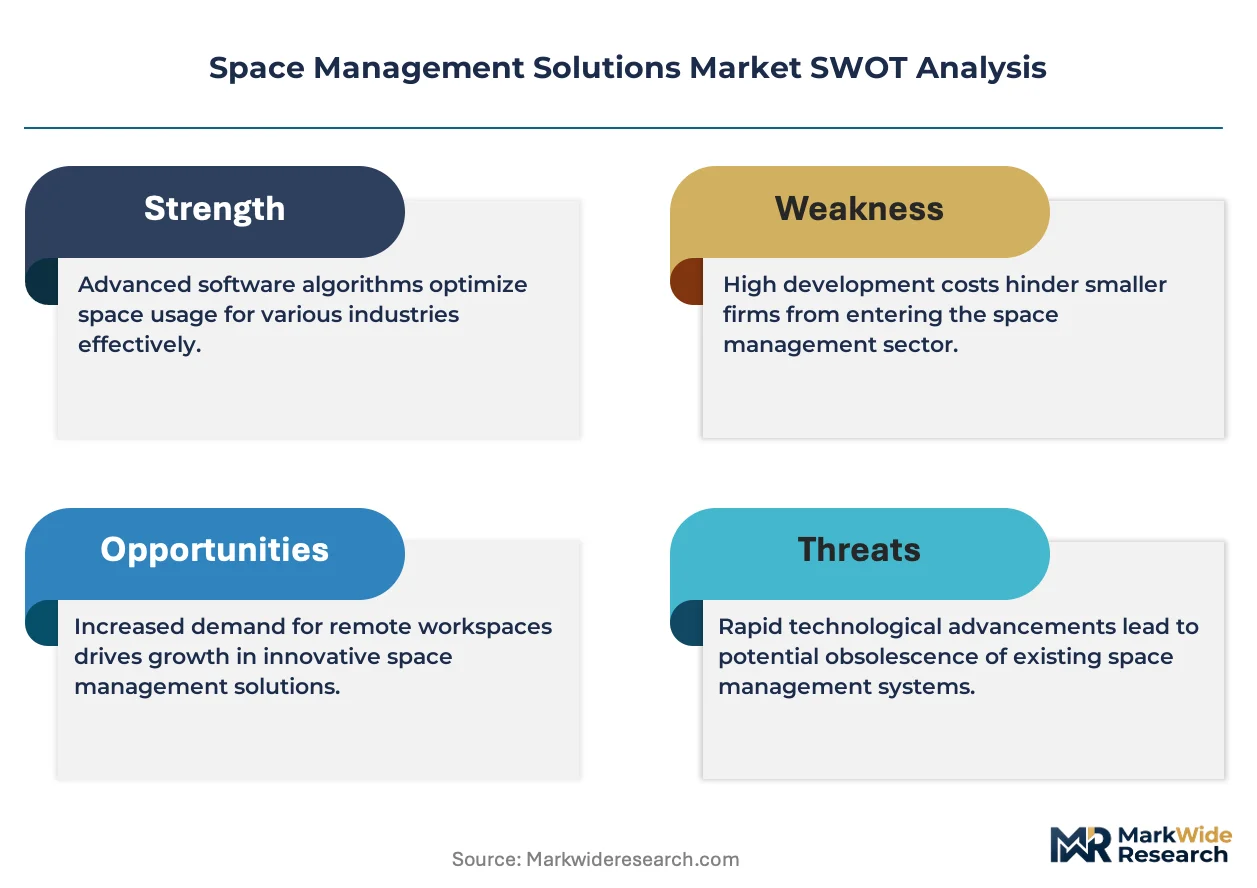
Capital-intensity divergence between cloud-native platforms and legacy on-premise incumbents is redrawing competitive boundaries in space management. Johnson Controls International plc leverages its building automation heritage to anchor integrated hardware-software bundles across commercial portfolios. IBM Corporation sustains enterprise-grade AI analytics capabilities that differentiate its offerings in data-intensive corporate deployments. Eptura Inc competes through specialized cloud platforms targeting mid-market facility operators seeking rapid deployment without infrastructure overhead.
Space management solutions encompass software systems, sensor networks, and analytical tools that measure, visualize, and optimize physical workplace utilization through real-time occupancy tracking and predictive modeling. These solutions integrate IoT sensors, digital twins, and AI-driven analytics to automate space allocation, reduce real estate overhead, and improve employee experience in built environments. Software solutions dominate current revenue pools due to recurring subscription economics, while cloud platforms represent the fastest-expanding segment as organizations abandon on-premise maintenance burdens. IoT sensors command premium pricing in integrated deployments, and consulting services retain margin strength in complex campus transformations where change management determines implementation success.
The U.S. Department of Energy's building efficiency standards and the EU Green Deal's decarbonization mandates for commercial real estate are accelerating sensor deployment and analytics adoption across regulated portfolios. FDA guidelines for healthcare facility spatial workflows and OSHA workplace density requirements further shape product specifications in clinical and industrial settings. Buyers must evaluate vendor interoperability with existing building management systems before committing to platform architectures that will define operational flexibility through the next technology refresh cycle.
Market Dynamics
Hybrid work permanence is compressing corporate real estate footprints while forcing facility managers to justify every square meter through continuous occupancy verification rather than periodic manual audits.
Growth Catalysts
- EU Green Deal decarbonization mandates:Commercial building owners across Germany and France face binding emissions reduction timelines that require granular space utilization data to optimize HVAC cycling and lighting loads.
- IoT sensor cost curves:MEMS-based occupancy detectors and computer vision endpoints have crossed price thresholds enabling wall-to-wall deployment in mid-market office portfolios previously restricted to sampling-based approaches.
- Healthcare facility redesign:FDA spatial workflow guidelines for sterile processing and patient flow are driving hospitals toward real-time location systems integrated with space management platforms.
Market Restraints
- Silicon supply concentration:Advanced sensor fabrication depends on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea, creating procurement vulnerability for integrated hardware-software vendors.
- Legacy system entrenchment:BACnet and Modbus protocol stacks in existing building automation infrastructure resist seamless API integration with cloud-native analytics platforms.
- Data sovereignty friction:GDPR cross-border transfer restrictions and China's data localization requirements complicate multinational deployment architectures for unified space management dashboards.
Strategic Opportunities
- Japan's smart building acceleration:METI's 2025 targets for net-zero commercial structures create immediate demand for predictive occupancy modeling in Tokyo and Osaka financial districts.
- Digital twin convergence:Integration of BIM models with live sensor streams enables simulation-based space reconfiguration before physical moves, opening consulting revenue pools in campus transformations.
- Channel evolution through systems integrators:Schneider Electric and Siemens-certified integration partners are becoming primary procurement paths for mid-market buyers seeking bundled installation and change management.
Industry Challenges
- Interoperability certification delays:BTL (BACnet Testing Laboratories) and WSP (WELL Building Standard) compliance timelines stretch 8-14 months, compressing vendor product roadmaps and customer implementation windows.
- Edge AI deployment complexity:On-premise inference for occupancy pattern recognition requires scarce machine learning operations talent capable of balancing latency, privacy, and model drift in distributed architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Management Solutions Market |
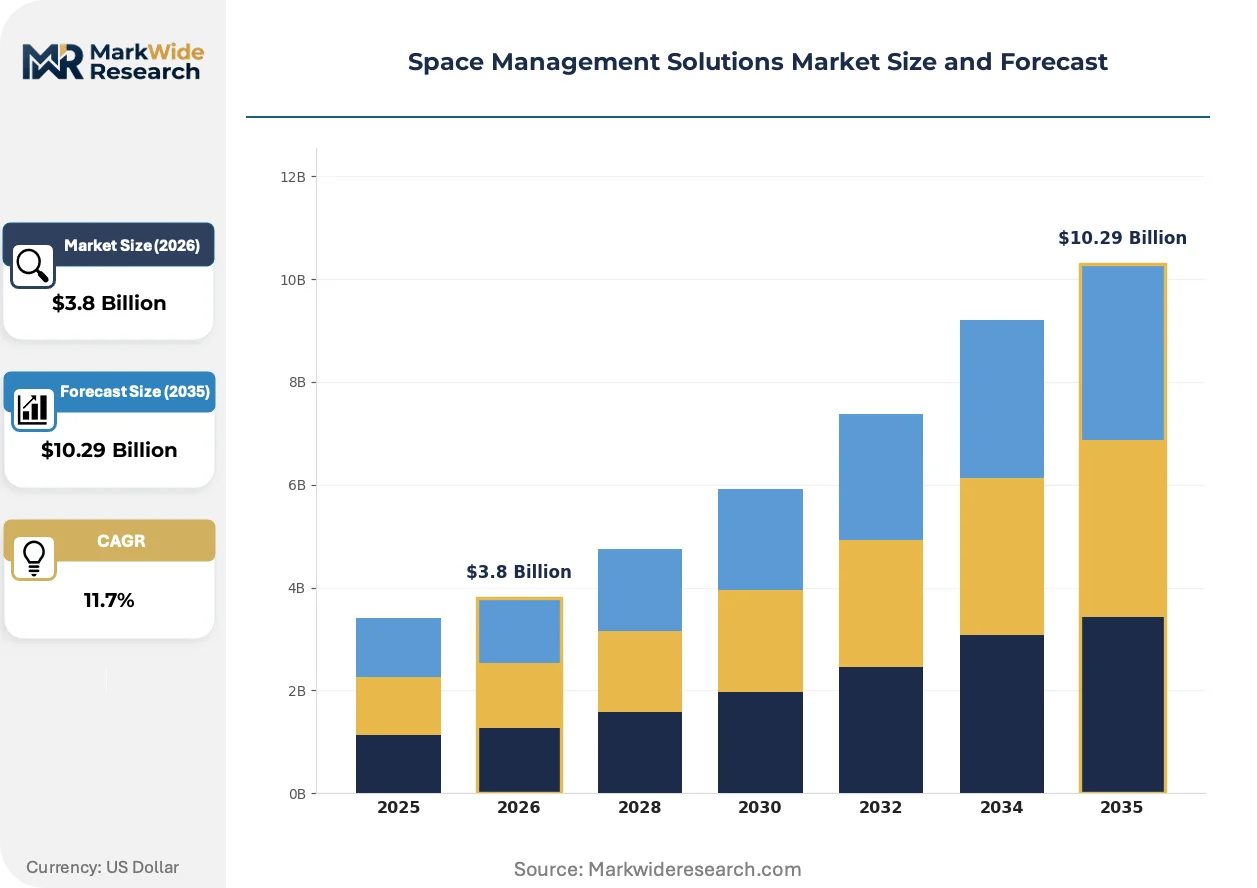
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Consulting Services, Hardware Tools, Cloud Platforms End User: Corporate Offices, Educational Institutions, Retail Spaces, Healthcare Facilities Technology: AI Analytics, IoT Sensors, AR Solutions, 3D Modeling Deployment: On-Premise, Cloud-Based, Hybrid Systems, Mobile Applications |
| Companies Covered | International Business Machines Corporation, Johnson Controls International plc, Trane Technologies plc, Fortive Corporation, Yardi Systems Inc., Nemetschek Group SE, Eptura Inc, Planon Group BV, Accruent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Management Solutions Market Evolving Landscape
Computer vision and depth-sensing modalities are displacing passive infrared as the dominant occupancy detection paradigm, while AI-driven predictive models compress the cycle between data collection and space reconfiguration decisions.
Depth-sensing LiDAR arrays combined with edge-processed computer vision are fragmenting the occupancy sensor market by delivering anonymous people-counting accuracy above 98 percent while eliminating the privacy concerns that stalled camera deployment in European workplaces. Financial services firms in London and Frankfurt are piloting these systems across trading floors where precise density management supports business continuity planning. The technology is fragmenting procurement patterns by forcing buyers to choose between hardware-agnostic software platforms and vertically integrated sensor-analytics bundles.
CSRD disclosure requirements for commercial real estate are mandating granular energy attribution to specific tenant spaces, which in turn requires sub-metering integration with occupancy data to validate efficiency claims. Property managers in the Netherlands and Denmark face immediate compliance deadlines that prioritize vendors with pre-certified sustainability reporting connectors. Industrial warehouse operators are responding fastest by deploying combined environmental and occupancy sensors that feed directly into CSRD-aligned carbon accounting dashboards.
Subscription-based platform pricing is displacing perpetual license models as facility management outsourcing contracts consolidate vendor relationships under integrated service agreements. Corporate real estate departments in the United States are bundling space analytics with cleaning, security, and maintenance spend under single-source providers. This compression is most visible in the technology sector where San Francisco and Seattle headquarters reductions have triggered renegotiation of entire vendor stacks around outcome-based utilization metrics rather than fixed service levels.
Space Management Solutions Market Segmentation
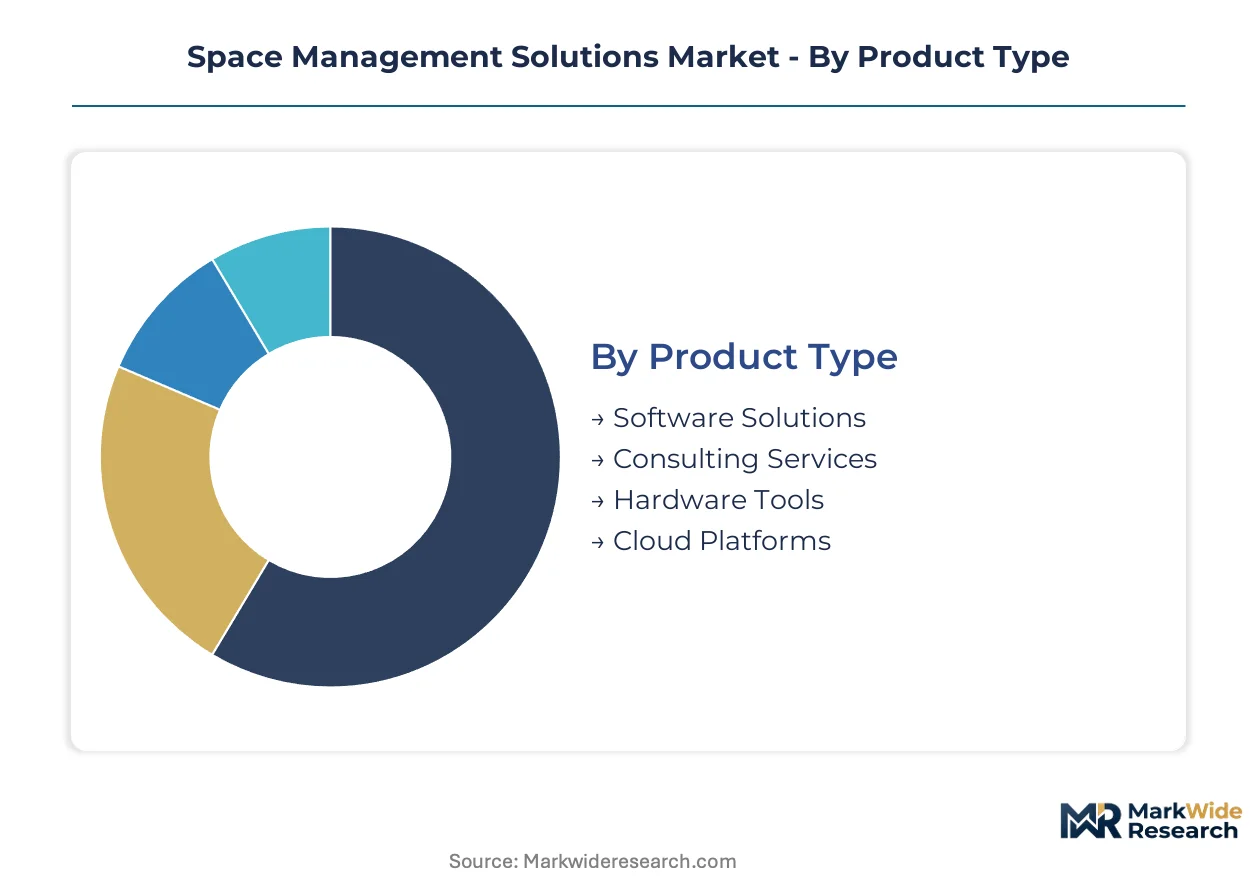
Segmentation in space management solutions reveals how procurement decisions split between capital-intensive infrastructure plays and recurring operational expenditures. Facility managers weigh regulatory compliance timelines against technology refresh cycles when allocating budgets across hardware, software, and service categories.
Product Type:
EU Green Deal disclosure mandates and FDA healthcare facility guidelines create divergent certification burdens across product categories, favoring vendors with pre-certified sustainability reporting connectors.
- Software Solutions:Subscription-based platforms integrate occupancy analytics with building management systems through API architectures. Corporate real estate departments in Germany and France prioritize CSRD-aligned carbon accounting modules to meet binding emissions reduction timelines. Established volume favors software solutions; emerging adoption favors cloud platforms.
- Cloud Platforms:Multi-tenant SaaS architectures eliminate on-premise maintenance overhead while enabling real-time dashboard access across distributed portfolios. Mid-market facility operators in the United States and Japan are consolidating vendor relationships under integrated service agreements that bundle space analytics with maintenance spend.
- Consulting Services:Change management expertise determines implementation success in complex campus transformations involving digital twin integration.
- Hardware Tools:MEMS-based occupancy detectors and depth-sensing LiDAR arrays command premium pricing in integrated deployments requiring wall-to-wall sensor coverage.
Cost tier stratification separates enterprise buyers pursuing bundled hardware-software contracts from mid-market operators seeking rapid SaaS deployment without infrastructure overhead.
End User:
Application intensity varies sharply across built environment types, with healthcare and corporate offices driving the steepest expansion trajectories due to regulatory compliance deadlines.
- Healthcare Facilities:FDA spatial workflow guidelines for sterile processing and patient flow mandate real-time location systems integrated with space management platforms. Hospital networks in the United States and Japan face immediate procurement windows to redesign clinical layouts around occupancy verification rather than periodic manual audits.
- Corporate Offices:Hybrid work permanence compresses real estate footprints while forcing continuous square-meter justification through IoT sensor verification. Financial services firms in London and Frankfurt pilot depth-sensing computer vision across trading floors where precise density management supports business continuity planning.
- Educational Institutions:Campus-wide space reconfiguration requirements favor vendors offering BIM-integrated digital twin simulation before physical moves.
- Retail Spaces:Footfall analytics integration with inventory positioning drives demand for anonymous people-counting accuracy above threshold levels.
Margin concentration sits with healthcare deployments due to FDA compliance complexity; volume scaling favors corporate office segments undergoing hybrid work restructuring.
Technology:
Technology maturity curves determine procurement risk profiles, with computer vision and edge AI requiring scarce machine learning operations talent that fragments vendor capabilities.
- IoT Sensors:Computer vision and depth-sensing modalities displace passive infrared as the dominant occupancy detection paradigm. TSMC and Samsung foundry capacity concentration in Taiwan and South Korea creates procurement vulnerability for integrated hardware-software vendors dependent on advanced sensor fabrication.
- AI Analytics:Predictive occupancy modeling compresses the cycle between data collection and space reconfiguration decisions. Property managers in the Netherlands and Denmark face immediate CSRD compliance deadlines prioritizing vendors with pre-certified sustainability reporting connectors.
- 3D Modeling:BIM integration with live sensor streams enables simulation-based space planning in campus transformation projects.
- AR Solutions:Spatial visualization tools support facility manager training and maintenance workflow optimization in complex building systems.
Supply concentration in semiconductor fabrication constrains IoT sensor deployment timelines; AI analytics climbs the fastest as cloud-native platforms democratize predictive modeling access.
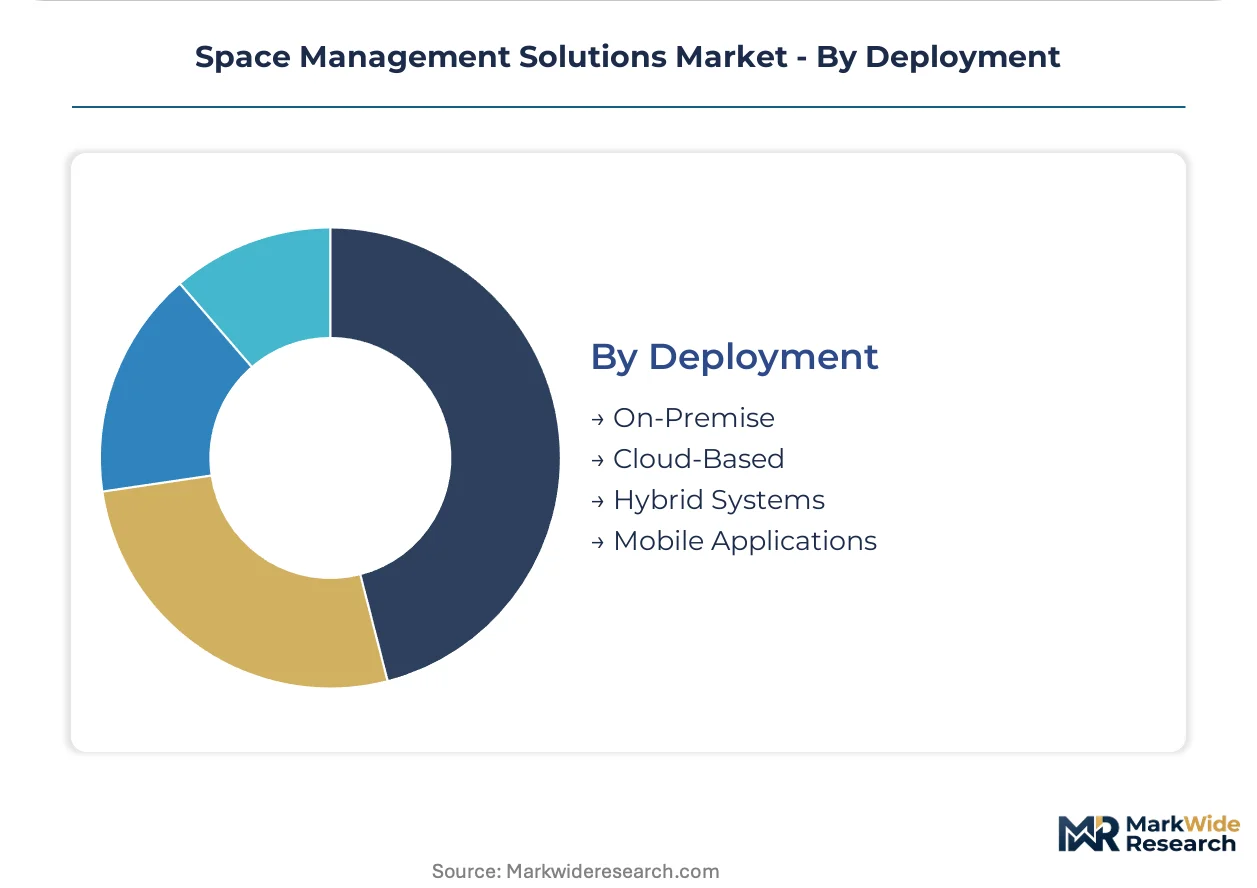
Deployment:
Customer type segmentation reflects IT infrastructure maturity, with cloud-native mid-market operators abandoning on-premise maintenance burdens faster than regulated industries with legacy protocol entrenchment.
- Cloud-Based:Multi-tenant architectures enable unified space management dashboards across multinational portfolios, though GDPR cross-border transfer restrictions and China's data localization requirements complicate deployment architectures. Technology sector headquarters reductions in San Francisco and Seattle trigger renegotiation of entire vendor stacks around outcome-based utilization metrics.
- Hybrid Systems:Edge-processed inference for occupancy pattern recognition balances latency, privacy, and model drift in distributed architectures. BACnet and Modbus protocol stacks in existing building automation infrastructure resist seamless API integration, forcing hybrid approaches in retrofitted commercial portfolios.
- On-Premise:Air-gapped deployments retain preference in defense and critical infrastructure facilities with stringent data sovereignty requirements.
- Mobile Applications:Field technician access to real-time occupancy data supports maintenance prioritization and cleaning schedule optimization.
Legacy system entrenchment prolongs hybrid system dominance in retrofitted buildings; greenfield developments in Japan's Tokyo and Osaka financial districts favor pure cloud architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in Japan deploy space management solutions for predictive HVAC cycling and net-zero compliance, whereas German operators prioritize CSRD-aligned carbon accounting modules for binding emissions disclosures. The United States concentrates on hybrid work footprint compression, while Dutch property managers face immediate sustainability reporting deadlines.
United States
Corporate real estate departments in San Francisco and Seattle are renegotiating entire vendor stacks around outcome-based utilization metrics following technology sector headquarters reductions. OSHA workplace density requirements shape product specifications in industrial settings. Financial services firms in New York pilot depth-sensing computer vision across trading floors where precise density management supports business continuity planning.
Germany
Commercial building owners face EU Green Deal binding emissions reduction timelines that require granular space utilization data to optimize HVAC cycling and lighting loads. CSRD disclosure requirements mandate granular energy attribution to specific tenant spaces. Property managers in Frankfurt prioritize vendors with pre-certified sustainability reporting connectors for immediate compliance deadlines.
Japan
METI's 2025 targets for net-zero commercial structures create immediate demand for predictive occupancy modeling in Tokyo and Osaka financial districts. Hospital networks face procurement windows to redesign clinical layouts around occupancy verification rather than periodic manual audits. Greenfield developments in Tokyo favor pure cloud architectures over hybrid system deployments.
Netherlands
Property managers face immediate CSRD compliance deadlines that prioritize vendors with pre-certified sustainability reporting connectors. EU Green Deal decarbonization mandates for commercial real estate accelerate sensor deployment across regulated portfolios. Industrial warehouse operators in Rotterdam deploy combined environmental and occupancy sensors feeding directly into CSRD-aligned carbon accounting dashboards.
United Kingdom
Financial services firms in London pilot depth-sensing LiDAR arrays combined with edge-processed computer vision delivering anonymous people-counting accuracy above threshold levels. GDPR cross-border transfer restrictions complicate multinational deployment architectures for unified space management dashboards. Corporate offices in London's financial district compress real estate footprints while forcing continuous square-meter justification through IoT sensor verification.
Space Management Solutions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes through rapid deployment capabilities and change management expertise. The market structure reflects capital-intensity divergence between cloud-native platforms and legacy on-premise incumbents. Three strategic archetypes dominate: building automation heritage players bundling hardware-software contracts, enterprise-grade AI analytics specialists serving data-intensive deployments, and cloud-native platform providers targeting mid-market facility operators. Competitive moves concentrate on API interoperability certification and channel evolution through systems integrator partnerships.
Within the integrated hardware-software tier, Johnson Controls International plc and Trane Technologies plc exemplify building automation heritage players leveraging commercial portfolio scale. International Business Machines Corporation occupies a position among enterprise-grade AI analytics specialists, while Eptura Inc represents the cloud-native platform archetype targeting rapid deployment without infrastructure overhead. These three anchors illustrate how procurement criteria split between bundled automation contracts and specialized SaaS architectures.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Johnson Controls International plc |
| Trane Technologies plc |
| Fortive Corporation |
| Yardi Systems Inc. |
| Nemetschek Group SE |
| Eptura Inc |
| Planon Group BV |
| Accruent |
| Others |
Value Network & Pricing Analysis
Twenty-four-week lead times for MEMS-based occupancy sensors from Taiwan-based foundries concentrate pricing power with integrated hardware-software vendors capable of pre-purchasing wafer starts, while SaaS providers face margin compression from cloud infrastructure cost pass-throughs.
Pricing Analysis
Long-term bundled contracts dominate enterprise procurement, locking facility managers into three-to-five-year service agreements that amortize sensor hardware across subscription fees. Price differentiation hinges on CSRD certification tier and API interoperability depth, with premium tiers commanding substantial uplifts for pre-certified sustainability reporting connectors. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler compute pricing resets quarterly. Corporate real estate departments in technology sector clusters exhibit highest price sensitivity, while healthcare networks facing FDA compliance deadlines show lowest.
Supply Chain Analysis
Container availability constraints on the Asia-North America trade lane inflate inbound logistics costs for sensor hardware shipments from Taiwan, South Korea, and China. Advanced MEMS fabrication and LiDAR array production draw from concentrated semiconductor foundry capacity, while edge AI processors rest on TSMC advanced node allocation. Single-source vulnerability in Taiwan Strait shipping lanes threatens just-in-time deployment schedules for integrated system vendors. Distribution runs through Schneider Electric and Siemens-certified integration partners serving mid-market facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switching costs embedded in building management system integrations create durable defensive moats for established vendors, as facility managers face prohibitive re-certification timelines when contemplating platform migrations.
For Market Incumbents: Fortify API interoperability certification pipelines to accelerate BACnet and Modbus protocol stack integration, compressing the 8-14 month BTL compliance windows that stall competitive displacement. Deepen backward integration into edge AI processor supply through strategic foundry partnerships, reducing exposure to TSMC capacity allocation volatility that threatens hardware-software bundle margins.
For New Entrants and Emerging Players: Lead with cloud-native SaaS architectures targeting mid-market facility operators in Japan's Tokyo and Osaka financial districts, where METI net-zero deadlines outpace incumbent deployment capacity. White-space concentration sits with digital twin consulting services for educational institution campus transformations, where BIM-integrated simulation capabilities remain undersupplied.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because EU Green Deal and CSRD disclosure mandates create irreversible compliance infrastructure demand across commercial real estate portfolios. Acquisition target archetype: cloud-native platforms with pre-certified sustainability reporting connectors serving Netherlands and Denmark property managers facing immediate deadlines. Signal to watch: BTL certification backlog duration as indicator of vendor implementation capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Certification | BTL and WELL Building Standard pre-certification compresses vendor product roadmaps and customer implementation windows. |
| Edge AI Processor Supply Agreement | Strategic foundry partnerships reduce TSMC capacity allocation exposure threatening hardware-software bundle margins. |
| Digital Twin Platform Integration | BIM model convergence with live sensor streams opens consulting revenue pools in educational campus transformations. |
| CSRD Reporting Connector Development | Pre-certified sustainability modules command premium pricing from Netherlands and Denmark property managers facing compliance deadlines. |
| Systems Integrator Channel Partnership | Schneider Electric and Siemens-certified partners become primary procurement paths for mid-market facility operators. |
Research Methodology
The analysis maps software solutions, cloud platforms, IoT sensor hardware, and consulting services segments, each validated through facility management directors, corporate real estate executives, building automation engineers, and systems integration specialists. Primary interview findings triangulate against SEC 10-K filings, EU CSRD disclosure databases, METI smart building policy documents, and hyperscaler capex disclosures. Bottom-up deployment estimates cross-check with top-down building stock analysis across regulated commercial portfolios.
Consistency checks validate volume and value outputs against external benchmarks including building automation infrastructure spend patterns and IoT sensor shipment data across the analysis window. Segmentation models incorporate deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to technology adoption S-cycles and compliance deadline clustering, with inputs including HVAC retrofit timelines and sensor cost curve trajectories.
Forecasts assume regulatory continuity in EU Green Deal implementation, FDA spatial workflow guidelines, and METI net-zero commercial building targets; material policy shifts would require re-modeling. Semiconductor supply concentration, data sovereignty friction, and legacy protocol entrenchment represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Lander and Rover Market
Space
Europe Space Electronics Market
Space
Space Debris Monitoring Market
Space
Asia-Pacific Space Logistics Market
Space
Space Blanket Market
Space
Astronaut Spacesuit Market
Space
India Aviation, Defense, and Space Market
Space
Space Battery Market
Space
Carrier Rocket Market
Space
Space Wheel Market
Space
India Space Electronics Market
Space
Space Designing Market
Space
UK Space Electronics Market
Space
Deep Space Exploration Market
Space
US Reusable Launch Vehicle Market
Space
Electrically Powered Spacecraft Propulsion Market