
 Space Service Market | 2026-2036
Space Service Market Size, Share, and Industry Trends Forecast 2026-2036
Space Service Market Analysis
Orbital-class payload certification is reorganizing competitive hierarchies in the space service industry. SpaceX leverages its reusable Falcon architecture to sustain price leadership on commercial launch manifests. Blue Origin anchors its position through heavy-lift New Glenn development and NASA lunar lander contracts.
Space services encompass the design, integration, and operation of orbital and suborbital systems delivering payload deployment, communications relay, and remote sensing capabilities, typically requiring launch velocities exceeding 7.8 km/s for low-Earth orbit insertion and thermal protection systems rated for atmospheric reentry. Satellite communications generates the most stable revenue pool among service types, while launch services captures the fastest expansion as flight frequency scales. Government agencies remain the dominant customer type by contract value, though commercial enterprises are deepening procurement of Earth observation data for agricultural monitoring and disaster management applications.
FAA launch licensing governs US orbital operations, while ESA procurement rules shape European vendor qualification and ITAR controls restrict cross-border technology transfer for propulsion and guidance systems. Stakeholders must monitor how national security classifications and export control frameworks fragment supplier ecosystems as launch cadence accelerates.
Market Dynamics
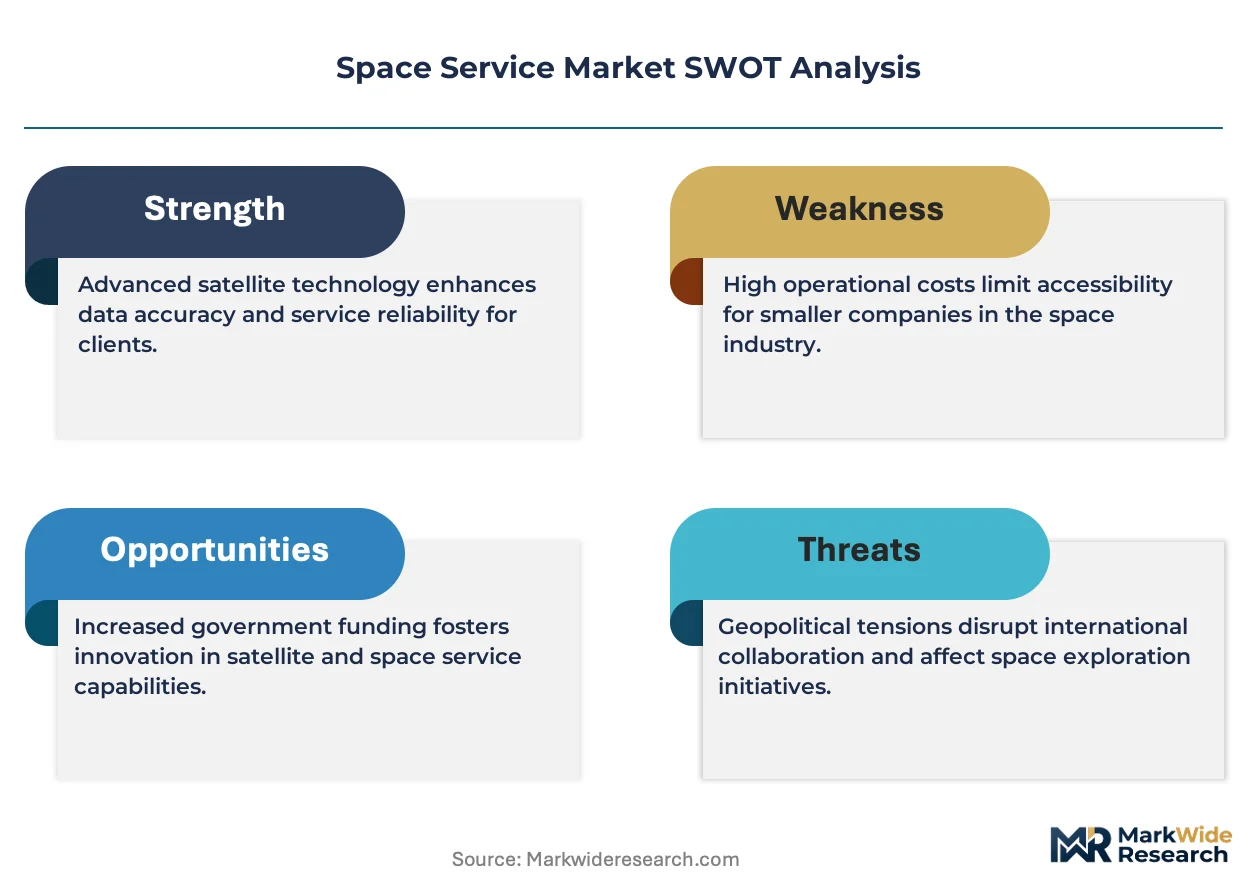
Reusable propulsion architecture is compressing launch economics and forcing incumbent operators to restructure cost bases around flight-proven hardware rather than expendable systems.
Growth Catalysts
- NATO Defense Procurement:Allied defense agencies are expanding satellite communications contracts and launch service agreements to secure resilient orbital infrastructure for contested environments.
- Earth Observation Demand:Agricultural monitoring and disaster management applications are deepening commercial procurement of remote sensing data from low-Earth orbit constellations.
- FAA Streamlined Licensing:The regulator's expedited launch authorization pathways are reducing time-to-flight for commercial orbital operations.
Market Restraints
- ITAR Export Controls:US restrictions on propulsion and guidance technology transfer fragment supplier ecosystems and limit cross-border component sourcing.
- Launch Site Concentration:Eastern Range and Western Range capacity bottlenecks constrain flight cadence scaling regardless of vehicle availability.
- Specialized Alloy Supply:Inconel and titanium sourcing for engine components faces aerospace-grade certification delays and foundry capacity limits.
Strategic Opportunities
- Lunar Infrastructure Services:NASA Artemis program requirements for crew transport and surface logistics create new contract categories beyond Earth orbit.
- On-Orbit Servicing:Satellite life extension through robotic refueling and component replacement addresses stranded asset value in geostationary fleets.
- Space Situational Awareness Mandates:FCC debris mitigation rules are compelling operators to procure tracking and collision avoidance services.
Industry Challenges
- Propulsion Engineering Talent:Liquid oxygen and methane turbopump design expertise concentrates at a handful of legacy contractors and startup spinouts.
- Flight Heritage Requirements:Payload insurers and government customers demand demonstrated orbital insertion reliability that new entrants cannot shortcut.
- Range Integration Complexity:Each launch vehicle configuration requires bespoke telemetry and safety system certification with Eastern Range operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Service Market |
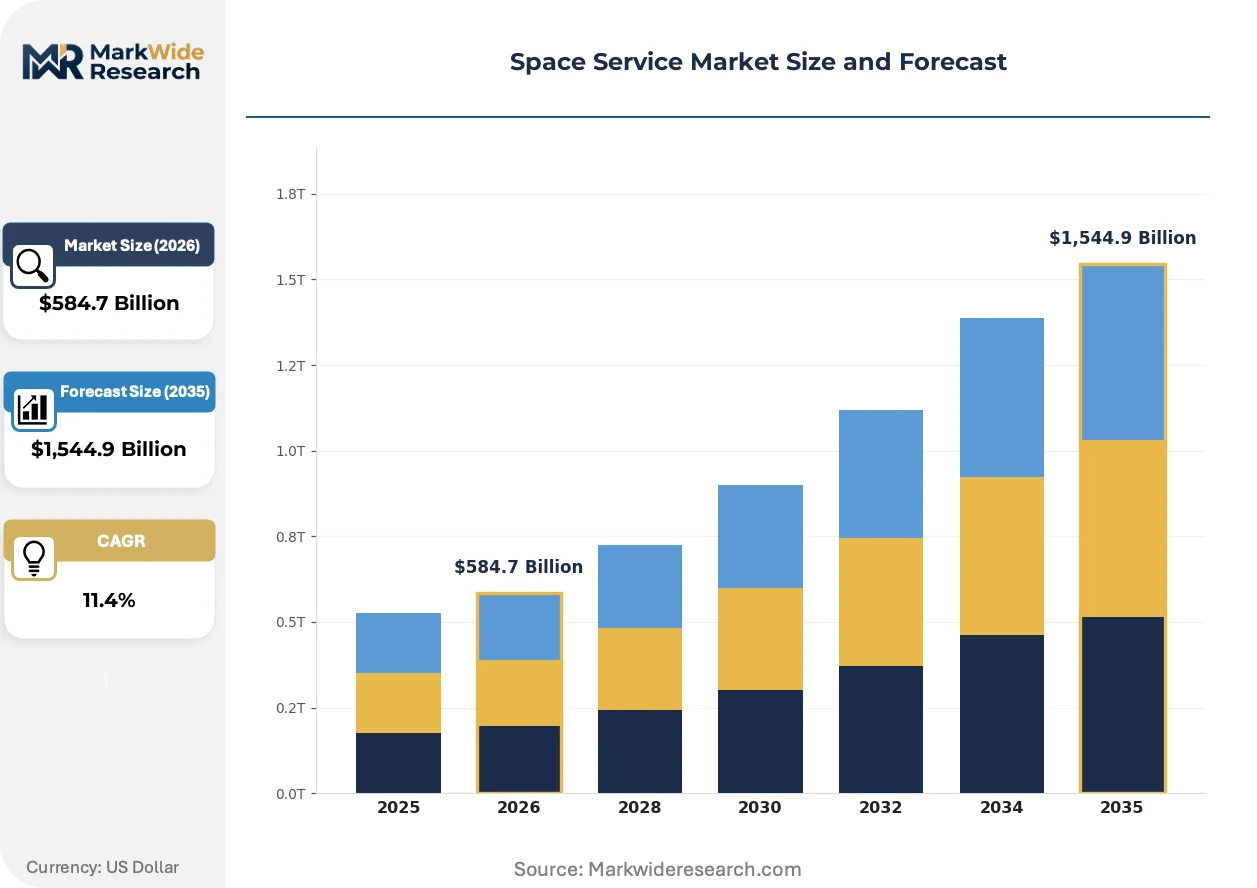
| Market Size in 2026 | $584.7 Billion |
| Market Size in 2035 | $1,544.9 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Satellite Communications, Launch Services, Space Tourism, Space Exploration Customer Type: Government Agencies, Commercial Enterprises, Research Institutions, Non-profits Technology: Reusable Rockets, CubeSats, Space Robotics, Propulsion Systems Application: Agricultural Monitoring, Disaster Management, Earth Observation, Scientific Research |
| Companies Covered | Firefly Aerospace, ClearSpace SA, SpaceX, Northwood Space, Stoke Space Technologies, Blue Origin, Astranis, Planet Labs, Axiom Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Service Market Emerging Trajectories
Orbital service provision is fragmenting into specialized layers as standardized interfaces enable payload-agnostic platforms and third-party mission services.
Additive manufacturing is decomposing traditional supply chains for combustion chamber and nozzle production. SpaceX and Relativity Space are qualifying printed superalloy components for flight-critical applications. This technology is decomposing the multi-year forging and machining timelines that previously gated engine production rates.
REACH chemical registration in Europe is imposing new material disclosure requirements on thermal protection systems and propellant formulations. Manufacturers must document substance volumes and toxicity profiles across their supply bases. Satellite operators procuring European launch services are selecting providers with pre-registered material certifications to avoid mission delays.
Commercial buyers are unbundling launch services from integrated mission management. Agricultural enterprises and insurance underwriters now contract directly with data analytics platforms rather than vertically integrated satellite operators. This pattern is most pronounced in North American precision agriculture, where farm cooperatives subscribe to crop health monitoring without acquiring ground segment expertise.
Space Service Market Segmentation
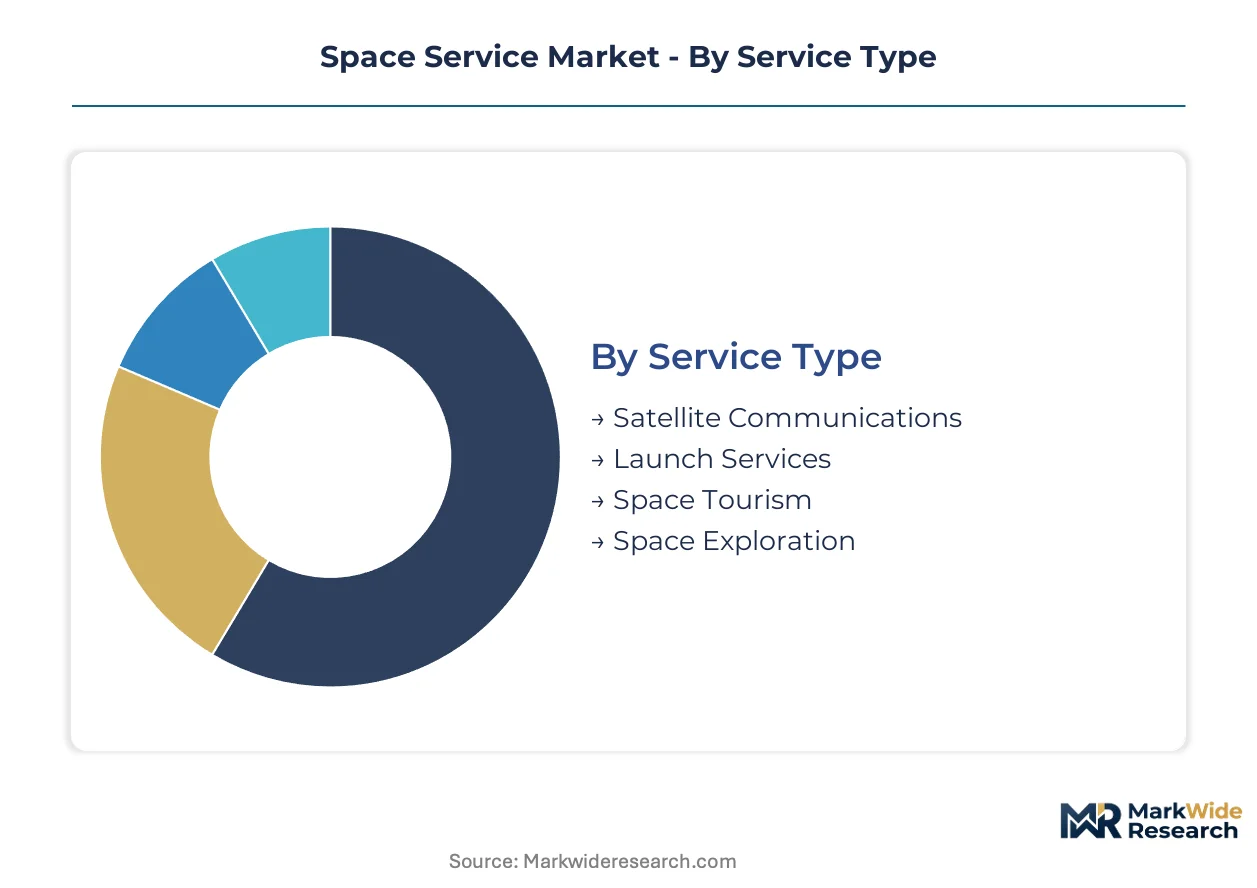
Segmentation in space services reveals how procurement authority, technical maturity, and application economics partition contract flows across orbital and suborbital categories. Understanding these divisions exposes where pricing power concentrates and which technology transitions threaten incumbent positions.
Service Type:
Satellite Communications and Launch Services anchor domestic procurement from NASA and Space Force, while Space Tourism and Space Exploration draw export-led demand from allied defense agencies and international research consortia.
- Satellite Communications:Geostationary and low-Earth orbit relay networks deliver persistent bandwidth for military C4ISR and commercial broadcast. Demand concentrates in United States defense procurement, where Space Force resilient communications mandates sustain multi-year contract visibility.
- Launch Services:Orbital insertion capabilities span small-lift through super-heavy classes, with reusable architectures compressing cost per kilogram. Growth concentrates in commercial constellation deployment, where Starlink and competitor mega-constellations drive flight cadence expansion.
- Space Tourism:Suborbital passenger flights and orbital private missions target high-net-worth individuals and corporate experiential marketing.
- Space Exploration:Crewed lunar surface operations and deep-space robotic missions serve NASA Artemis requirements and international partnership frameworks.
Satellite Communications holds the largest share; momentum sits with Launch Services as flight frequency scales.
Customer Type:
Government Agencies dominate contract value through multi-year appropriations, while Commercial Enterprises are deepening procurement of Earth observation analytics and bandwidth services.
- Government Agencies:National space agencies and defense departments fund infrastructure development, technology demonstration, and assured access to orbit through cost-plus and fixed-price mechanisms. NASA and Space Force procurement in the United States anchors this segment's revenue concentration.
- Commercial Enterprises:Agricultural conglomerates, insurance underwriters, and logistics operators subscribe to remote sensing data and satellite communications without acquiring ground segment expertise. Demand is climbing fastest in North American precision agriculture.
- Research Institutions:Universities and national laboratories procure hosted payload opportunities and dedicated small satellite launches for atmospheric and astrophysical investigation.
- Non-profits:Environmental monitoring organizations and disaster response coalitions access subsidized or donated Earth observation capacity for humanitarian applications.
Government Agencies command the largest contract value; Commercial Enterprises are gaining share fastest through unbundled data procurement.
Technology:
Reusable Rockets and Propulsion Systems concentrate development investment, while CubeSats and Space Robotics spread across distributed manufacturing bases.
- Reusable Rockets:Flight-proven first stages and emerging second-stage recovery systems reduce marginal launch costs through rapid turnaround operations. SpaceX Falcon and Blue Origin New Glenn development programs anchor this segment's technical leadership.
- Propulsion Systems:Liquid oxygen and methane turbopump architectures, plus electric propulsion for orbital maneuvering, determine payload delivery precision and satellite operational lifespan. Supply concentrates at legacy contractors and startup spinouts with demonstrated combustion stability.
- CubeSats:Standardized 10x10x10 centimeter form factors enable university and commercial developers to access orbital deployment at reduced non-recurring engineering cost.
- Space Robotics:On-orbit servicing vehicles and lunar surface mobility systems address satellite life extension and crew logistics requirements.
Reusable Rockets capture the steepest investment trajectory; Propulsion Systems remain the critical path constraint for new vehicle qualification.
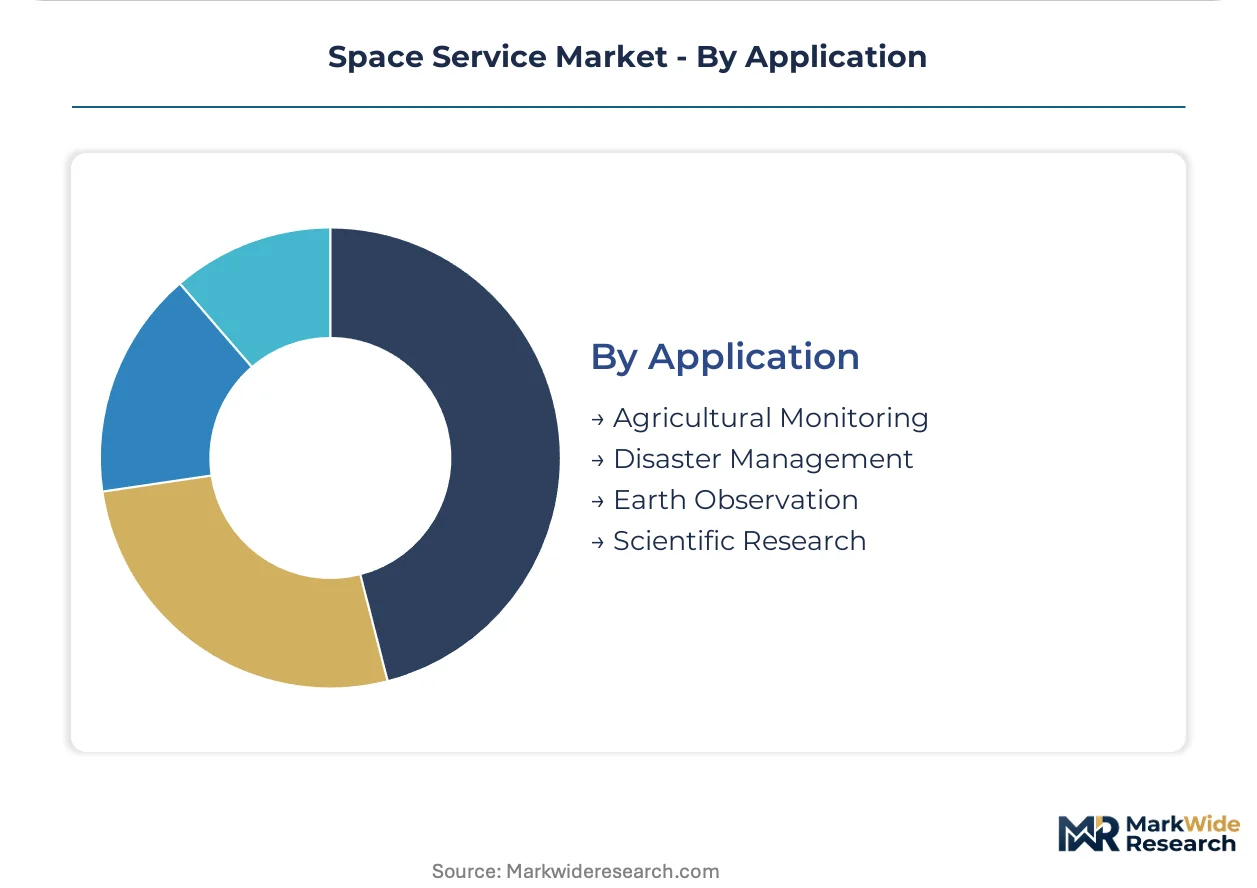
Application:
Agricultural Monitoring and Disaster Management applications unbundle vertically integrated service stacks, while Earth Observation and Scientific Research sustain traditional procurement relationships.
- Earth Observation:Optical and synthetic aperture radar imaging from low-Earth orbit constellations supports defense intelligence, environmental compliance, and urban planning. Demand concentrates in United States federal procurement and European Copernicus program participation.
- Agricultural Monitoring:Crop health indices, yield prediction models, and irrigation optimization analytics deliver direct economic returns to farm cooperatives and agribusiness operators. Commercial subscription models are displacing government-subsidized data access.
- Disaster Management:Rapid damage assessment and communications restoration following natural hazards serves insurance underwriters and emergency response agencies.
- Scientific Research:Astronomy, heliophysics, and planetary science missions access dedicated orbital platforms and deep-space trajectories through competitive peer review allocation.
Earth Observation retains the largest installed base; Agricultural Monitoring is expanding most quickly as precision farming adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across geographies. United States buyers absorb premium pricing for assured access, while European and Asian operators prioritize cost-per-kilogram compression. Commercial constellation operators in emerging markets exhibit the highest price sensitivity.
United States
NASA Artemis lunar infrastructure contracts and Space Force resilient communications mandates anchor procurement volume. FAA streamlined launch licensing reduces time-to-flight for commercial operators. Cape Canaveral and Vandenberg Space Force Base concentrate flight operations, with Eastern Range capacity expansion addressing cadence bottlenecks.
China
State-owned launch service providers serve domestic mega-constellation deployment and Belt and Road satellite export agreements. MIIT satellite frequency coordination governs orbital slot allocation and debris mitigation compliance. Wenchang Satellite Launch Center on Hainan Island hosts heavy-lift operations, with new coastal facilities reducing inland transport constraints.
France
ESA procurement rules shape Ariane launch service qualification and Copernicus Earth observation program participation. CNES funding sustains Guiana Space Centre operations at Kourou. Toulouse aerospace cluster concentrates satellite manufacturing and mission control expertise for European institutional customers.
Japan
METI space industry competitiveness initiatives support H3 rocket development and commercial launch service expansion. JAXA international partnership frameworks enable ISS utilization and lunar exploration technology demonstration. Tanegashima Space Center and Uchinoura Space Center anchor domestic launch capacity.
United Kingdom
Civil Aviation Authority spaceflight licensing governs vertical and horizontal launch operations from Scottish spaceports. UK Space Agency funding targets small satellite manufacturing and downstream data analytics capabilities. Cornwall Spaceport and SaxaVord Spaceport developments aim to capture European small-lift launch demand.
Space Service Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Reusable rocket developers compress launch economics through flight-proven hardware, while specialized satellite operators capture recurring service revenue. The field separates into three strategic archetypes: vertically integrated launch-service providers, focused satellite operators, and emerging on-orbit servicing specialists. Competitive moves center on launch cadence scaling and payload-agnostic platform development.
Among vertically integrated launch-service providers, SpaceX and Blue Origin exemplify the cost-leadership archetype through reusable propulsion architectures. Firefly Aerospace occupies a position within the small-lift specialist tier. These companies represent the dominant competitive anchors shaping procurement expectations and flight-frequency benchmarks across defense and commercial customer segments.
| Leading Market Players |
|---|
| Firefly Aerospace |
| ClearSpace SA |
| SpaceX |
| Northwood Space |
| Stoke Space Technologies |
| Blue Origin |
| Astranis |
| Planet Labs |
| Axiom Space |
| Others |
Supply Flow & Price Mechanics
Fixed-price milestone contracts for NASA Artemis and Space Force resilient communications programs lock in multi-year supply access for engine components and launch range capacity while capping price volatility for prime contractors. This contract structure concentrates procurement leverage among a shrinking pool of qualified bidders with demonstrated flight heritage, compressing margins for second-tier suppliers dependent on spot-market component sales.
Pricing Analysis
FAA launch licensing dictates the pricing tier structure across orbital service providers, separating flight-proven operators with streamlined authorization pathways from new entrants facing extended certification timelines. Pricing stratifies across heritage-verified, provisional-certification, and experimental-flight tiers, with differentiation driven by insurance premium loads and range integration complexity. Cost compression in small-lift segments is intensifying because Firefly Aerospace and emerging entrants are undercutting legacy providers on dedicated rideshare missions. Commercial constellation operators exhibit the highest price sensitivity, while defense agencies absorb premiums for assured access and security-cleared ground operations.
Supply Chain Analysis
Extended lead times for Inconel 718 and titanium 6Al-4V forgings constrain engine production rates regardless of final assembly capacity. Supply concentrates in United States, France, and Japan for aerospace-grade superalloy castings and precision turbopump components. Raw material sourcing draws from Canadian nickel mines, Australian titanium sponge facilities, and domestic vacuum arc remelting operations. Single-source vulnerability persists for large-diameter carbon fiber filament winding used in solid rocket motor casings. Distribution runs through vertically integrated prime contractors with captive foundry and machining capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among defense procurement offices and mega-constellation operators, fragmenting pricing leverage across smaller satellite developers and research institutions. This concentration demands differentiated positioning strategies by competitive archetype.
For Market Incumbents: Secure flight-proven hardware advantages through rapid turnaround operations and exclusive range slot reservations at Cape Canaveral and Vandenberg. Vertical integration into superalloy additive manufacturing reduces dependency on qualified forging suppliers facing capacity constraints. Threat from reusable second-stage recovery technologies demands accelerated R&D investment to maintain cost leadership against Blue Origin and Stoke Space Technologies. For New Entrants and Emerging Players: Anchor in on-orbit servicing and debris removal contracts where flight heritage requirements are nascent and regulatory mandates are creating first-mover advantages. The most penetrable segment sits with commercial Earth observation analytics platforms unbundling vertically integrated service stacks. Go-to-market execution should emphasize direct partnerships with agricultural cooperatives and insurance underwriters bypassing traditional satellite operator intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among satellite communications operators with multi-year bandwidth lease contracts and ground station-as-a-service platforms. Long-term viability over the coming decade hinges on regulatory capture in lunar infrastructure and space situational awareness services. Acquisition targets should demonstrate pre-qualified additive manufacturing capabilities or exclusive launch site access rights. The critical inflection signal to watch is FCC debris mitigation rule enforcement compelling legacy constellation operators to procure external tracking and collision avoidance services.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Second-Stage Recovery | Blue Origin and SpaceX development programs compress marginal launch costs through rapid turnaround operations. |
| On-Orbit Servicing Vehicle Deployment | ClearSpace SA and Northwood Space address stranded asset value in geostationary satellite fleets. |
| Lunar Lander Capability Qualification | NASA Artemis crew transport contracts create new revenue categories beyond low-Earth orbit services. |
| Additive Manufacturing Scale-Up | Relativity Space and SpaceX qualify printed superalloy components, decomposing traditional forging timelines. |
| Space Situational Awareness Platform Launch | FCC debris mitigation rules compel operators to procure external tracking and collision avoidance services. |
Methodological Framework
A standing panel of launch vehicle program managers, satellite constellation operators, range safety officers, and defense procurement specialists provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FAA launch licensing databases, NASA contract award announcements, ESA procurement registries, and SEC filings from publicly traded space companies. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the space services value chain.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled service type, customer category, propulsion technology, and orbital application dimensions. CAGRs were derived from trajectory analysis of flight cadence scaling, constellation deployment schedules, and defense appropriation patterns. Industry-specific inputs included Eastern Range capacity expansion timelines and ITAR-controlled technology transfer restrictions.
Material uncertainties — abrupt shifts in NATO defense procurement priorities, FAA licensing moratoria following launch anomalies, and REACH chemical registration delays for European thermal protection systems — sit outside the modeled envelope. Forecasts reflect documented assumptions about reusable rocket reliability maturation and mega-constellation deployment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Radar Market
Space
Deep Space Robotics Market
Space
Suborbital Space Tourism Market
Space
Space Lander and Rover Market
Space
Space Debris Monitoring and Removal Market
Space
Astronaut Spacesuit Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space-Based Smart Sensors Market
Space
Space Technology (Spacetech) Market
Space
Space Tourism Market
Space
Space-Based C4ISR Market
Space
Space Rover Market
Space
Space Mining Market
Space
Asteroid Mining Market
Space
Germany Space Electronics Market
Space
Space in Orbit Refueling Market