
 Space Wheel Market | 2026-2036
Space Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Space Wheel Market Insights
Aftermarket service revenue for orbital track wheel refurbishment is tilting toward captive in-house programs at major space agencies. Boeing sustains vertical integration across wheel design and thermal testing for crewed vehicles. Lockheed Martin anchors long-cycle production through classified defense satellite contracts. Northrop Grumman specializes in gyroscopic wheel stabilization systems for geostationary platforms.
A space wheel is a precision rotating assembly engineered for vacuum operation, typically fabricated from aluminum alloy or carbon composite substrates with integrated bearing seals rated for thermal cycling between minus 150 and plus 120 degrees Celsius, serving to provide locomotion, attitude control, or centrifugal artificial gravity in spacecraft and surface vehicles. Orbital track wheels and gyroscopic wheels command the largest installed base due to sustained space station logistics and communications satellite deployment. Lunar rover wheels represent the fastest-expanding product category as Artemis-derived surface missions advance from concept to hardware qualification.
FAA licensing protocols for commercial orbital platforms shape wheel certification requirements for space tourism vehicles. NASA technical standards for extravehicular mobility units establish baseline material performance thresholds that propagate through supplier chains. ESA's Clean Space initiative imposes debris-mitigation criteria affecting wheel end-of-life disposal design. Stakeholders must weigh sovereign space agency procurement cycles against commercial operator volume commitments when calibrating capacity investments.
Market Dynamics
Artemis program lunar mobility requirements are compressing wheel qualification timelines while forcing simultaneous upgrades to thermal cycling tolerance and debris impact resistance across supplier networks.
Growth Catalysts
- Commercial Orbital Habitat Expansion:Space station operators are multiplying permanent crewed platforms, generating sustained demand for orbital track wheel refurbishment and replacement cycles.
- FAA Commercial Launch Licensing:The administration's streamlined certification pathways for space tourism vehicles are accelerating wheel qualification programs for suborbital and orbital passenger craft.
- Carbon Composite Substrate Adoption:Advanced fiber-reinforced polymers are displacing aluminum alloys in next-generation gyroscopic wheels, cutting mass fractions by double-digit percentages.
Market Restraints
- Specialized Bearing Seal Supply Concentration:Vacuum-rated ceramic bearing production concentrates among a handful of Japanese and German precision manufacturers, creating single-source vulnerability.
- Extreme Thermal Cycling Qualification Costs:Validating wheel assemblies across minus 150 to plus 120 degrees Celsius regimes requires capital-intensive thermal vacuum chamber access.
- Debris Mitigation Design Burden:ESA's Clean Space initiative mandates end-of-life disposal trajectories that add engineering complexity and mass penalties to wheel systems.
Strategic Opportunities
- Artemis-Derived Lunar Rover Programs:NASA's surface mobility requirements are opening dedicated procurement channels for wheels rated to abrasive regolith abrasion and extreme temperature differentials.
- In-Space Servicing and Manufacturing:Orbital assembly platforms are creating demand for wheels designed for microgravity fabrication environments rather than Earth launch survival.
- Geostationary Platform Life Extension:Satellite operators are retrofitting gyroscopic stabilization wheels to extend operational lifespans, generating aftermarket refurbishment revenue streams.
Industry Challenges
- Vacuum Tribology Expertise Scarcity:The specialized knowledge base for lubricant-free bearing operation in hard vacuum conditions remains concentrated among retiring NASA and ESA engineering cohorts.
- Multi-Agency Certification Parallel Processing:Suppliers must simultaneously satisfy NASA technical standards, FAA commercial licensing, and ESA debris protocols, fragmenting qualification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Wheel Market |
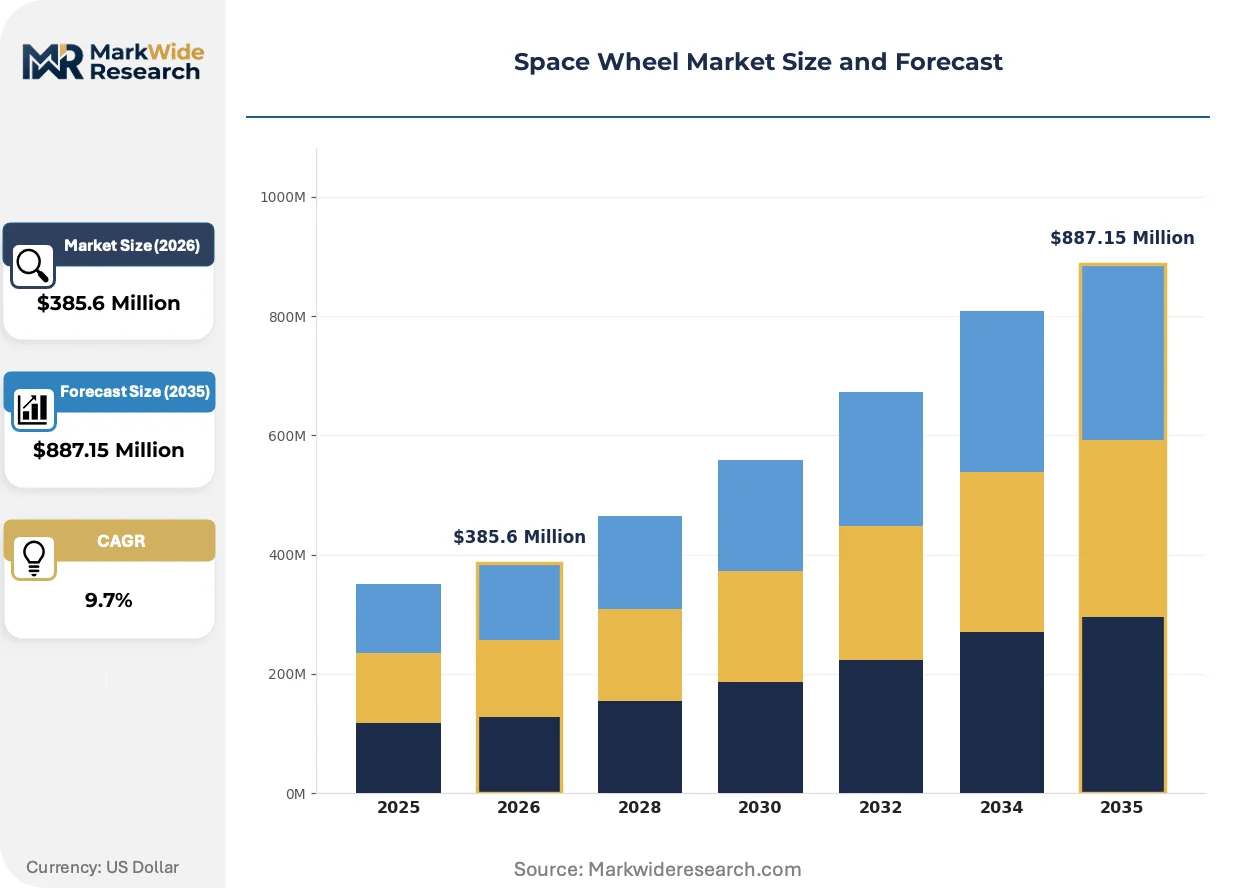
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orbital Track Wheel, Extravehicular Mobility Wheel, Lunar Rover Wheel, Satellite Stabilizer Wheel, Gyroscopic Wheel Material: Aluminum Alloy, Carbon Composite, Titanium, High-Density Polymer, Ceramic Matrix Application: Space Exploration Vehicles, Scientific Satellites, Space Stations, Space Tourism, Defense Satellites End User: Space Agencies, Aerospace Manufacturers, Commercial Space Operators, Research Laboratories, Defense Contractors |
| Companies Covered | Boeing, Arianespace, NASA, Thales Alenia Space, Roscosmos, Airbus, Lockheed Martin, Northrop Grumman, SpaceX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Wheel Market Trends and Innovations
Materials science advances and regulatory harmonization pressures are converging to reshape wheel architecture, manufacturing methods, and supplier qualification pathways across orbital and surface applications.
Additive manufacturing of titanium aluminide wheel hubs is migrating from prototyping to flight-qualified production at major space agencies. NASA's Marshall Space Flight Center has certified laser powder bed fusion for select structural wheel components. This process is compressing lead times for complex geometries that previously required multi-piece welded assemblies.
REACH substance restrictions are forcing reformulation of conventional thermal control coatings used on aluminum wheel substrates. European suppliers are pivoting to chromium-free conversion coatings and ceramic-based alternatives. Lunar rover wheel programs are most affected, as heritage coating systems face sunset dates before Artemis hardware qualification completes.
Agency procurement offices are consolidating wheel purchases into multi-mission framework contracts with performance-based acceptance criteria. Prime contractors are responding by internalizing wheel design capabilities rather than sourcing from specialty vendors. The United States exhibits this pattern most acutely, where SpaceX and Blue Origin captive programs are displacing traditional supplier relationships.
Space Wheel Market Segmentation
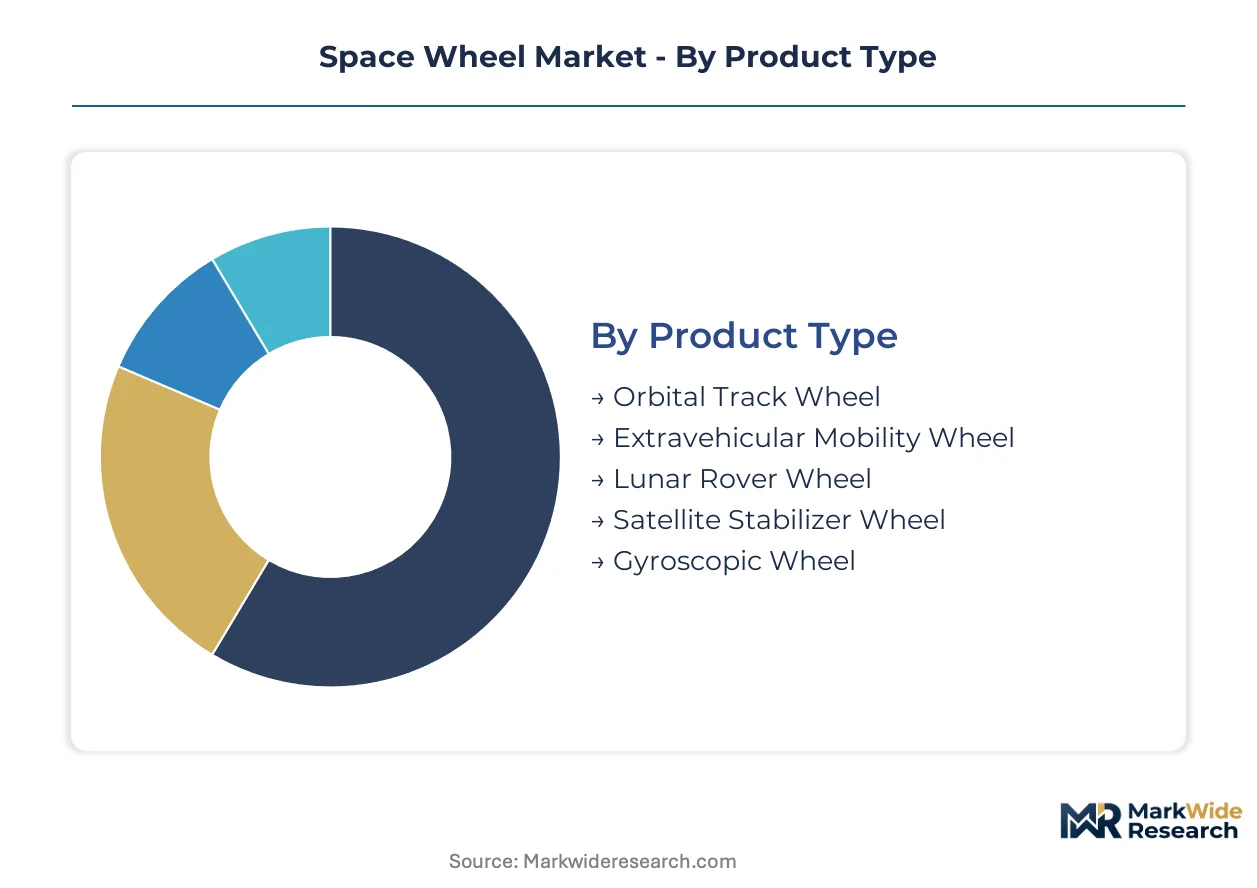
Wheel architecture varies sharply across orbital, surface, and stabilization functions, with each segment demanding distinct thermal tolerance specifications and bearing seal configurations. Procurement patterns diverge between agency-led qualification programs and commercial operator volume purchasing.
Product Type:
After-sales intensity peaks with orbital track wheels, where refurbishment cycles generate recurring revenue streams distinct from initial hardware sales.
- Orbital Track Wheel:Aluminum alloy construction with integrated ceramic bearing seals rated for thermal cycling between minus 150 and plus 120 degrees Celsius. Demand concentrates in United States low Earth orbit logistics platforms, constrained by NASA technical standards for material performance thresholds.
- Lunar Rover Wheel:Carbon composite substrates with regolith-abrasion-resistant tread geometries engineered for Artemis program surface mobility requirements. United States procurement channels are expanding fastest as NASA compresses qualification timelines for Artemis-derived hardware.
- Extravehicular Mobility Wheel:Compact precision assemblies for astronaut suits with vacuum-rated lubricant-free operation.
- Satellite Stabilizer Wheel:Gyroscopic momentum wheels for attitude control in geostationary communications platforms.
- Gyroscopic Wheel:High-speed rotating masses for three-axis stabilization of long-duration orbital assets.
By volume, orbital track wheels lead. By growth pace, lunar rover wheels are climbing the fastest.
Material:
Cost tier stratification separates flight-qualified substrates from developmental alternatives still seeking certification pathways.
- Carbon Composite:Fiber-reinforced polymer matrices displacing aluminum alloys in next-generation gyroscopic wheels, cutting mass fractions by double-digit percentages. United States commercial operators are driving adoption fastest as launch cost sensitivity intensifies.
- Aluminum Alloy:Heritage substrate for orbital track wheels with established thermal control coating systems and multi-decade flight heritage. REACH substance restrictions are forcing European suppliers toward chromium-free conversion coatings before Artemis hardware qualification completes.
- Titanium:Additive-manufactured titanium aluminide hubs migrating from prototyping to flight-qualified production at NASA Marshall Space Flight Center.
- High-Density Polymer:Emerging substrate for disposable or short-duration mission profiles with reduced qualification burdens.
- Ceramic Matrix:Ultra-high-temperature capable materials for specialized solar probe or inner-planet missions.
By installed base, aluminum alloy dominates. By technology transition velocity, carbon composites are gaining share fastest.
Application:
Customer type concentration varies sharply between sovereign procurement cycles and commercial operator volume commitments.
- Space Stations:Permanent crewed platforms generating sustained demand for orbital track wheel refurbishment and replacement cycles. United States concentration is highest where SpaceX and Blue Origin anchor launch cadence and in-orbit infrastructure deployment.
- Space Exploration Vehicles:Lunar and planetary surface craft requiring simultaneous thermal cycling tolerance and debris impact resistance. Artemis program requirements are tightening durability specifications across supplier networks.
- Scientific Satellites:Precision pointing platforms with gyroscopic stabilization demands for astrophysics and Earth observation missions.
- Space Tourism:Suborbital and orbital passenger craft subject to FAA commercial launch licensing protocols shaping wheel certification requirements.
- Defense Satellites:Classified programs with long-cycle production anchored through prime contractor vertical integration.
By mission count, scientific satellites lead. By procurement momentum, space stations are expanding most quickly.
End User:
Supply concentration patterns favor captive in-house programs at major agencies over specialty vendor relationships.
- Commercial Space Operators:SpaceX and Blue Origin captive programs are displacing traditional supplier relationships in the United States. FAA licensing protocols for commercial orbital platforms shape wheel certification requirements distinct from agency technical standards.
- Space Agencies:NASA, ESA, and JAXA procurement offices consolidating purchases into multi-mission framework contracts with performance-based acceptance criteria. ESA's Clean Space initiative imposes debris-mitigation criteria affecting wheel end-of-life disposal design.
- Aerospace Manufacturers:Boeing sustains in-house production across wheel design and thermal testing for crewed vehicles.
- Defense Contractors:Lockheed Martin anchors production through classified satellite contracts with specialized security requirements.
- Research Laboratories:Academic and institutional buyers with fragmented demand and extended qualification timelines.
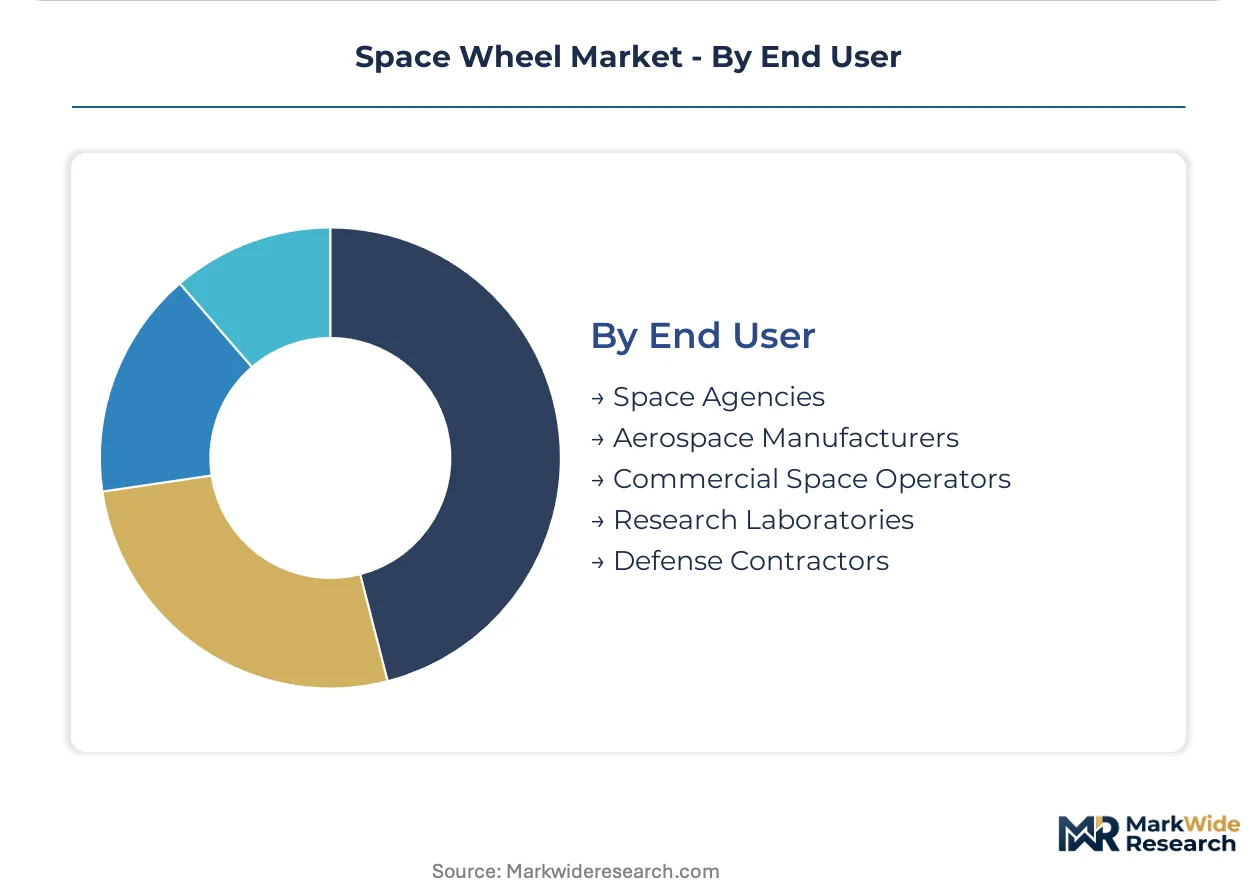
By contract value, space agencies lead. By growth trajectory, commercial space operators are pulling ahead fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheel fabrication capacity clusters around sovereign space agency procurement centers and commercial launch complexes. NASA's Artemis program requirements are compressing qualification timelines across North American supplier networks. ESA's Clean Space debris protocols and JAXA's technology transfer programs are shaping parallel certification pathways in Europe and Asia.
United States
SpaceX and Blue Origin anchor commercial launch cadence and in-orbit infrastructure deployment across Texas and Florida spaceports. FAA commercial launch licensing protocols shape wheel certification requirements distinct from NASA technical standards. Houston and Huntsville engineering clusters concentrate thermal vacuum testing capabilities for Artemis-derived lunar mobility hardware.
Germany
Precision ceramic bearing manufacturers in Bavaria and Baden-Württemberg supply vacuum-rated components for gyroscopic stabilization systems. REACH substance restrictions force reformulation of thermal control coatings on aluminum wheel substrates before Artemis hardware qualification completes. Stuttgart and Munich aerospace clusters specialize in debris-mitigation design for ESA Clean Space compliance.
France
Arianespace launch operations at Kourou generate sustained demand for orbital track wheel refurbishment cycles. ESA technical standards propagate through Toulouse and Paris-Saclay engineering centers. Thales Alenia Space anchors long-cycle production for geostationary platform stabilization wheels.
Japan
JAXA technology transfer programs concentrate precision manufacturing expertise in Nagoya and Tokyo metropolitan clusters. Japanese ceramic bearing producers supply critical vacuum-rated components to global wheel assemblers. Tsukuba Space Center qualification protocols establish baseline thermal cycling tolerance specifications.
United Kingdom
Scottish spaceport development at SaxaVord and Sutherland is creating regional demand for suborbital vehicle wheel certification. UK Space Agency procurement frameworks align with ESA debris-mitigation criteria for end-of-life disposal trajectories. Harwell and Glasgow engineering clusters focus on small satellite stabilization wheel miniaturization.
Space Wheel Market Competitive Landscape
Prime contractors and captive agency programs split the market between vertically integrated production and outsourced specialty fabrication. Boeing sustains in-house wheel design and thermal testing capabilities for crewed vehicle programs. Lockheed Martin anchors classified defense satellite contracts through long-cycle production arrangements. Competitive moves concentrate on backward integration into bearing seal supply and strategic partnerships with carbon composite substrate developers.
Among US-based prime contractors, Boeing, Lockheed Martin, and Northrop Grumman exemplify the vertically integrated archetype controlling design through qualification. SpaceX represents the captive commercial operator model displacing traditional supplier relationships through internalized production. Thales Alenia Space occupies a position bridging European agency procurement and commercial platform supply.
| Leading Market Players |
|---|
| Boeing |
| Arianespace |
| NASA |
| Thales Alenia Space |
| Roscosmos |
| Airbus |
| Lockheed Martin |
| Northrop Grumman |
| SpaceX |
| Others |
Pricing and Supply Chain Analysis
Bavarian precision manufacturing clusters anchor vacuum-rated ceramic bearing supply, concentrating pricing power among German and Japanese specialists who feed downstream wheel assemblers across three continents. This geographic chokepoint translates into cost pass-through capability at the component tier, while prime contractors respond through backward integration into seal design and thermal testing capabilities.
Pricing Analysis
Aftermarket refurbishment contracts for orbital track wheels generate the dominant lifetime value stream, with recurring service revenue outpacing initial hardware sales by substantial multiples. Three-tier pricing structure across flight-qualified, development-grade, and research-tier certification levels segments buyer budgets sharply. Cost compression in development-grade tiers is intensifying because SpaceX and Blue Origin captive programs are displacing traditional supplier relationships. Commercial space operators exhibit the highest price sensitivity due to launch cost pressures, while classified defense programs show minimal elasticity.
Supply Chain Analysis
Aluminum alloy feedstock draws from primary smelters in the United States, Germany, and Japan, with carbon fiber prepregs sourcing from Toray and Hexcel production networks across Asia-Pacific and North America. Vacuum-rated ceramic bearings, titanium aluminide powder stocks, and REACH-compliant thermal control coatings constitute critical input dependencies. Single-source vulnerability concentrates in Japanese and German bearing manufacturers, creating tariff exposure and logistics chokepoint risk. Distribution runs through prime contractor captive programs and space agency framework contracts rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
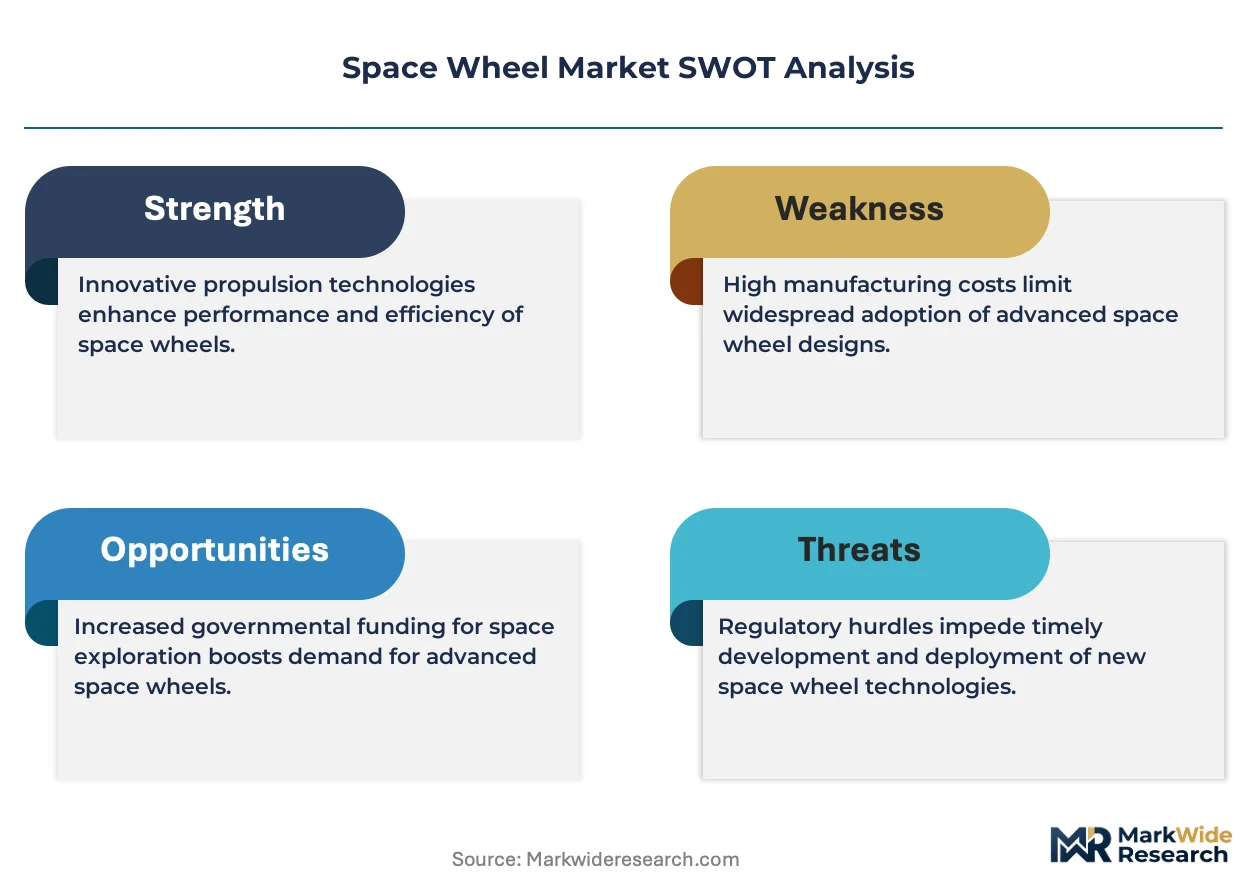
This market functions as a defensive-moat story anchored in regulatory entrenchment. NASA, FAA, and ESA qualification protocols create decade-long certification barriers that protect incumbents from rapid displacement.
For Market Incumbents: Build certification moats by deepening thermal vacuum testing capabilities at Huntsville and Houston engineering clusters. Pursue backward integration into ceramic bearing seal supply through partnerships with Bavarian precision manufacturers. Lockheed Martin's classified satellite contracts demonstrate how security-cleared production lines create entrant barriers. Threat substitution emerges from additive manufacturing of titanium aluminide hubs compressing lead times for complex geometries. For New Entrants and Emerging Players: Scottish spaceport development at SaxaVord and Sutherland represents the most penetrable geographic white space, with suborbital vehicle wheel certification demand outpacing local supply capacity. Target small satellite stabilization wheel miniaturization for academic and institutional buyers with fragmented demand and extended qualification timelines. A go-to-market angle through UK Space Agency procurement frameworks aligned with ESA debris-mitigation criteria offers regulatory legitimacy without full NASA qualification burden. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because orbital habitat expansion and Artemis-derived surface missions lock in sustained replacement cycle demand. Acquisition targets should concentrate on specialty vacuum tribology firms with retiring NASA and ESA engineering cohorts concentrated in their technical staff. The signal to watch is FAA licensing velocity for commercial orbital platforms, which would accelerate wheel qualification program volumes and validate capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Bearing Supply Agreement | Secures vacuum-rated component access from German and Japanese precision manufacturers. |
| Additive Manufacturing Certification | NASA Marshall Space Flight Center qualification compresses lead times for titanium aluminide hubs. |
| REACH-Compliant Coating Transition | European suppliers pivot to chromium-free alternatives before Artemis hardware qualification completes. |
| Multi-Mission Framework Contract | Agency procurement consolidation favors primes with performance-based acceptance criteria. |
| In-Space Servicing Capability | Orbital assembly platforms create demand for microgravity fabrication-rated wheel designs. |
Research Methodology
A standing panel of thermal vacuum chamber operators, ceramic bearing procurement leads at prime contractors, space agency qualification officers, and carbon composite substrate R&D directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from NASA technical standards documentation, FAA commercial launch licensing records, ESA Clean Space initiative protocols, and SEC filings from publicly traded aerospace manufacturers. Bottom-up segment sizing triangulated against top-down market boundary estimates from customs trade data and space agency budget disclosures.
Scenario-bracketing framed the analytical approach, with volume and value outputs tested across low, base, and high case assumptions over the projection horizon. Segmentation dimensions modeled include wheel architecture type, substrate material tier, application function, and end-user procurement pattern. CAGRs were derived from fitted growth curves anchored to observable qualification timeline compression and launch cadence announcements. Industry-specific forecast inputs incorporated Artemis program milestone schedules and commercial orbital habitat deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by captive commercial operators such as SpaceX and Blue Origin would shift outcomes through accelerated vertical integration. Cross-checking against FAA commercial launch licensing velocity and NASA procurement award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Spacecraft Market
Space
China Space Propulsion System Market
Space
Astronaut Spacesuit Market
Space
Asia-Pacific Space Logistics Market
Space
Space Ground System Market
Space
Asia-Pacific Space Electronics Market
Space
Space in Orbit Refueling Market
Space
UK Space Propulsion System Market
Space
Space Radar Market
Space
Space Management Solutions Market
Space
US Space Electronics Market
Space
Space Semiconductor Market
Space
UK Space Electronics Market
Space
Space Robotics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
US Space Launch Services Market